

Key Takeaways
- Zscaler fell 11% in the past week with no news of its own, as a selloff that began at Fortinet hit security stocks.
- Cloudflare just posted strong results, and tech analyst Dan Ives says security budgets could double.
- At 40x forward earnings, well below its usual level, Zscaler looks like a buy before Dec. 2, with Palo Alto Networks’ Nov. 18 report the first read.
Zscaler (ZS) is down 11% in the past week, with no news of its own to blame.
The selling started at Fortinet (FTNT) and peaked on Nov. 5. The Nasdaq Composite fell 5.5% that day, and Zscaler, Palo Alto Networks (PANW), CrowdStrike and Cloudflare (NET) fell 8% to 10% as the AI trade unwound. Zscaler fell another 3% on Nov. 6, even as Cloudflare jumped 10% on its report.
Fortinet started it
Fortinet beat estimates after the Oct. 28 close, but its service revenue grew just 13% and it trimmed its full-year service forecast, blaming the timing of service activations on large deals. Investors sold subscription security stocks as a group, and few are more exposed than Zscaler, which got about 98% of its fiscal 2026 revenue from subscriptions. Its only news on Nov. 5 was its earnings date.
Cloudflare found “an even higher gear”
Cloudflare’s third-quarter revenue rose 39% to $782.5 million, its fastest growth in nearly four years, and CEO Matthew Prince said it has “found an even higher gear.” That fits what tech analyst Dan Ives, who left Wedbush in July to co-found Yorkville Ives, said on the Nov. 3 RiskReversal Pod: “budgets are going to potentially double in cybersecurity for IT over the next two, three years.” He named Zscaler and Palo Alto among the companies that win when hacks pick up.
TIKR tracks 47 analysts on Zscaler. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Zscaler, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Zscaler’s Analyst Ratings
Dec. 2 has to show more than a beat
Zscaler reports after the close on Dec. 2, guiding to $935 million to $939 million of first-quarter revenue. The number to watch is net new ARR. The full-year guide implies $625 million to $655 million, only about 2% to 7% more than the $615 million Zscaler added in fiscal 2026 without Red Canary. Palo Alto’s Nov. 18 report will show first whether Fortinet’s slowdown is spreading; its guide calls for $9.54 billion to $9.56 billion of Next-Generation Security ARR for the quarter ended Oct. 31. Analysts still expect Zscaler’s normalized EPS to climb to $6.70 by fiscal 2029:
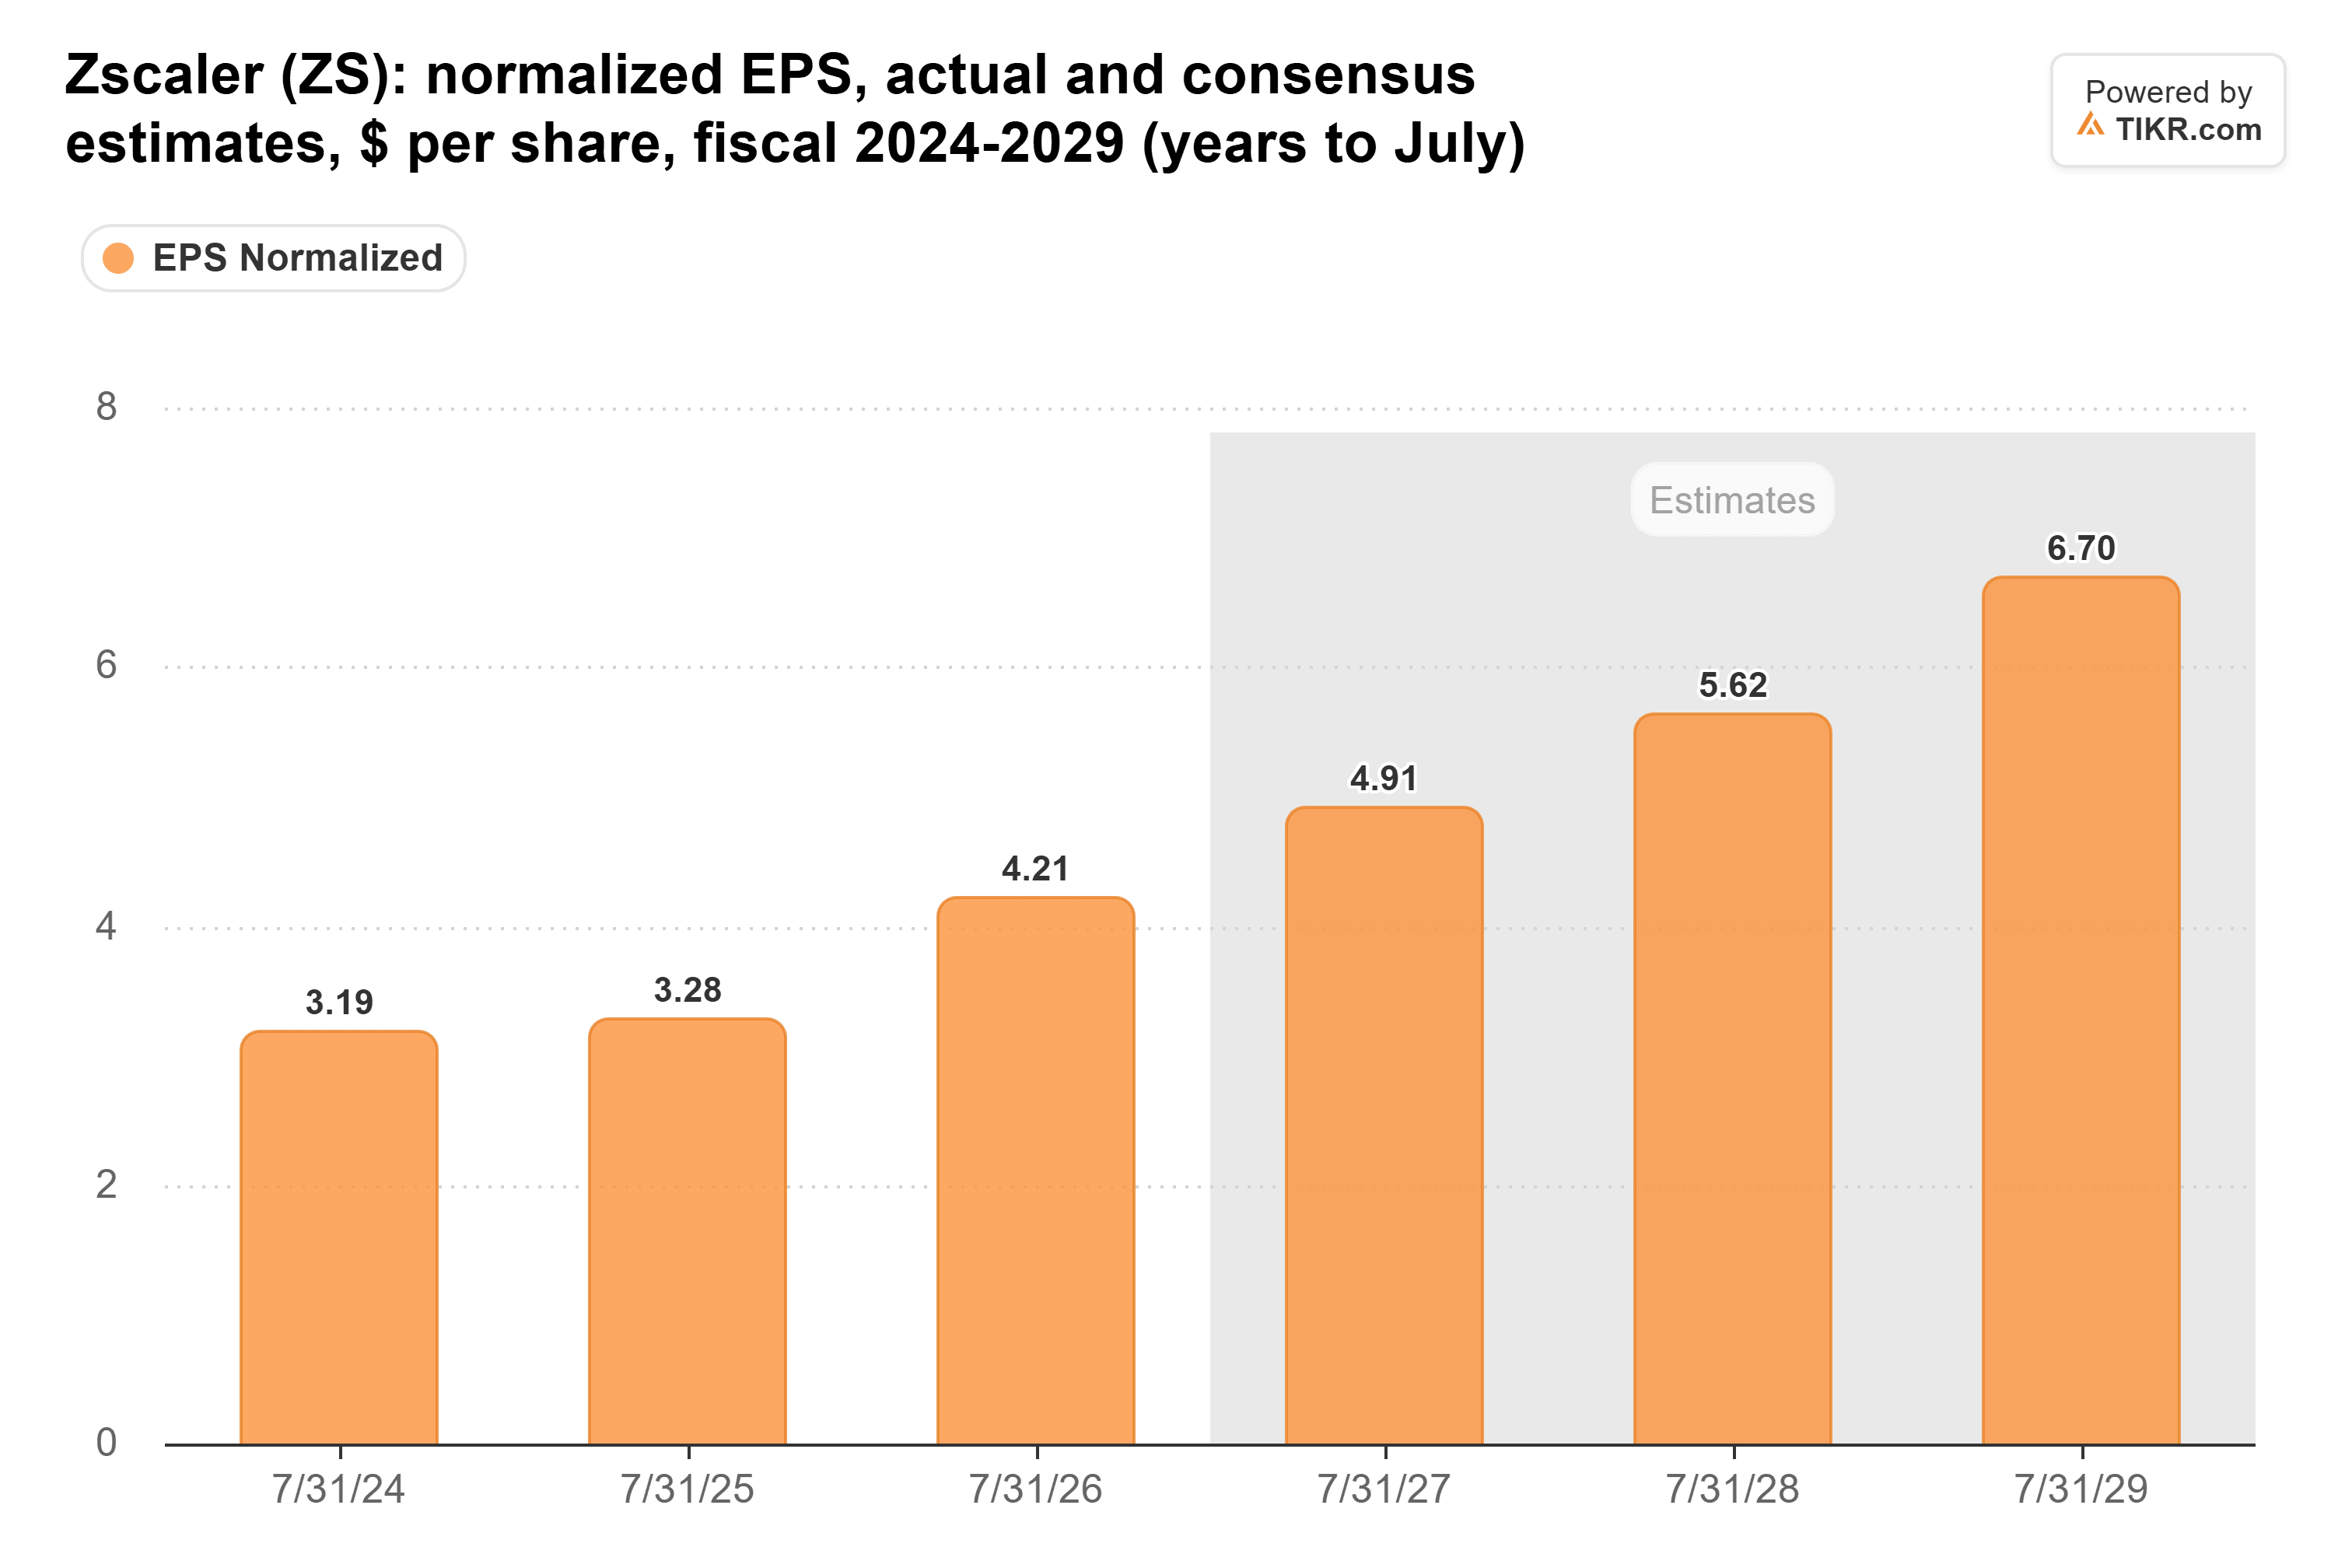
Nothing this week gives them a reason to cut.
Cheaper than it usually trades
The selloff has left Zscaler’s forward P/E well below its usual level:
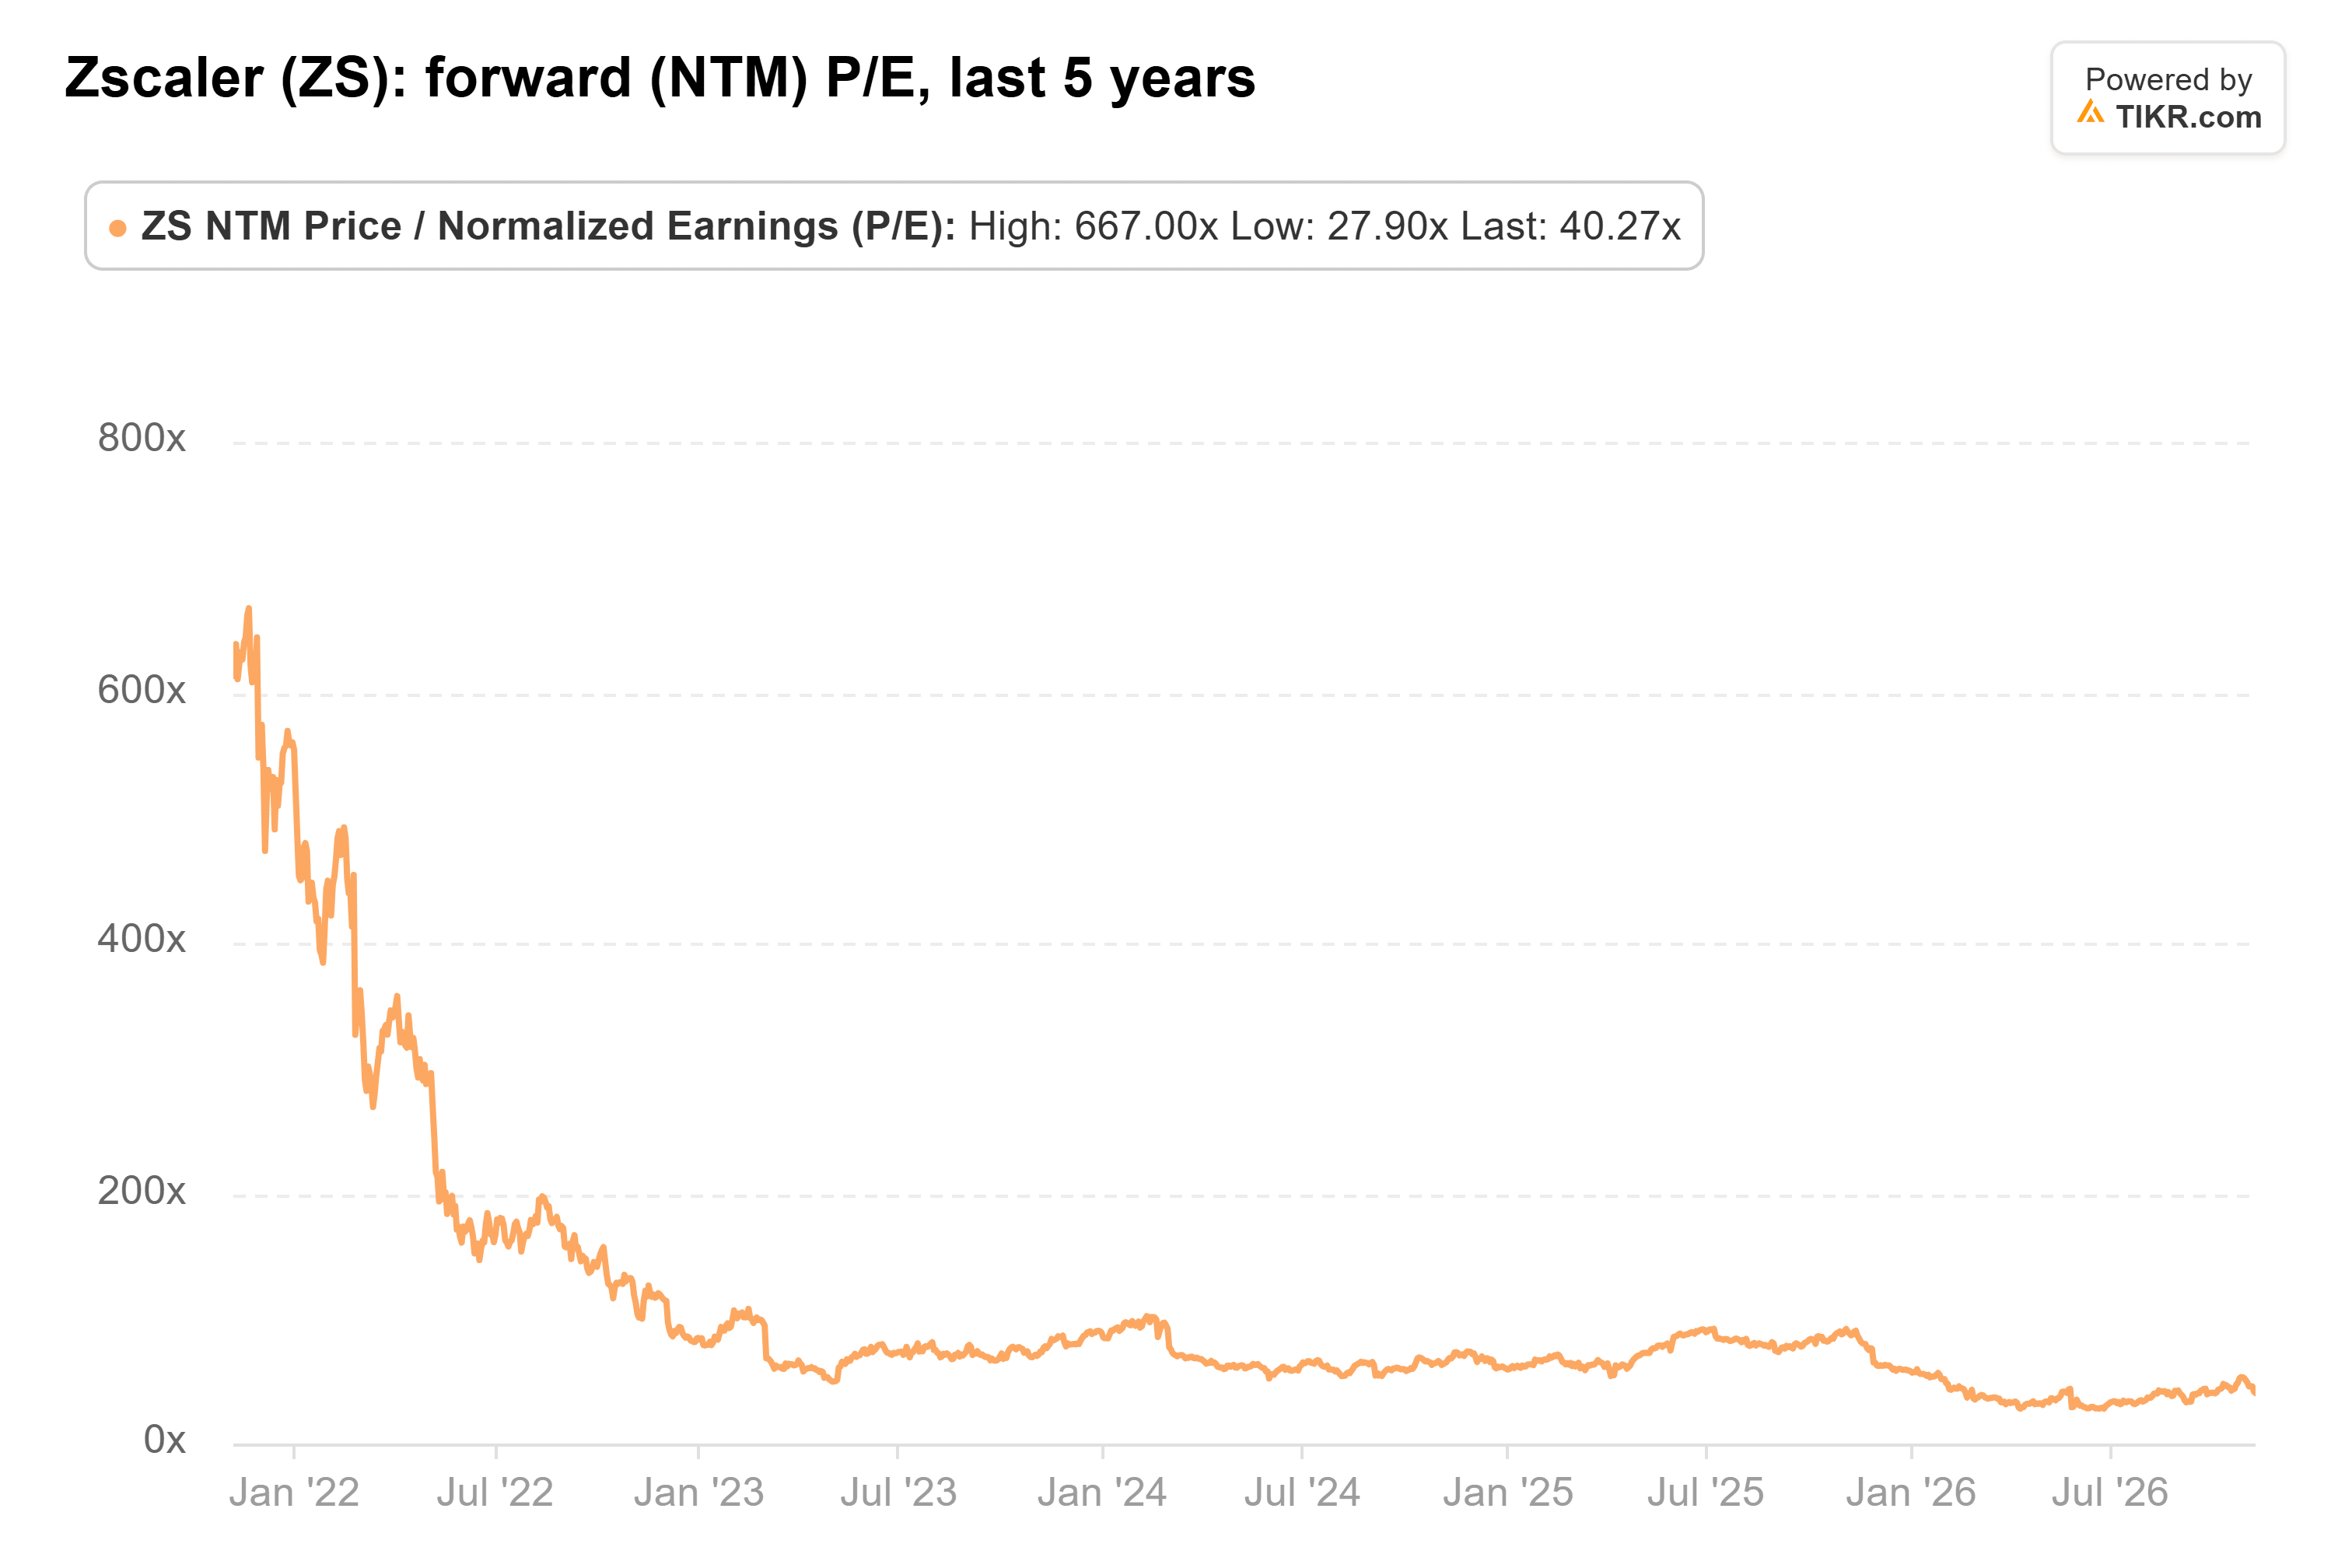
It was 40x at the Nov. 6 close, against a three-year average of about 63x, and the $235 consensus target sits about 18% above the Nov. 9 close.
The risk is a guidance reset like May’s, when the stock fell 32% the day after its report. At 40x, the stock looks worth buying before Dec. 2, with room to add if net new ARR beats the plan. If Palo Alto’s ARR lands at the low end of its guide, though, expect the group to get cheaper first.
So what is Zscaler stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Zscaler could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


