Key Takeaways
- Visa (V) raised its quarterly dividend 16% to $0.78 a share on Oct. 27, while Mastercard (MA) has held its quarterly payout at $0.87 all year.
- Both dividends are well-covered: they use 23% of Visa’s free cash flow and 19% of Mastercard’s over the 12 months to Sept. 30.
- Visa’s dividend has grown 16% a year over five years against Mastercard’s 14%, though both stocks yield under 1%.
- Mastercard’s board usually decides on its raise in December, so that decision is the next one to watch.
Visa raised its quarterly dividend 16% on Oct. 27, to $0.78 a share from $0.67, after a fiscal 2026 in which net revenue rose 15% to $45.9 billion.
Mastercard, meanwhile, declared the same $0.87 quarterly dividend on Sept. 29 that it has paid all year.
Neither stock yields much: 0.7% for Visa and 0.6% for Mastercard. Over 20 years, though, the raises matter far more than the yield you start with. So if you could only own one, which should it be?
| Metric | Visa (V) | Mastercard (MA) |
|---|---|---|
| Dividend yield | 0.7% | 0.6% |
| Annual dividend, current rate | $3.12 | $3.48 |
| 5-year dividend growth | 16% a year (fiscal 2021-2026) | 14% a year (fiscal 2020-2025) |
| Cash dividend payout ratio, TTM to Sept. 30, 2026 | 23% | 19% |
| Cash dividend payout ratio, forward | 21% (fiscal 2027) | 18% (fiscal 2026) |
| Net debt/EBITDA | 0.3x | 0.6x |
| Interest coverage | 38.6x | 26.8x |
Source: TIKR and company releases, Nov. 9, 2026.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Visa has the cash for a 16% raise
Visa’s fiscal 2026, the year ended September 2026, was a strong one. Adjusted EPS rose 16% to $13.27, and value-added services revenue grew 30% in constant dollars to $14 billion on demand for its cyber and risk products.
Visa paid $5.11 billion in dividends over the 12 months to Sept. 30, a well-covered 23% of its $22.06 billion of free cash flow. On analysts’ fiscal 2027 estimates, that ratio falls to 21%.
Free cash flow rose from $8.61 billion in fiscal 2017 to $22.1 billion in fiscal 2026, and dividends paid rose from $1.58 billion to $5.11 billion:
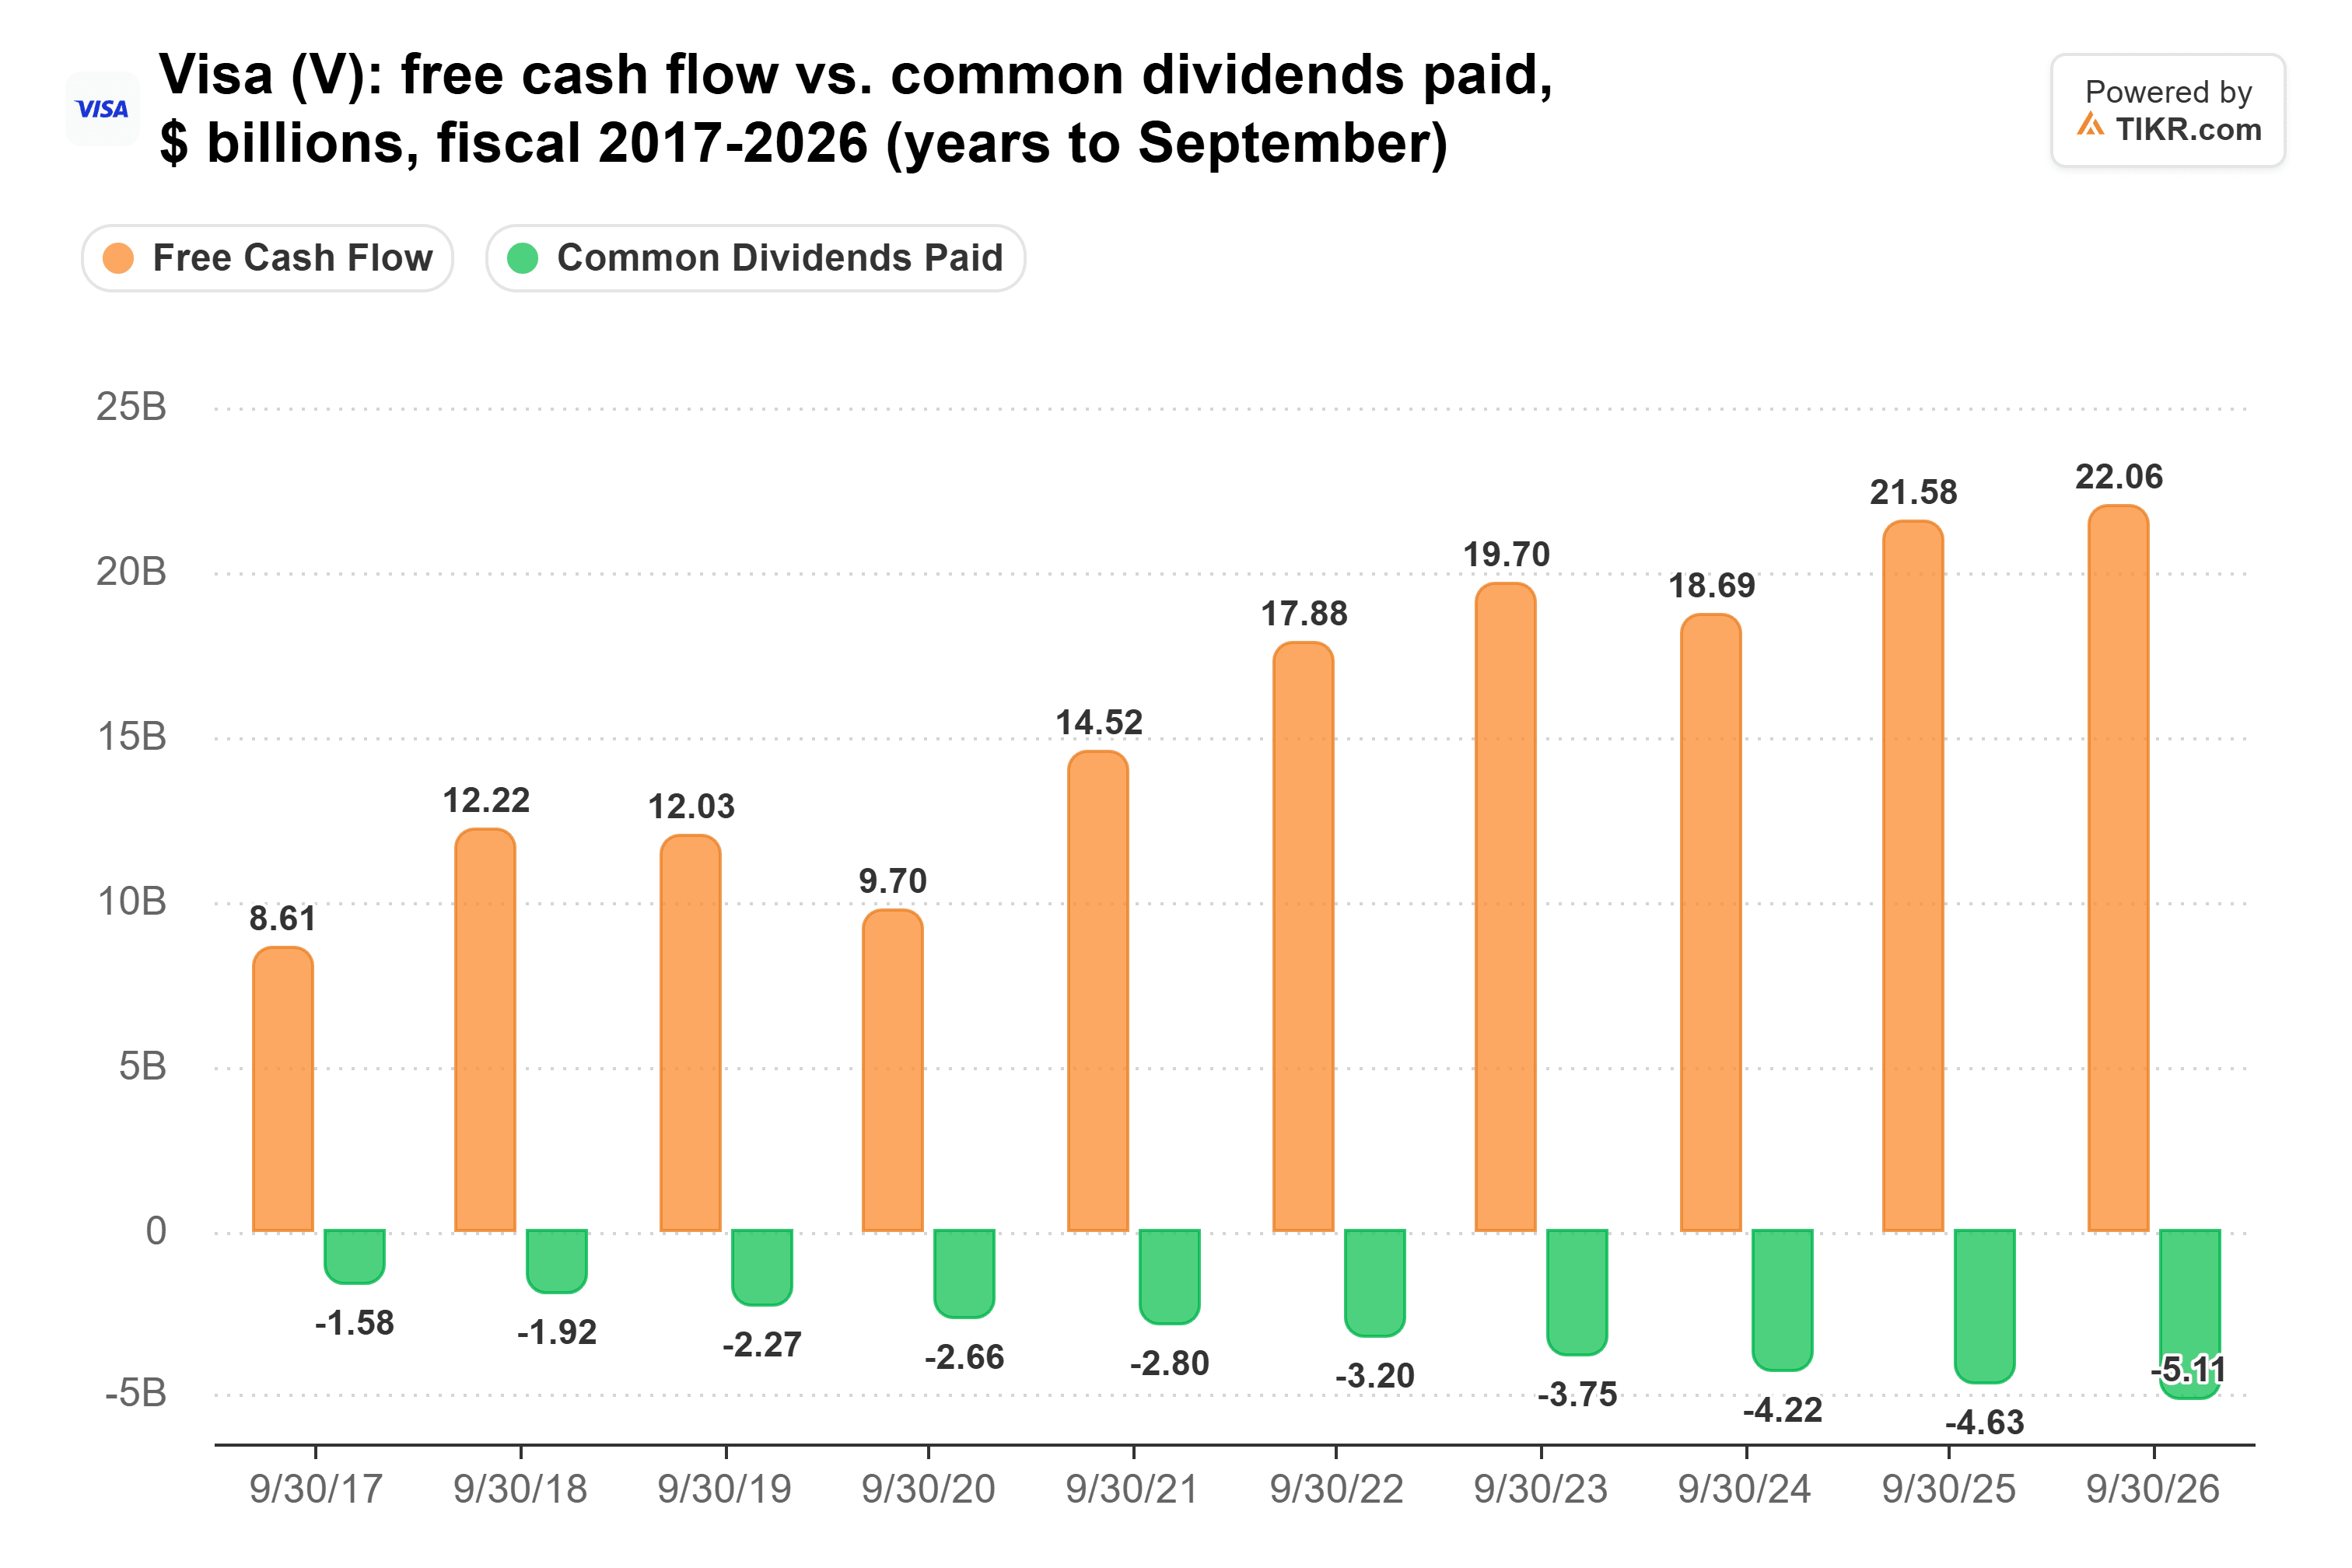
The dividend has grown a bit faster than the cash, though, which lifted the ratio from 19.3% in fiscal 2021 to 23.2% in fiscal 2026.
The main risk is legal: on Oct. 1, three merchants appealed part of the amended settlement in the interchange litigation, according to Visa’s annual report, so the cost and timing of that case are still uncertain.
Mastercard covers its dividend with even more room
Mastercard’s business is keeping pace with Visa’s. Its Q3 net revenue rose 14% to $9.8 billion, and adjusted EPS rose 21% to $5.31.
Its dividend is even better covered than Visa’s. Mastercard paid $3.00 billion over the 12 months to Sept. 30, just 19% of its $16.08 billion of free cash flow, and 18% of analysts’ 2026 estimates.
Free cash flow rose from $4.42 billion in 2016 to $17.2 billion in 2025, outpacing dividends paid, which rose from $0.84 billion to $2.76 billion:
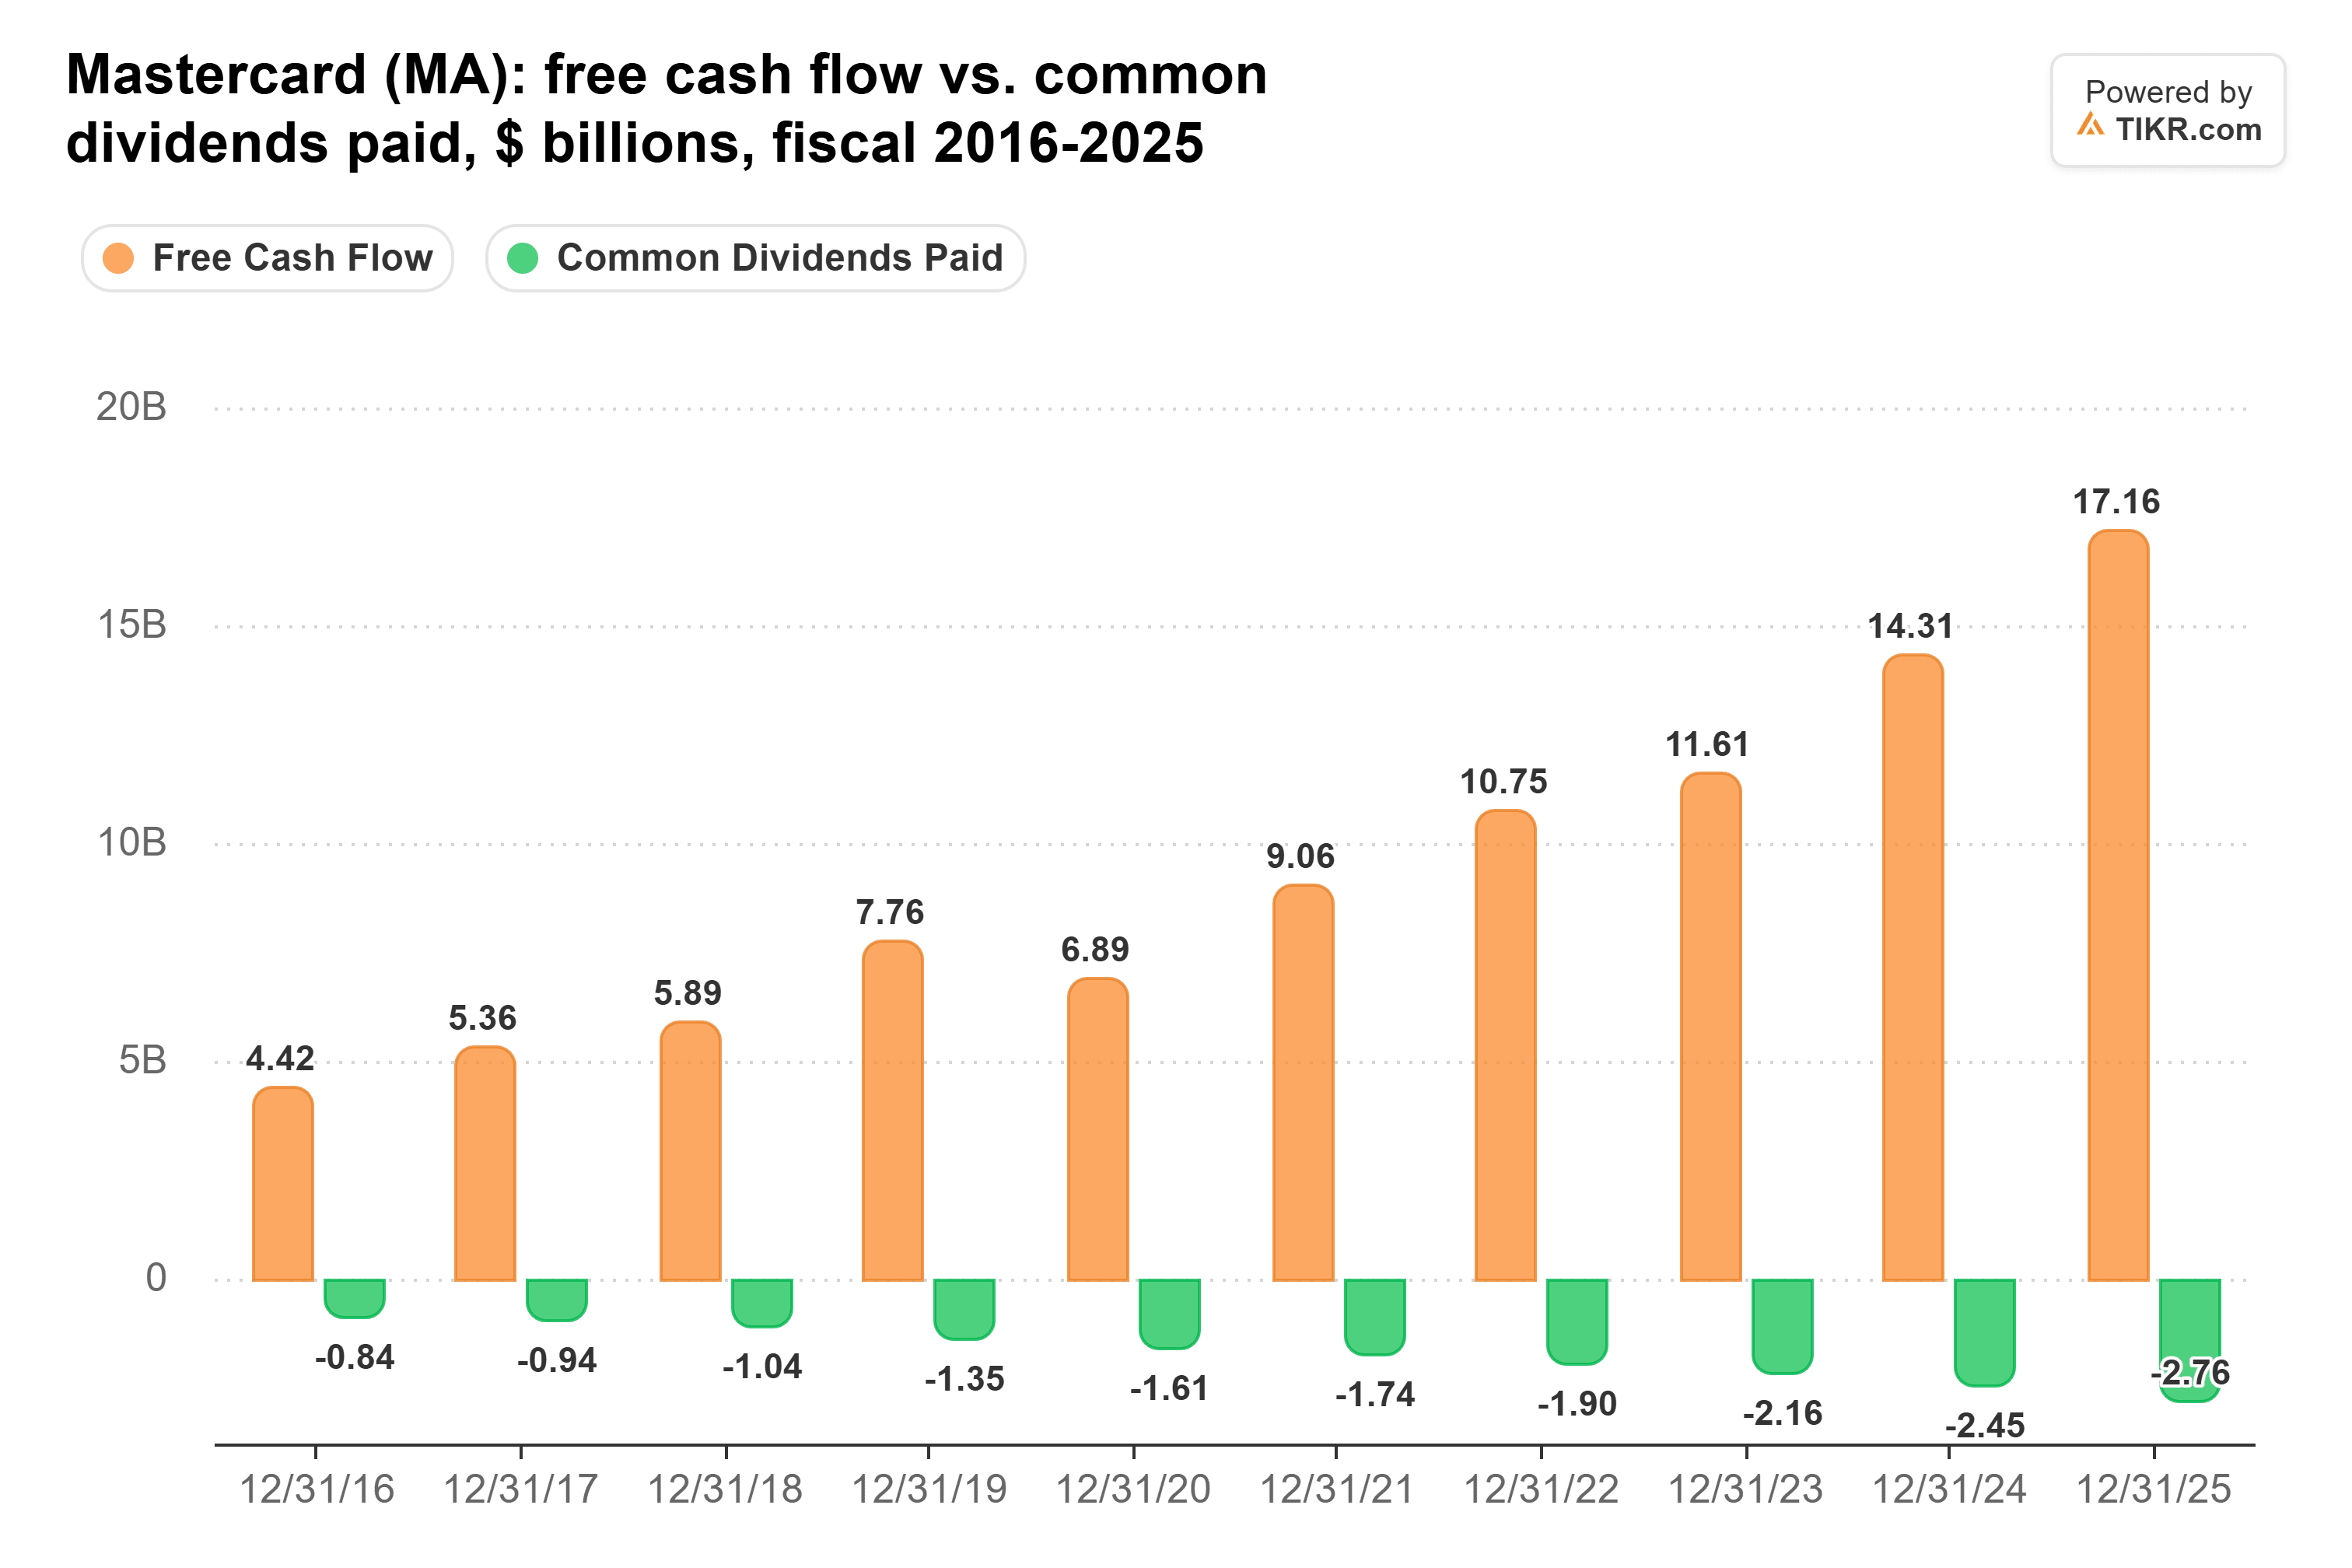
But Mastercard’s raises have slowed. Dividends per share grew 10.9% in 2025, against 13.1% a year from 2020 to 2025. Regulation of interchange rates and surcharging is its main risk, and Visa faces the same scrutiny.
So which dividend wins?
For the next 20 years, I’m picking Visa.
Over that long a stretch, durability comes first. Both companies pay out less than a quarter of their free cash flow, so I don’t put much weight on Mastercard’s four-point edge in coverage.
Visa has the edge everywhere else: less debt, at 0.3x EBITDA against 0.6x, a bigger check today, and faster raises.
Those raises add up. Put $10,000 in Visa at its 0.7% yield, and it pays $70 a year now.
Growing 16.0% a year, its five-year rate, that’s about $1,169 in year 20. Call it an 11.7% yield on your original $10,000, and about $8,049 over the 20 years. The same $10,000 in Mastercard, growing 13.1% a year, pays about $4,935.
At each dividend’s latest pace (Visa up 14% in fiscal 2026, Mastercard up 11% in 2025), Visa still pays about $6,636 to Mastercard’s $3,830. Those totals aren’t a fortune either way, so capital appreciation matters here too.
Analysts also expect the cash behind Visa’s dividend to keep rising. Nine of them see free cash flow growing from $22.1 billion in fiscal 2026 to $27.6 billion in fiscal 2027 and $30.9 billion in fiscal 2028:
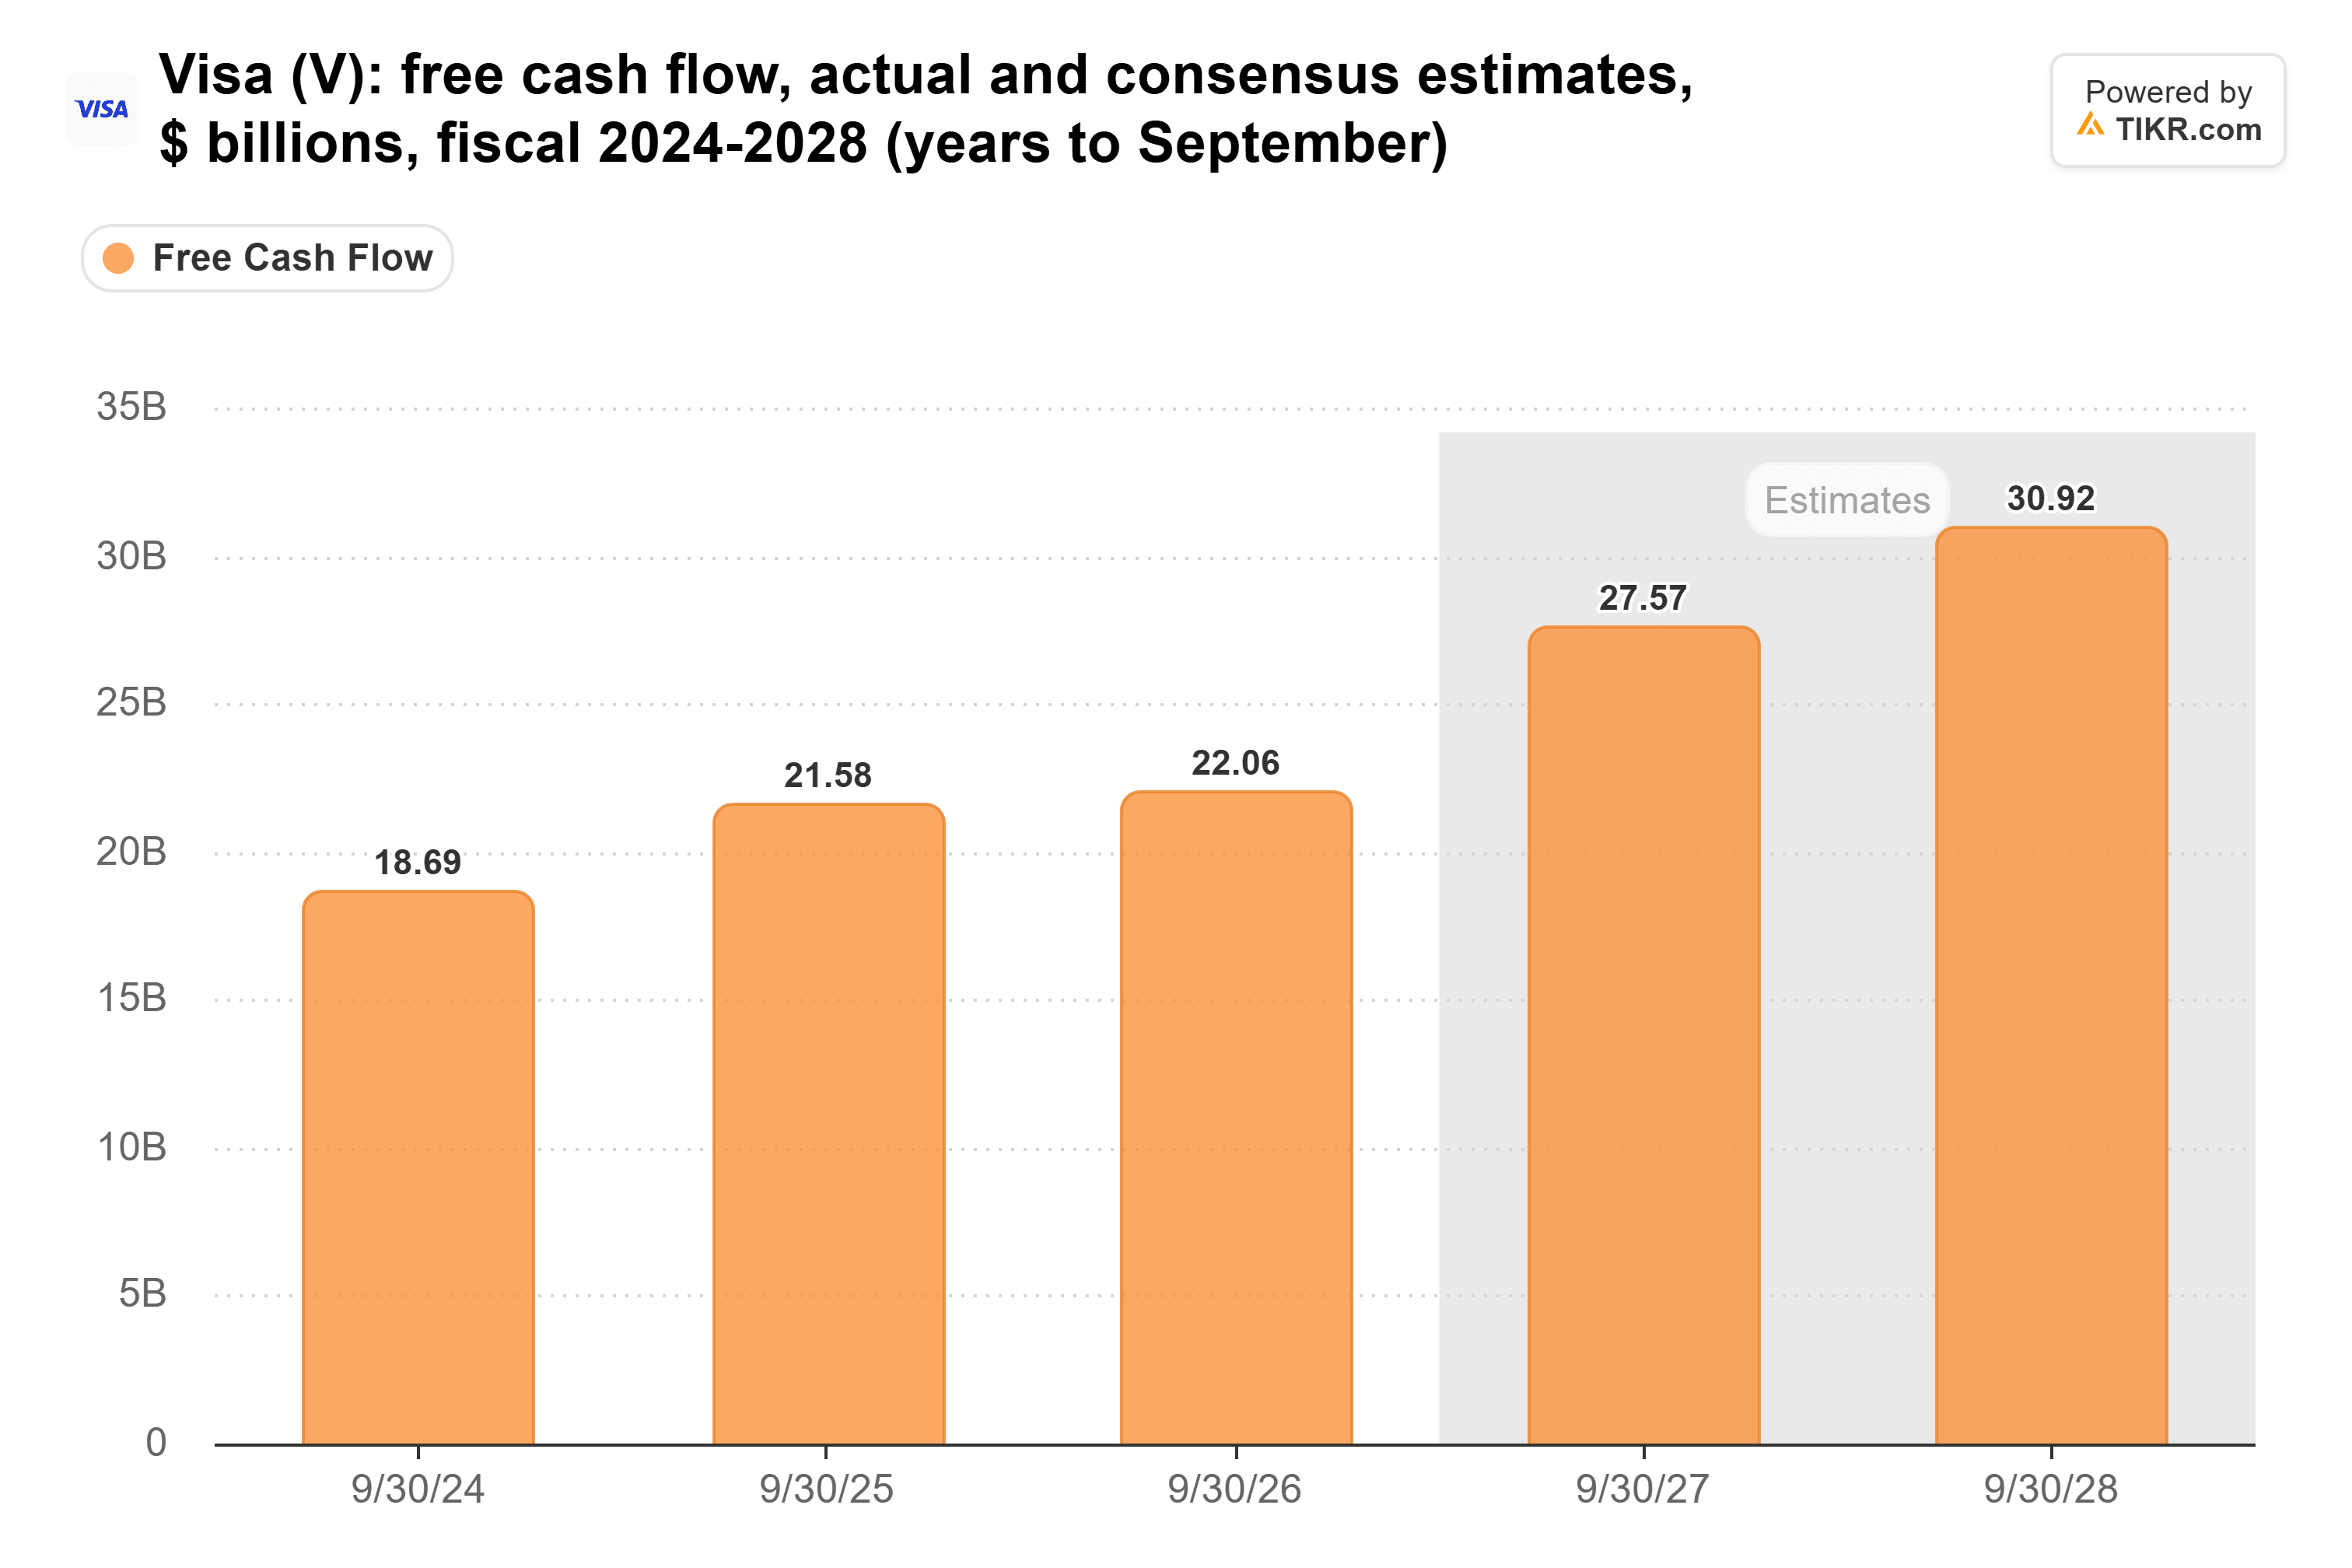
Last year’s consensus came within 6% of the actual, which makes me fairly comfortable leaning on it.
This isn’t to say Mastercard’s dividend is any less safe. It takes less of its cash, and with its ratio down to 16.1% in 2025, it has room for a much bigger raise whenever its board wants one.
It’s just that, over 20 years, I’d rather own the dividend that’s already bigger and growing faster, from a business with less debt.
Of course, Mastercard’s board usually decides on its raise in December, and a big one would narrow the gap.
Forget Visa: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Visa isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!