UnitedHealth Group (UNH) shares are up about 4.5% in premarket trading on Tuesday, October 13 (at about $396), after the insurer beat third-quarter profit estimates and raised its 2026 outlook. Adjusted earnings came in at $4.69 per share, against the $4.14 analysts expected, according to LSEG data cited by Reuters, and up from $2.92 a year earlier.
UnitedHealth now expects 2026 adjusted EPS of at least $20.50, up from the $19.50 to $20 range it set on July 16. The twist: revenue slipped to $112.7 billion from $113.2 billion. The company earned far more on slightly less business.
UnitedHealth Is Shrinking Its Way Back
Cost management, repricing and benefit changes helped drive the beat. The medical care ratio fell to 88.4% from 89.9%, also benefiting from $610 million of favorable reserve development related to earlier periods in 2026. CEO Stephen Hemsley credited “the discipline and execution our teams are bringing to every part of our business.”
The shrinking shows up across the business, and not all of it is by choice:
- Medicare Advantage membership is down 935,000 since the end of 2025.
- Employer and individual plans lost 165,000 members in the quarter, and Medicaid lost 85,000.
- Optum Health revenue fell 10%, yet its operating earnings rose to $735 million from $41 million.
UnitedHealth is exiting some unprofitable business, but the membership declines also reflect employer attrition and Medicaid eligibility changes.
What the Margin Chart Shows

UNH’s EBIT margin ran above 8% in late 2024 and early 2025, then bottomed at 2.46% in the fourth quarter of 2025. (That low excludes one-off charges. On a reported basis, UnitedHealth’s operating margin that quarter was just 0.34%.) It snapped back to 8.05% in the first quarter of 2026 and 7.13% in the second.
On the release’s figures, third-quarter operating earnings of $6.6 billion work out to a margin of about 5.9%, up from 3.8% a year earlier. (Care costs tend to build through the year, so the third quarter usually runs below the first half.) That’s still well short of the 8.64% UnitedHealth earned in the third quarter of 2024, and that gap is the upside case.

Revenue tells the other half. Quarterly sales climbed 12% from $100.8 billion in the third quarter of 2024 to $113.2 billion a year later, then stalled. Every quarter since mid-2025 has landed between $111.6 billion and $113.6 billion. For now, all the earnings growth is coming from margin.
Is the Recovery Priced Into UNH Stock?
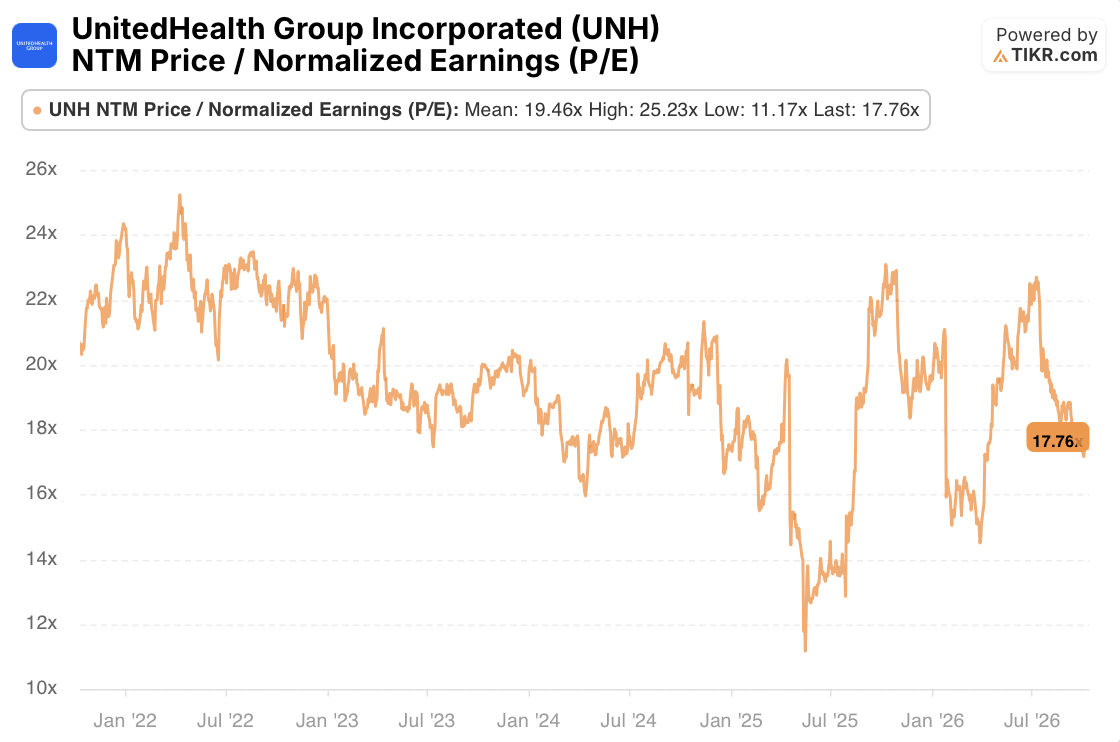
Before today’s move, UNH traded at 17.76 times next-twelve-months normalized earnings, about 9% below its five-year average of 19.46x. That’s far above the 11.17x low from mid-2025, when the margin collapse was fresh, and far below the 25.23x peak. Investors have paid for survival, not a full return to 2024 margins.
The quarter matters beyond UnitedHealth, too. If its 150-basis-point drop in the medical care ratio reflects easing industry cost trends, not just its own repricing and a $610 million reserve release, that’s good news for Humana (HUM), the purest Medicare Advantage play, and for CVS Health (CVS), which owns Aetna. Elevance Health (ELV) is the next big check on whether the relief is industrywide.
Two Ways to Read UnitedHealth’s Quarter
The bull read sits in the margin gap. At roughly $450 billion in annual revenue, every percentage point of operating margin UnitedHealth wins back is worth about $4.5 billion in operating profit, and the third quarter still ran nearly 3 points below 2024.
The bear read sits in the revenue line. Six straight quarters of flat sales and 935,000 fewer Medicare Advantage members mean the cuts can only carry earnings so far. Once the unprofitable business is gone, growth has to return, and Medicare Advantage rates are set in Washington.
The margin repair is real and unfinished. After a 4.5% share-price rise, UNH would trade at about 18.6 times the same forward earnings estimate, still below its five-year average. That tilts the odds toward the bulls, as long as UnitedHealth’s 2027 guidance shows membership stabilizing instead of shrinking further.
You can pull up UNH’s margin history, quarterly revenue and valuation multiples yourself on TIKR, free, and compare them with Humana, CVS and Elevance side by side. Learn more here.
So what is UnitedHealth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what UNH stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value UnitedHealth Group Incorporated for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!