Key Takeaways
- U.S. Bancorp raised its quarterly dividend 3.8% to $0.54 in June, and Fifth Third Bancorp raised its quarterly dividend 5% to $0.42 in September.
- Both dividends are well covered, at 44% and 42% of fiscal 2025 normalized EPS, and analysts expect both ratios to fall in fiscal 2026.
- U.S. Bancorp pays the higher yield today, 3.6% against 3.1%, while Fifth Third has grown its dividend faster over the past five years.
- Over 10 years at each bank’s five-year growth rate, $10,000 in either stock pays about the same total income, within $41.
Anyone hunting for a bank dividend to hold for a decade has two fresh raises to weigh. U.S. Bancorp (USB) lifted its quarterly dividend 3.8% to $0.54 a share in June, and Fifth Third Bancorp (FITB) followed with a 5% raise to $0.42 in September.
Fifth Third’s raise came weeks before it finished moving Comerica onto its own systems.
So which one is the better dividend to own for the next 10 years?
| Metric | U.S. Bancorp (USB) | Fifth Third Bancorp (FITB) |
|---|---|---|
| Dividend yield | 3.6% | 3.1% |
| Annual dividend | $2.16 | $1.68 |
| Dividend growth, fiscal 2020-2025 | 4.0% a year | 7.4% a year |
| Payout ratio of normalized EPS, fiscal 2025 | 44% | 42% |
| Payout ratio of normalized EPS, fiscal 2026 consensus | 40% | 39% |
| Price/tangible book (LTM) | 2.1x | 2.5x |
Source: TIKR, StockAnalysis.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
U.S. Bancorp pays the bigger check
U.S. Bancorp’s business is growing. Third-quarter net revenue hit a record $7.97 billion, up from $7.33 billion a year earlier, and net income rose 10.0% to $2.2 billion. Capital markets revenue jumped 69.3% with its BTIG acquisition on board. The net interest margin widened to 2.84% from 2.75%, and management still sees a path to 3% in 2027.
The dividend took a well-covered 44% of normalized EPS in fiscal 2025, and 40% on fiscal 2026 consensus. That consensus comes from 13 analysts who expect normalized EPS to rise 16% to $5.34.
U.S. Bancorp has also kept raising its dividend through weak years for earnings:
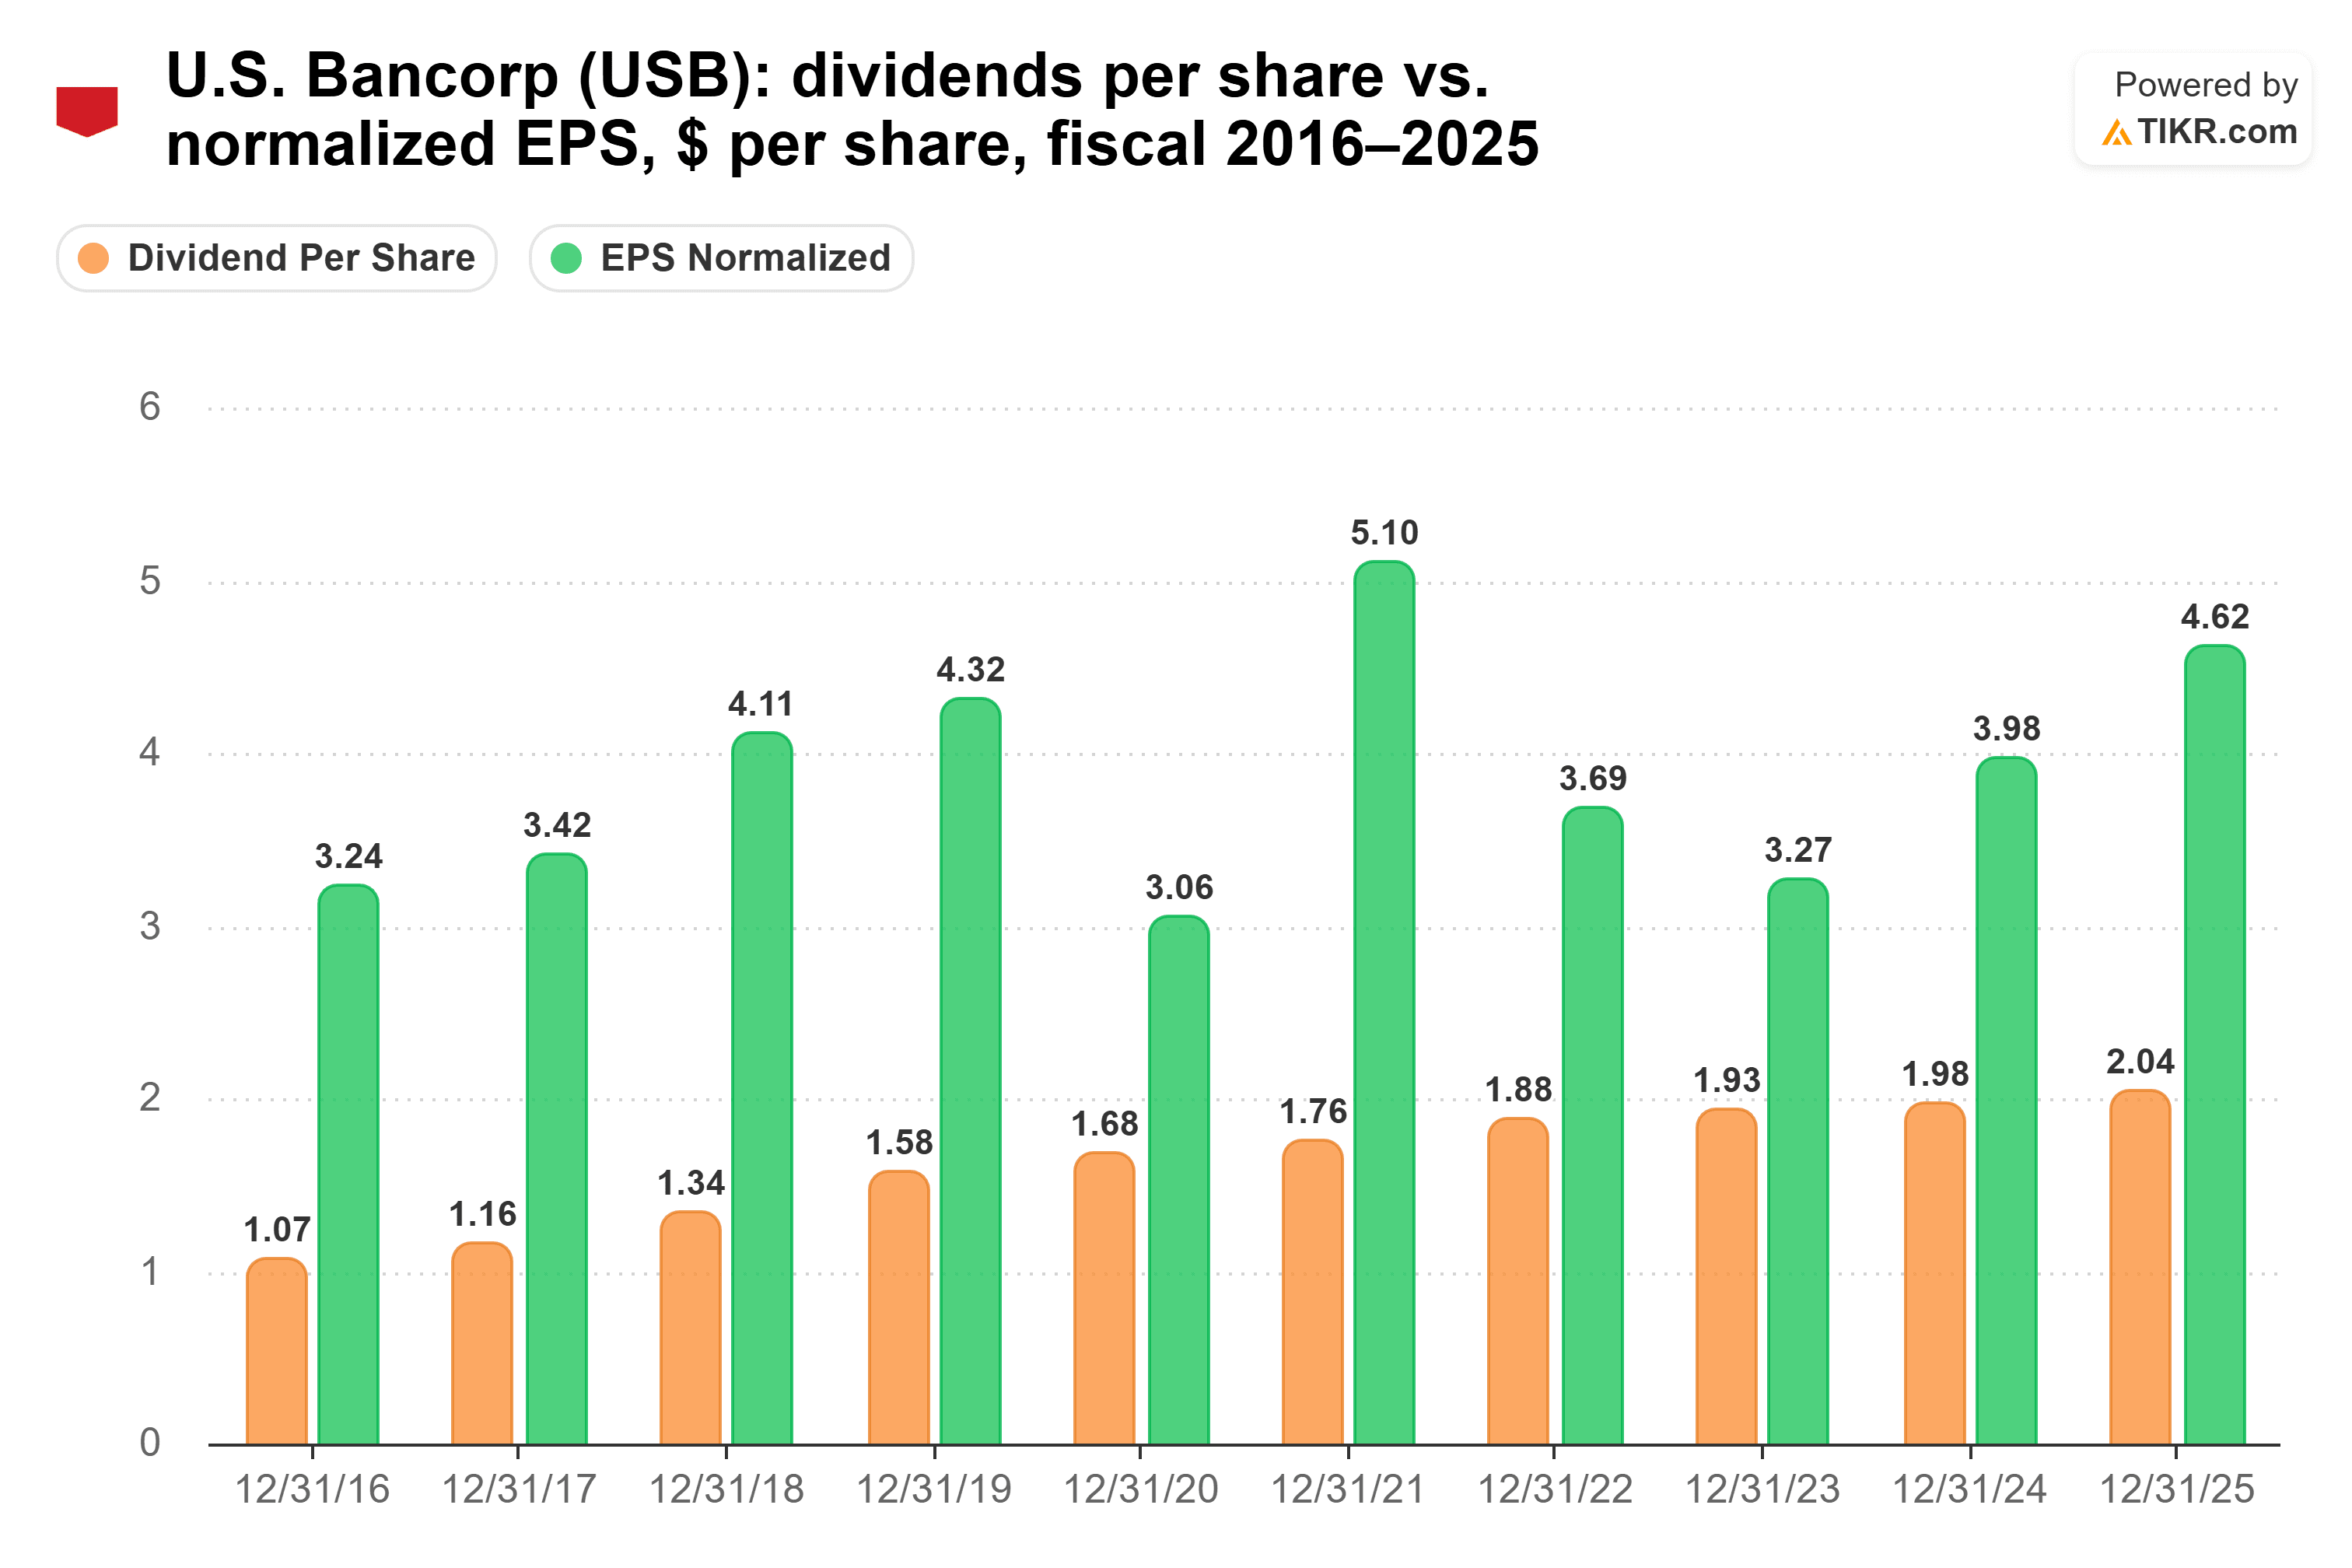
Normalized EPS fell from $5.10 in fiscal 2021 to $3.27 in fiscal 2023, pushing the payout ratio to 59%, and the dividend still rose.
When U.S. Bancorp needs capital, it pulls back on buybacks instead. CFO John Stern said on the third-quarter call that “we obviously are very much committed to the 70% to 75% payout from a capital distribution standpoint.” That range counts repurchases too. The bank paused them last quarter to fund loan growth, and it plans to restart within a quarter or two.
Its chief risk officer, Jodi Richard, left on Oct. 23 to take the same job at American Express. Chief credit officer Troy Remington is filling in while the bank searches for a permanent replacement. Credit is heading the right way, though, with the net charge-off ratio down to 0.51% from 0.56%.
Fifth Third raises faster
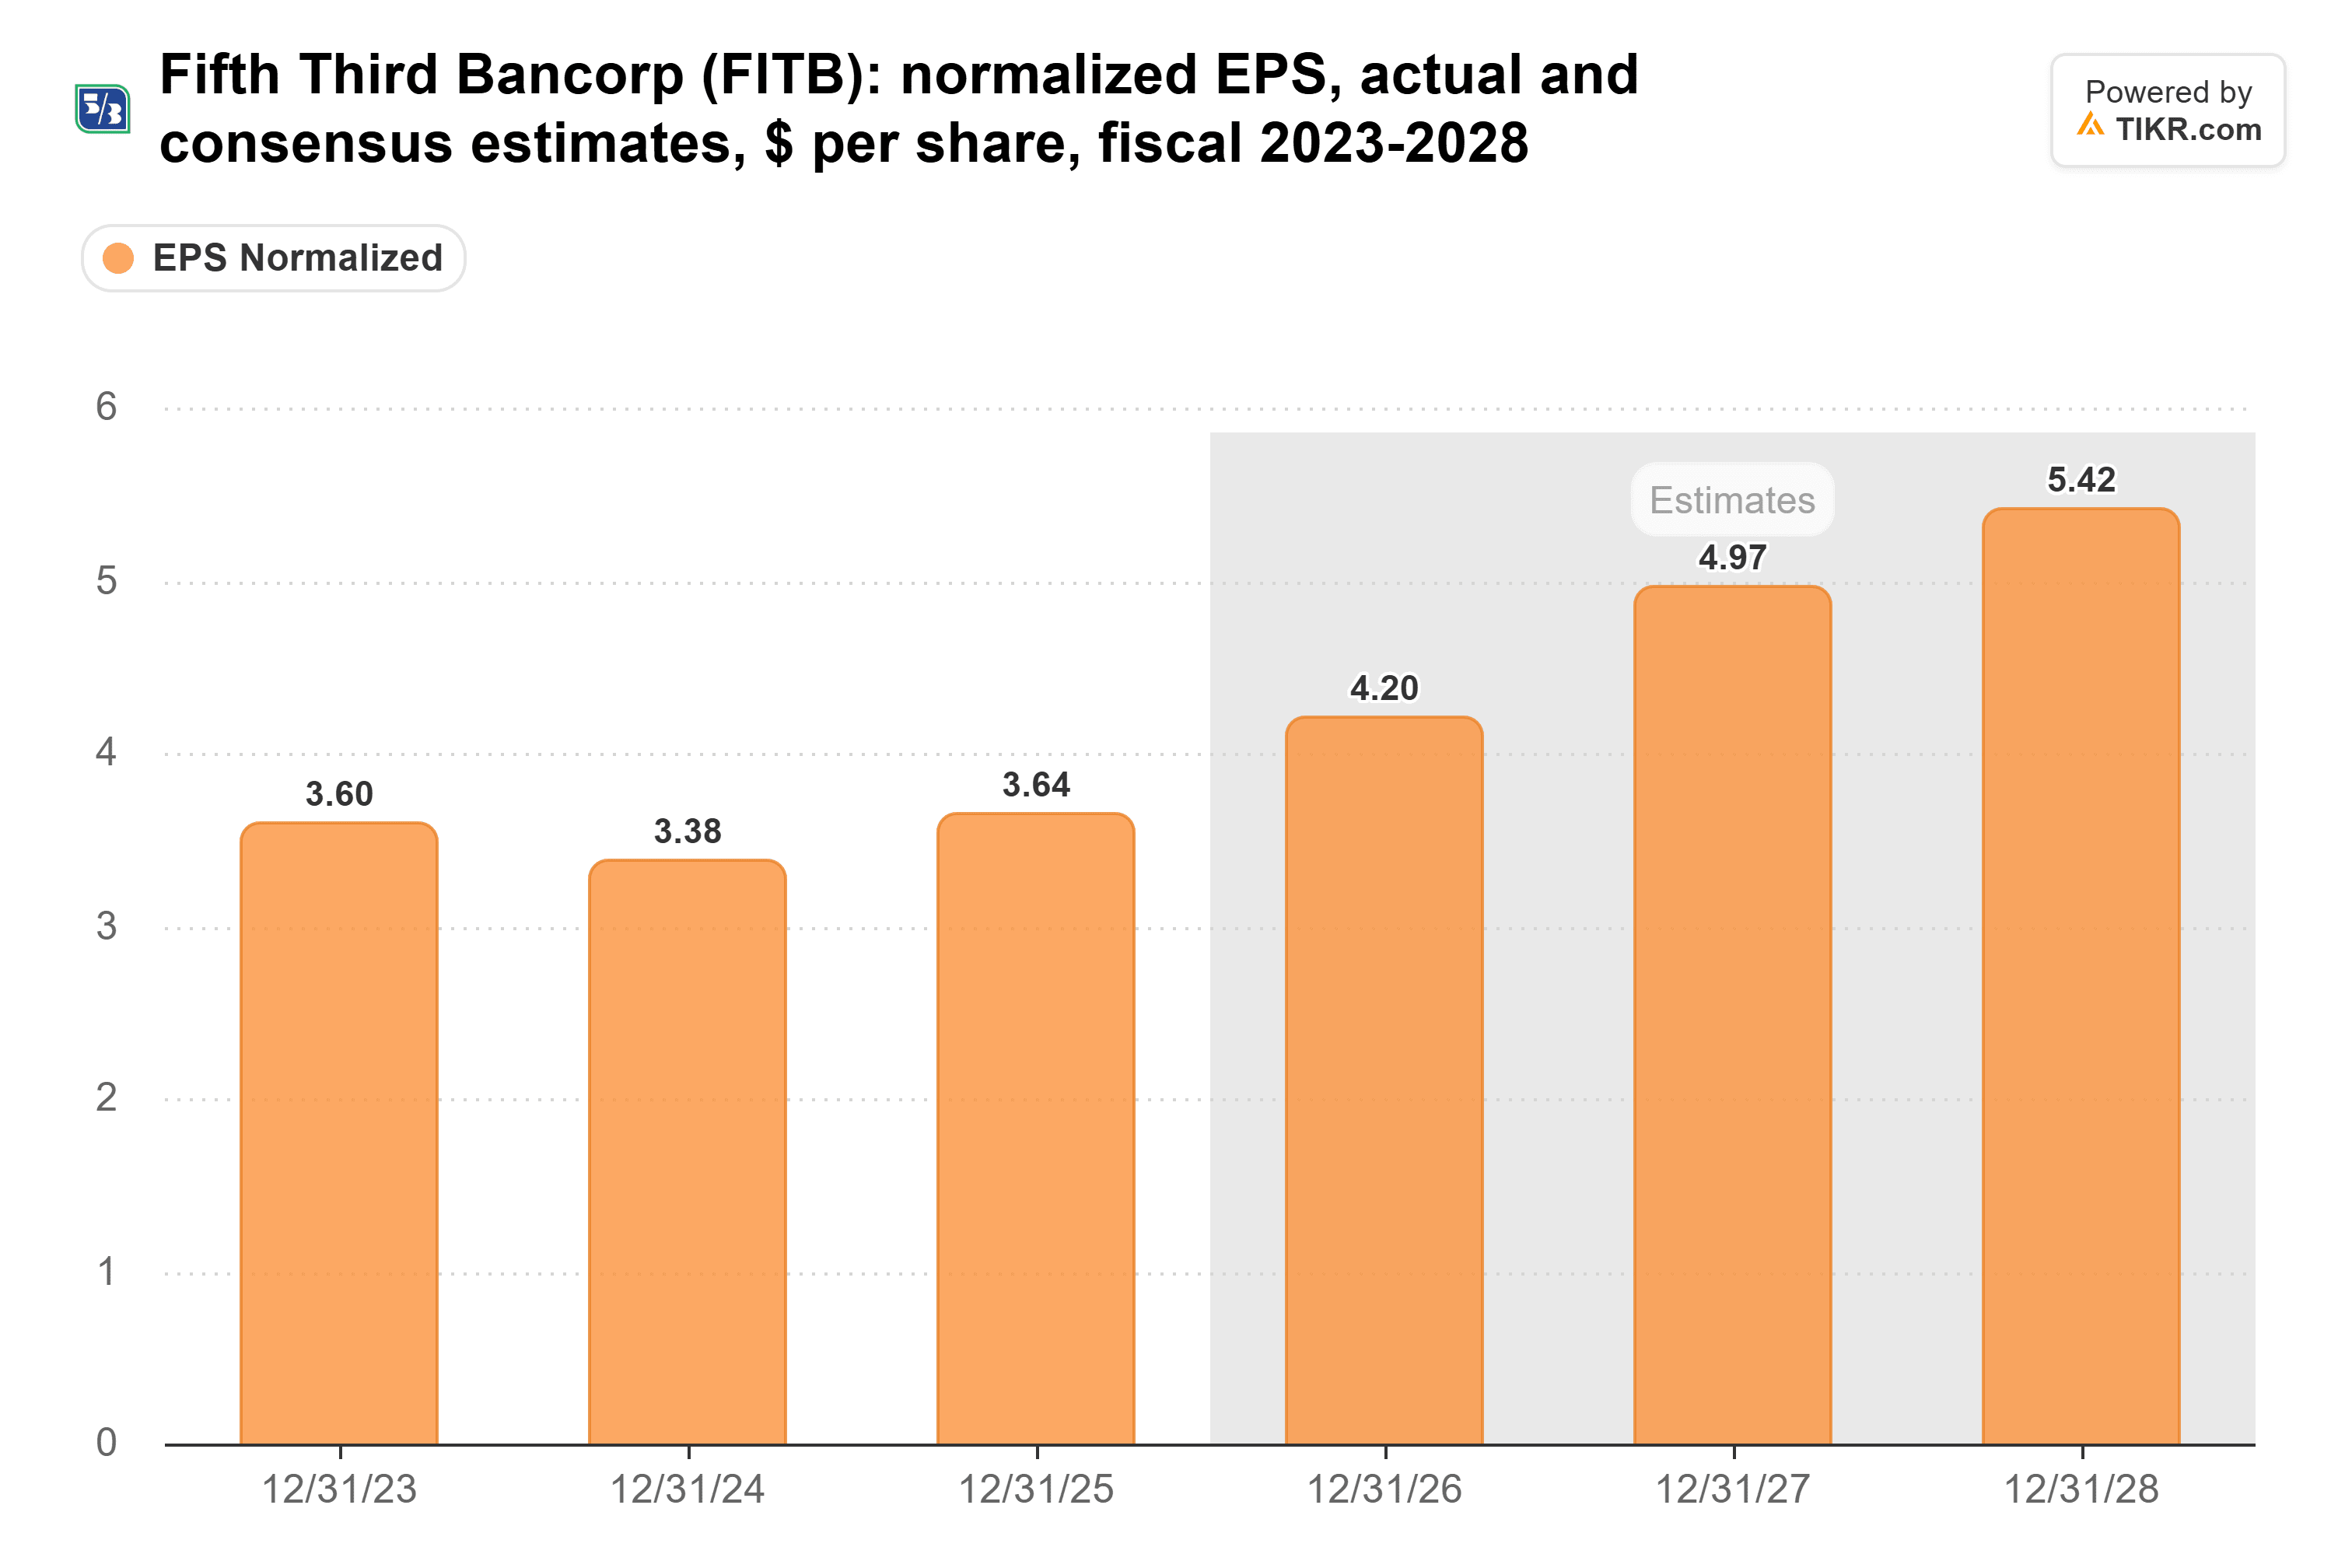
Fifth Third covers its dividend about as well as U.S. Bancorp does, but it has raised it much faster: 7.4% a year from fiscal 2020 to fiscal 2025, against U.S. Bancorp’s 4.0%. Its payout ratio was 42% of normalized EPS in fiscal 2025 and 39% on fiscal 2026 consensus. Nineteen analysts expect normalized EPS to rise 15% to $4.20. For both banks, last year’s consensus came within 2% of the actual.
Comerica is behind that jump. Third-quarter net interest income rose 49% from a year earlier to $2.28 billion. CEO Tim Spence said on the Oct. 19 call that the systems conversion finished with strong client and banker retention. Management expects the rest of the deal’s cost savings to land in the fourth quarter. That quarter also takes substantially all of what’s left of about $1.3 billion in merger charges.
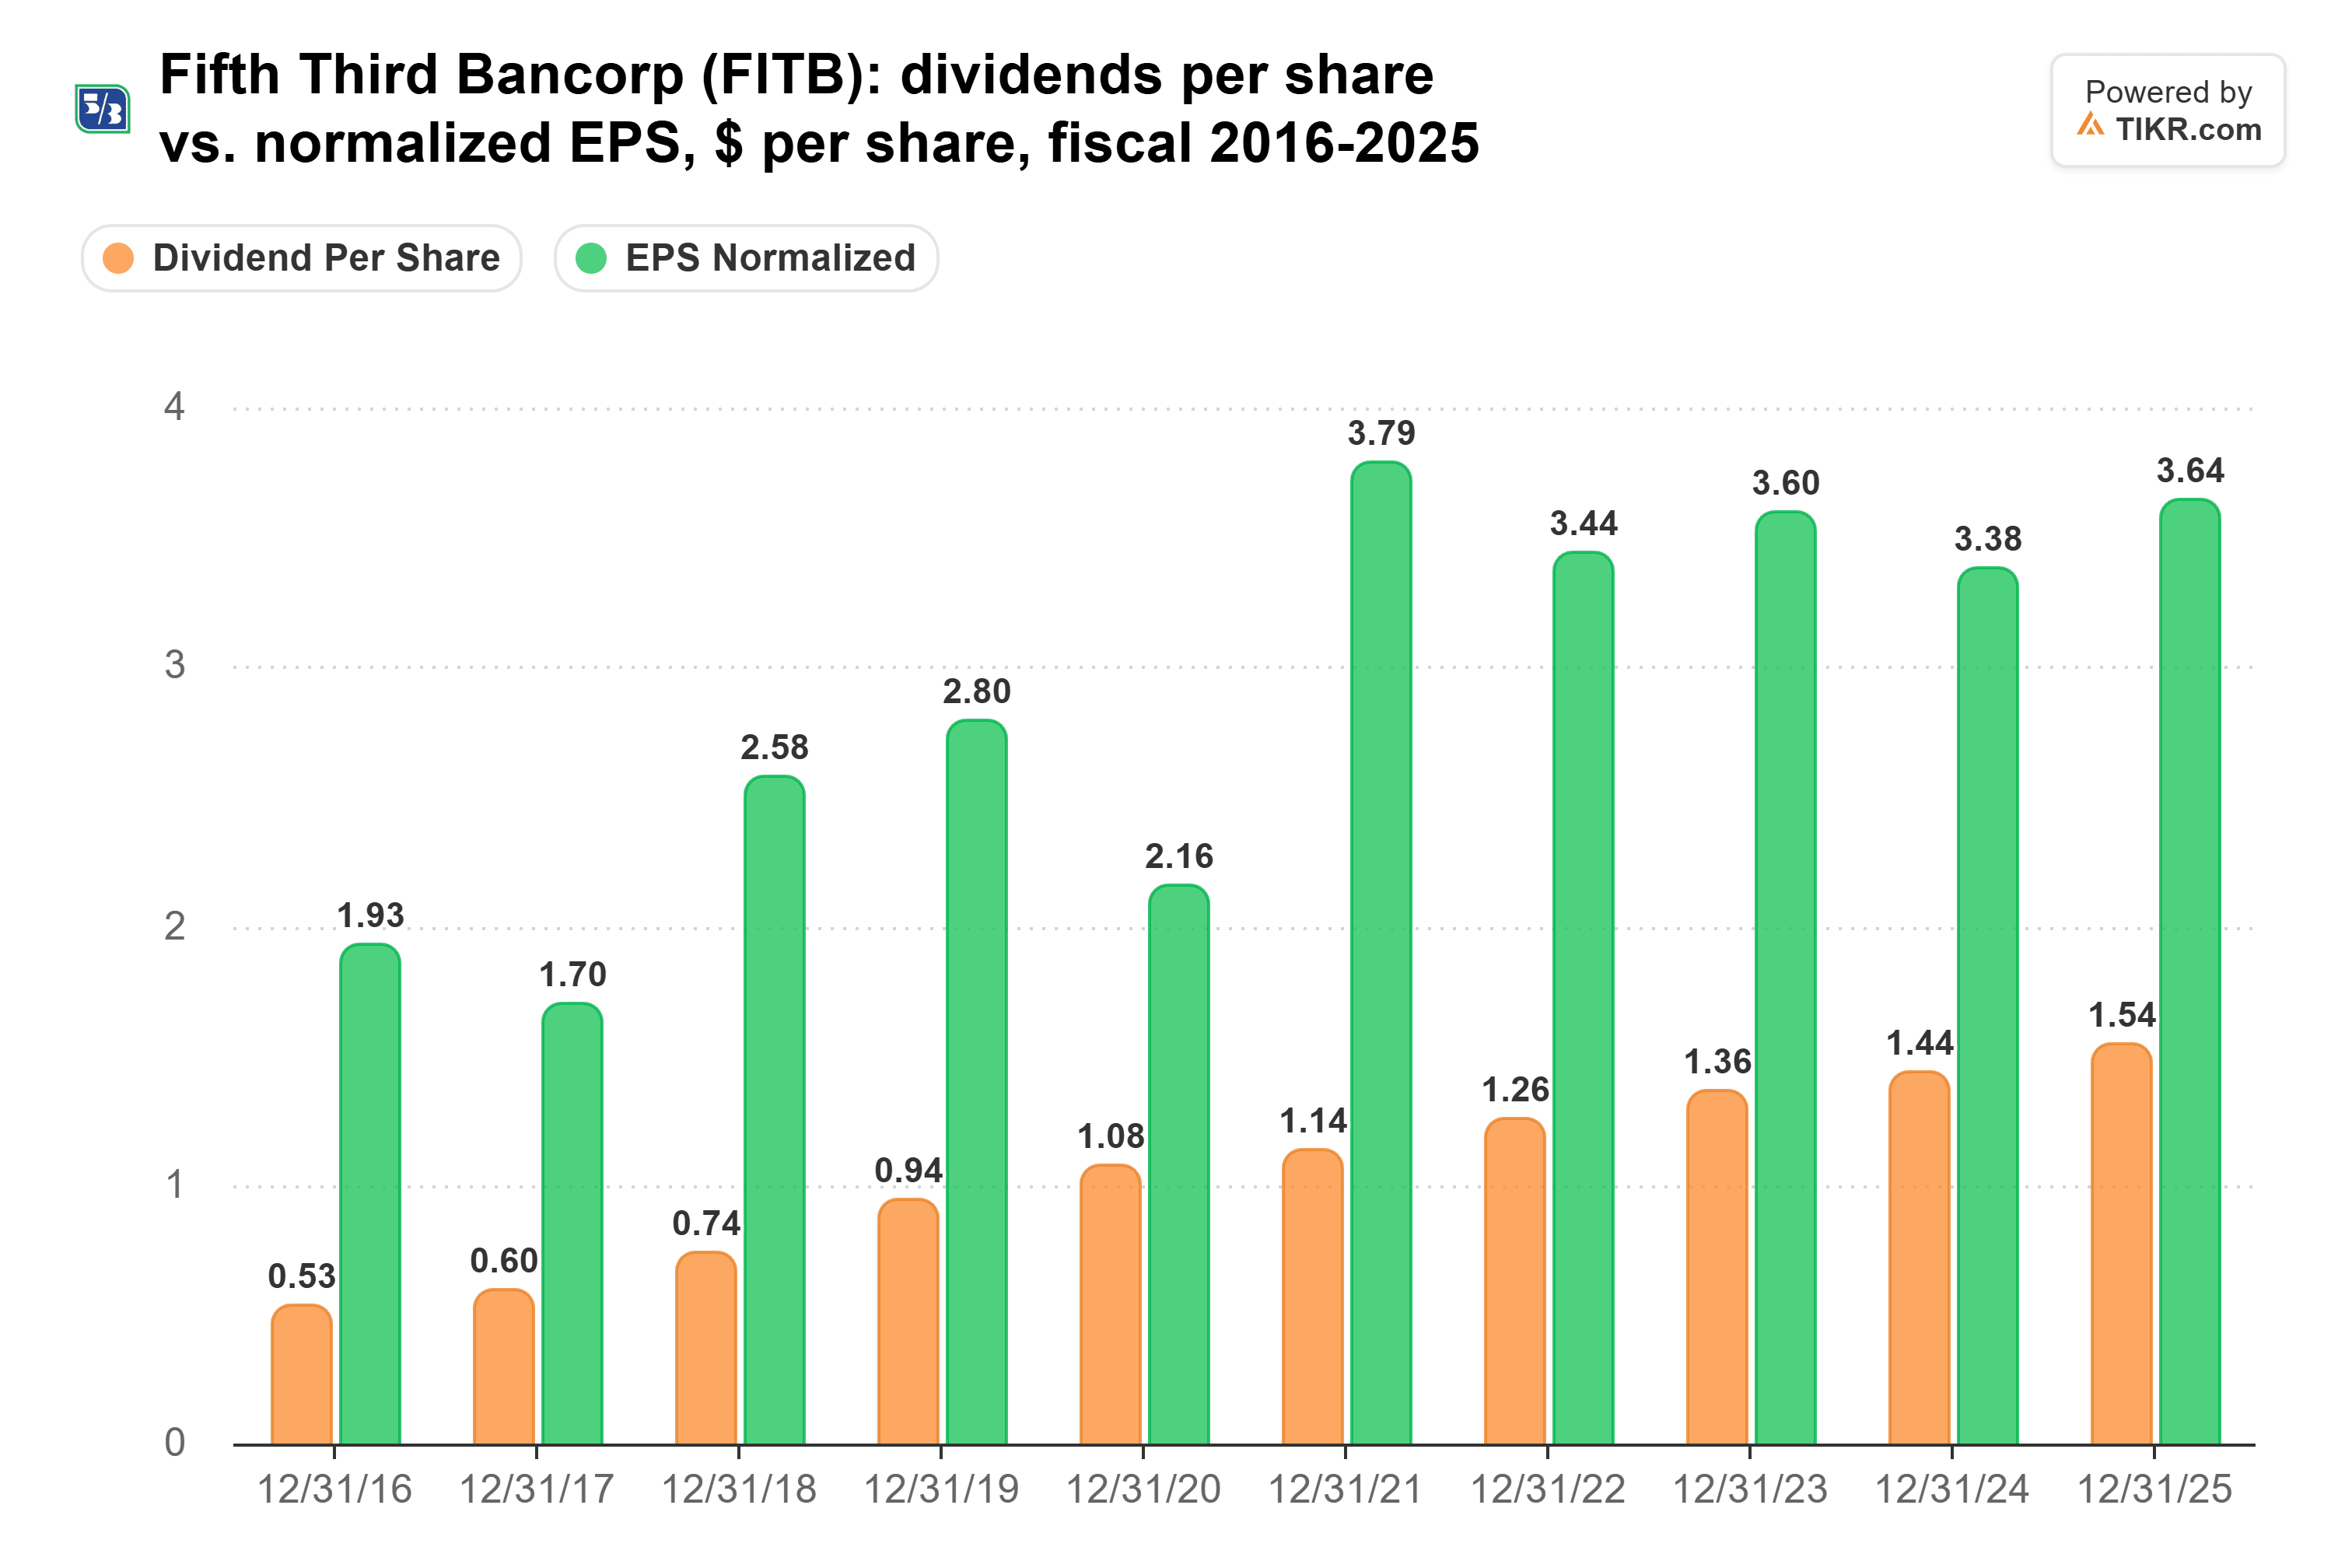
Fifth Third’s earnings have grown enough to carry those raises. Normalized EPS nearly doubled, from $1.93 in fiscal 2016 to $3.64 in fiscal 2025, while the dividend almost tripled:
Management ranks a strong dividend first among its uses of capital, ahead of organic growth and then buybacks. The coverage above gives it room to keep that order.
So which dividend wins?
If I could hold only one of these for the next 10 years, it’d be Fifth Third.
U.S. Bancorp pays more at the start: $10,000 at its 3.6% yield brings in $360 a year, against $310 at Fifth Third’s 3.1%. At each bank’s five-year growth rate, Fifth Third’s income passes U.S. Bancorp’s around 2031. By year 10 it reaches about $587, a 5.9% yield on the $10,000, against about $511. Over the whole decade, that’s about $4,355 to $4,314, close to a tie.
So I’m weighing which bank can keep its pace. Fifth Third has more earnings growth lined up behind its raises, and analysts expect its normalized EPS to reach $5.42 by fiscal 2028:
This year’s raises, 5% against 3.8%, also keep its dividend growing faster.
U.S. Bancorp is still a dividend I’d be glad to own. It pays the bigger check today, trades at 2.1x tangible book against Fifth Third’s 2.5x, and kept raising through its 2022-2023 earnings dip. It’s just that, over a decade, I’d rather hold the faster-growing dividend with the earnings to back it.
Of course, Fifth Third’s 2027 and 2028 estimates assume the Comerica savings arrive on schedule. If they slip, expect those numbers to come down.
Forget Fifth Third Bancorp: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Fifth Third Bancorp isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!