Key Takeaways
- Bloomberg’s Mark Gurman said the app paradigm will “slowly, if not quickly, dissipate” as AI calls for a new kind of operating system.
- Alphabet’s Gemini sits under Apple’s rebuilt AI models, while AppLovin’s install-driven ad business needs apps to last.
- Apple’s Services business, which includes App Store commissions, earned 42% of its fiscal 2025 gross profit on 26% of its revenue.
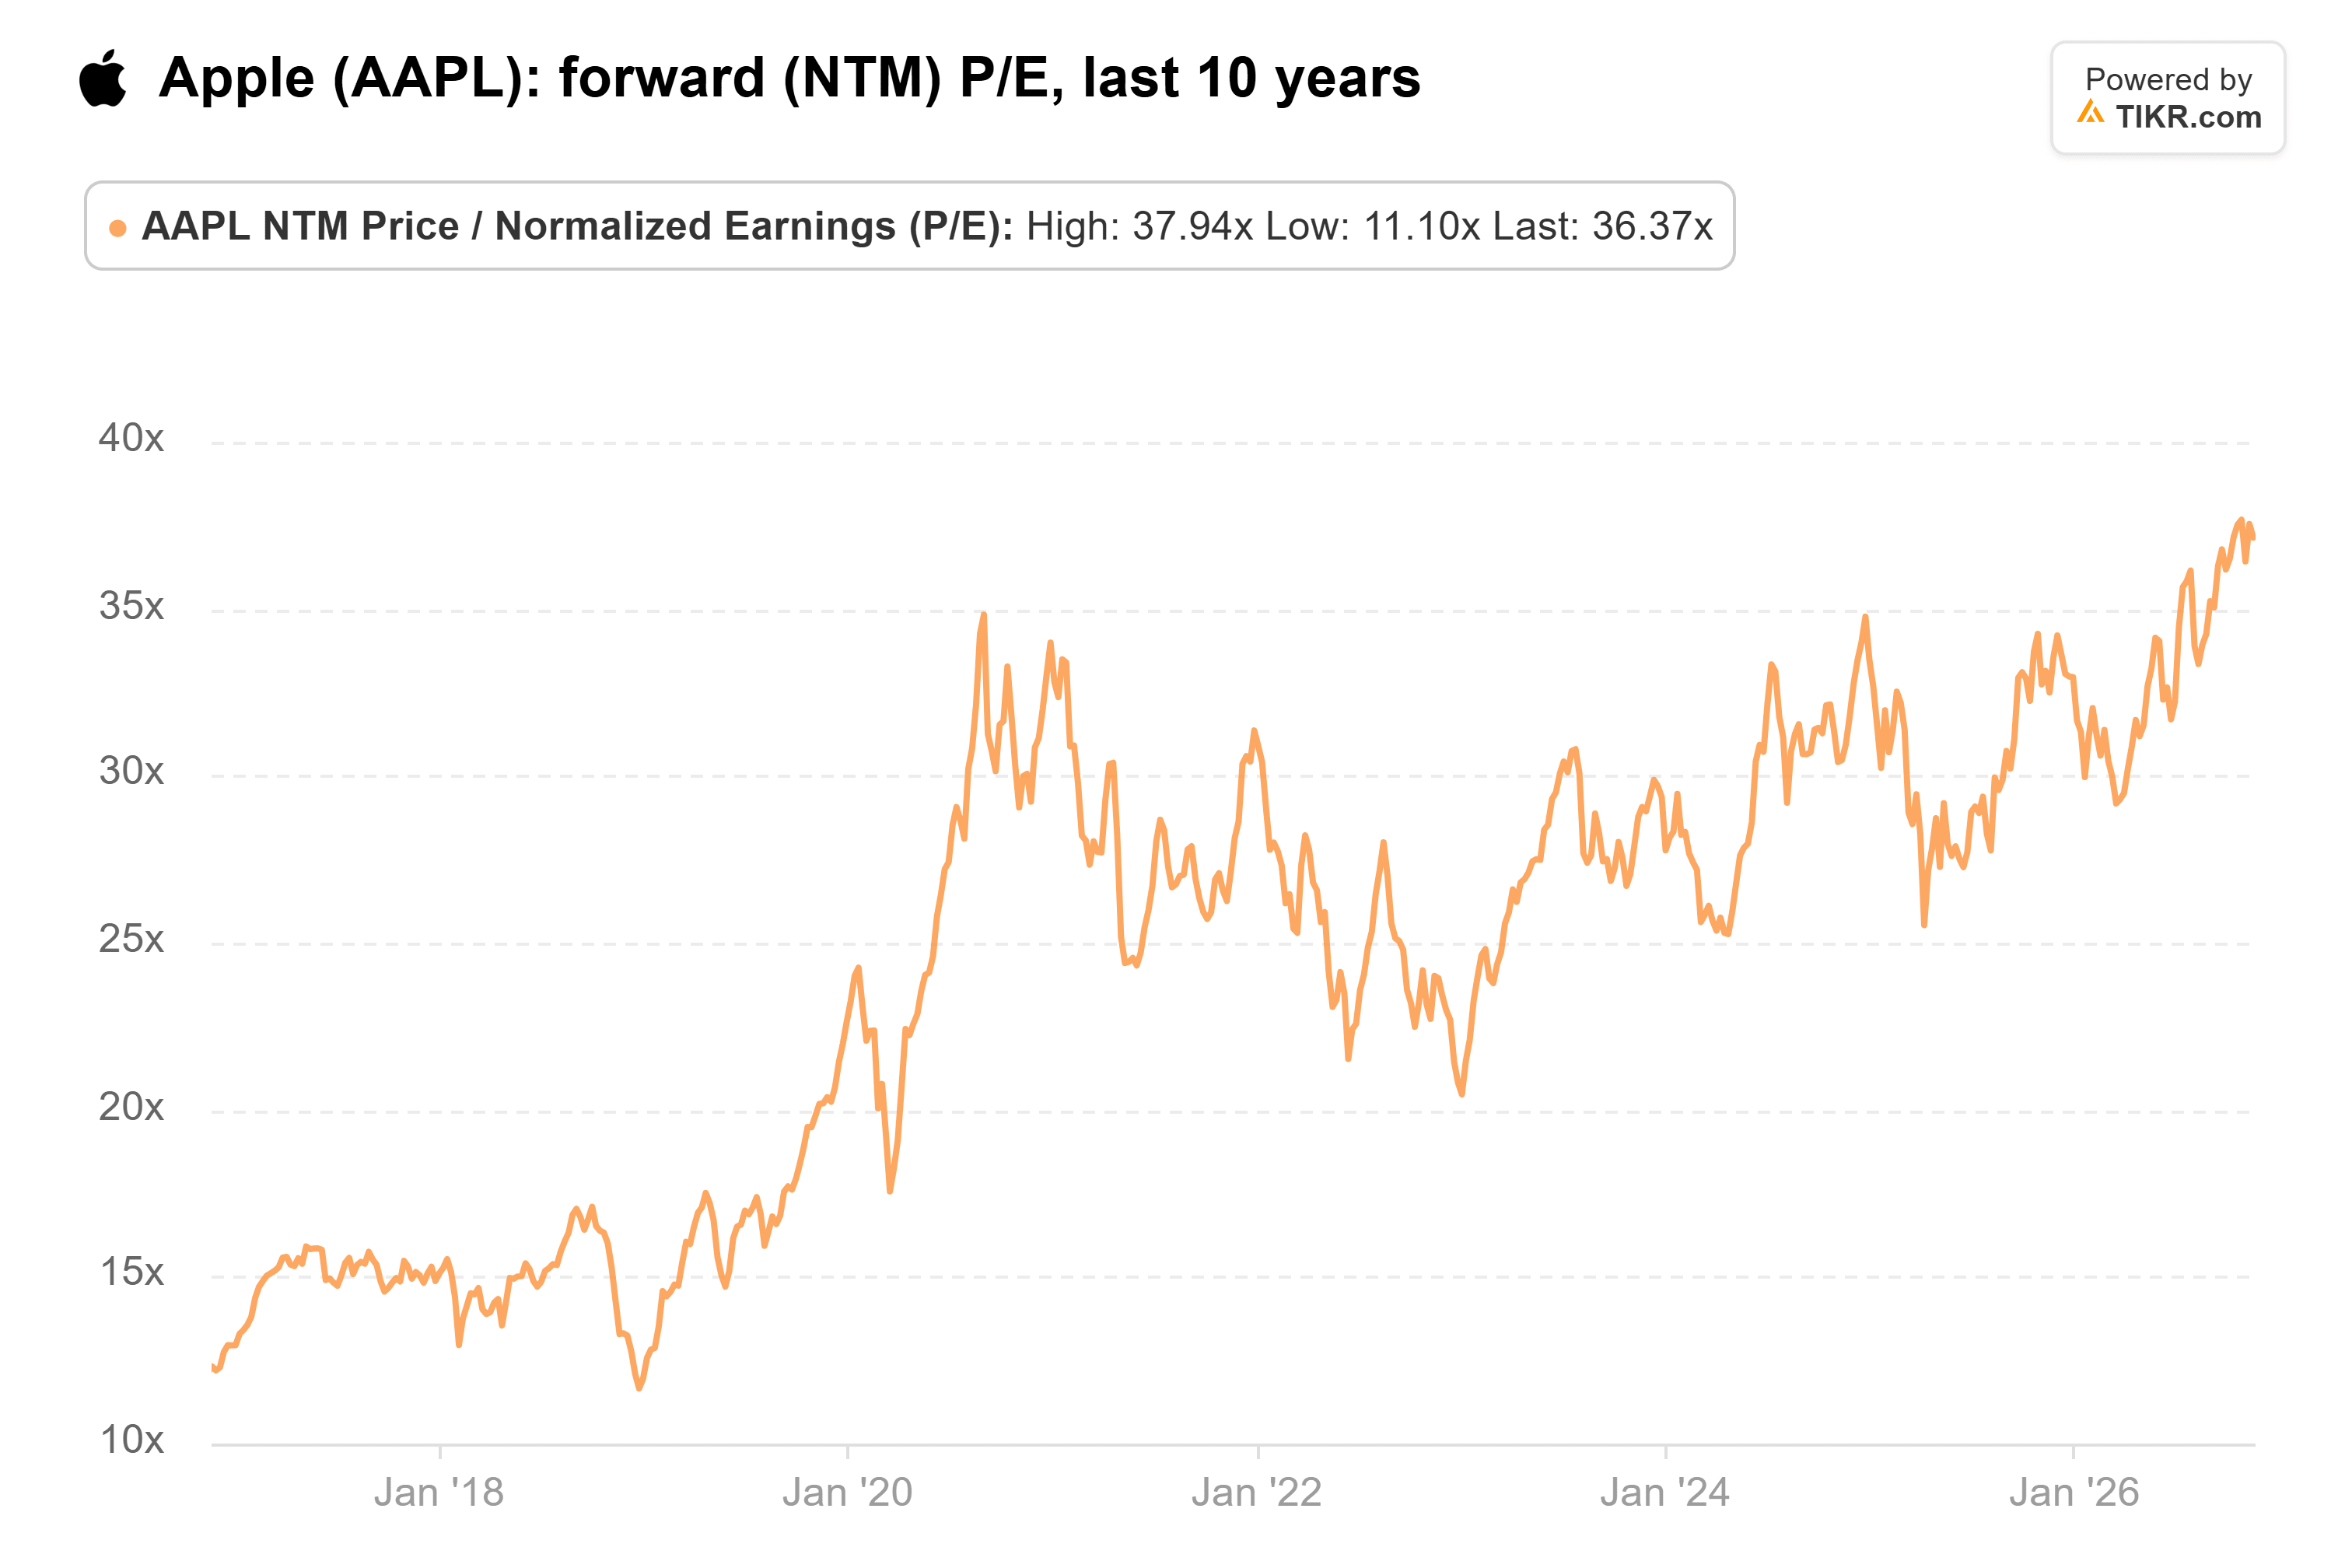
- At 36x forward earnings, nearly 50% above its 10-year average, Apple’s stock is priced as if that toll lasts for years.
Apple (AAPL) is worth close to $5 trillion and trades just below its all-time high. Bloomberg’s Mark Gurman thinks the way people use its most important product is running out of time.
On this weekend’s episode of the Bloomberg Tech podcast, Gurman asked at what point Apple starts over on the operating system, since iOS was itself a reboot for the mobile era. Then he went further:
“You’re kind of getting towards the need to have a brand new OS for the AI era. The app paradigm is going to slowly, if not quickly, dissipate.”
That’s a tough message for a company that makes its best money on apps.
And Apple would be doing the rebuild on someone else’s engine. Gurman said Apple’s foundation models have been rebuilt on a core from Alphabet (GOOG), so Gemini now sits under parts of Apple Intelligence and Siri AI. The shift reaches AppLovin (APP) too, whose ads that win app installs are built on the very model Gurman expects to fade.
TIKR tracks 45 analysts on Apple. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Apple’s margin runs on the toll
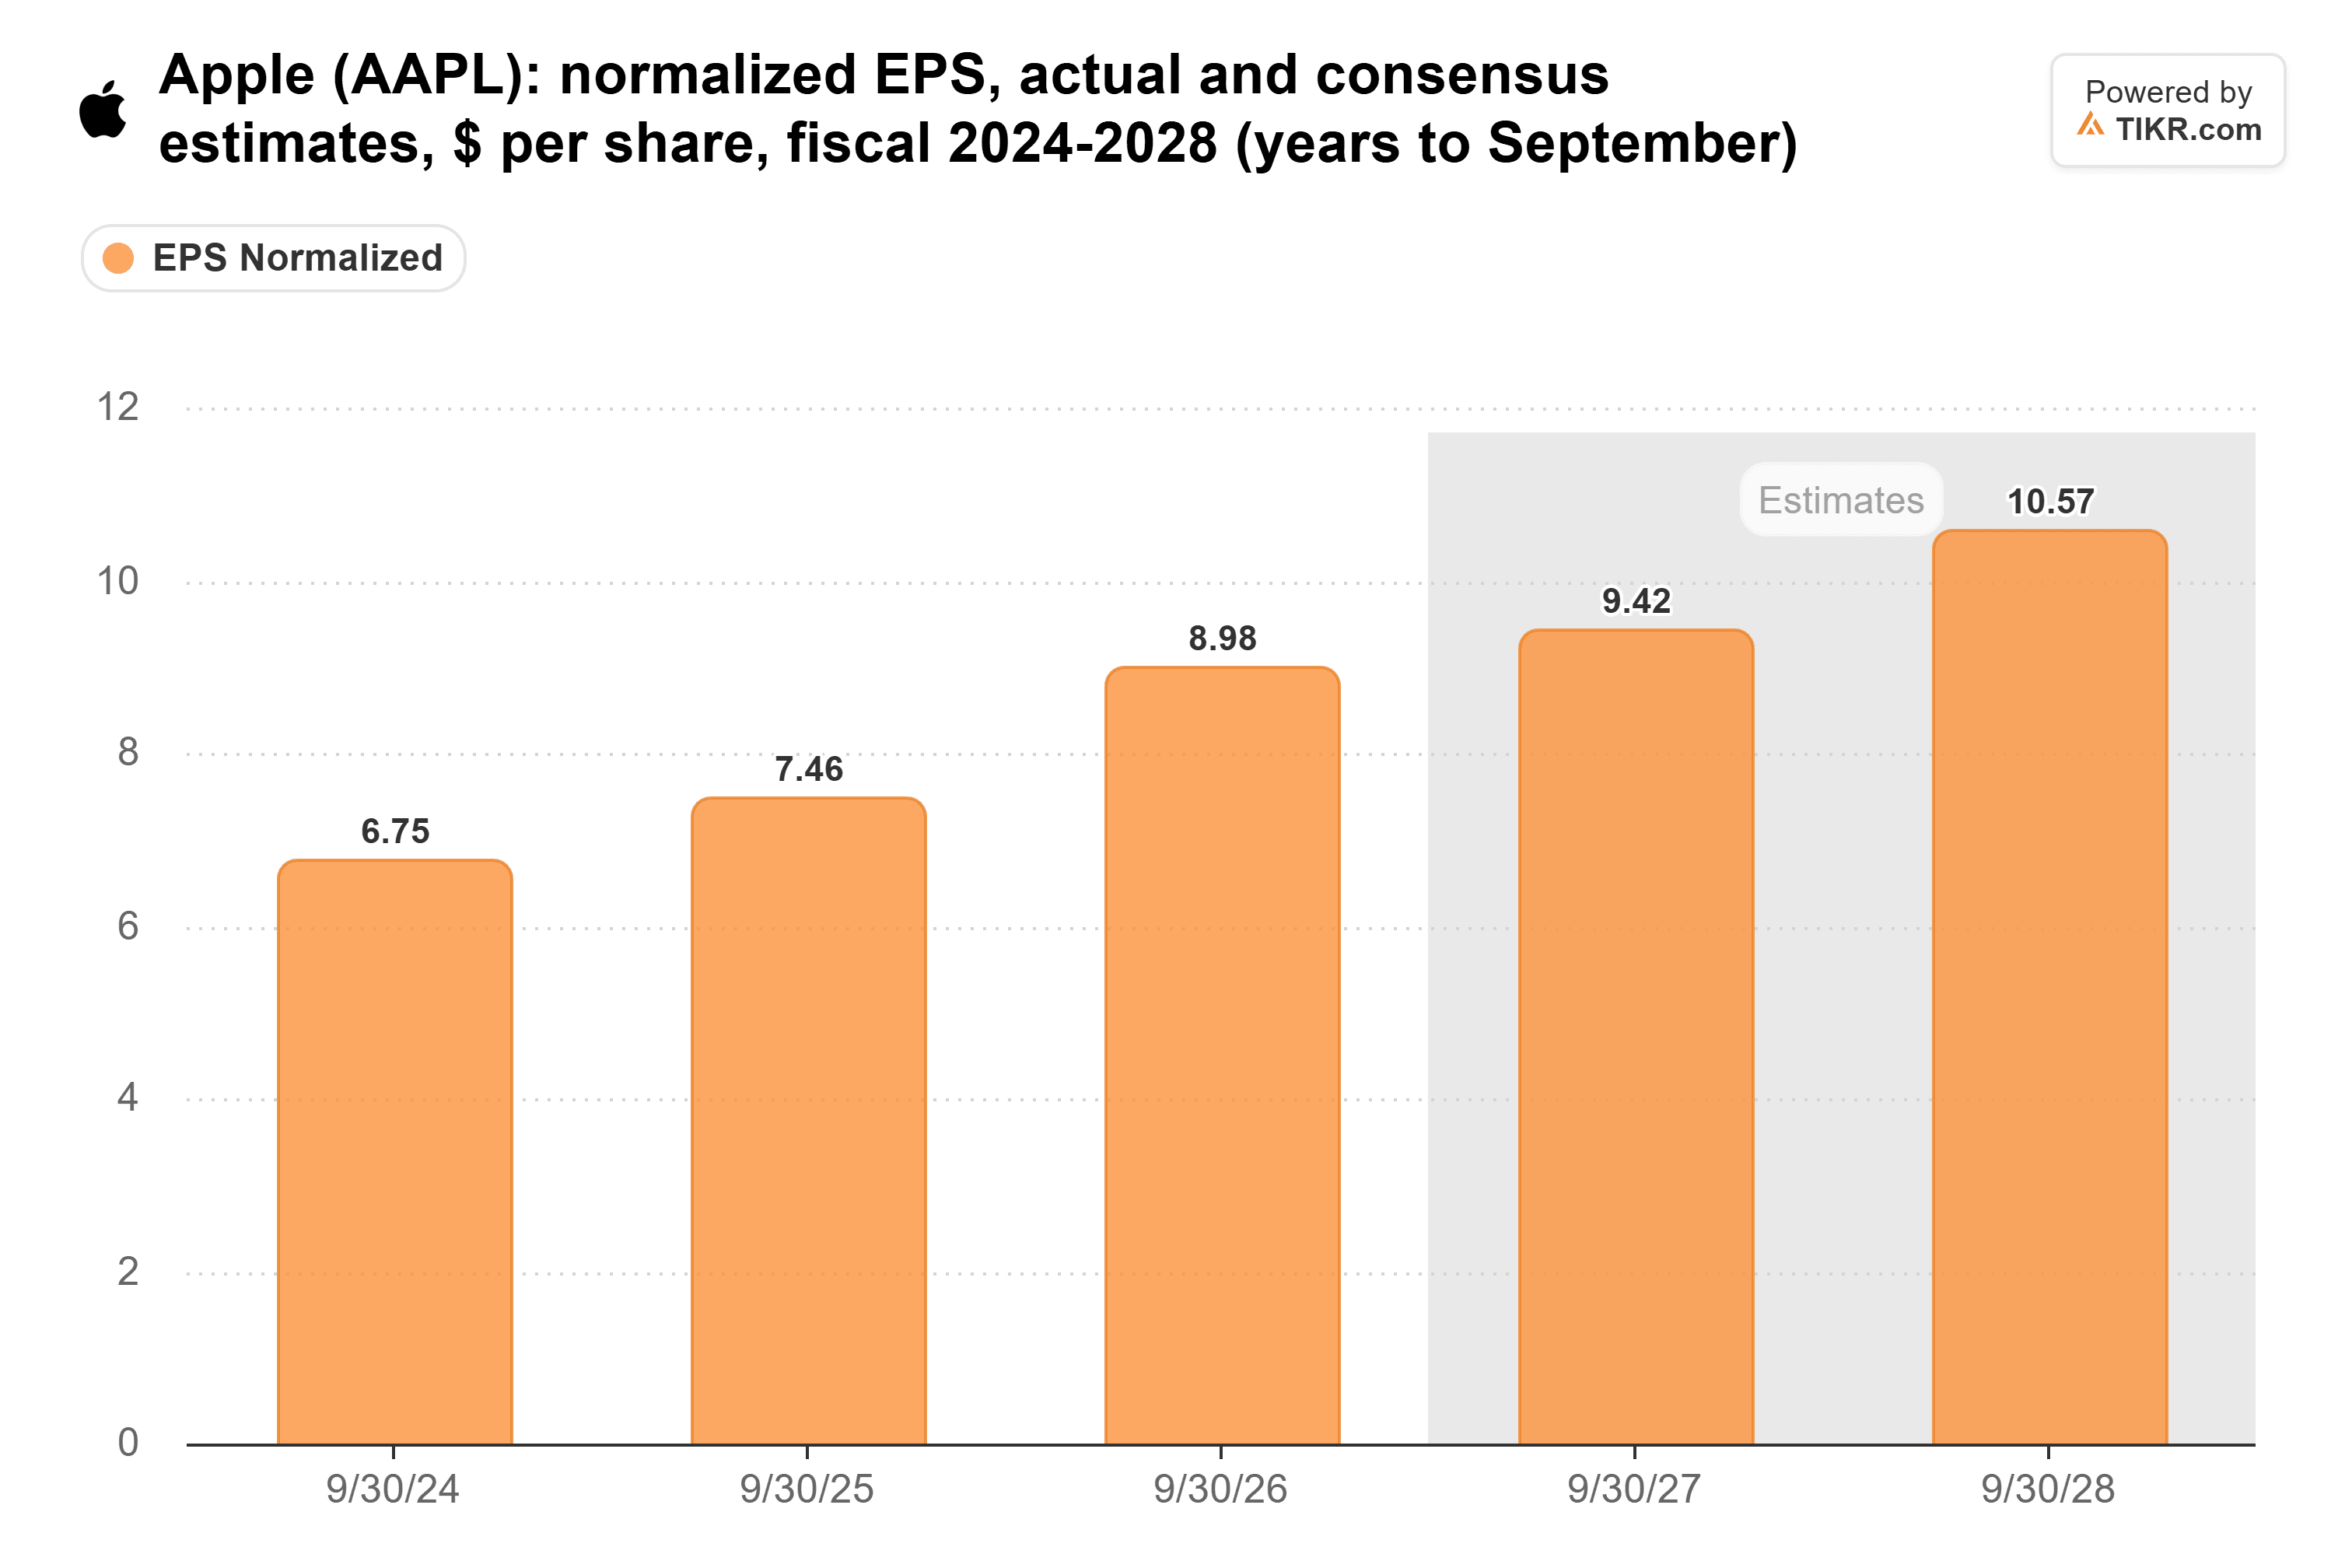
Analysts don’t expect any of this to show up soon. They see normalized EPS rising from $8.98 in fiscal 2026 to $10.57 in fiscal 2028.
Apple’s gross margin is where the toll shows up. It climbed from 38.5% in fiscal 2017 to 48.8% in fiscal 2026.

Services is a big reason for that climb. In fiscal 2025 it brought in 26.2% of Apple’s revenue and 42.2% of its gross profit, according to its annual report. Apple doesn’t report the App Store on its own, and Services also includes Google’s search payments and iCloud. But App Store commissions depend on people opening apps, and an agent that books the flight or orders dinner by itself never has to open one.
Investors are paying up for that toll anyway. Apple trades at 36x forward earnings, near the top of its 10-year range and well above its 25x average.
Apple still owns the front door
Apple has the device, and the personal context any agent needs to be useful. It can charge for agent access the way it charges for apps, and it has already started: heavier use of Siri AI comes with usage limits, and most paid iCloud+ plans unlock more of it. And in the macOS 27.3 beta, ChatGPT users reportedly need 14 steps to let a third-party tool take control of their Mac, up from four.
The weak spot is the brain behind that door. On Nov. 19, Bloomberg reported that Apple is building its own AI agent, which could launch as soon as the end of 2027 on the models it rebuilt on Gemini. Google added computer control to Gemini the same day.
That puts Alphabet in the stronger spot. It supplies the core of Apple’s AI and runs Android and Google Play, where Gurman thinks Google has “done a good job sort of rebuilding the plane in the air.” Whether apps hold on or agents take over, Alphabet sits on both sides.
AppLovin has the opposite problem. Its third-quarter revenue rose 55% to $2.18 billion, mostly from game makers paying for installs. My guess is that games will be among the last apps an agent replaces. But if shoppers start buying through an assistant, AppLovin’s push to sell the same ads to consumer brands has fewer people to reach.
Not at 36x
“Slowly” gives Apple some cover, and analysts’ numbers through fiscal 2028 don’t need the shift to happen fast. The problem is the price: 36x is a bet that the App Store keeps collecting for years, while the agent meant to protect that toll runs on a rival’s core and is more than a year away. I wouldn’t pay that for a toll booth when the road might move.
Apple reports its December quarter in late January. Services growth back in the double digits, or a first sign that Siri AI is selling iCloud+ upgrades, would make that multiple a lot easier to defend.
So what is Apple stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!