Key Takeaways
- Consolidated Edison yields 3.0% and Sempra 3.4%, and both declared their regular quarterly dividends in the past five weeks.
- Consolidated Edison has raised its dividend for 52 straight years, but it keeps selling new shares to fund its capital plan.
- Sempra paid out 55% of its normalized EPS in fiscal 2025, against 60% for Consolidated Edison, though it carries more debt.
- Sempra will lay out its 2027-2031 capital plan, including a bigger build-out in Texas, in February.
Anyone counting on 20 years of dividend income is going to look hard at utilities like Consolidated Edison (ED) and Sempra (SRE). And both just gave income investors news to weigh.
On Oct. 15, Con Edison declared a quarterly dividend of $0.8875 a share, which it says marks its “52nd straight year of dividend increases.” Sempra declared its $0.6575 quarterly dividend on Nov. 11. The next day, it closed the sale of a 45% stake in Sempra Infrastructure Partners to affiliates of KKR.
Both fund their growth with new debt and stock, so each is judged on the share of its normalized EPS it pays out. If I could only hold one for the next 20 years, which would it be?
| Metric | Consolidated Edison (ED) | Sempra (SRE) |
|---|---|---|
| Dividend yield | 3.0% | 3.4% |
| Annual dividend | $3.55 | $2.63 |
| Dividend growth, fiscal 2020-2025 | 2.1% a year | 4.3% a year |
| Payout ratio of normalized EPS, fiscal 2025 | 60% | 55% |
| Payout ratio of normalized EPS, fiscal 2026 consensus | 58% | 51% |
| Net debt/EBITDA (LTM) | 4.4x | 5.7x |
| Forward P/E (NTM) | 19x | 15x |
Source: TIKR and StockAnalysis, at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Con Edison keeps selling shares to grow
Con Edison’s earnings are growing with its rate base. A bigger electric rate base at its CECONY utility added $0.17 a share to third-quarter results against a year earlier, and adjusted EPS rose to $2.07 from $1.90 a year earlier.
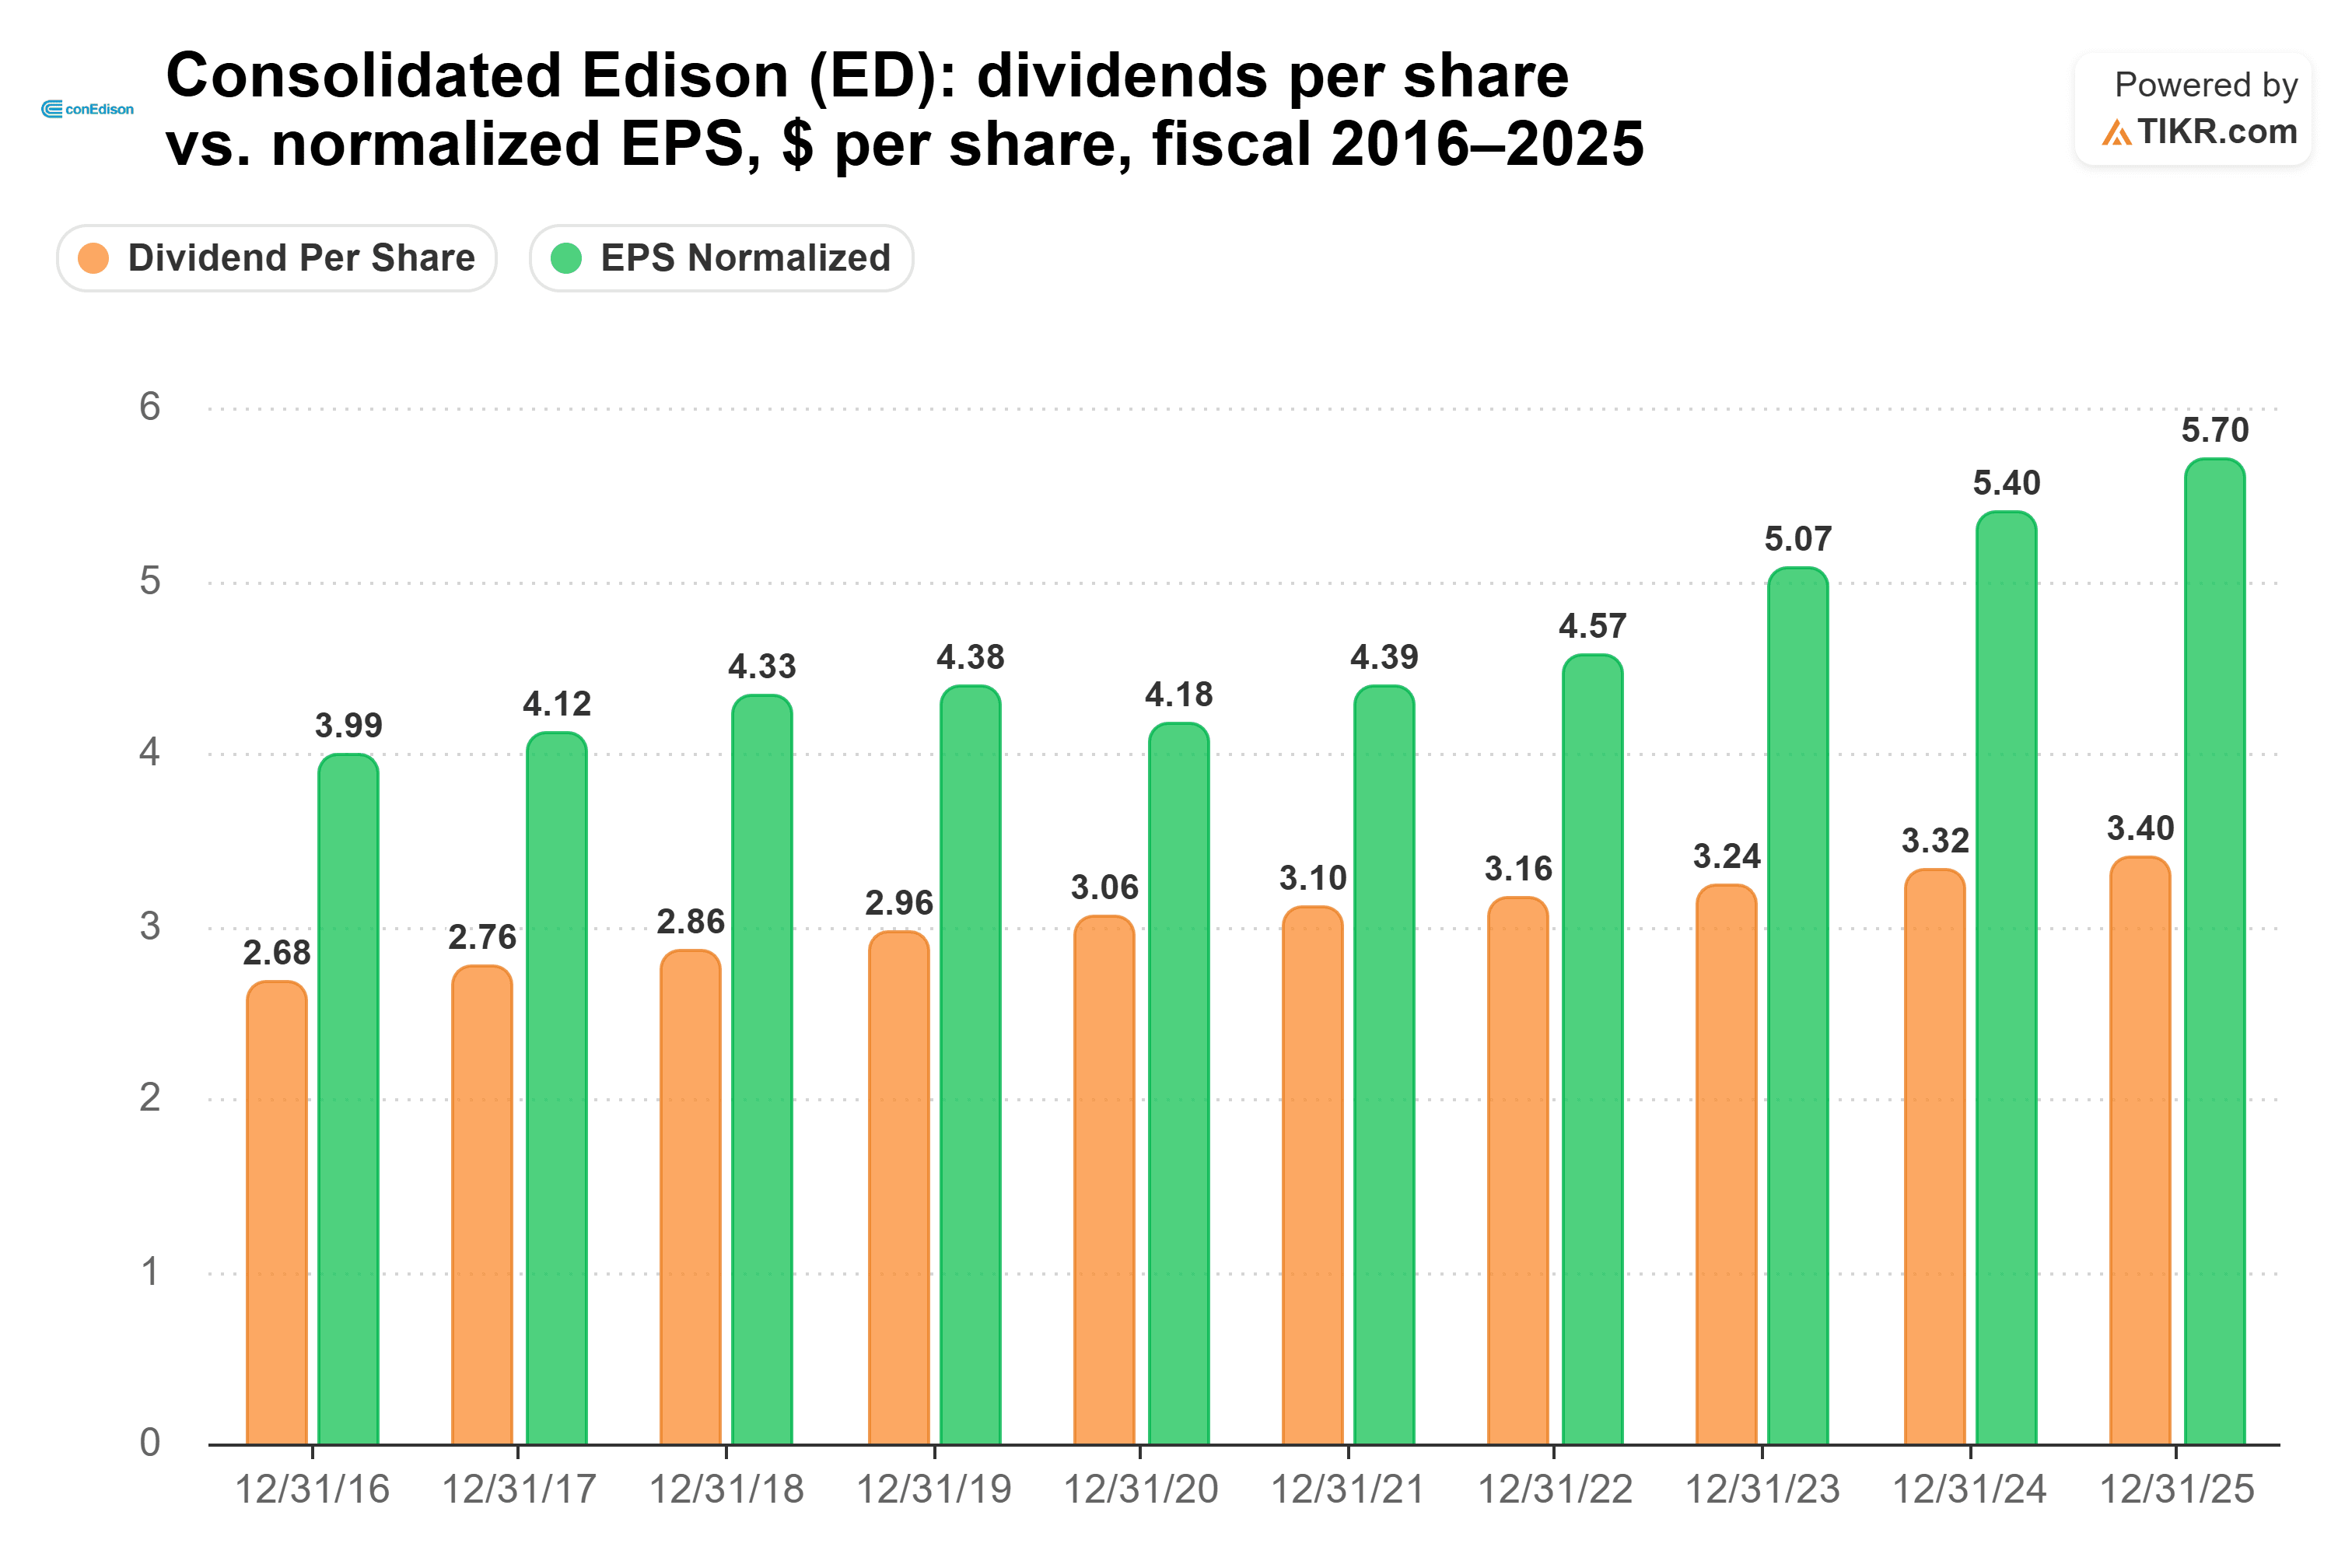
That leaves the dividend well-covered. Con Edison paid out 60% of its normalized EPS in fiscal 2025, and consensus has that at 58% for fiscal 2026. The ratio has come down from 73% in fiscal 2020, as normalized EPS rose from $4.18 to $5.70 and the dividend went from $3.06 to $3.40:
But Con Edison keeps issuing stock to pay for its plan. New shares took $0.05 off third-quarter EPS, and on Nov. 16 it announced an offering of 6 million more through a forward sale.
Sempra is betting big on Texas
Sempra’s Texas utility gives it more room to grow. Sempra expects to raise Oncor’s base capital plan about 20% for 2027-2031, from $47.5 billion for 2026-2030. Third-quarter adjusted EPS jumped to $1.40 from $1.11 a year earlier, and Sempra is guiding to the high end of its $4.80-$5.30 range for 2026.
Sempra paid out 55% of its normalized EPS in fiscal 2025, and consensus puts it at 51% for fiscal 2026. Still, the ratio climbed from 50% in fiscal 2022 to 55% in fiscal 2025. Normalized EPS sat between $4.61 and $4.69 from fiscal 2023 to fiscal 2025, while the dividend rose from $2.29 in fiscal 2022 to $2.58:
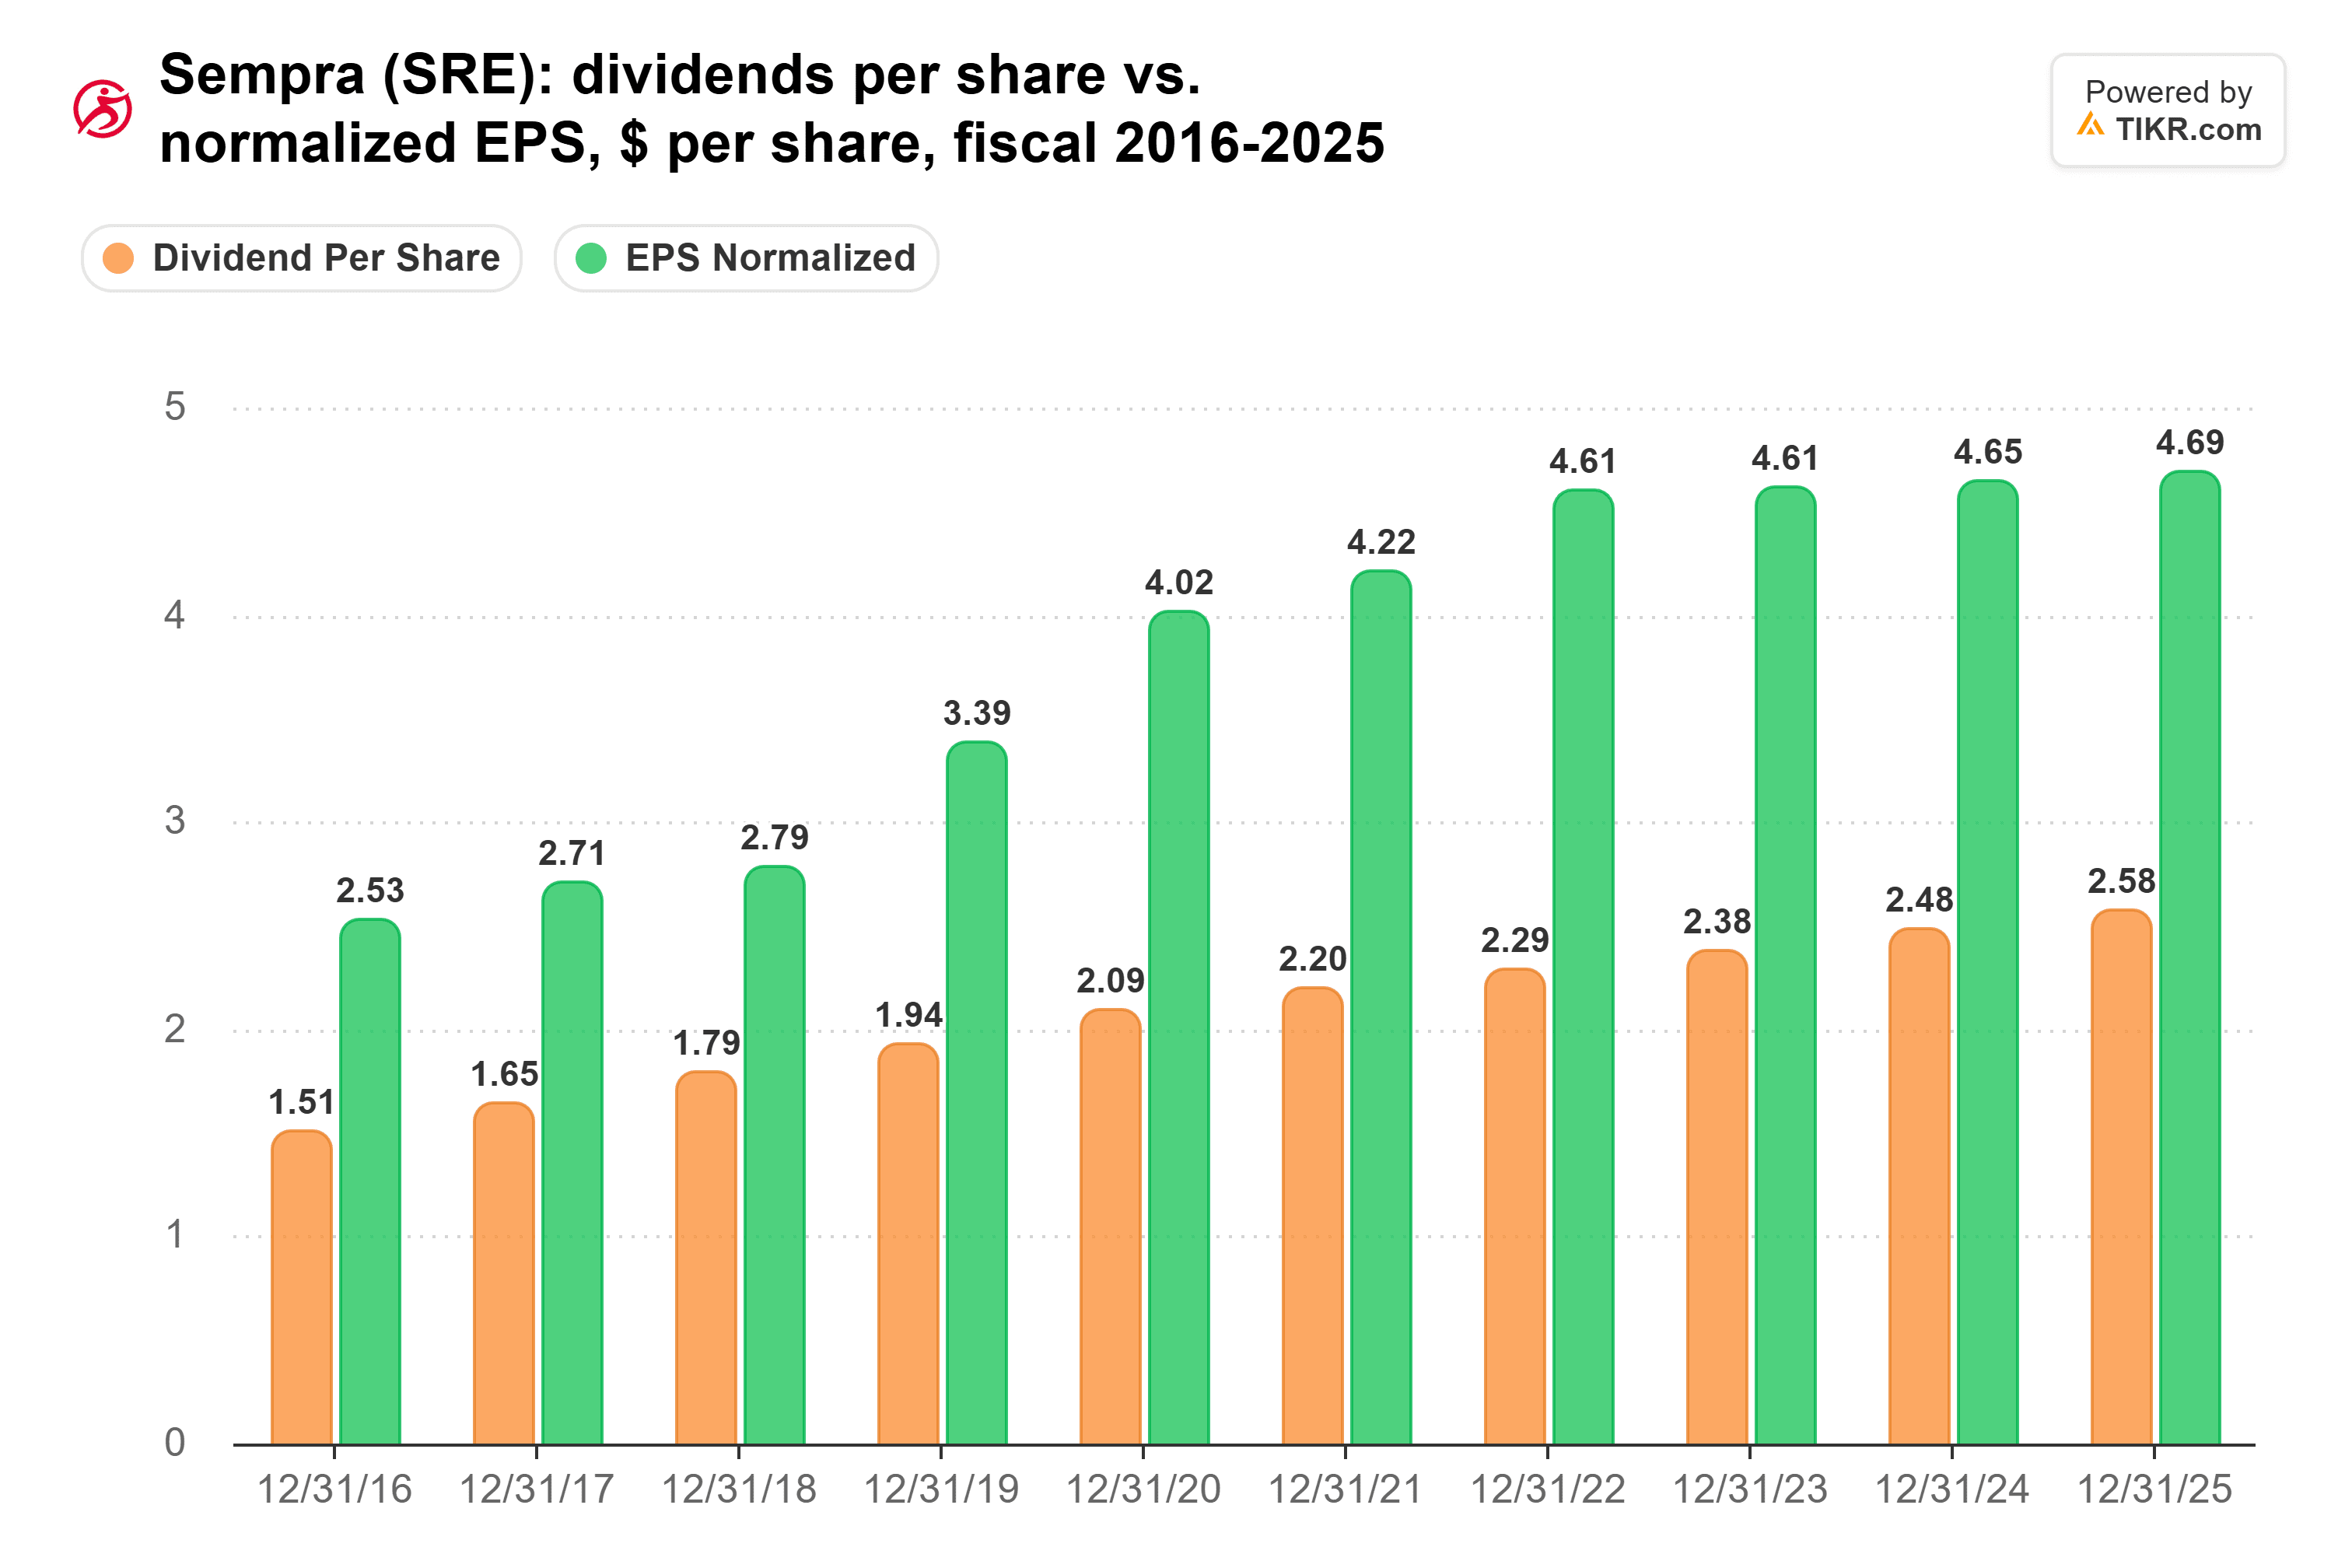
Sempra also carries more debt. Over the last twelve months, its EBIT covered interest 2.5x, against 3.0x at Con Edison. Chairman and CEO Jeffrey Martin said on the third-quarter call that “with the completion of the SI Partners transaction, we expect to pay down debt, strengthen the balance sheet and lower our risk profile to support future growth.”
So which dividend wins?
If I can only hold one for the next 20 years, it’s Sempra. It pays out less of its earnings, it has grown its dividend about twice as fast, and analysts expect its normalized EPS to climb from $4.69 in fiscal 2025 to $6.02 in fiscal 2028:

That’s in line with the 7% to 9% long-term EPS growth Sempra just affirmed. At each stock’s 5-year dividend growth rate, $10,000 in Sempra pays about $10,448 over the 20 years, against about $7,384 in Con Edison. And at 15x forward earnings, Sempra costs less than Con Edison’s 19x.
None of this makes Con Edison’s dividend shaky. A 52-year streak is one management will work very hard to keep, Con Edison carries less debt, and its 4.4% raise in 2026 ran well ahead of its 2.1% pace from fiscal 2020 to fiscal 2025. It’s just that, over 20 years, I’d rather own the dividend with more room under it and faster earnings growth behind it, without a steady stream of new shares.
Of course, much of Sempra’s growth has to come from Texas. Its 2027-2031 capital plan, due in February under new CFO Justin Bird, will show how much bigger Oncor’s build-out gets. A California decision that goes the wrong way would slow Sempra down.
Forget Sempra: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Sempra isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!