Key Takeaways
- Super Micro stock is down 33% in the past month, even after record fiscal first-quarter revenue of $19.9 billion and a fiscal 2027 revenue outlook raised to $72 billion to $82 billion.
- An AI hardware selloff hit the whole group, and Nvidia and Dell fell further. On top of that, Bloomberg reported that prosecutors are looking at whether entities tied to Alice Huang helped smuggle Super Micro products into China.
- Thinner margins and one customer at 44% of quarterly revenue are real risks, but the stock’s forward P/E sits near a five-year low.
- At this price the numbers favor buying for investors who can live with the legal overhang, and fiscal second-quarter results in early February are the next test.
Super Micro Computer (SMCI) stock is down 33% in the past month, right after the biggest quarter in its history.
Much of the drop came in an AI hardware selloff that hit chip supplier Nvidia (NVDA) and rival Dell Technologies (DELL) even harder. A Nov. 12 report put the Justice Department back in Super Micro’s headlines, and on Nov. 20 the stock fell another 9% as the selloff deepened.
TIKR tracks 18 analysts on Super Micro Computer. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Super Micro Computer, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Super Micro Computer’s Analyst Ratings
A record quarter, and a stock going the other way
After the close on Oct. 20, Super Micro said fiscal first-quarter revenue would land between $18.5 billion and $19.5 billion, far above its own guidance and the $15.23 billion analysts expected. On Nov. 3, it beat even that: $19.9 billion, nearly 4x the year before, with non-GAAP EPS of $1.81. Management guided the December quarter to $19.5 billion to $21.5 billion and raised its fiscal 2027 outlook to $72 billion to $82 billion, from $65 billion to $72 billion.
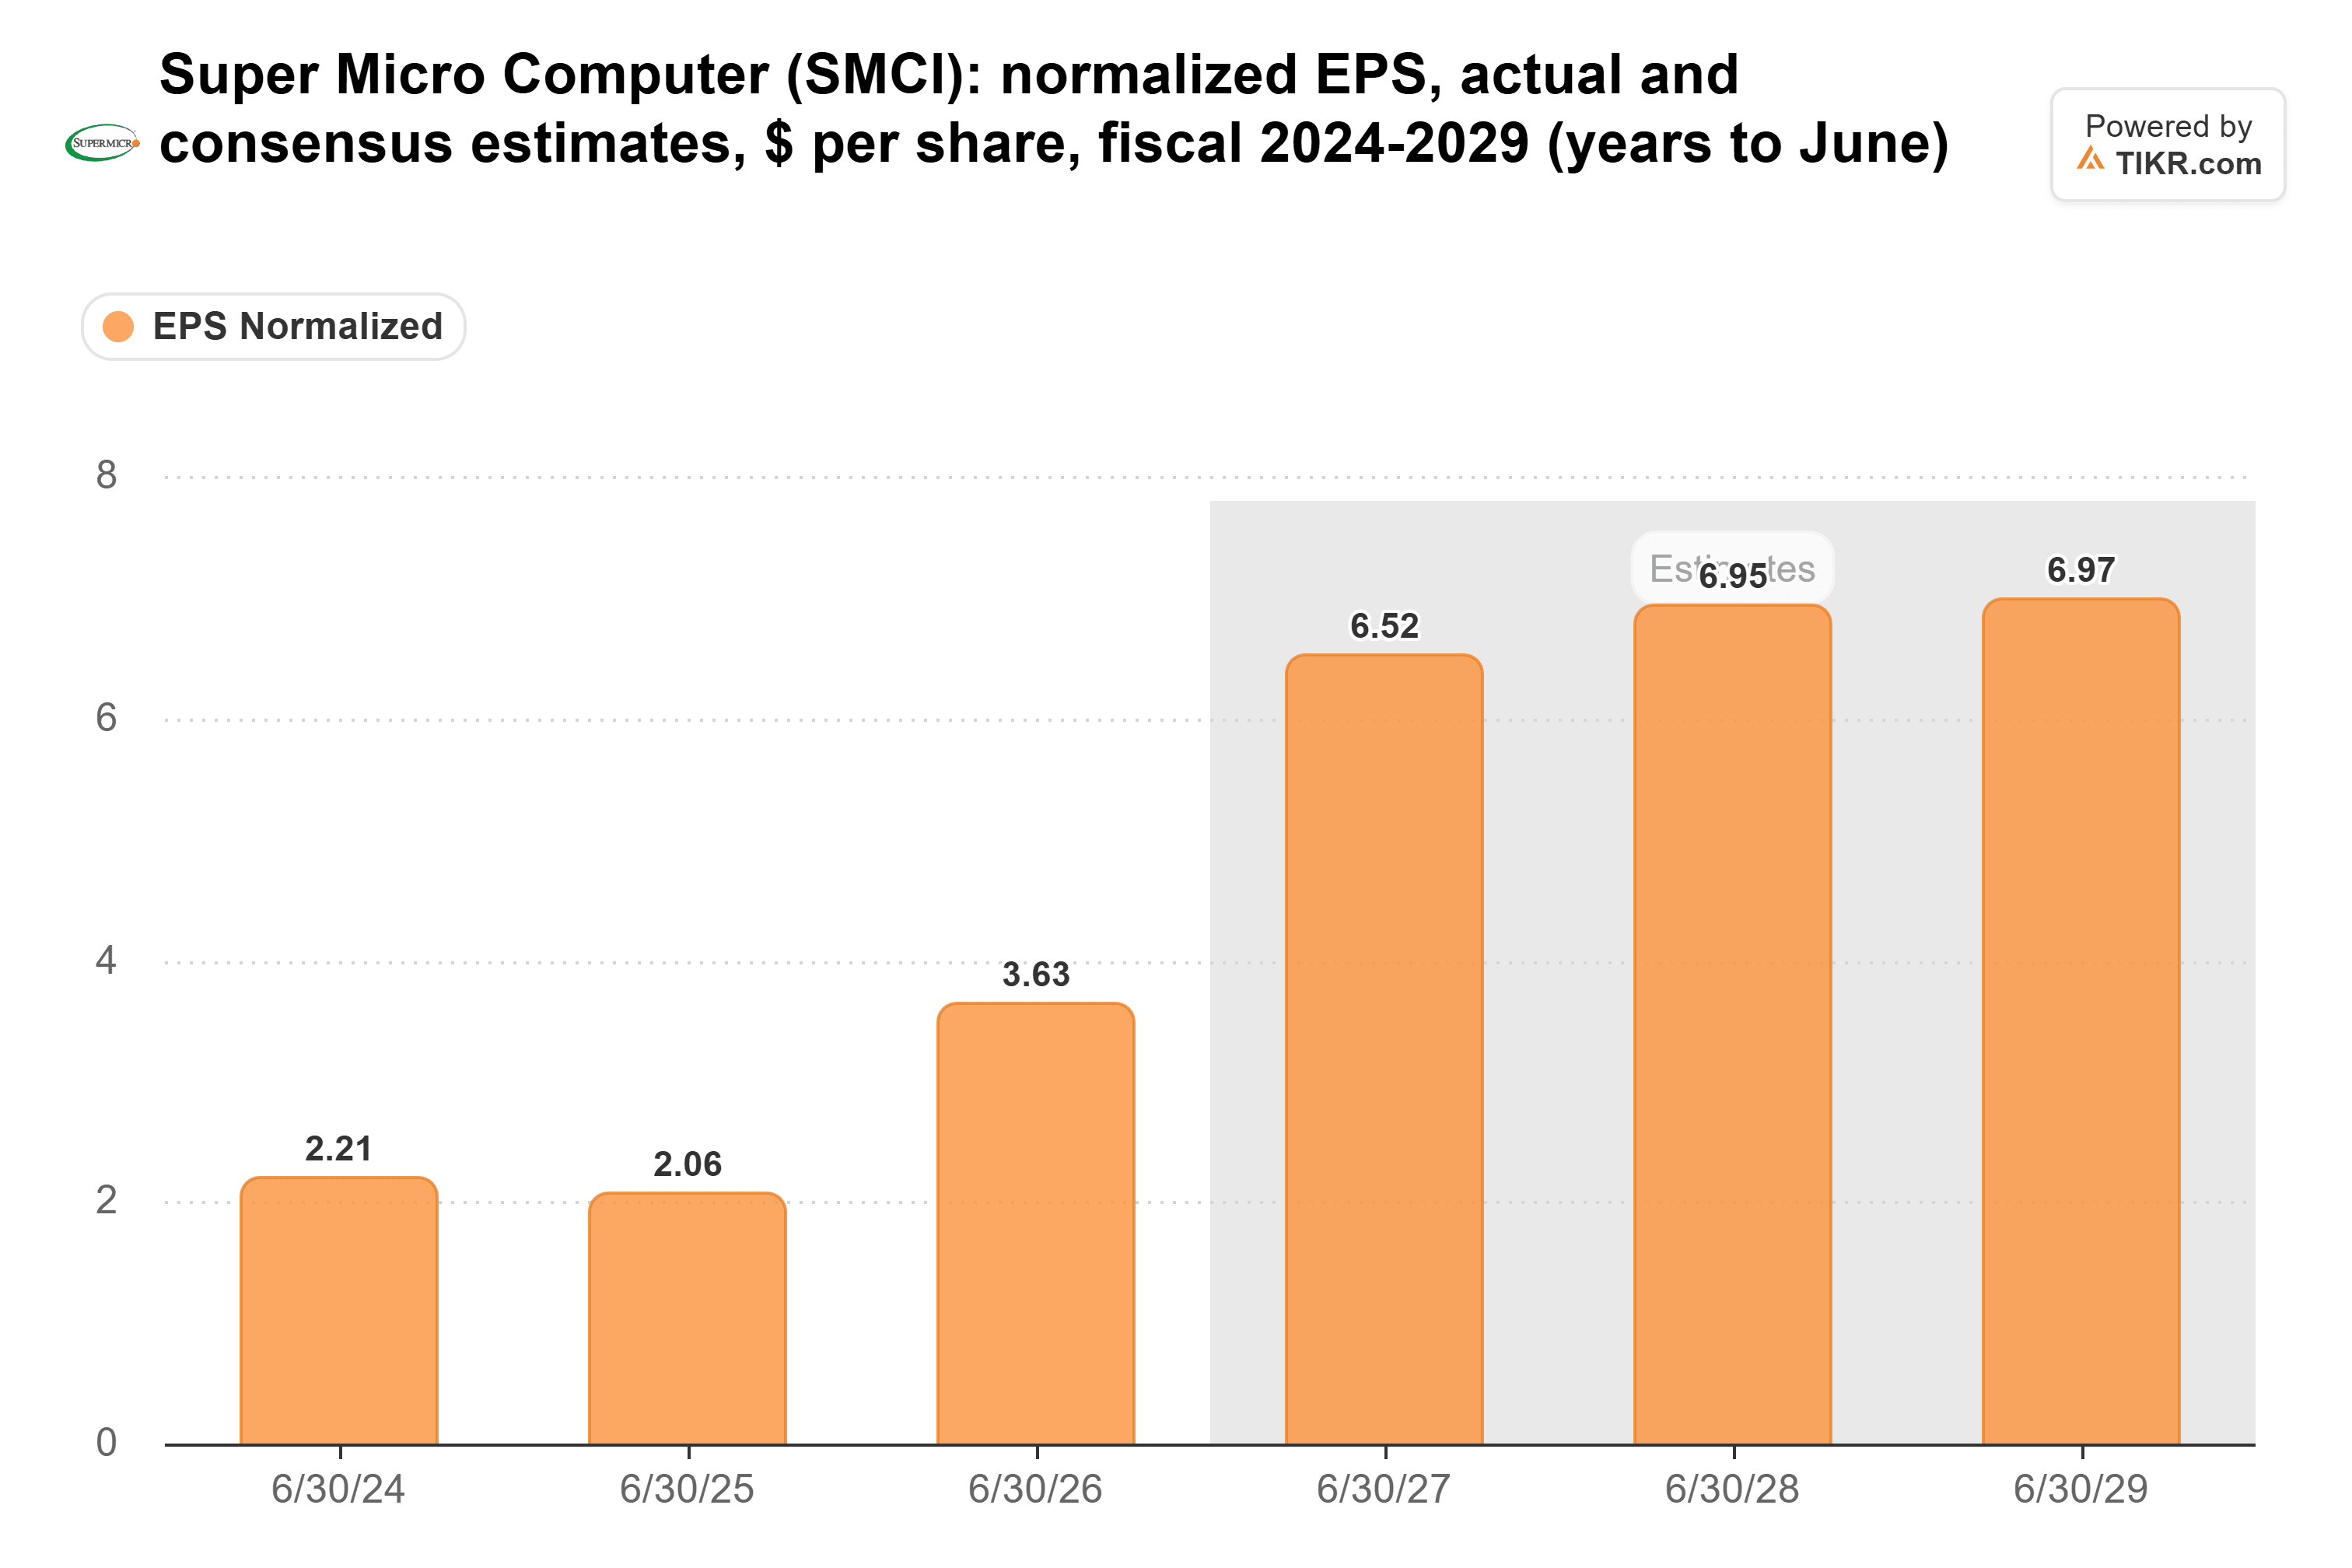
Analysts now expect $6.52 of normalized EPS for fiscal 2027, up from $4.75 for the next 12 months before the report, and more in fiscal 2028:
The fine print the market didn’t like
GAAP gross margin fell to 12.7%, from 17.5% in the June quarter, though above the 9.3% of a year earlier. That’s still well below the 18.0% of fiscal 2023. One data center customer made up 44% of the quarter’s revenue, CFO Mark Long said. Operations used $434 million of cash, and Super Micro ended September with $6.9 billion of cash against $8.6 billion of debt.
The probe lands on Super Micro
In October, a contractor tied to Super Micro pleaded guilty in a case over an alleged $2.5 billion scheme to divert AI servers to China, though the company wasn’t charged. On Nov. 12, Bloomberg reported federal prosecutors are examining whether entities tied to Alice Huang, a former Megaspeed executive, helped smuggle Super Micro products into China. Super Micro said Megaspeed “is not, and has never been, a Supermicro customer.” No charge names the company, though it has received a federal grand jury subpoena from Manhattan prosecutors.
Nvidia and Dell fell even harder
Nvidia fell 42%. Jensen Huang’s exit as CEO was announced Nov. 12, and on Nov. 20 the stock dropped 14% after Reuters reported SEC staff are examining potential accounting issues, which neither Nvidia nor the SEC has confirmed. On Nov. 17, Nvidia reported data center revenue up 110% and guided to about $130 billion of revenue for the January quarter, with no China data center compute sales assumed. AI solutions were 71% of Super Micro’s September-quarter revenue, so that guide matters here.
Dell fell 40% despite a record $95 billion AI backlog at the end of July. It still trades at nearly 3x Super Micro’s forward multiple, a gap that reflects Super Micro’s probe and margins. Dell’s Nov. 24 report will show whether that AI server demand is holding.
Priced for trouble
Super Micro trades at under 4x forward earnings, around its lowest level in five years and far below its 14.6x five-year average:
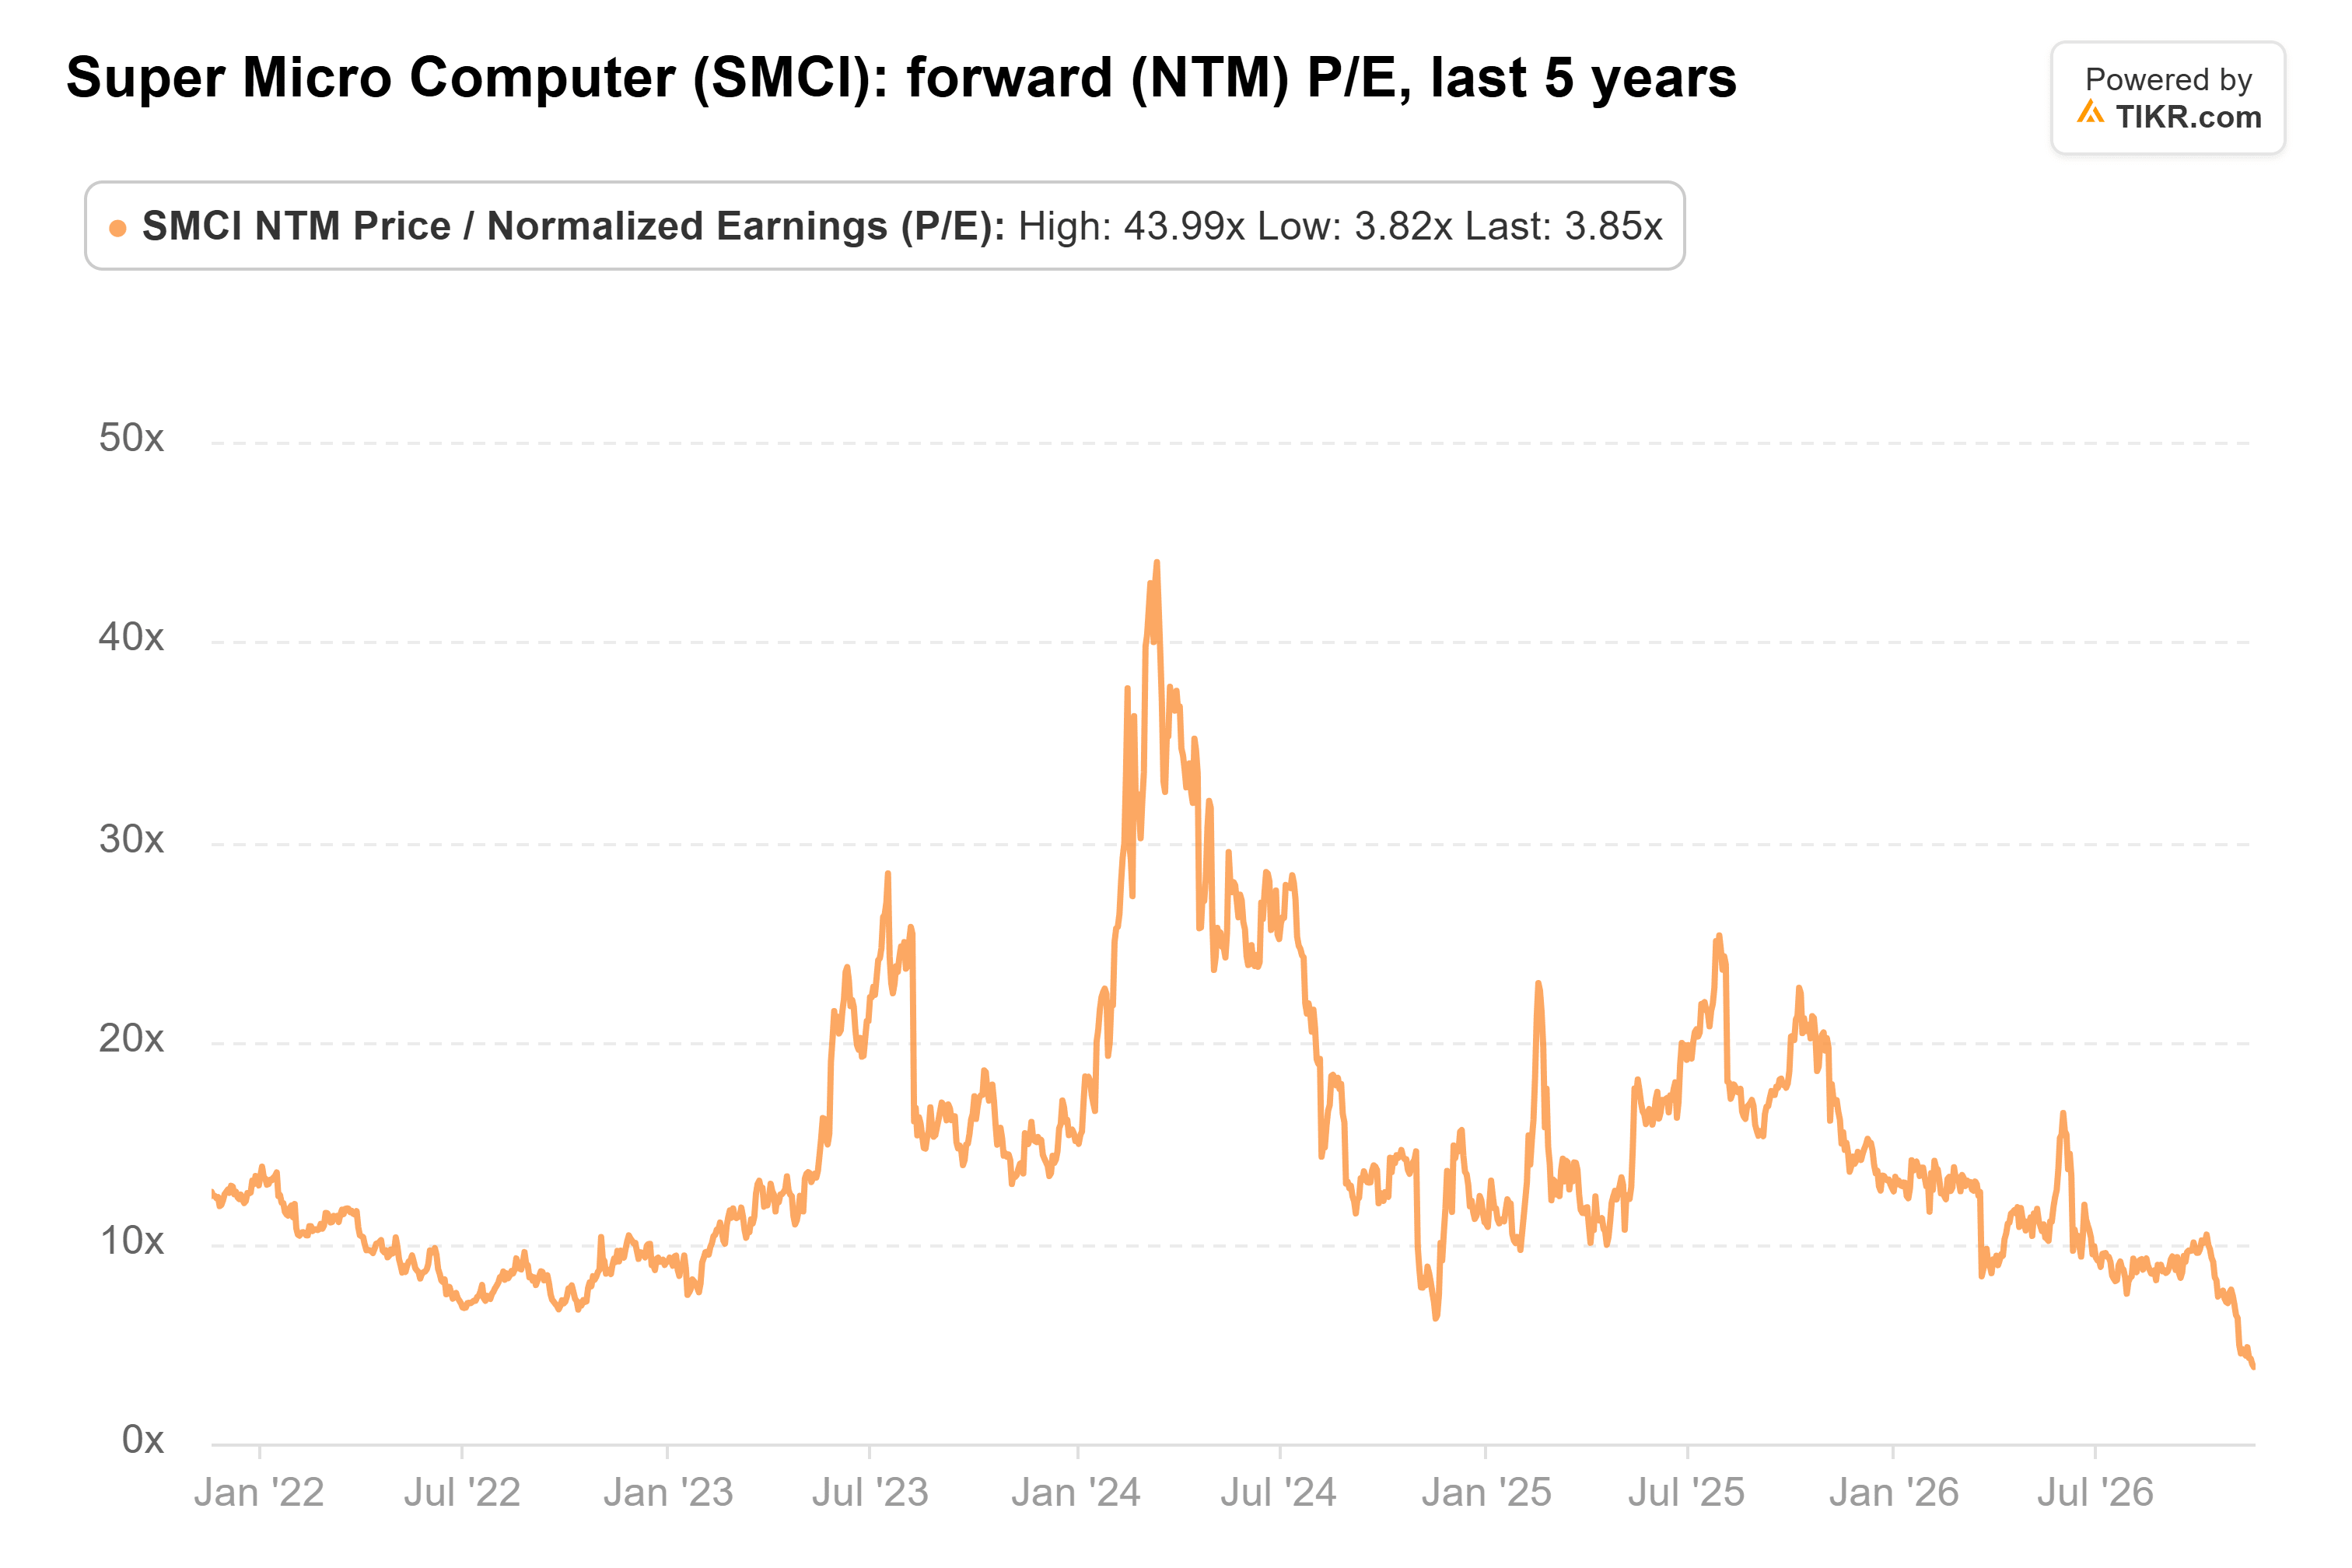
Raymond James raised its target to $65 from $48 on Nov. 4, and the consensus target is about $44. On the $6.95 of EPS analysts expect for fiscal 2028, those work out to 9.4x and 6.3x, so neither needs a return to the average. Mizuho cut its target the same day, though, and Susquehanna rates the stock Negative with an $18 target.
At this price, the numbers favor loading up for investors who can stomach more Justice Department headlines. A charge naming the company, or a pullback from that 44% customer, could keep it cheap. Fiscal second-quarter results, expected in early February, are the next test: revenue of at least $19.5 billion, the bottom of guidance, with gross margin holding near September’s 12.7% would back the case.
So what is Super Micro stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Super Micro could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!