Key Takeaways
- BMO Capital raised its Palo Alto Networks price target to $425 from $415 after a fiscal first quarter in which revenue grew 39% and management raised its full-year guidance.
- At the $4.91 of fiscal 2028 earnings per share that analysts expect, $425 works out to about 87x earnings. The stock traded at 84x at the last close, and its five-year average is 57x.
- The main risk is the pending Applied Compute deal, which management expects to cut fiscal 2028 operating margin by up to 200 basis points. Reports from CrowdStrike and Zscaler in early December will show whether Palo Alto is taking share.
- $425 isn’t too low, because it already asks investors to keep paying a multiple near the top of the stock’s five-year range.
Palo Alto Networks (PANW) is 19% below its October high but still up 75% over the past year. On Nov. 20, BMO Capital lifted its target to $425 from $415 and kept its Outperform rating. The new target is 22% above today’s price.
The quarter behind the call matters for CrowdStrike (CRWD) and Zscaler (ZS) too.
Growth sped up across the board
Revenue grew 39% to $3.44 billion in the fiscal first quarter ended Oct. 31. Management raised its fiscal 2027 revenue growth guidance to 26% to 27%, from 23% to 24%. Adjusted EPS rose only 13%, though, because diluted shares climbed 18% after the CyberArk deal.
“As AI accelerates cyber-attacks, enterprises are moving with urgency to replace disjointed tools with unified platforms,” CEO Nikesh Arora said on the call. Palo Alto’s SASE ARR grew 30%. CrowdStrike’s Dec. 1 report and Zscaler’s on Dec. 2 will show whether Palo Alto is winning deals at their expense.
TIKR tracks 55 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
BMO sees a new market, with new risk
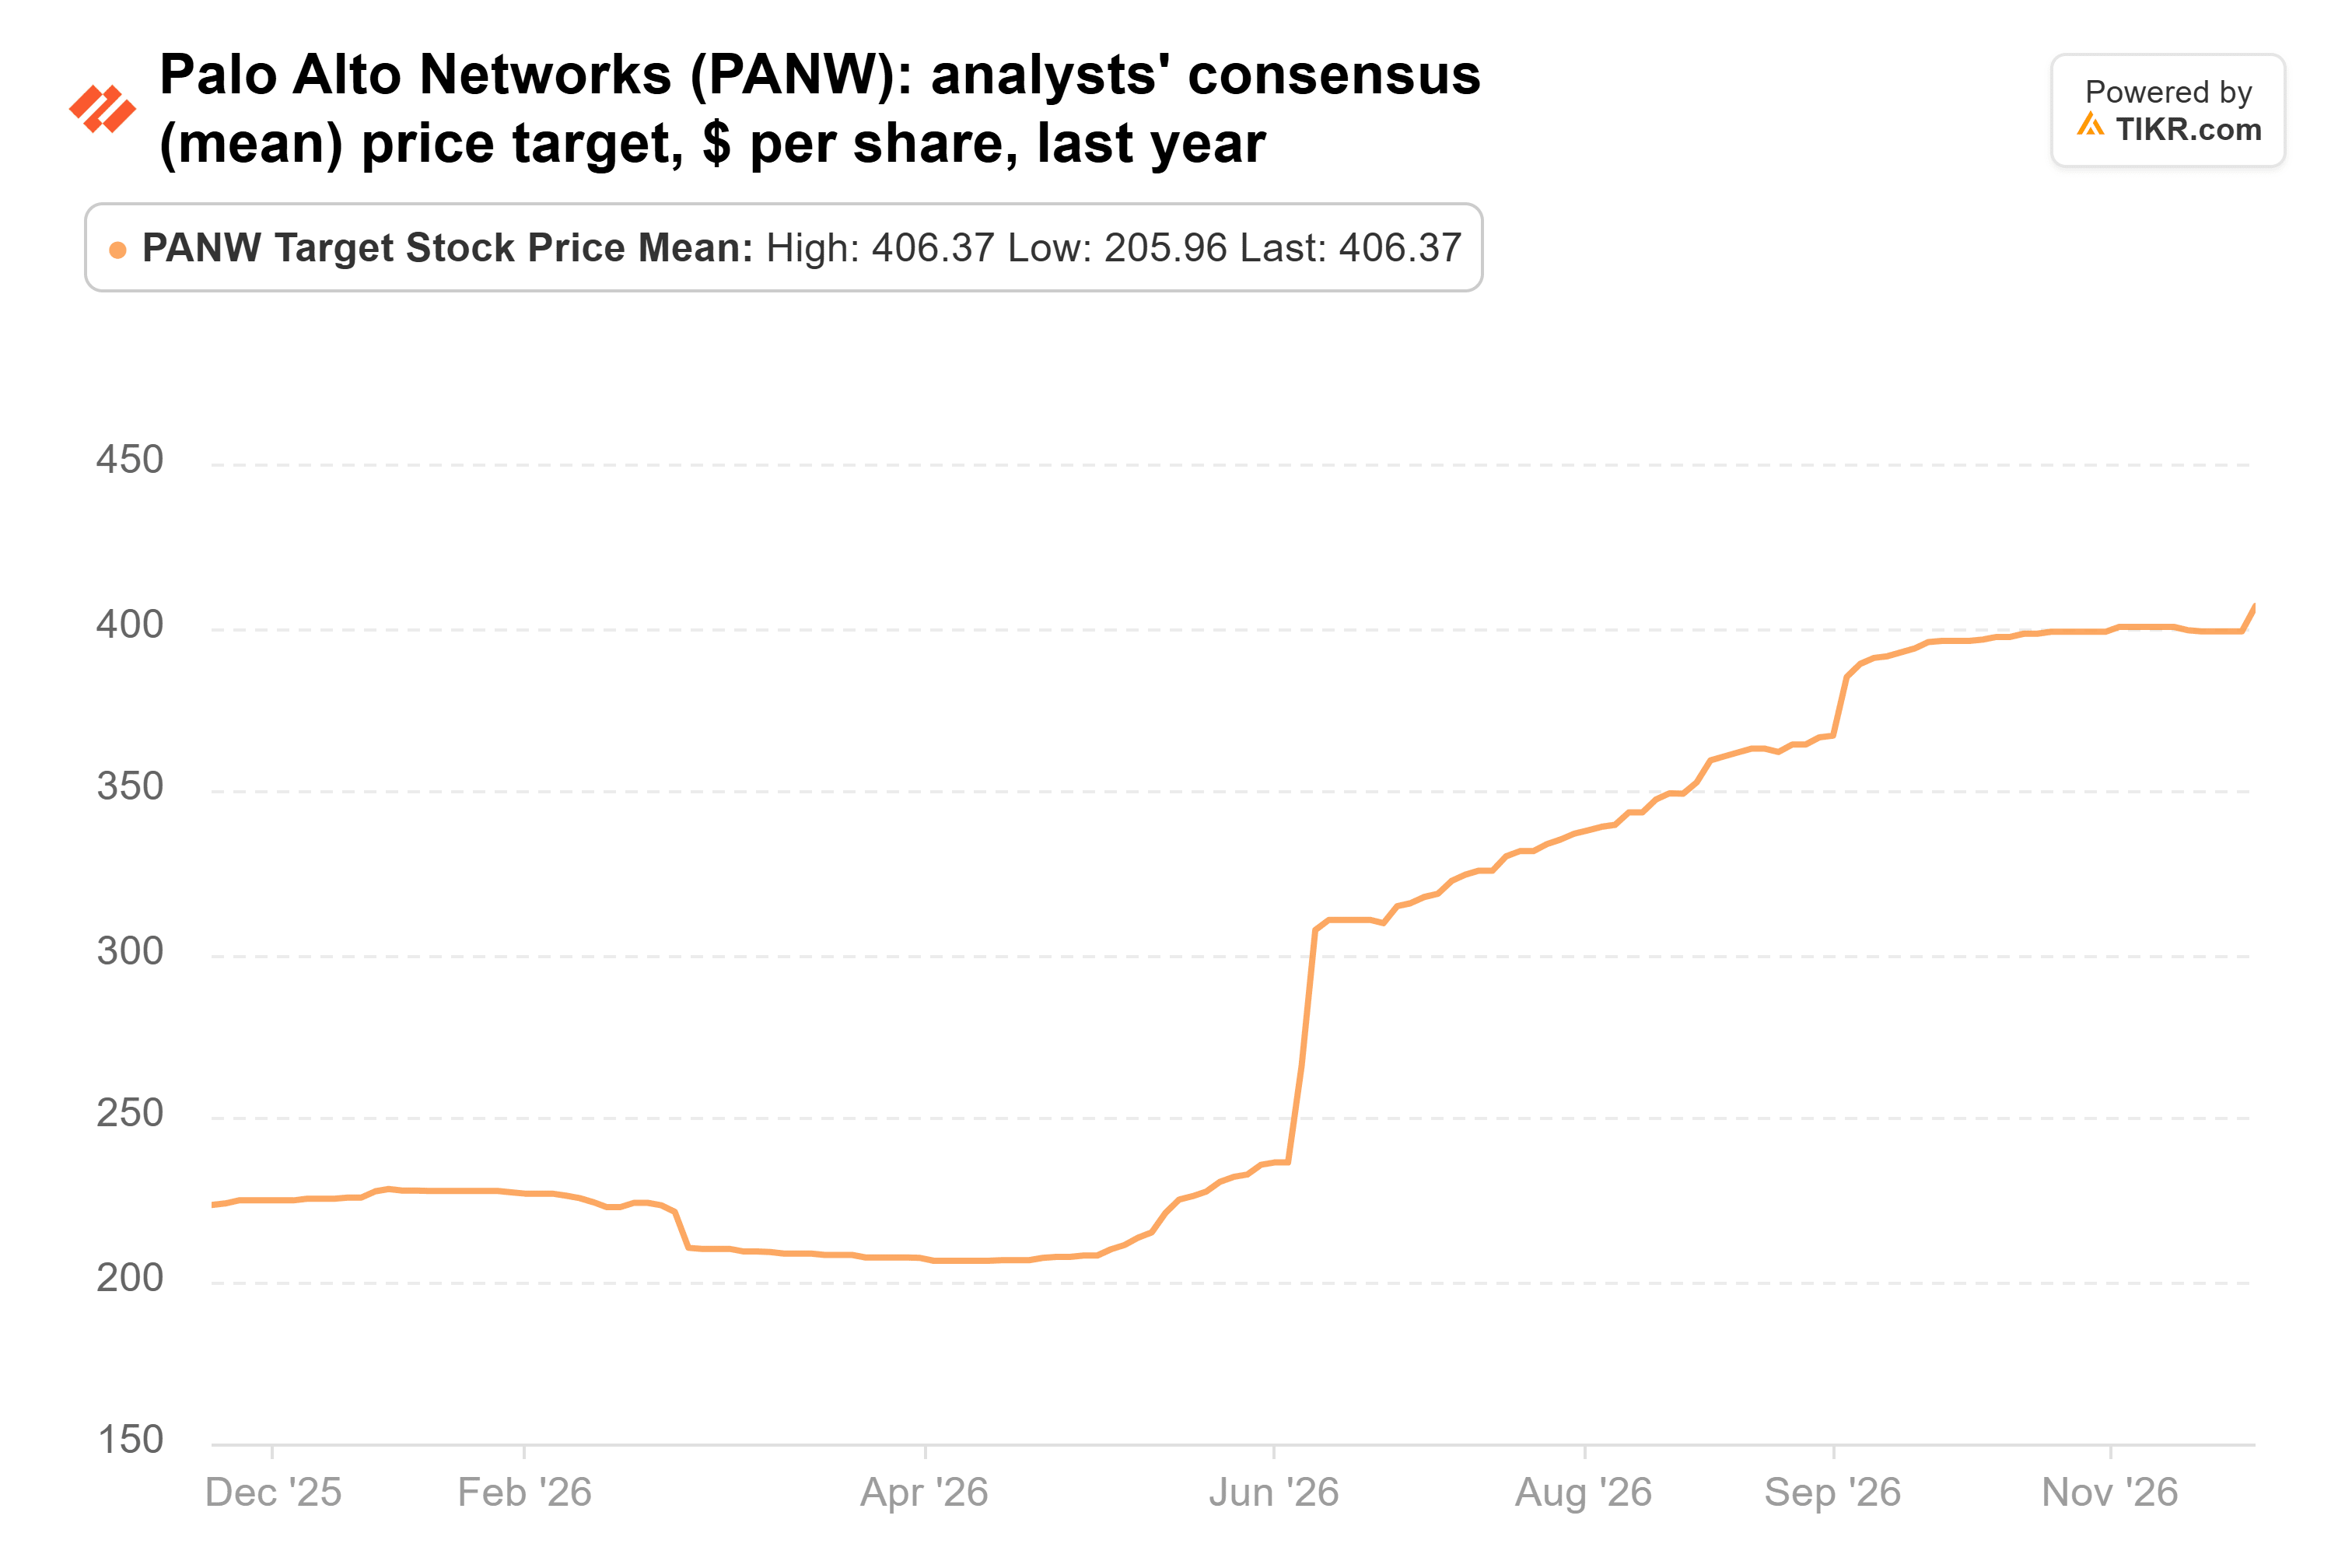
BMO pointed to revenue, NGS ARR and remaining performance obligations, which all grew faster and beat consensus. It thinks the $4.5 billion all-stock deal for AI startup Applied Compute opens up more of the market but adds execution risk. The raise is the latest step in a long climb, as the analysts’ average target has nearly doubled in a year, from $223 to $406.
Does $425 add up?
Analysts expect normalized EPS to rise from $3.84 in fiscal 2026 to $4.91 in fiscal 2028, the year to July 2028.
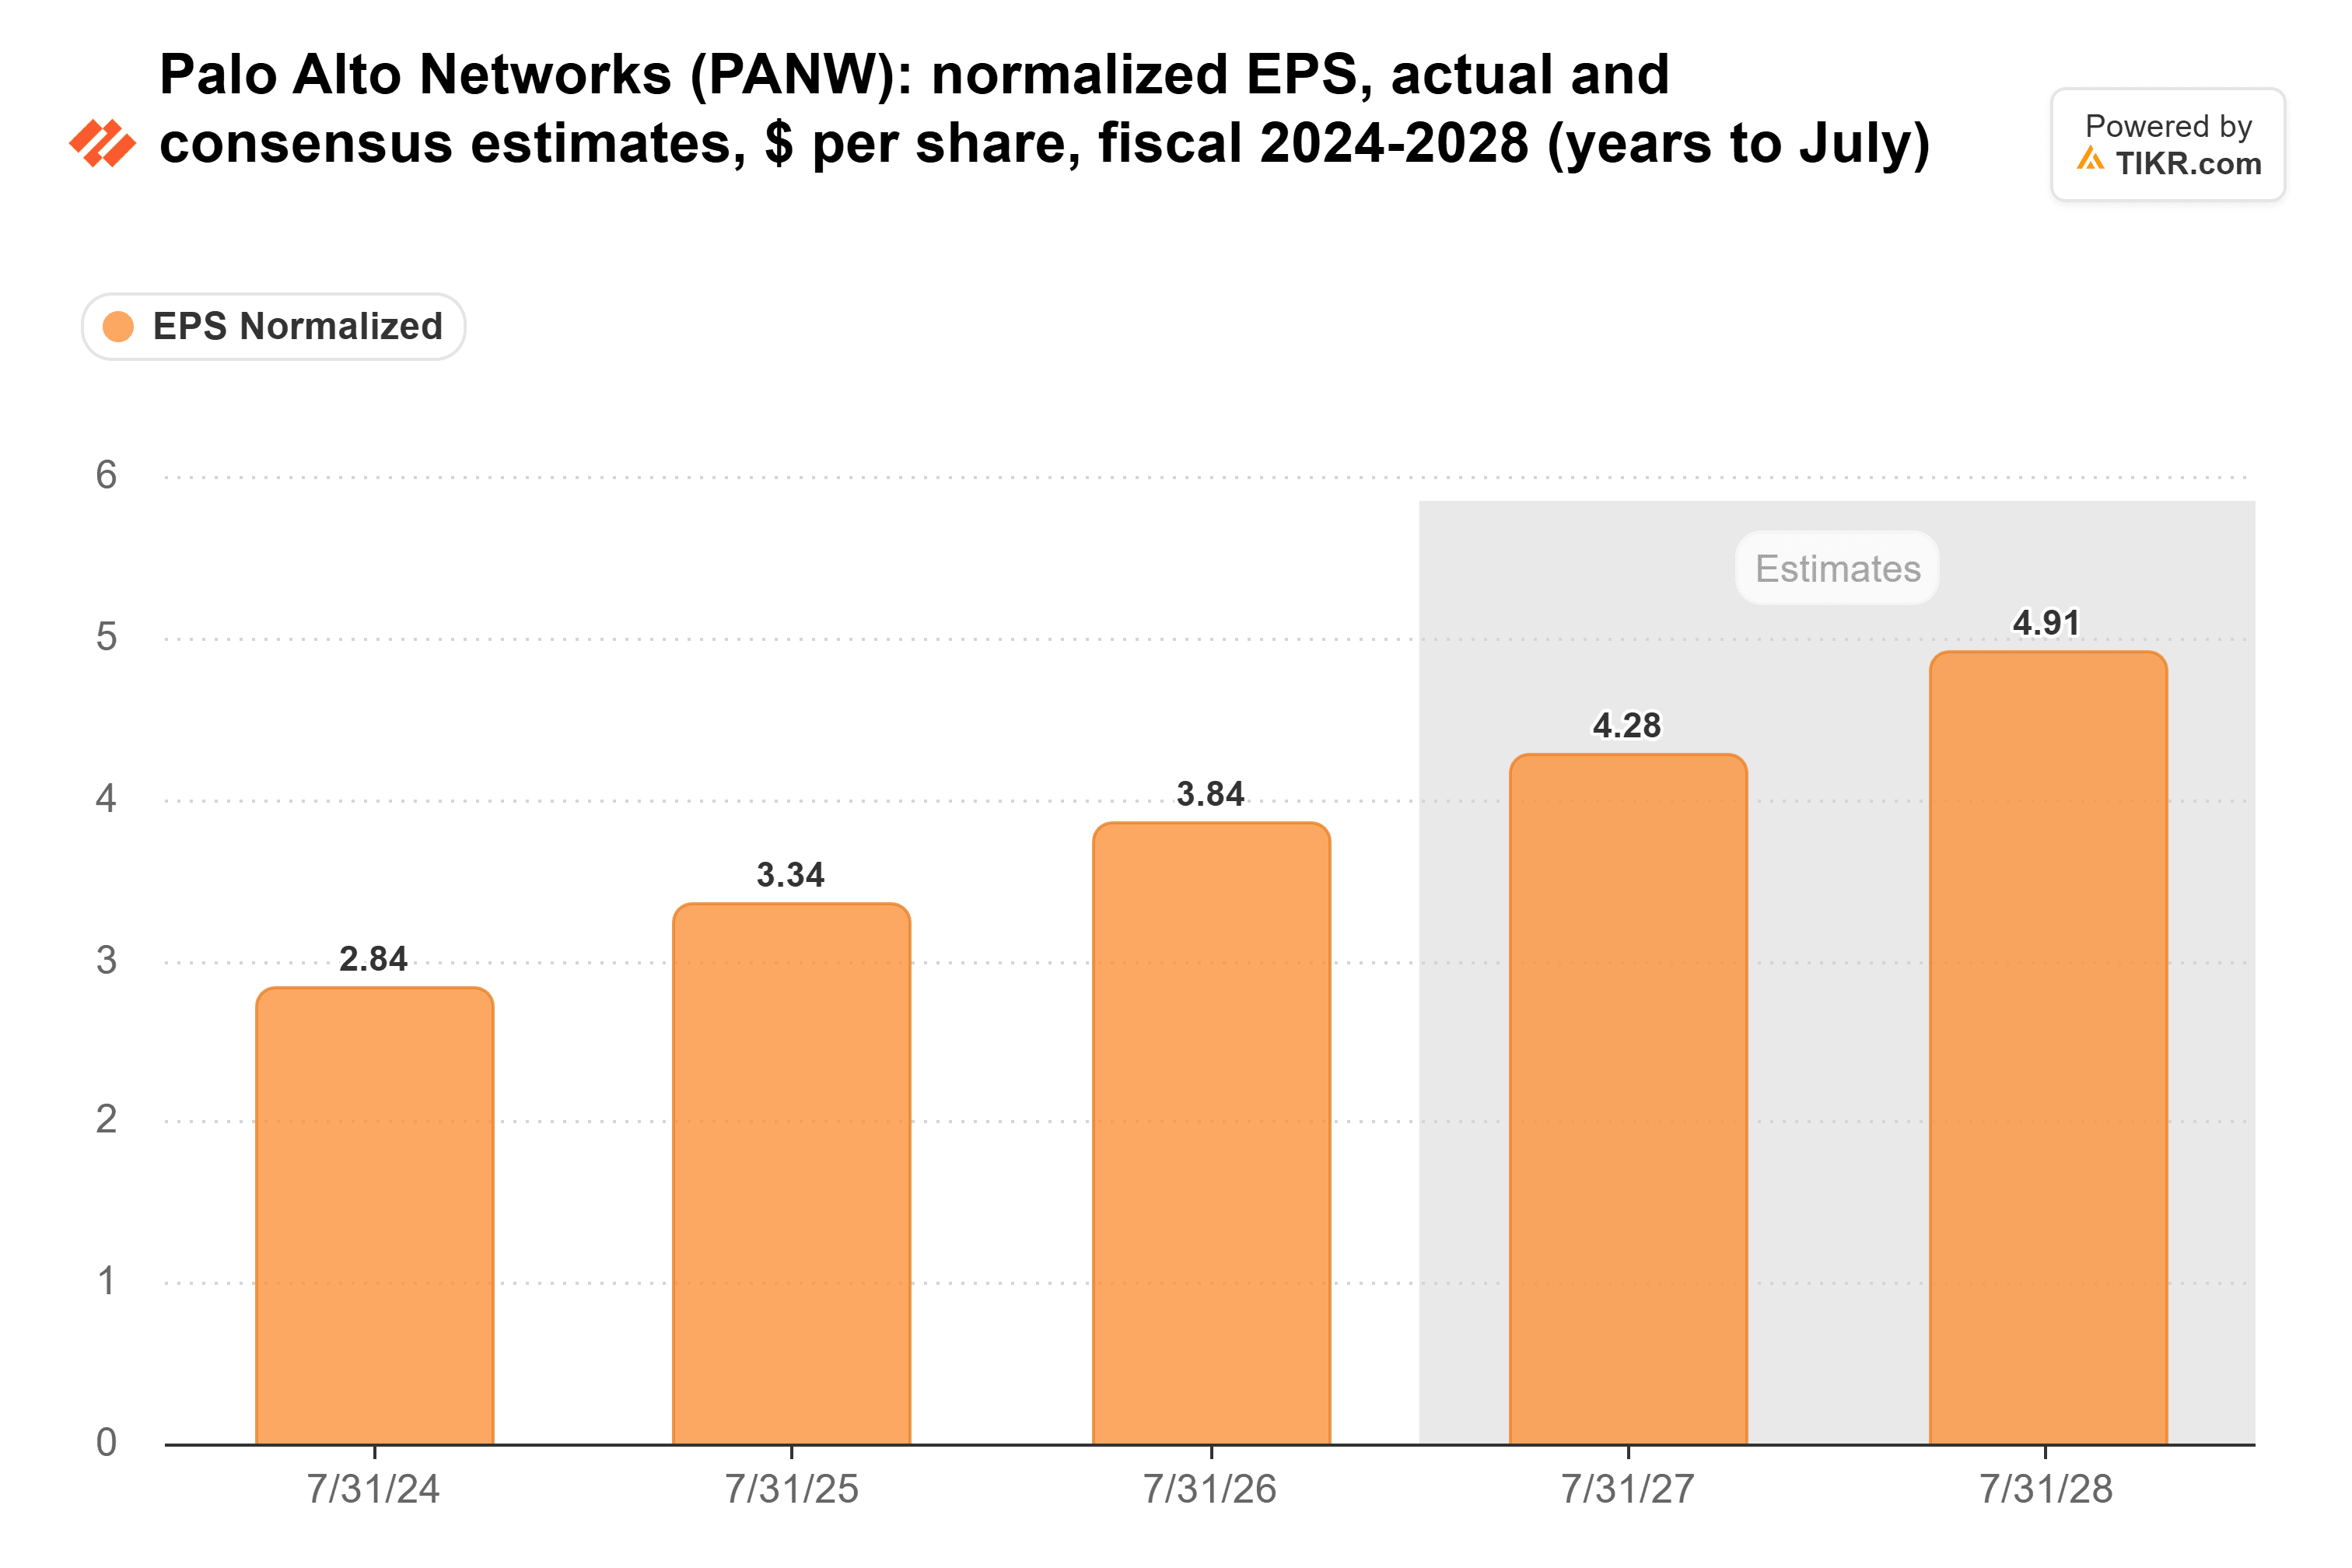
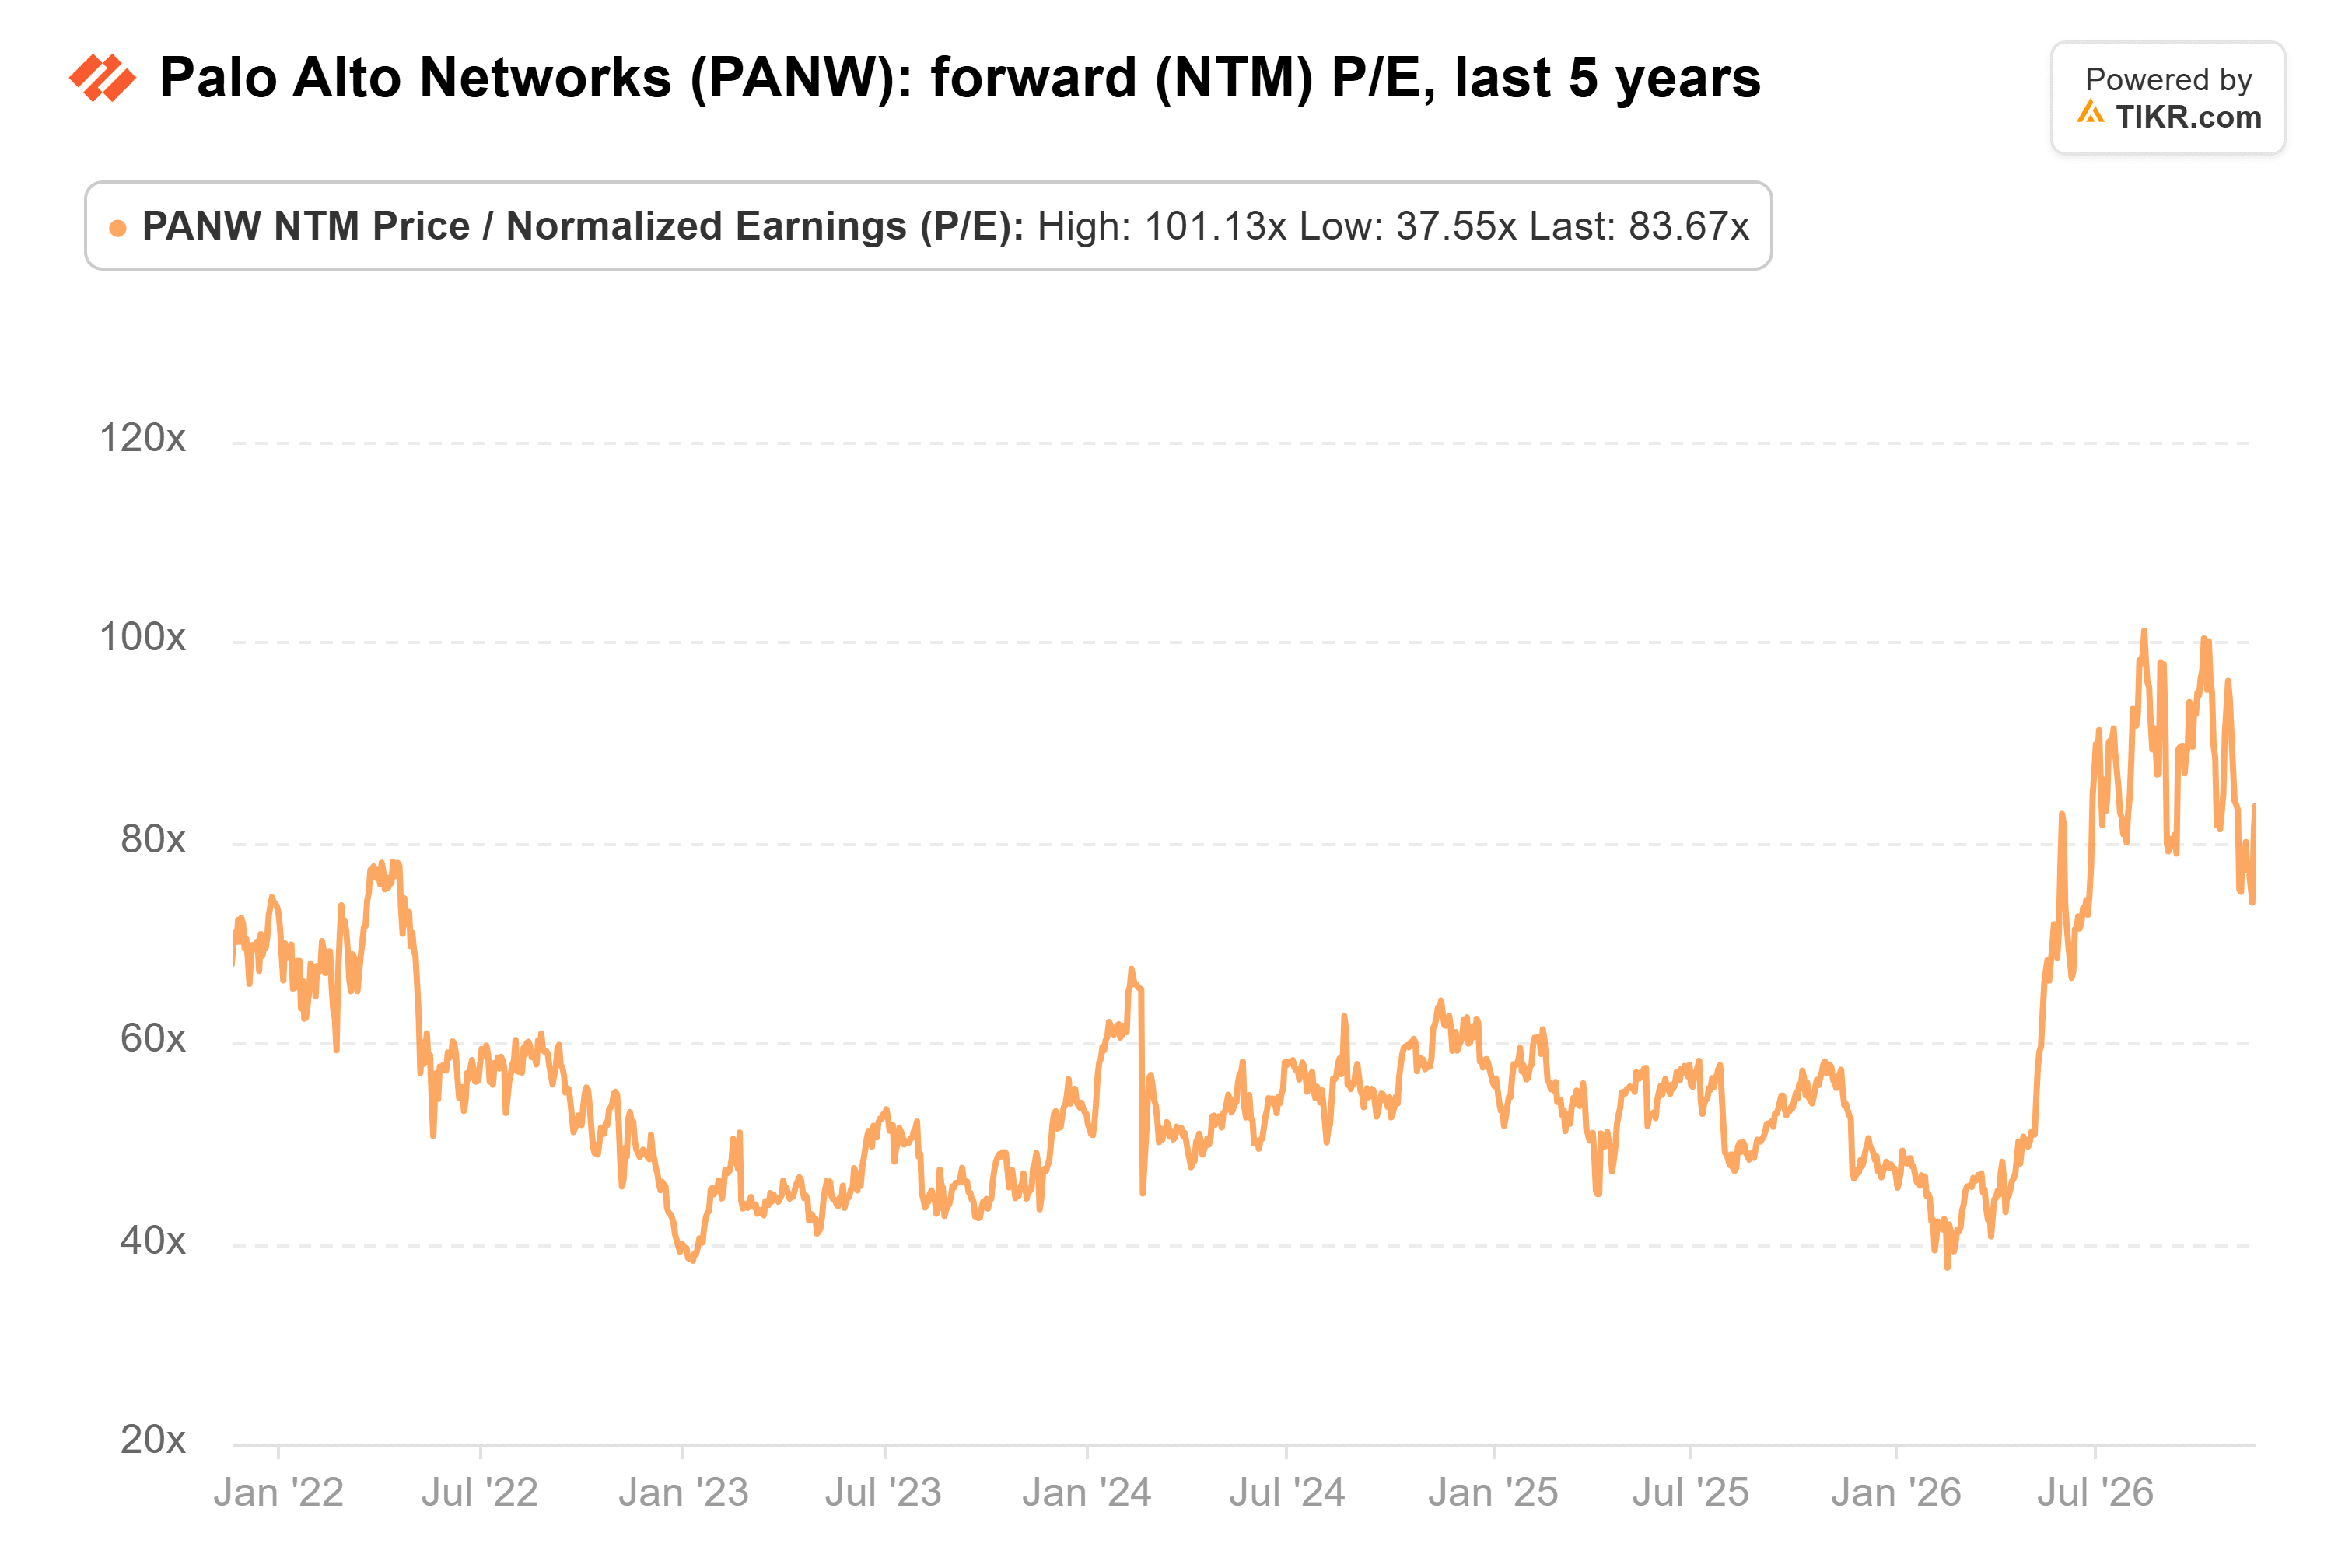
That’s the year investors will be pricing a year from now, and on $4.91 of EPS, $425 is about 87x earnings. Most of the upside comes from earnings growing about 14% from the $4.32 analysts expect over the next twelve months. The multiple only has to rise about 4%. But the stock already traded at about 84x forward earnings at the last close, against a five-year average of 57x.
Already priced for a great run
Palo Alto expects the pending Applied Compute deal to cut operating margin by up to 200 basis points in fiscal 2028, and it’s paying in new shares.
So no, $425 isn’t too low. It asks Palo Alto to hold a multiple near the top of its five-year range on earnings the deal will squeeze. I’d want a cheaper multiple before following BMO here.
The next test is the fiscal second-quarter report, likely in mid-February. Management guides adjusted EPS of $1.01 to $1.03 on 837 million to 842 million shares. A beat with the share count inside that range would make $425 look a lot more reasonable.
So what is Palo Alto Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Palo Alto Networks for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!