Key Takeaways
- SoundHound AI shares fell 8% after record third-quarter revenue of $62.4 million, as the company moves from upfront license deals to hosted contracts.
- The shift costs reported revenue now but ties revenue to what customers pay, a trade worth making.
- The 2027 revenue range centers below what analysts expected, and the company is still burning cash.
- The stock now rests on $120 million of cost cuts, and rival NiCE could pick up customers SoundHound drops.
SoundHound AI (SOUN) posted record revenue, and the stock is down 8% anyway.
Third-quarter revenue rose 48.5%. But SoundHound is also moving customers off upfront license deals and dropping money-losing contracts, which CFO John Collins said means “improving our quality of earnings.” That cleanup could matter for NiCE (NICE), a rival for the same customer-service budgets.
Less revenue now, steadier revenue later
An upfront license books much of a multi-year contract’s revenue at signing, though the customer pays over time. SoundHound had $47.9 million of revenue booked but not due to be billed within a year at Sept. 30, up from $29.9 million at the end of 2025.
Fixing it costs growth. Third-quarter revenue barely topped the second quarter’s $61.9 million, even with about four weeks of LivePerson inside. I’d put most of that stall down to the license shift.
SoundHound guided to $250 million to $260 million of 2026 revenue, above the $238 million analysts expected. But its 2027 range of $350 million to $400 million centers below their $390 million:
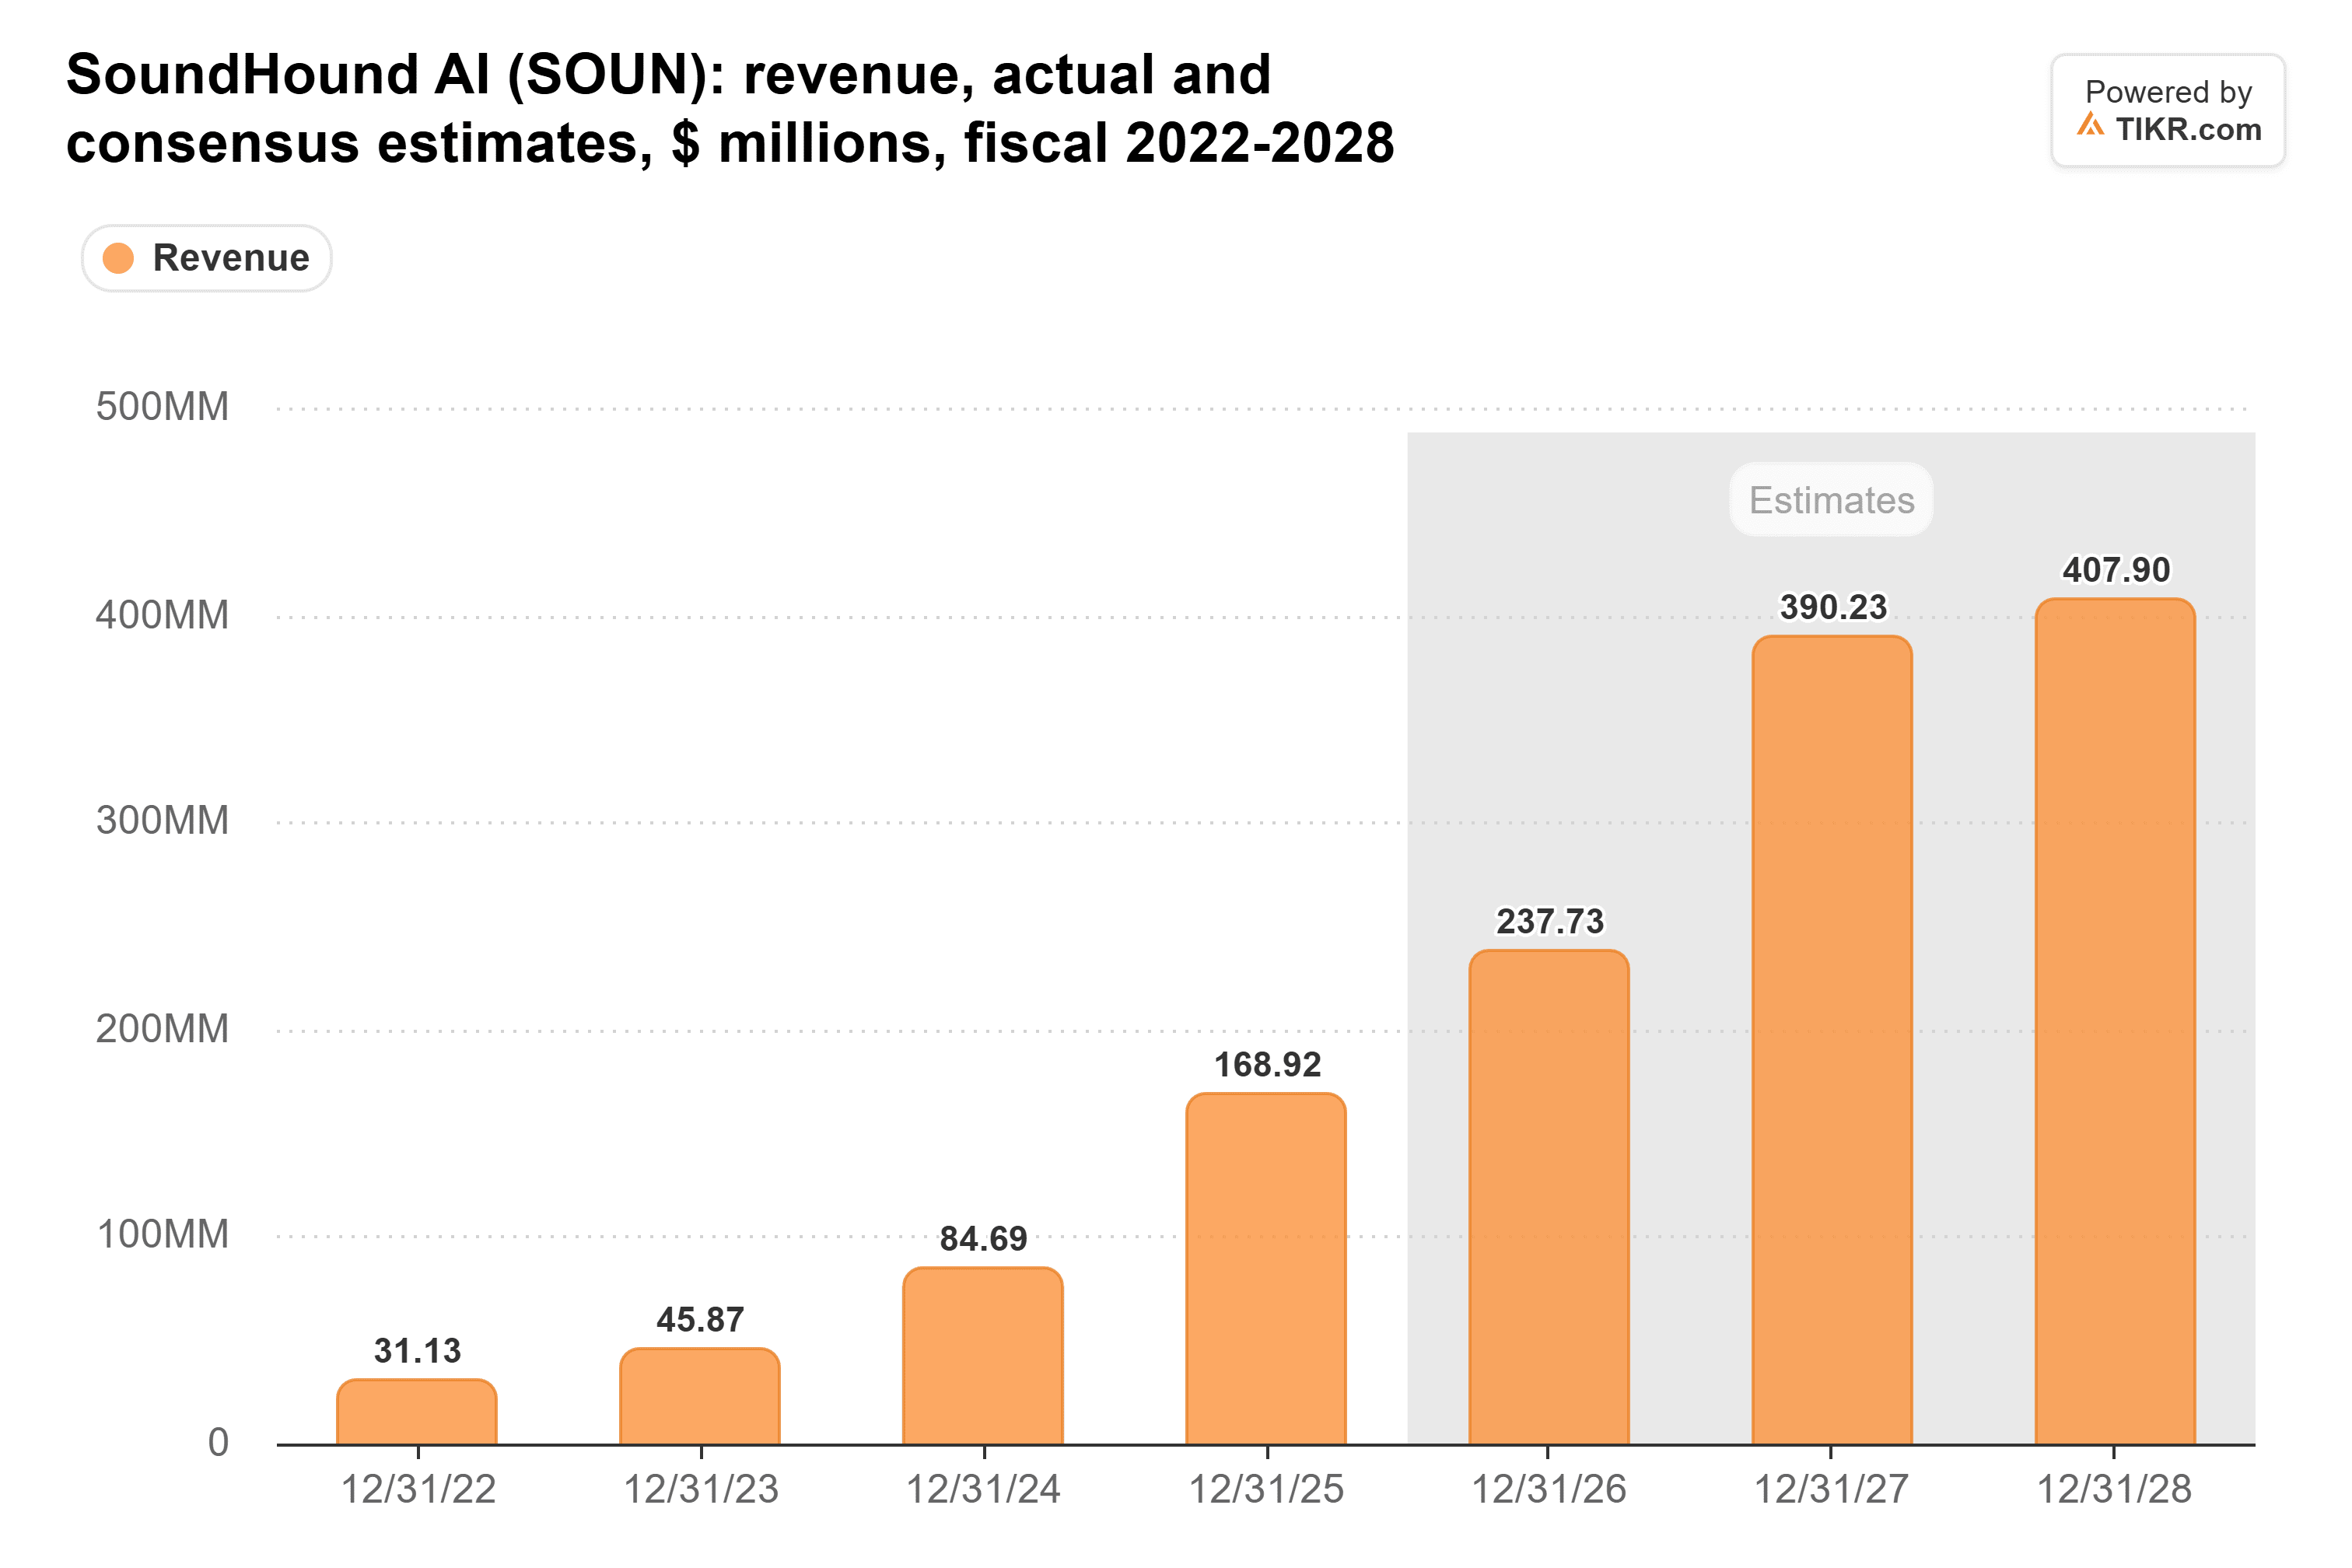
I’d expect those 2027 estimates to come down.
TIKR tracks 8 analysts on SoundHound AI. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SoundHound AI, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SoundHound AI’s Analyst Ratings
The cost cuts have to land
This report had to show SoundHound’s losses shrinking. Instead, its adjusted EBITDA loss widened to $20.7 million, from $14.5 million a year earlier, and it’s still burning cash every quarter:
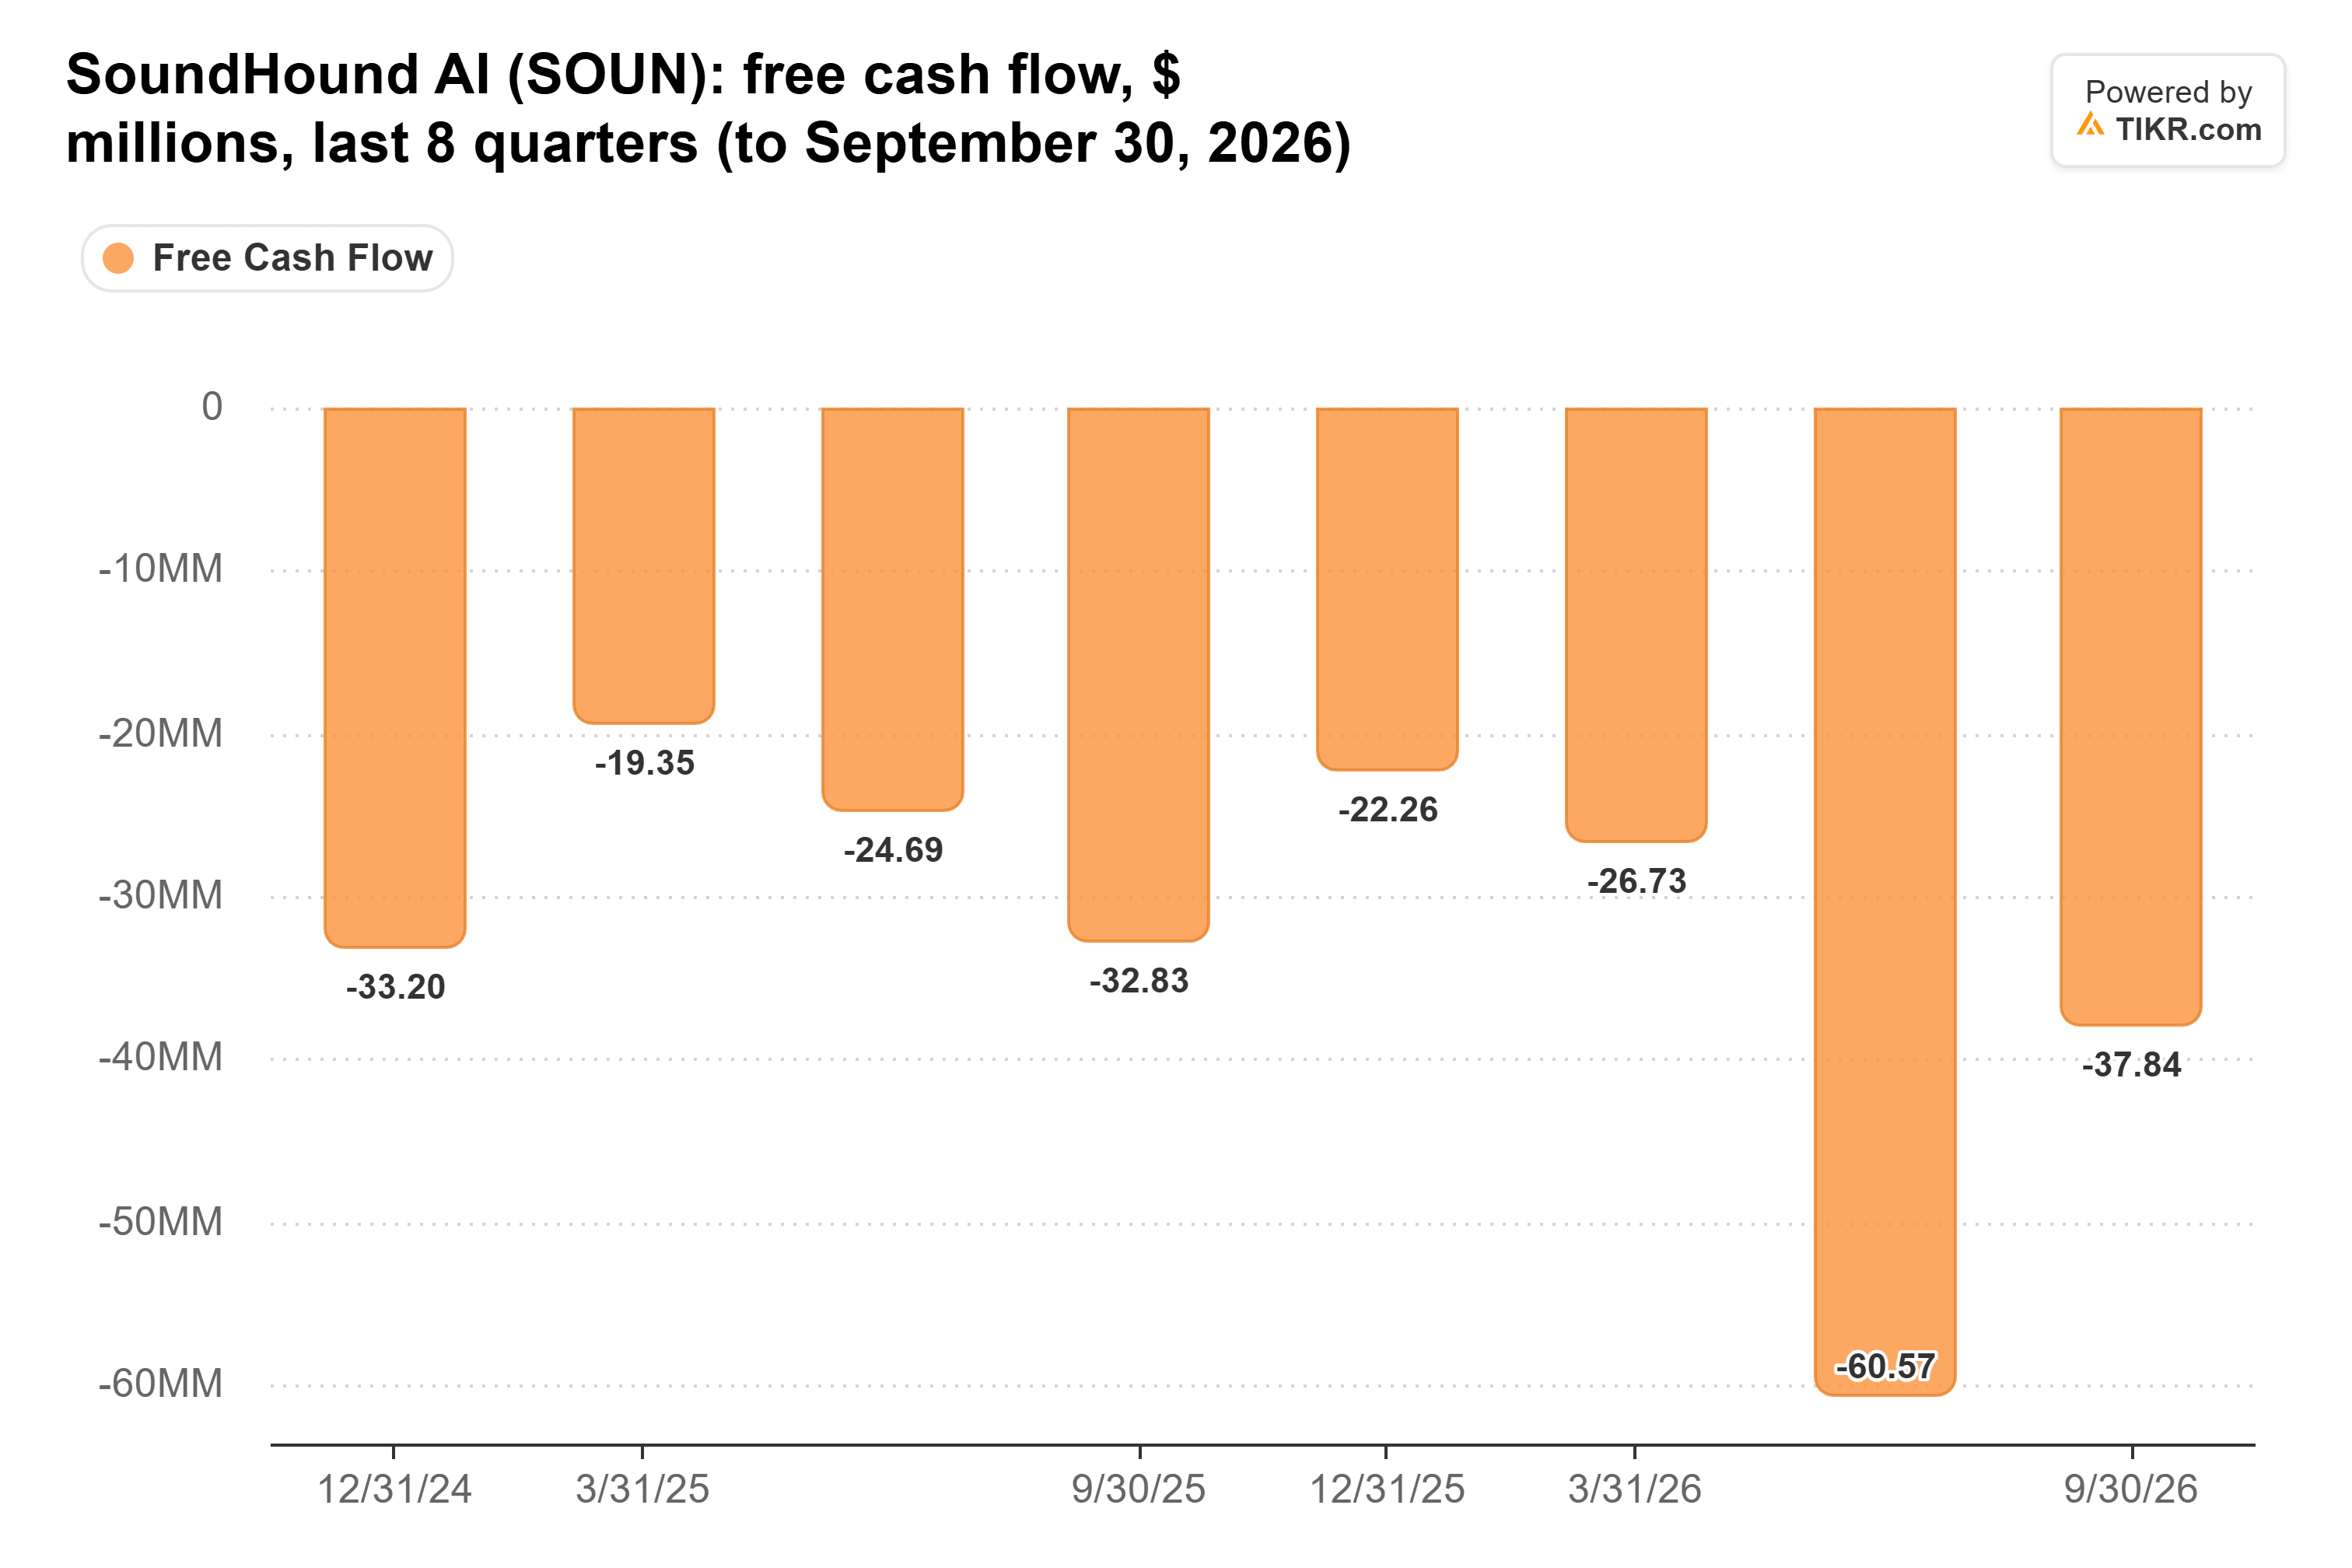
With $207.6 million in cash at Sept. 30, SoundHound is counting on $120 million of yearly cost savings, over $80 million of it in place before Jan. 1, to turn adjusted EBITDA positive for good in the second half of 2027.
The customers it walks away from will need somewhere to go, and NiCE is an obvious call. NiCE’s cloud revenue rose 10.6% in its third quarter, and its AI ARR climbed 46% to $392 million. Will its next call name any SoundHound castoffs?
Priced for the slowdown
SoundHound trades at 5.8x forward sales on TIKR’s latest reading. That’s its lowest in three years and far below its 20.3x average:

At today’s price, it’s even lower.
The way I see it, the market is punishing SoundHound for making its revenue more honest, and at this multiple, a lot of bad news is priced in. But if the first $80 million of cuts don’t show up in fourth-quarter results, I wouldn’t be surprised to see more share sales.
So what is SoundHound AI stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SoundHound AI could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!