Key Takeaways
- Oppenheimer kept its $475 price target on Snowflake on Nov. 18. That’s 77% above the Nov. 19 close, with the stock 27% below its October closing high.
- Snowflake hasn’t reported since September, and other companies in the business are sending mixed signals: Datadog guided to a flat fourth quarter, while MongoDB’s growth has picked up.
- Analysts expect $4.34 of normalized EPS for the year ending January 2029. On that figure, $475 is about 109x, richer than the roughly 88x the stock trades at on next year’s estimates, so the target needs both earnings growth and a higher multiple.
- Oppenheimer’s target is fair but leaves no room for error, and Snowflake’s Dec. 2 report is the next test.
Snowflake (SNOW) is 27% below its Oct. 9 closing high of $368.89, and it hasn’t reported a new quarter since early September. On Nov. 18, Oppenheimer’s Ittai Kidron kept his Outperform rating and $475 price target on the stock. Shares fell another 3.9% the next day to $268.59, leaving that target 77% above the price.
Investors are watching other software companies that bill on usage just as closely. Datadog (DDOG) guided on Nov. 4 to a flat fourth quarter. MongoDB (MDB) competes for the same AI data budgets and reports on Dec. 1, the day before Snowflake’s own Dec. 2 release.
A great quarter, then nervous peers
In its fiscal second quarter, which ended July 31, Snowflake grew product revenue 37% to $1.49 billion, its third straight quarter of faster growth. CEO Sridhar Ramaswamy said on the call that AI products “contributed approximately half of the acceleration that we are seeing.” Datadog then grew third-quarter revenue 35% to $1.20 billion, but its fourth-quarter guide implies no sequential growth after its largest customer cut usage. That shows how quickly one customer’s pullback can stall consumption revenue, and Snowflake bills the same way.
MongoDB’s Dec. 1 report is the next read. It grew revenue 30% to $771.8 million in its July quarter, with what CEO CJ Desai called “early momentum with AI use cases.” That report will show whether AI is lifting more than one data platform.
TIKR tracks 51 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Oppenheimer hasn’t budged
Kidron raised his target to $475 from $400 right after that report, and he’s held it through the slide. His Nov. 18 note said Snowflake is set to deliver fiscal third-quarter product revenue upside, according to MT Newswires. UBS’s Karl Keirstead went the other way the same day, cutting his target to $450 from $500 while keeping a Buy rating. The Street’s average target is at its highest point of the past year:
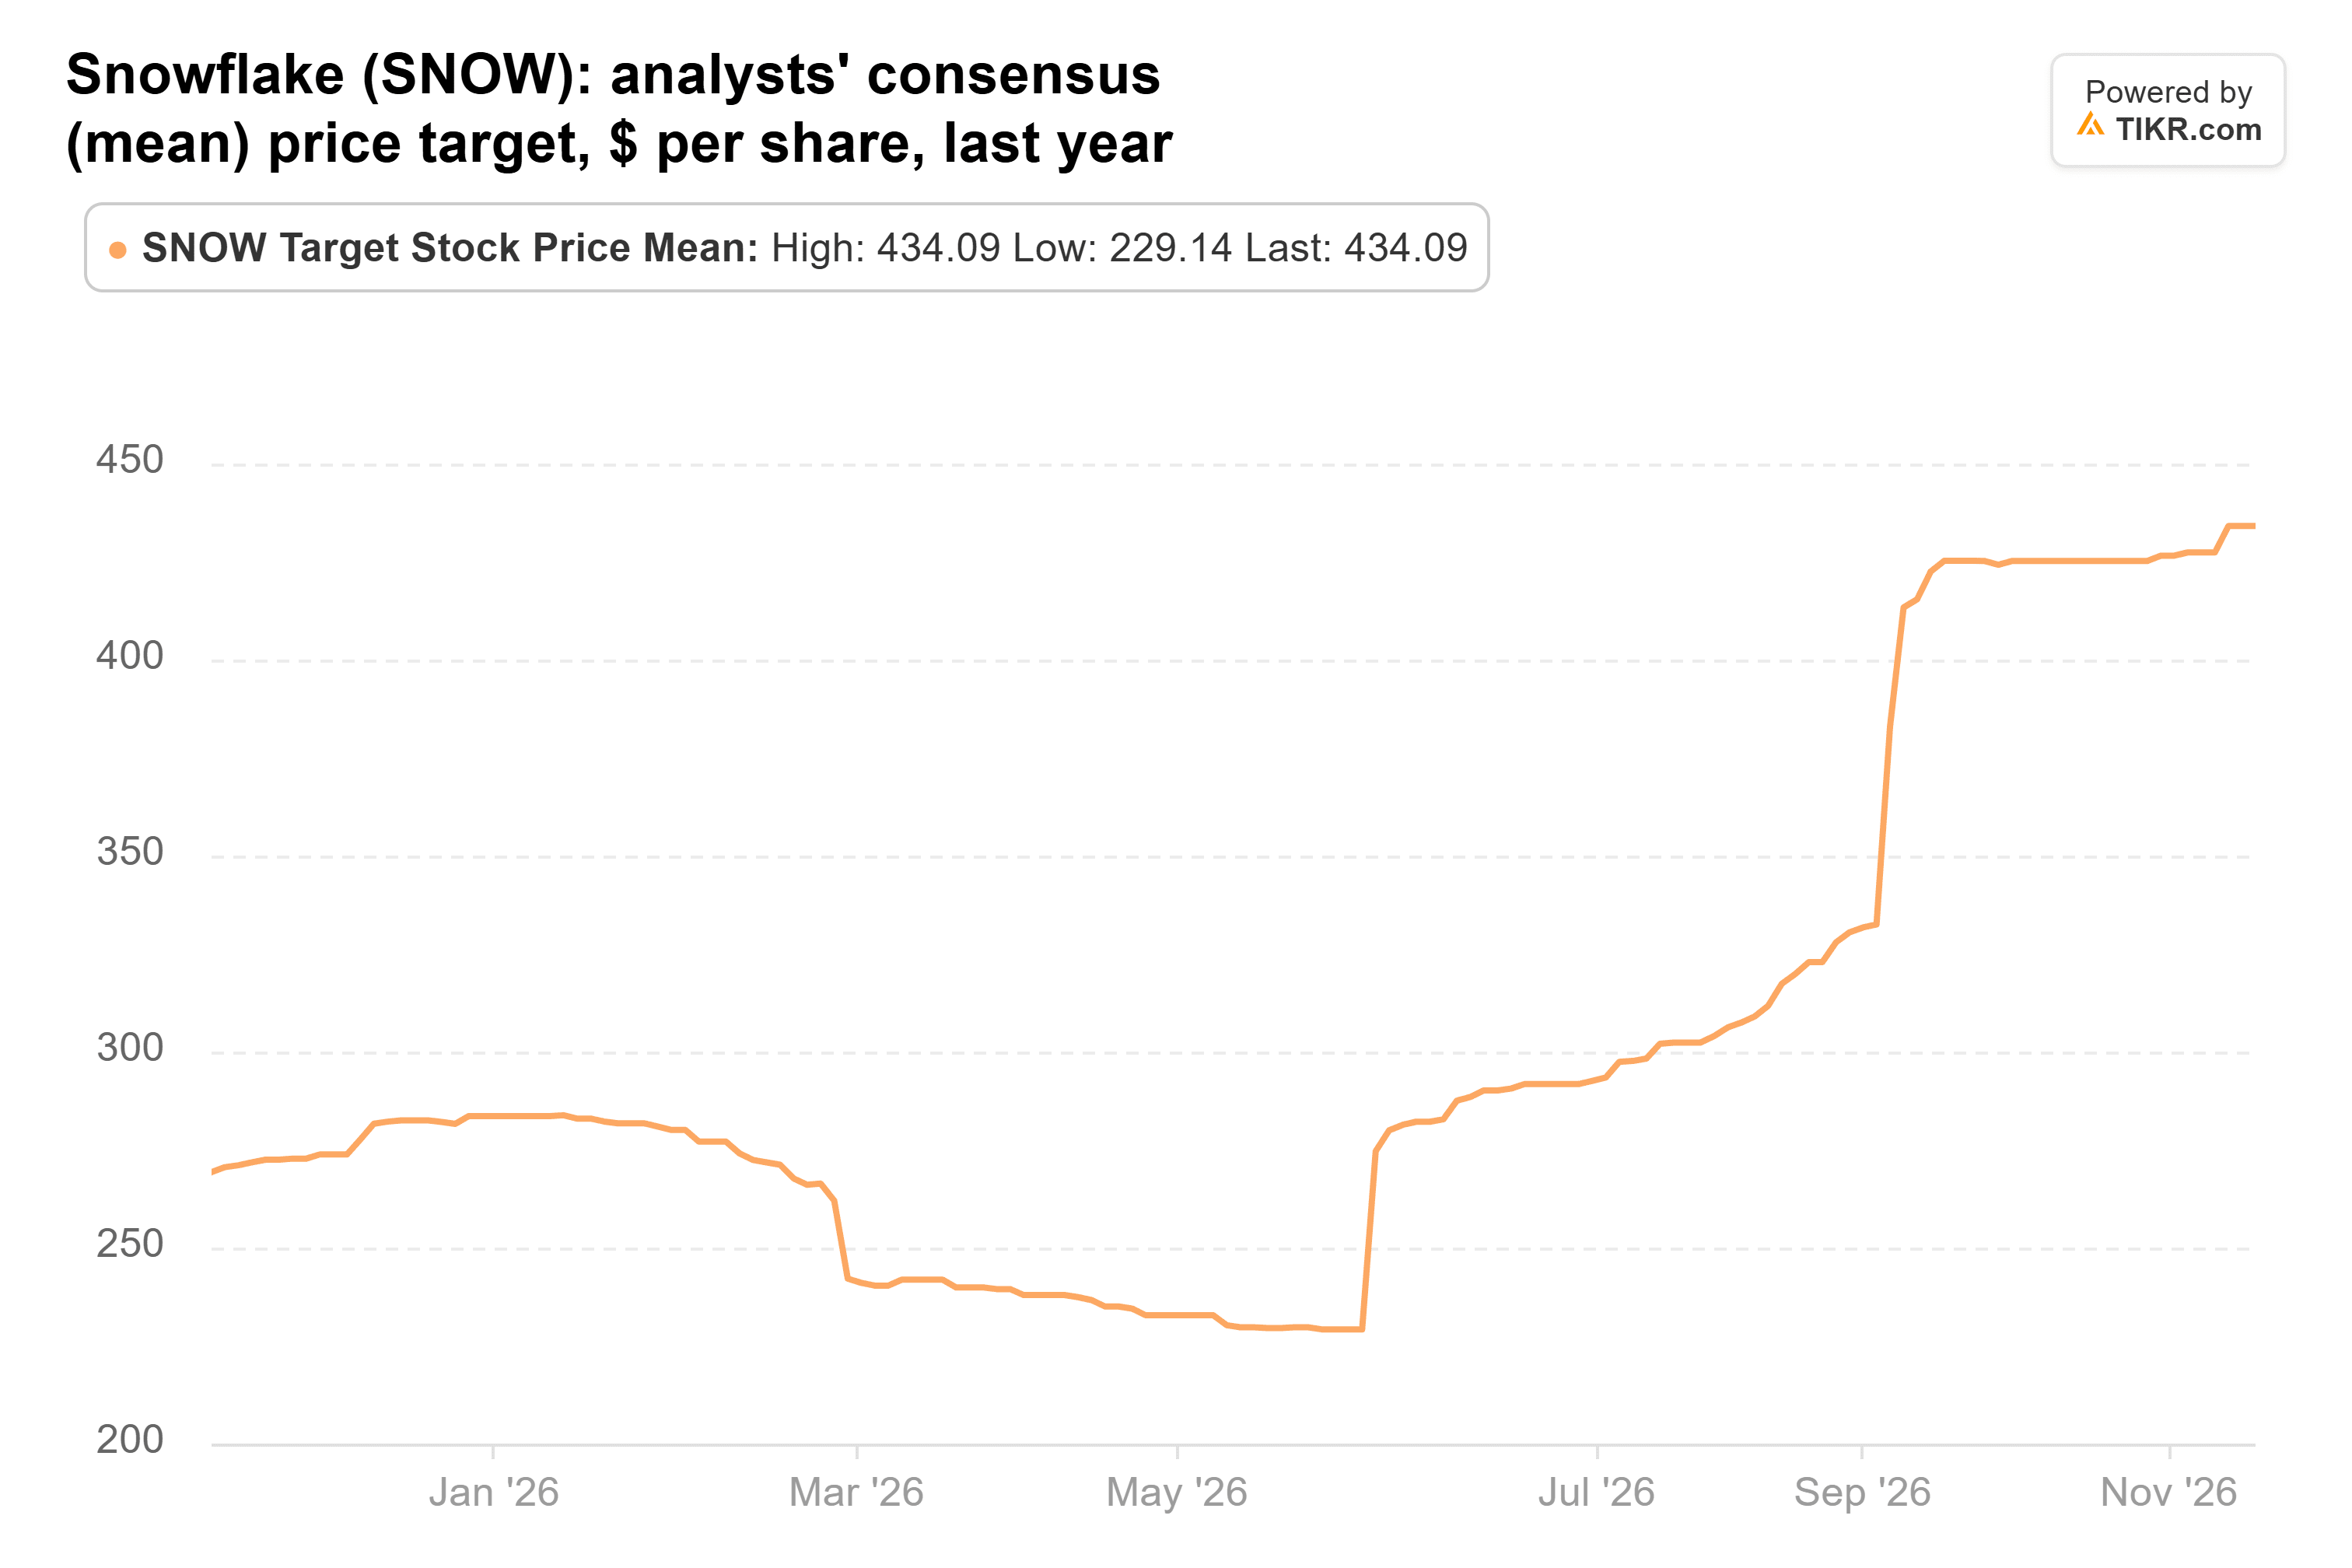
That $434 average, from the 53 analysts who cover Snowflake, is 62% above the Nov. 19 close and up from $269 a year ago.
Does $475 add up?
Analysts keep raising their numbers. They now expect $2.23 of normalized EPS for the fiscal year ending January 2027, up from $1.94 three months ago, $3.06 for the year ending January 2028, and $4.34 for the year ending January 2029:
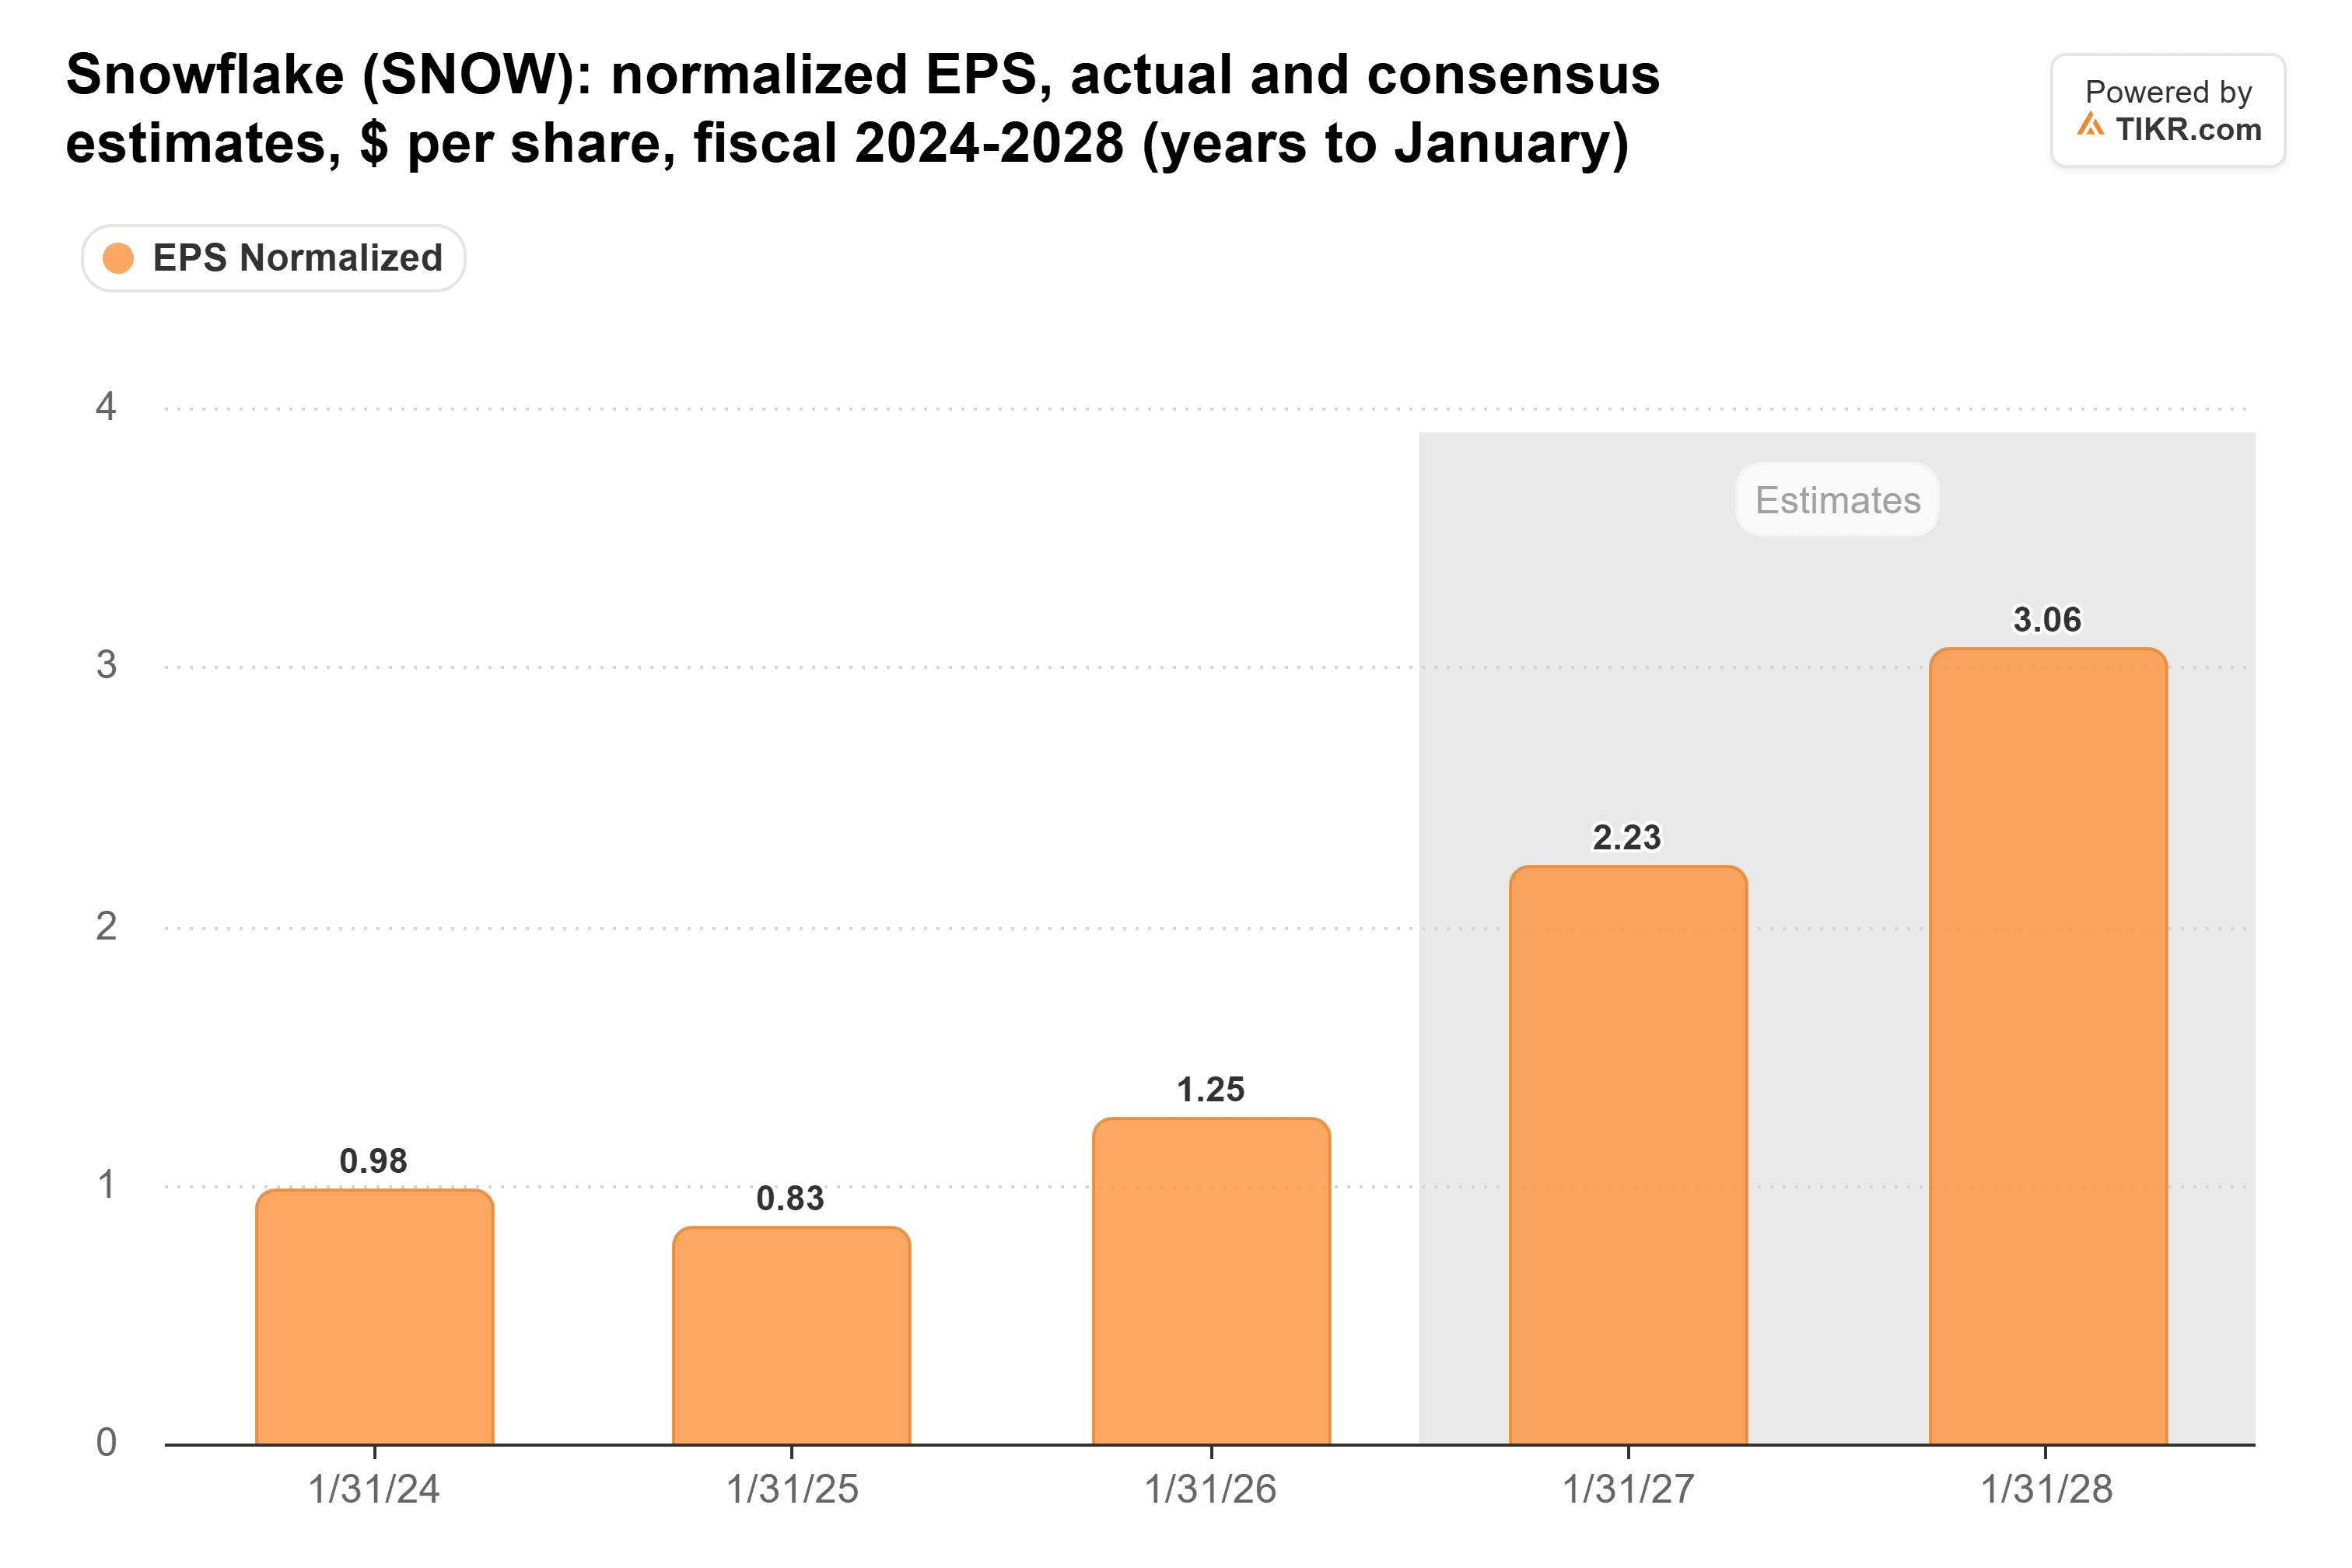
A year from now, the market will be looking ahead to that $4.34, and on that figure $475 is about 109x. Today, Snowflake trades at about 88x the $3.06 analysts expect for the year ending January 2028. So the target asks for two things: earnings growth of about 42% in a year, and a multiple about a quarter richer than today’s.
A fair target with no cushion
The risk is the margin. AI workloads “carry a lower contribution margin today,” CFO Brian Robins said in September, as Snowflake cut its full-year non-GAAP product gross margin outlook to 74% from 75%.
Oppenheimer’s $475 is a fair target only if Snowflake keeps beating, since it asks investors to pay a richer multiple for estimates that already assume fast growth. At about 88x next year’s earnings, Snowflake can’t afford a stumble. On Dec. 2, product revenue above the top of the $1,588 million to $1,593 million guide, with product gross margin at or above 74%, would back Kidron’s case.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!