Key Takeaways
- Evercore ISI kept its $325 price target on Vertiv on Nov. 18, 76% above the Nov. 19 close, with the stock down 51% from its May high.
- Vertiv fell on a second-quarter sales miss, questions about product quality and the midterm election, even though it beat in the third quarter and raised its guidance.
- Rivals nVent and Modexus Solutions (formerly Modine) are also posting fast data center growth, and analysts keep raising Vertiv’s earnings estimates.
- $325 is about 26x 2028 earnings estimates, close to Vertiv’s 5-year average multiple, so the target looks reachable if estimates hold.
Vertiv Holdings (VRT) has lost 51% since its May high, and Evercore ISI says that’s too much. On Nov. 18, analyst Amit Daryanani reiterated his Outperform rating and $325 price target, 76% above the stock’s Nov. 19 close of $184.99.
Its rivals are still booming: nVent Electric (NVT) grew organic sales 44% in its third quarter, and Modexus Solutions (MOD), formerly Modine, said its data center sales rose 95% in the quarter ended Sept. 30. On Nov. 18, Modexus also targeted 40% to 55% compound annual revenue growth from fiscal 2027 through fiscal 2029.
Three hits in four months
On July 29, Vertiv’s second-quarter sales of $3.27 billion missed the midpoint of its guidance. Questions about product quality followed, and CEO Giordano Albertazzi answered them on the Oct. 28 call: “when we look at the quality data, we are optimistic about what we see.”
The third quarter beat anyway. Sales rose 61% to $4.31 billion, and Vertiv raised its 2026 adjusted EPS guidance to $7.15 at the midpoint. Then Democrats won Congress on Nov. 3, reviving fears that Washington could slow data center construction.
Evercore is betting on share gains
Evercore cut its target to $325 from $375 on Nov. 5 and kept it there. On the Oct. 28 call, Daryanani said organic orders growth of more than 100% “would almost imply that Vertiv is actually picking up market share.”
Analysts’ average target is $334, 81% above the Nov. 19 close and below its July peak of $381:
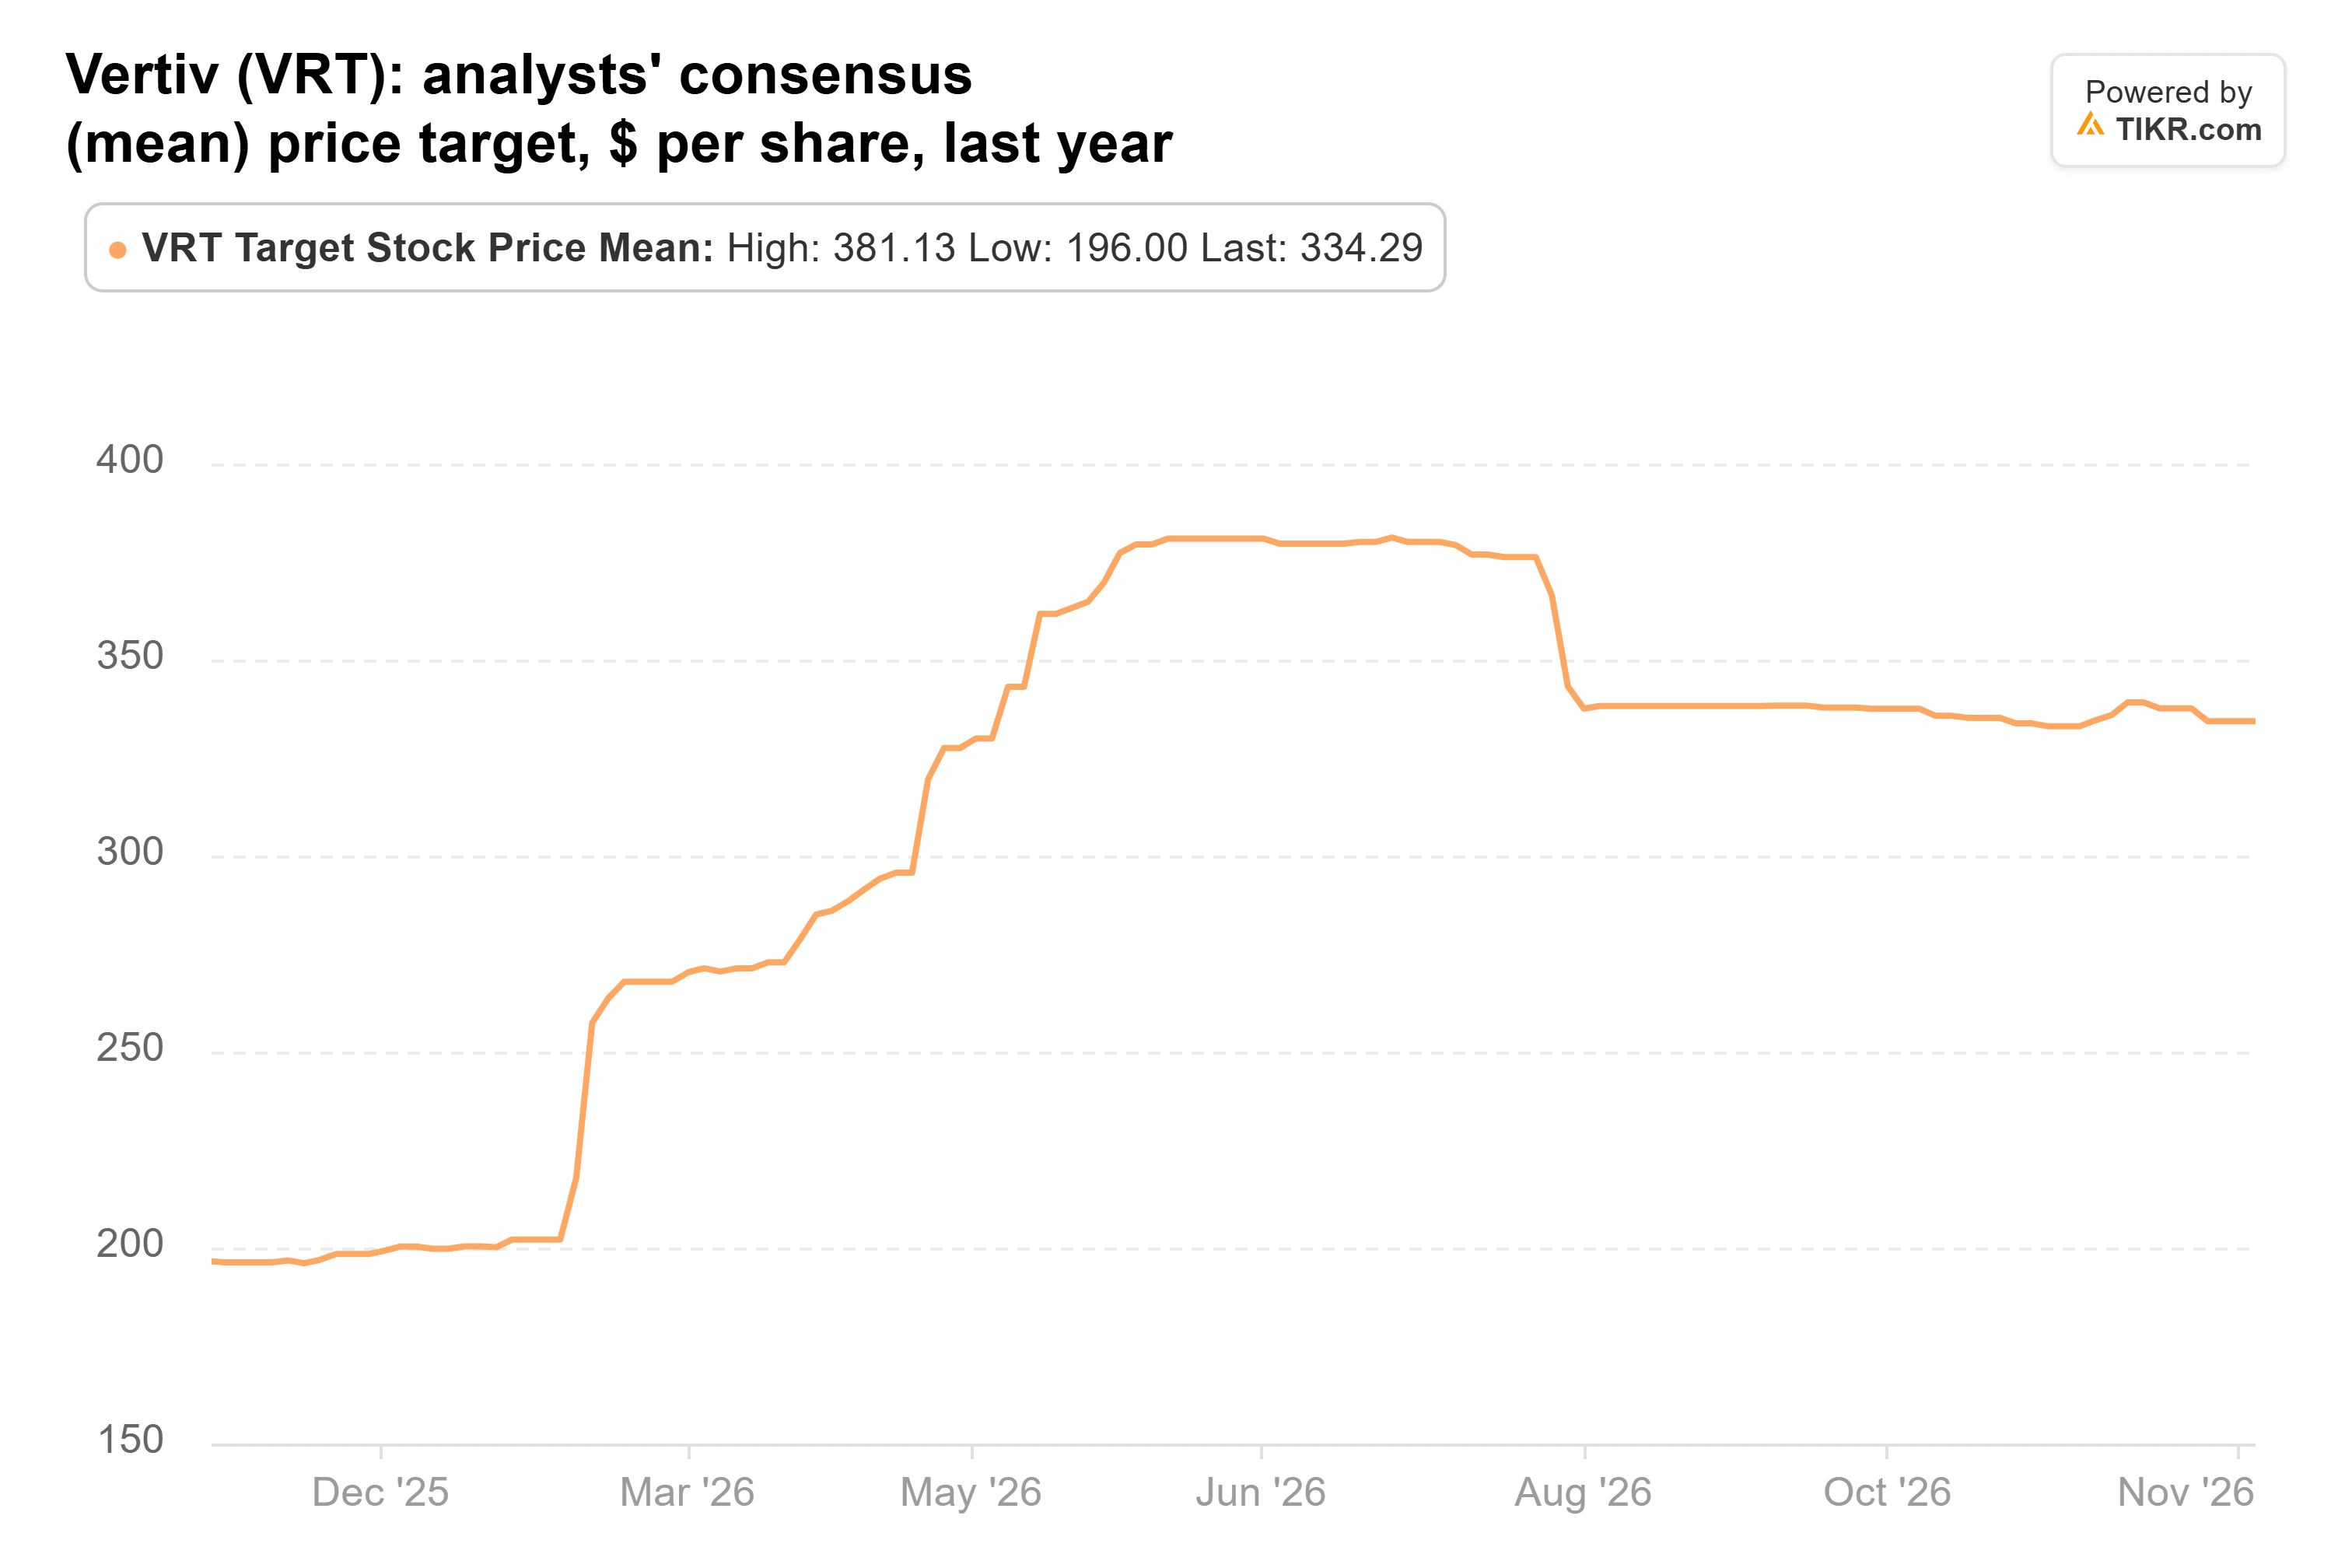
JPMorgan is at the bottom of TIKR’s range. It resumed coverage at Neutral with a $240 target on Nov. 11.
TIKR tracks 31 analysts on Vertiv. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Vertiv, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Vertiv’s Analyst Ratings
Does $325 add up?
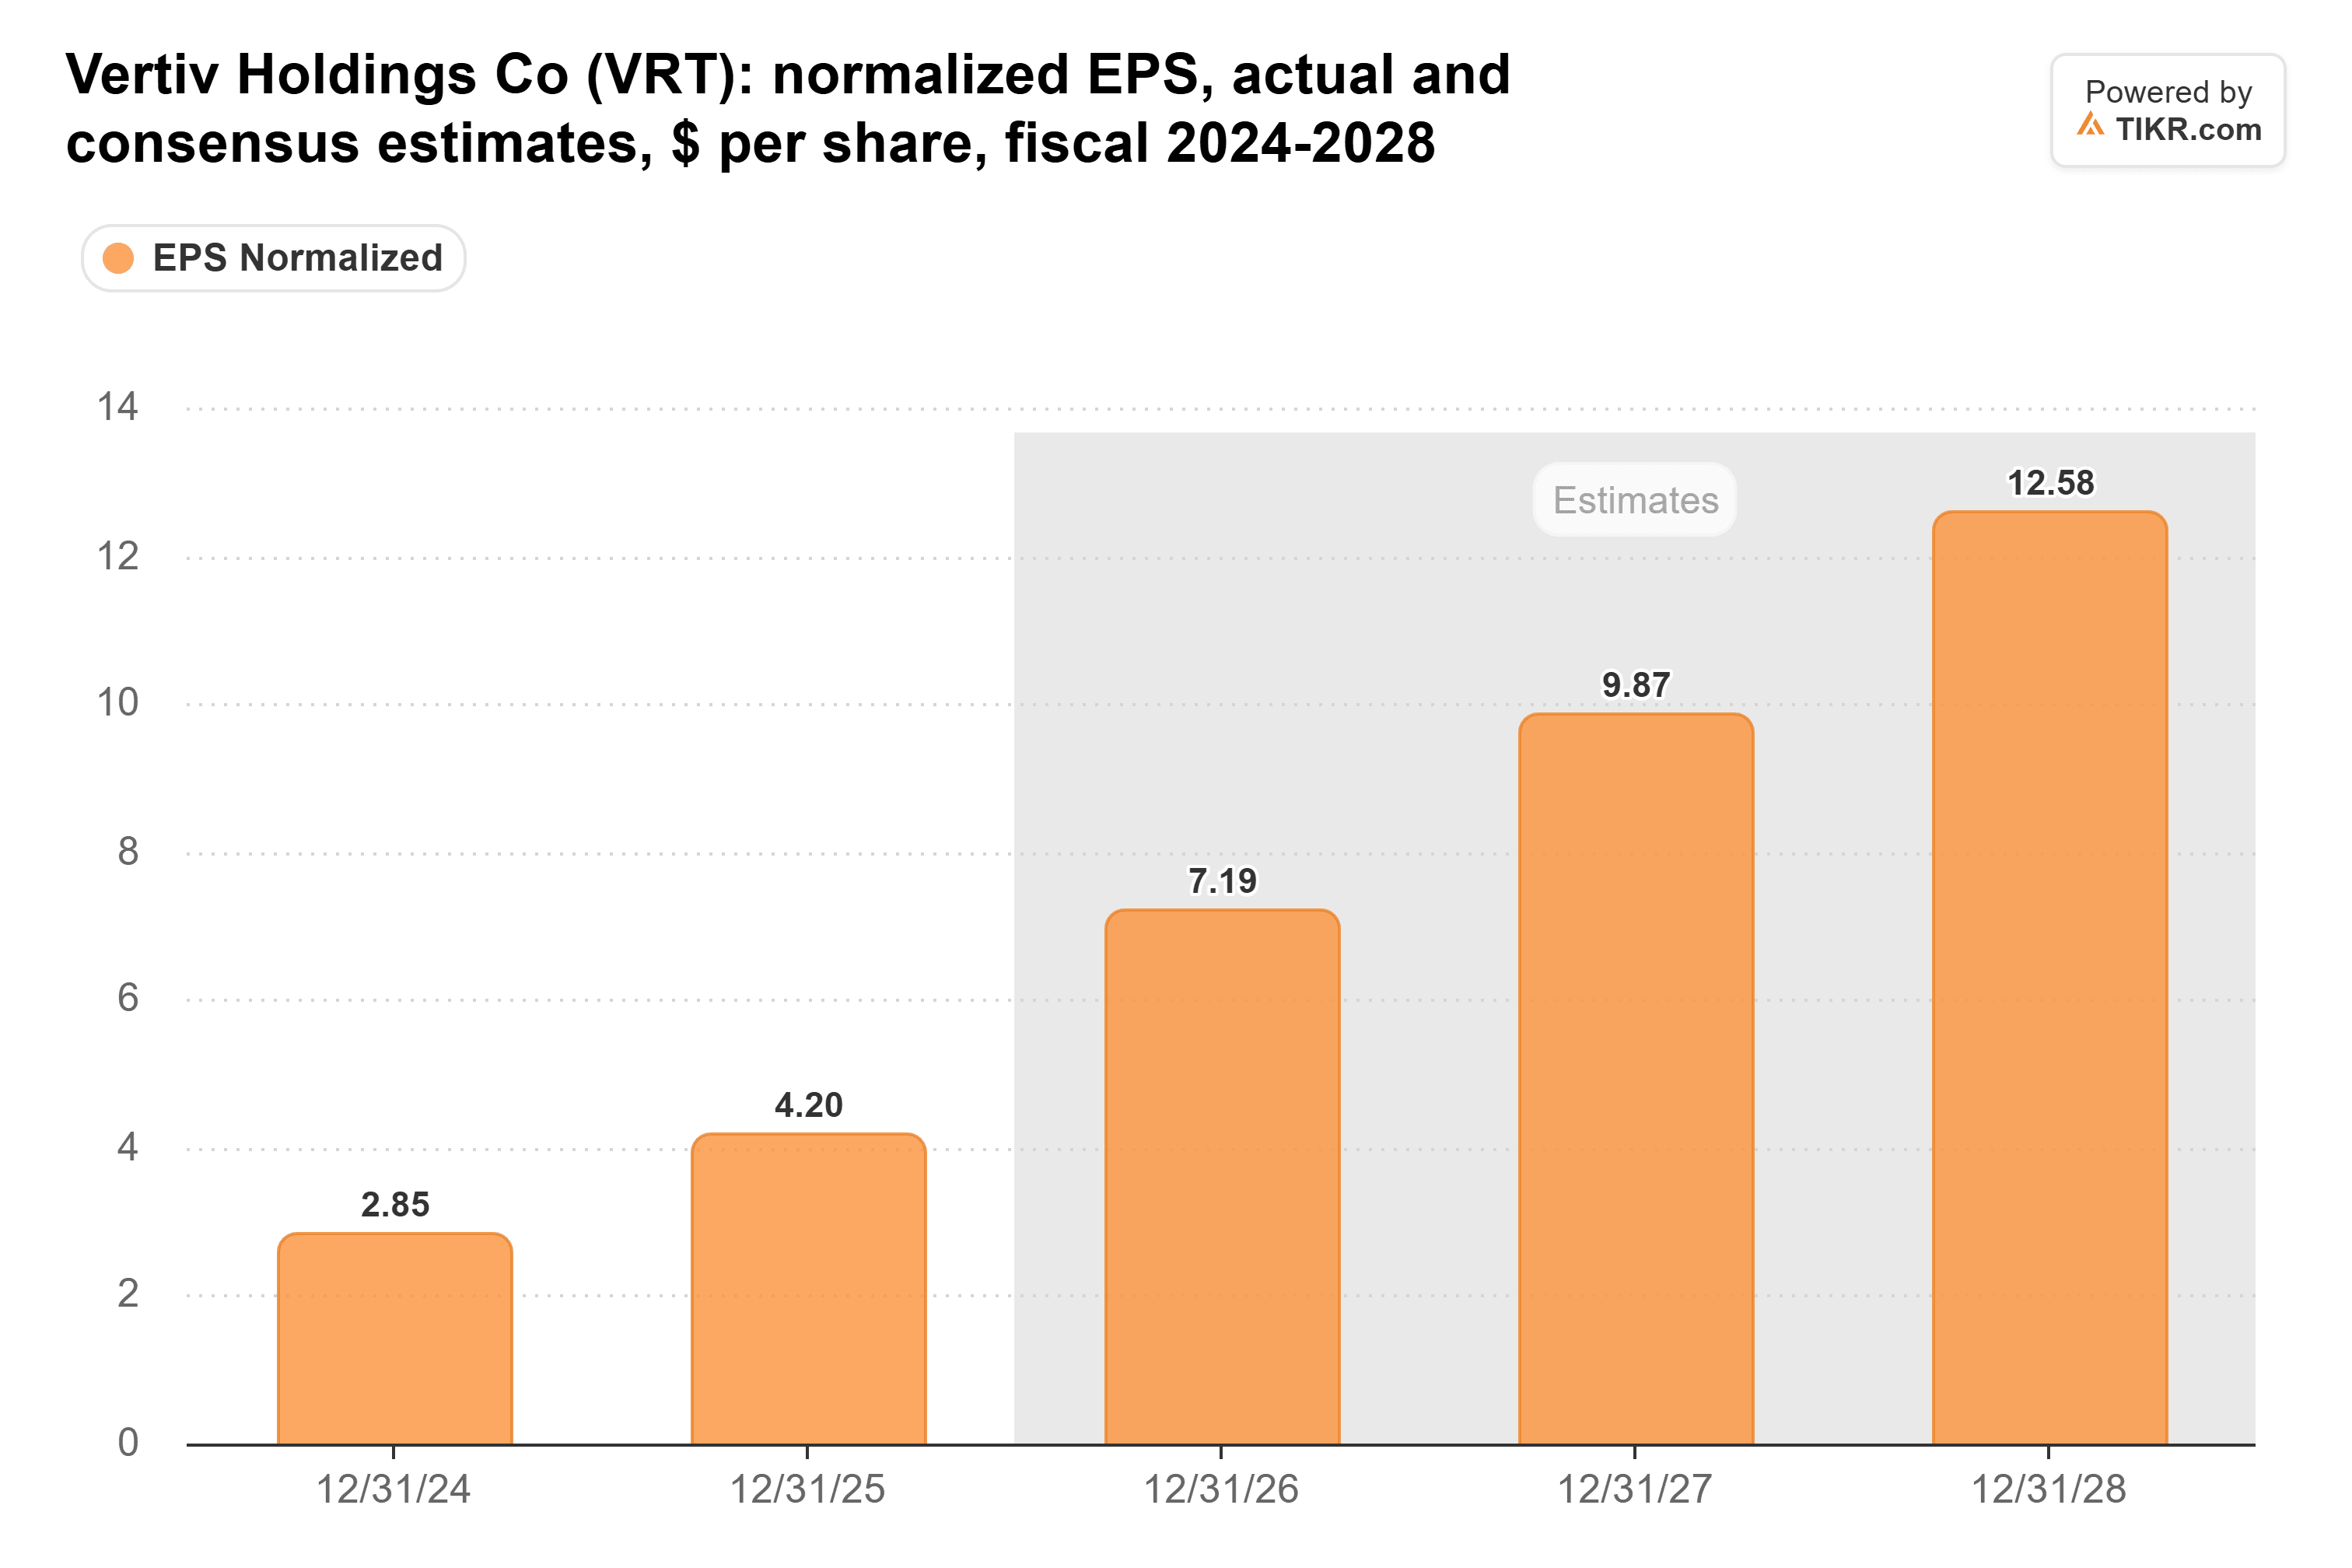
Estimates kept rising during the selloff. Consensus normalized EPS for 2027 is $9.87, up from about $9.10 three months ago, and analysts see $12.58 for 2028:
The multiple went the other way. Vertiv trades at about 20x forward earnings, against a 5-year average of 27x:
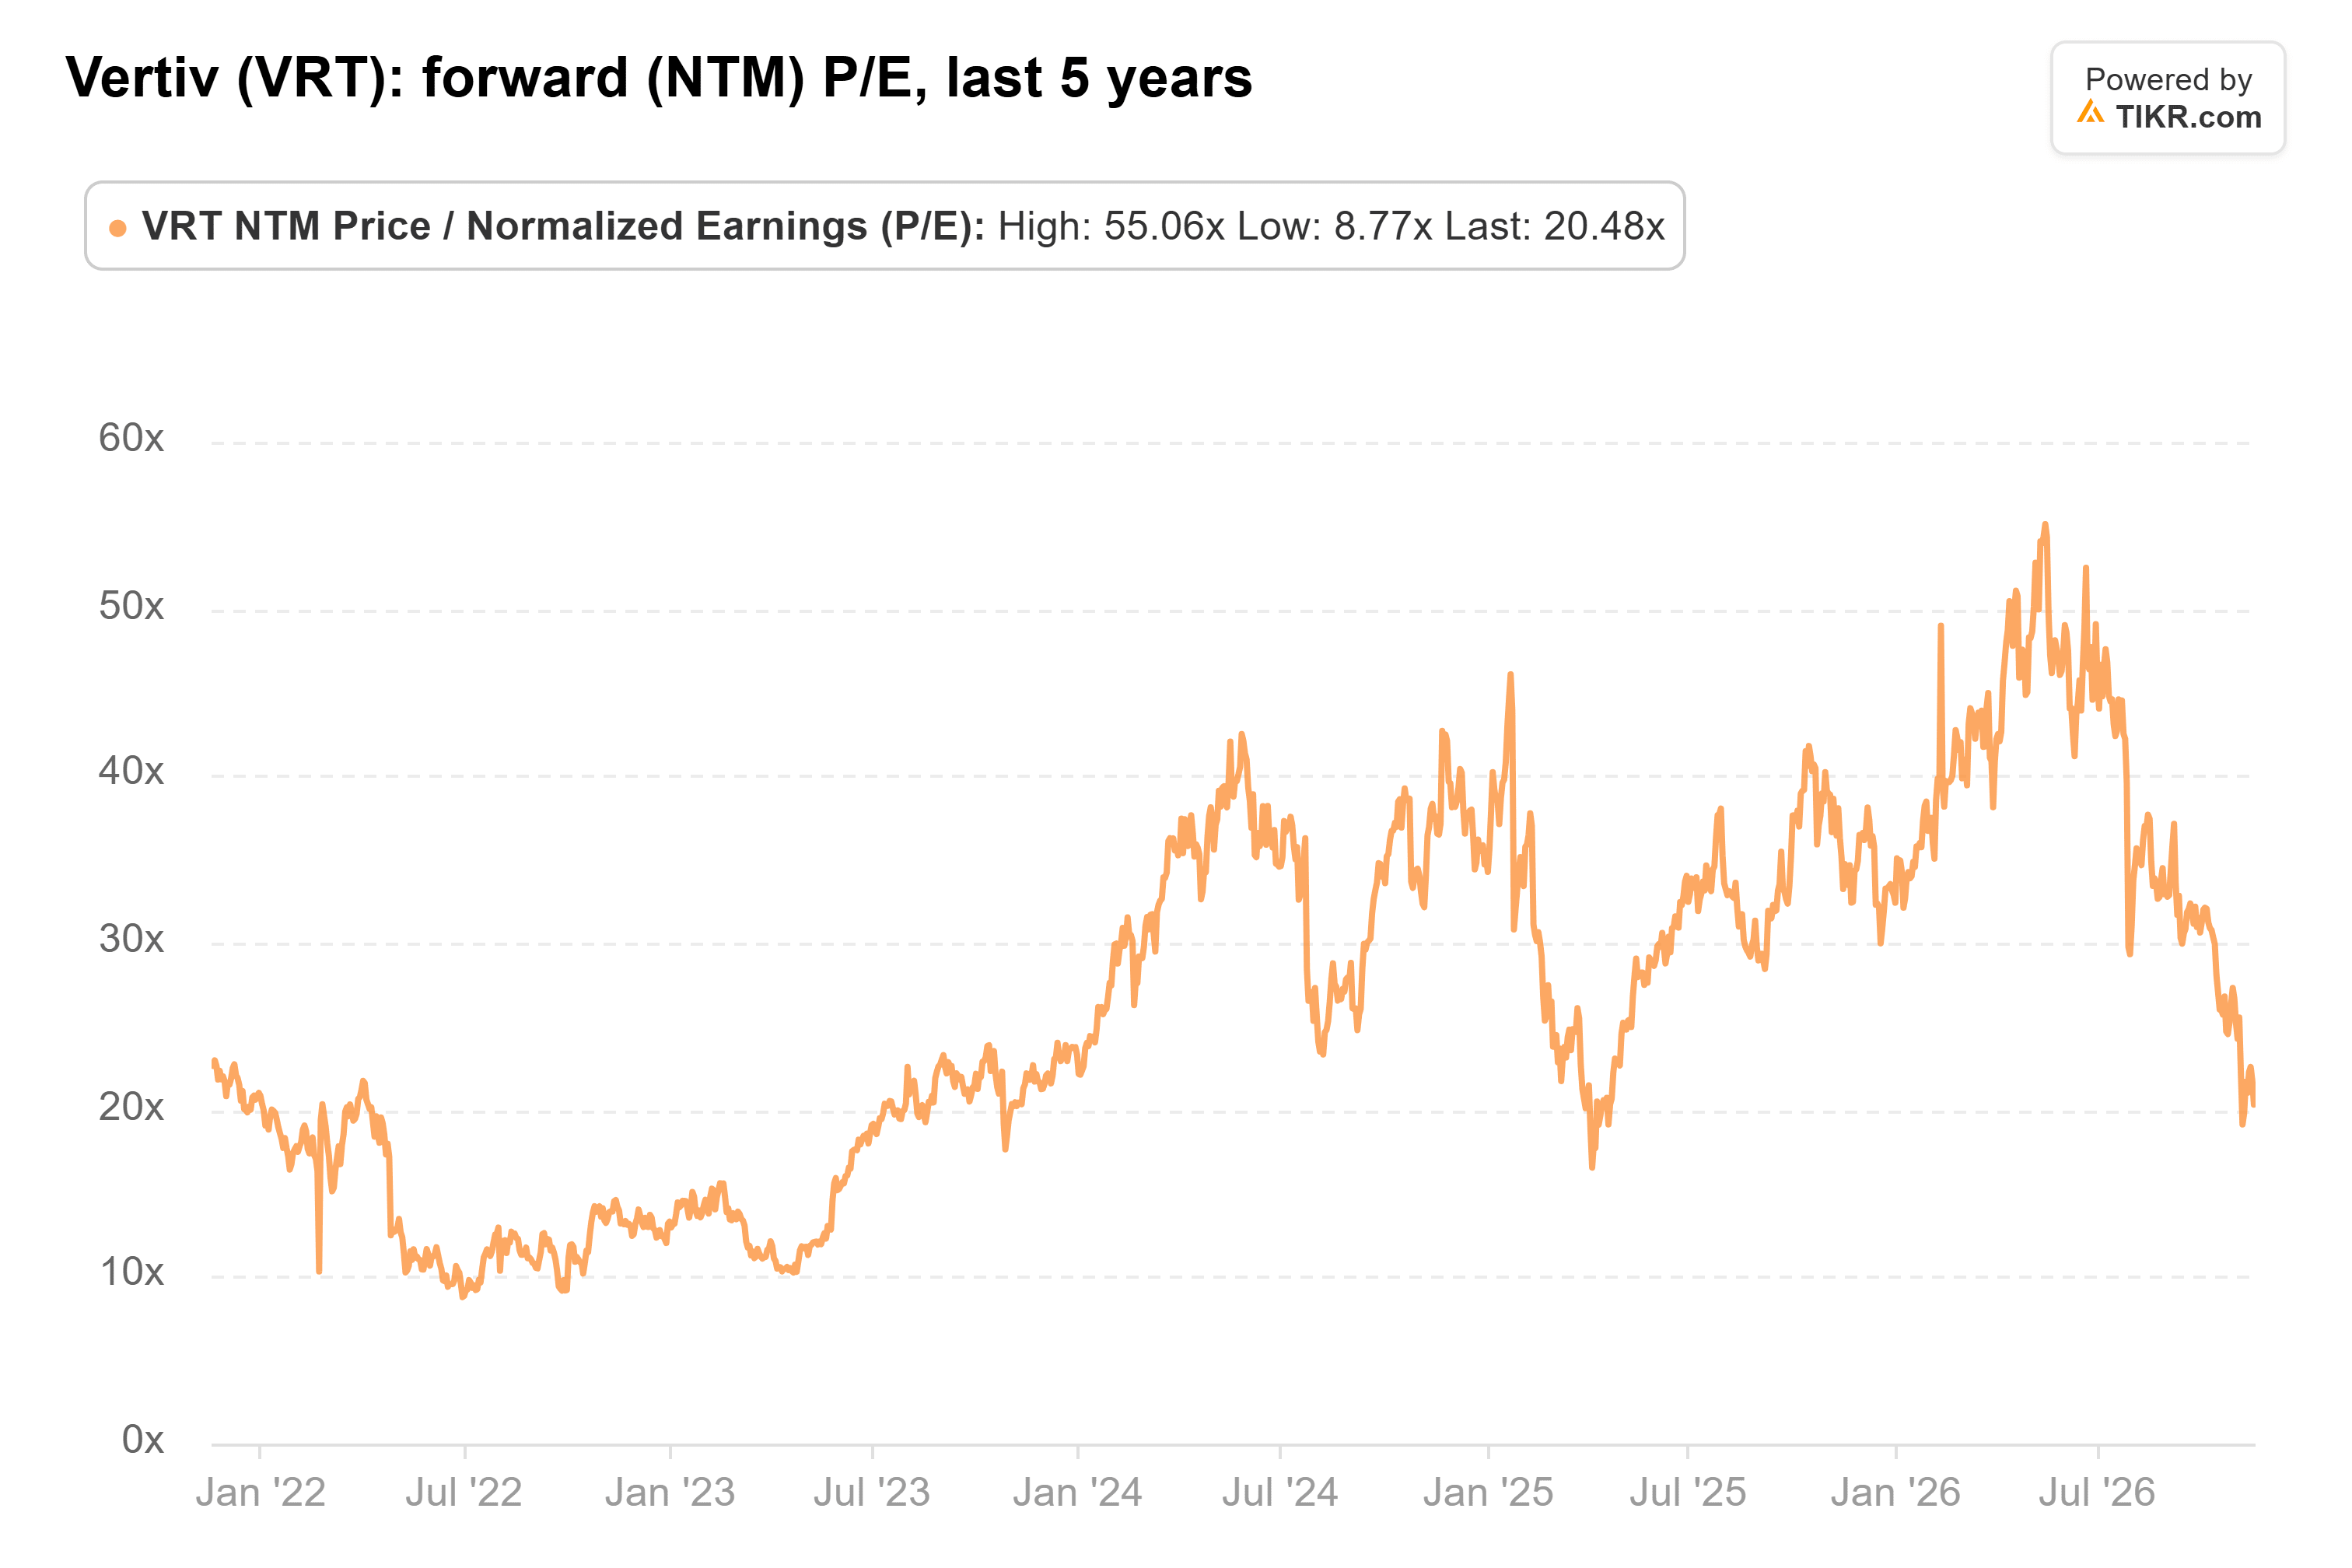
$325 works out to about 26x the 2028 consensus, a touch below that average. Getting there takes about 35% earnings growth plus a multiple roughly 30% higher than today’s. Vertiv costs more than nVent and Modexus, which both trade near 17x, but it’s making more of the boom: its third-quarter adjusted operating margin of 25.2%, up 290 basis points, tops nVent’s roughly 22%.
Evercore has the better argument
Politics is the risk. A slowdown in construction would hit orders first, and Executive Chairman Dave Cote said on the call that “we’re not planning to share orders data going forward.” Not every bull is leaning in, either: BofA dropped Vertiv from its US 1 List of top ideas on Nov. 18.
With estimates still rising, $325 looks like a fair bet. The fourth-quarter report in February is the next test: sales near the $4.41 billion guidance midpoint, adjusted EPS of $2.25, and a 2027 outlook that supports the $9.87 consensus.
So what is Vertiv stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Vertiv could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!