Key Takeaways
- DoubleLine Capital founder Jeffrey Gundlach called Anthropic’s hopes for an investment-grade bond rating “simply absurd” as the AI lab lines up its IPO.
- Anthropic has signed more than $800 billion of compute commitments, including deals with Amazon, Alphabet’s Google and Broadcom, and Bill Gurley says those weigh on its credit like a lease or a loan.
- Its suppliers already stand behind its credit: Broadcom guarantees $43 billion of the debt Anthropic raised to buy its chips, and Amazon lends to it as it uses AWS.
- For all three suppliers, the IPO’s cash matters more than any rating, and Broadcom has the most riding on it, with $66.5 billion of debt against $16.2 billion of cash at the end of its last fiscal year.
Anthropic wants an investment-grade credit rating. DoubleLine Capital founder Jeffrey Gundlach thinks that’s a fantasy, and he said so on X on Sunday:
“Anthropic hoping to get an investment grade bond rating is simply absurd. Any rating agency that might give such a rating should be investigated/shut down immediately.”
(Tell us how you really feel, Jeff.)
And Anthropic isn’t the only company with a stake in the answer. Amazon (AMZN), Alphabet (GOOG) and Broadcom (AVGO) all count Anthropic’s commitments in their backlogs, and Broadcom already guarantees much of the debt Anthropic took on to buy its chips.
The argument started on X on Friday, when The Nvidia Way author Tae Kim asked:
“In what universe is SpaceX investment grade but Anthropic isn’t after the S-1 revealed its inference economics, limited cash burn alongside exponential growth, leadership in the most important market of this generation and net cash position? Are the rating agencies insane?”
Benchmark’s Bill Gurley had a quick answer:
“Tae – calm down and look at the future commitments. Those are future claims on FCF just like a lease or a loan. They have many of them – record levels. Maybe of all time.”
TIKR tracks 60 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Gurley has the better of that argument. Kroll Bond Rating Agency rated Anthropic BB+ in June, one notch below investment grade, the Financial Times reported in October.
The suppliers are already the lenders
On last week’s episode of the Prof G Markets podcast, co-host Ed Elson went through Anthropic’s S-1 and pointed out that “Anthropic has signed more than $800 billion in future compute commitments, none of which are reflected in the current income statement.”
According to Elson, that total includes $110 billion with Amazon, $115 billion with Google and $161 billion with Broadcom.
Each of those dollars also sits in a supplier’s backlog. Analysts expect Alphabet’s revenue to nearly double from fiscal 2025 to fiscal 2028:
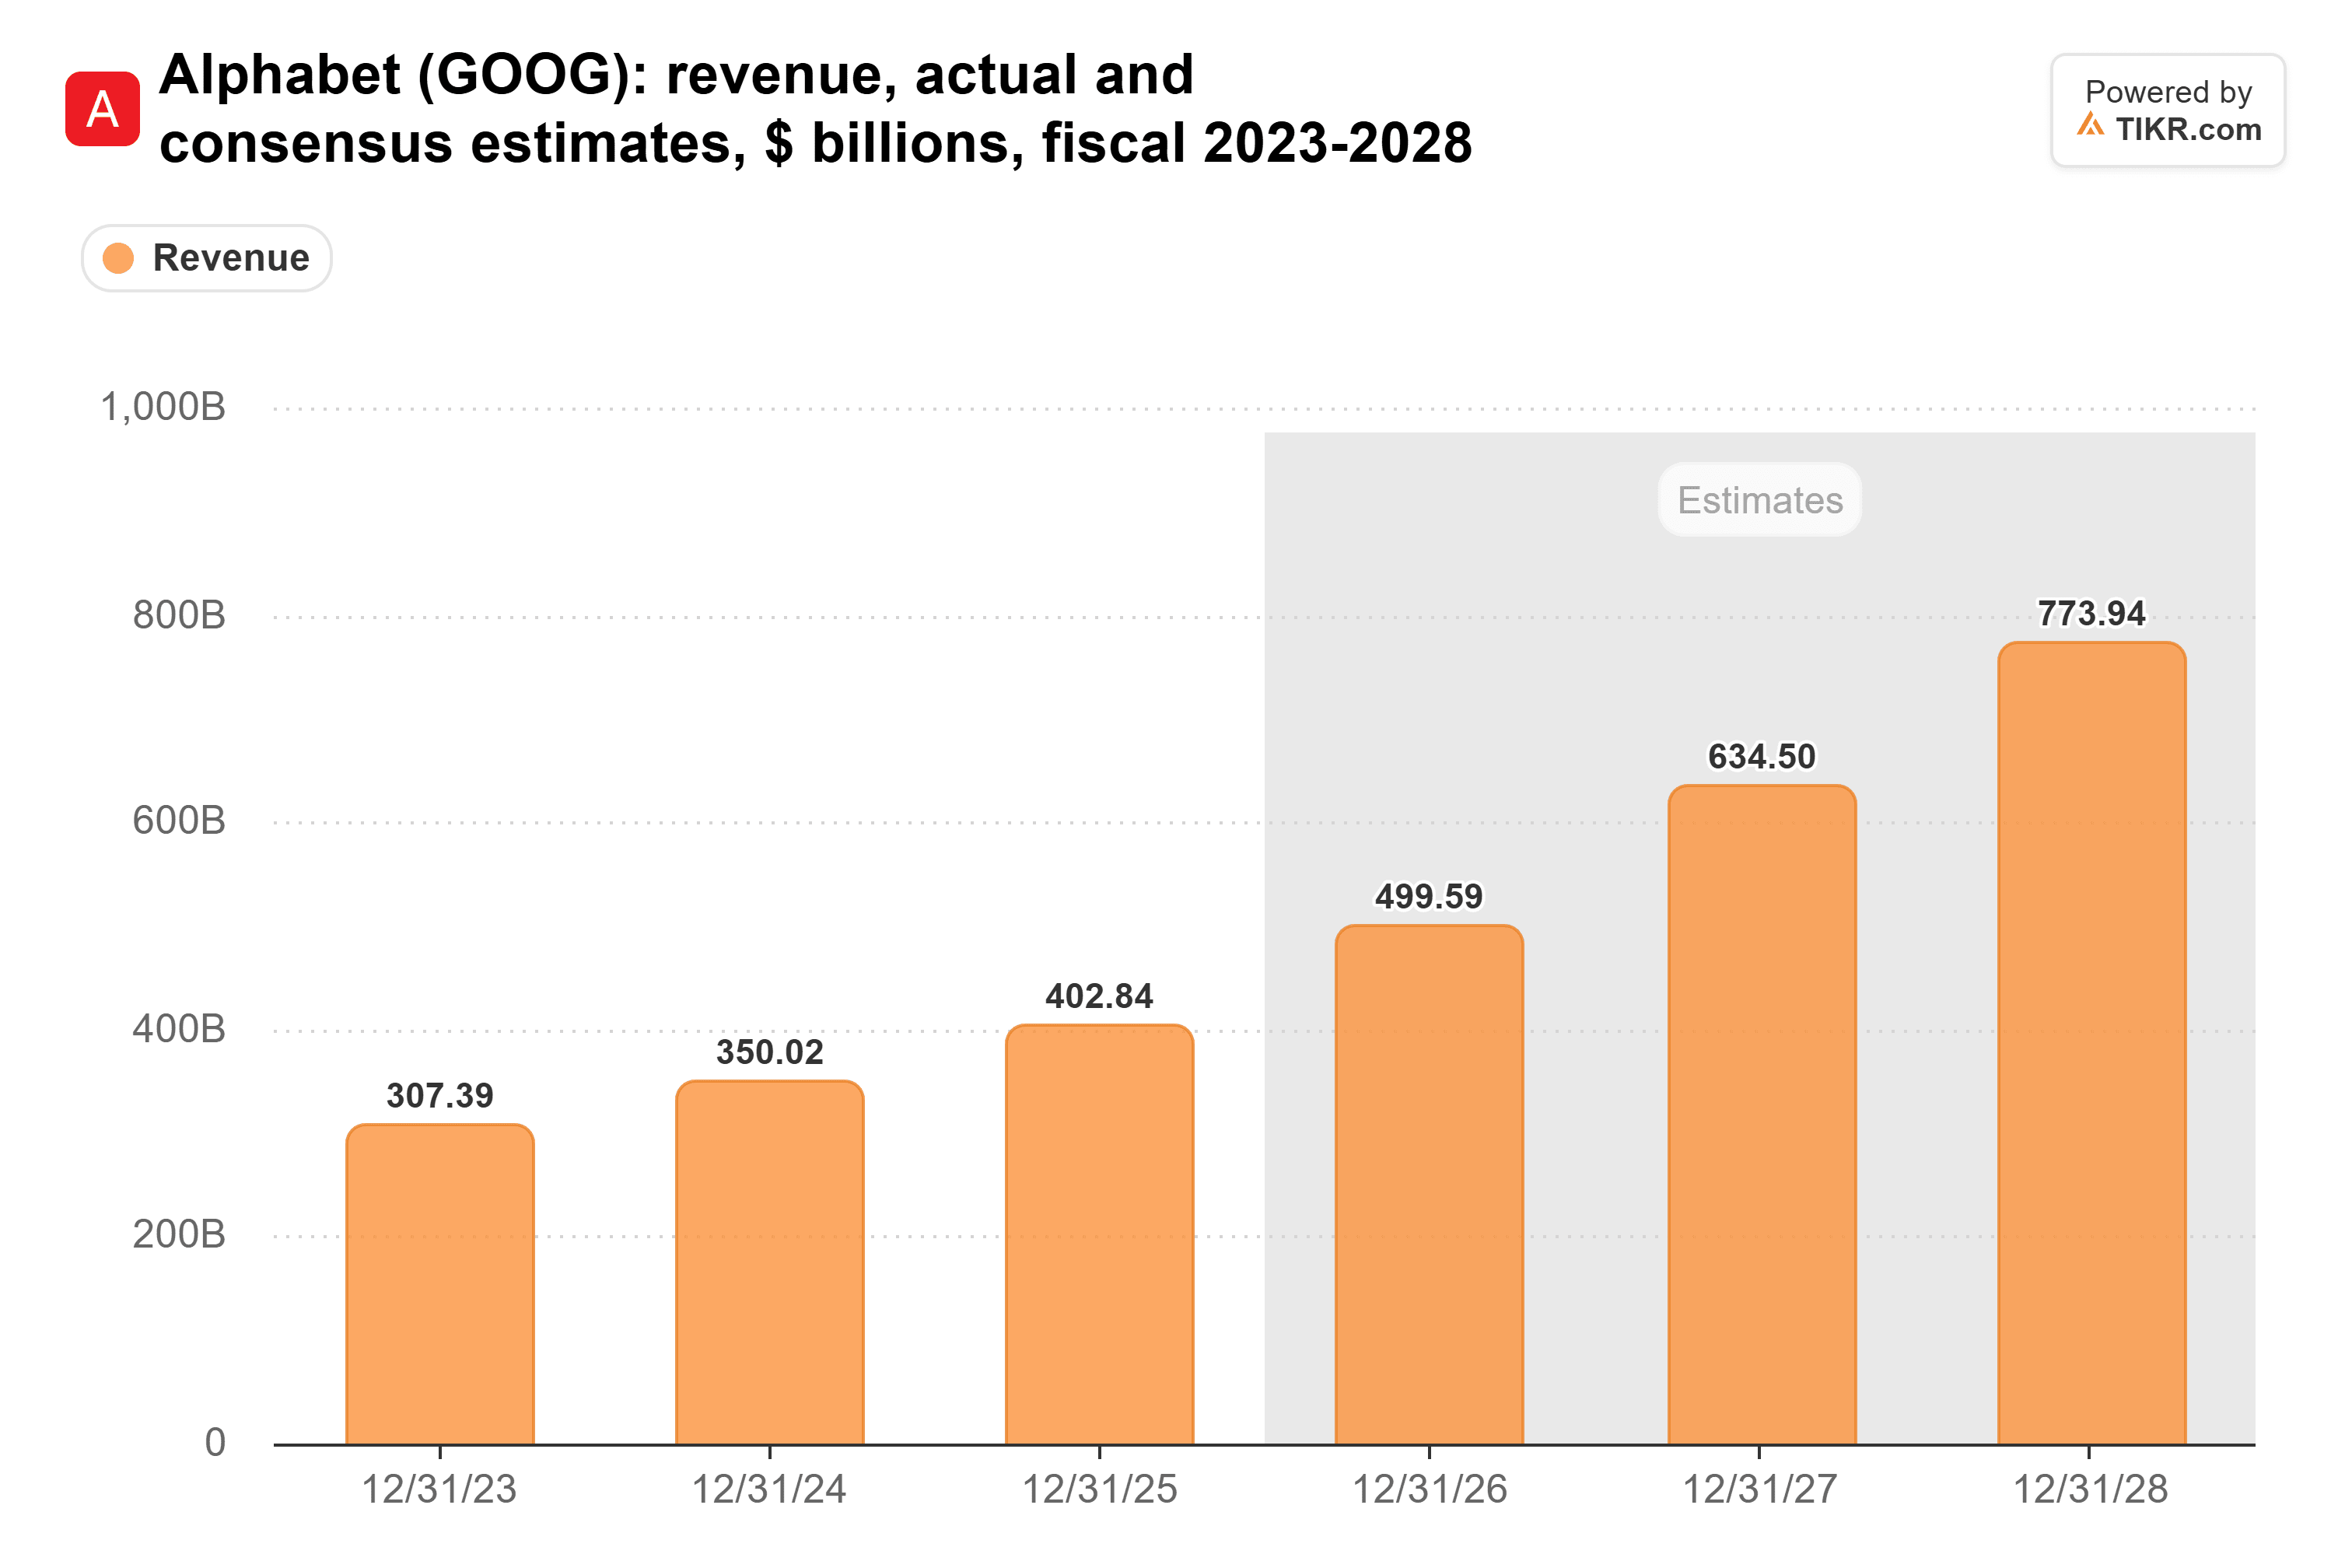
Anthropic’s $115 billion alone is more than a quarter of the $403 billion Alphabet brought in during all of 2025.
Amazon goes a step further. Anthropic has to pay for its AWS commitment whether it uses the capacity or not, and Amazon is also lending it money along the way. It has a $20 billion facility that Amazon funds as AWS delivers compute, and $15 billion of it was still undrawn at June 30.
Amazon is doing all this while its own cash shrinks. Its free cash flow fell to $7.7 billion in 2025, from $32.9 billion in 2024:
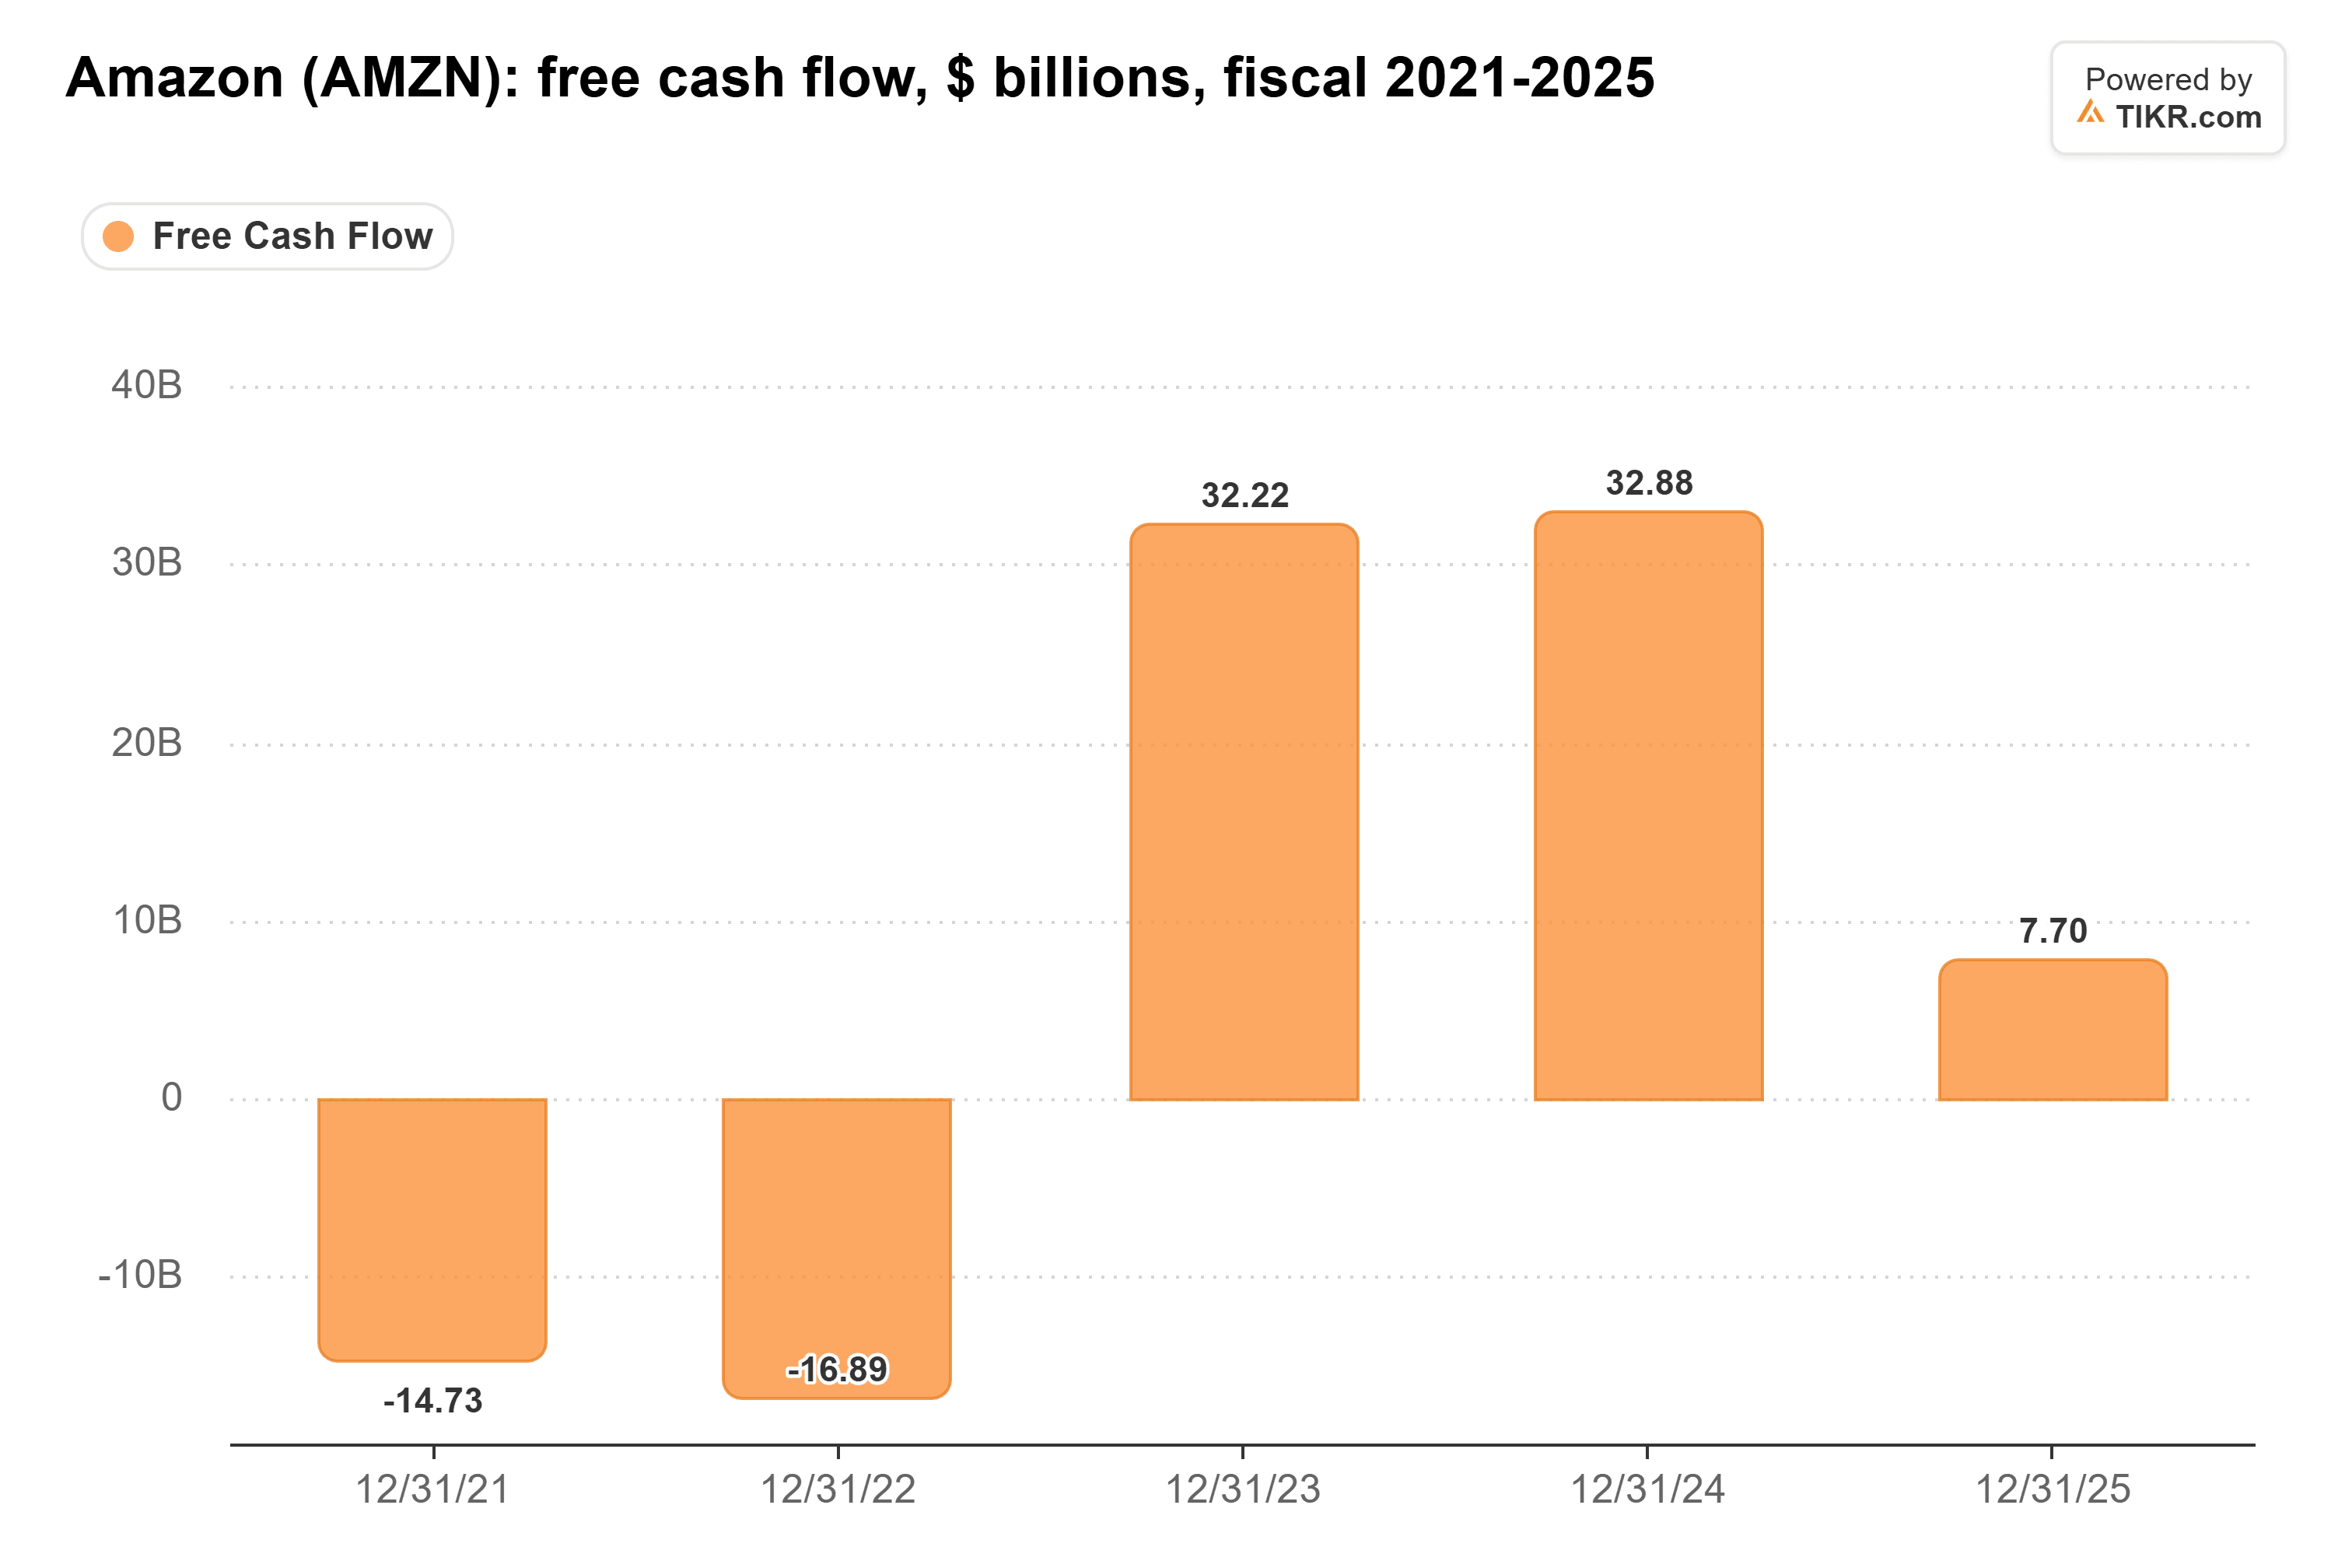
And over the twelve months to Sept. 30, it was a $42.4 billion outflow.
Broadcom signed on the dotted line
Broadcom’s role in Anthropic’s chip financing came up on last week’s episode of 20VC. SaaStr founder Jason Lemkin said that “they weren’t able to get this debt for this semi-circular deal with Broadcom and Broadcom had to come in and guarantee most of it.”
That guarantee covers $43 billion of a $63 billion chip package. Broadcom also carries about four times as much debt as cash:
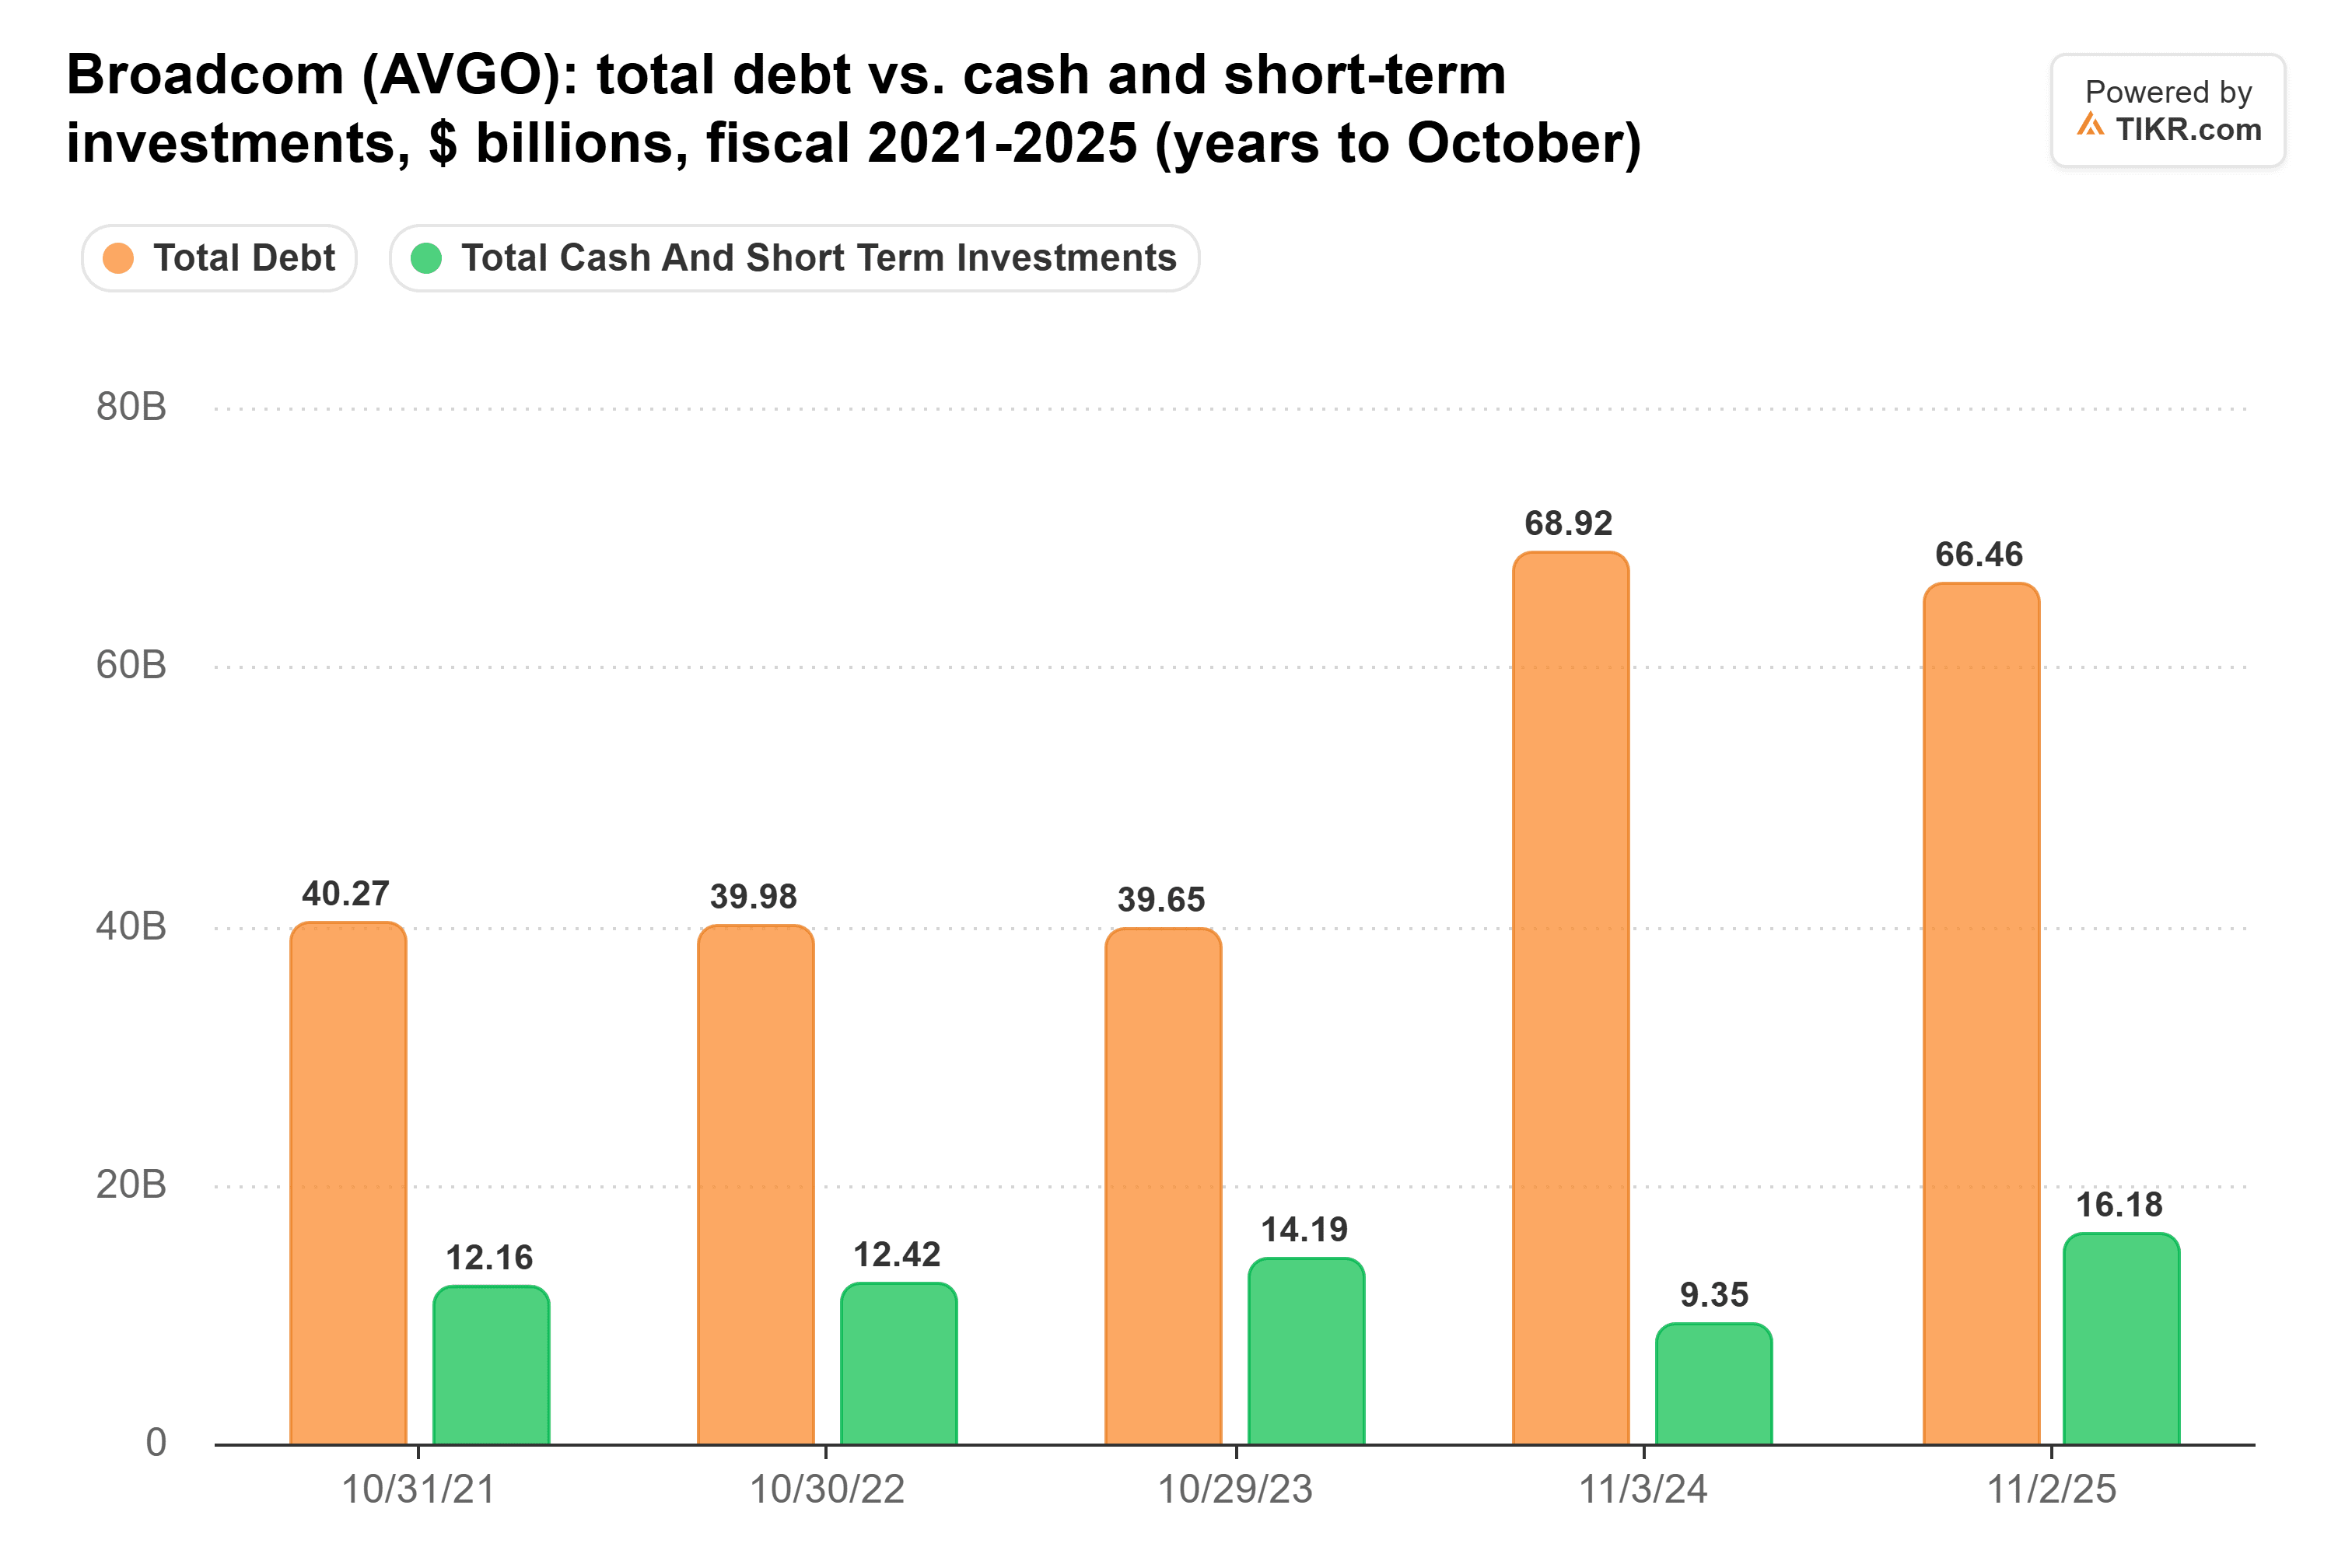
The guarantee alone is about two-thirds the size of the debt on Broadcom’s own balance sheet.
The IPO is the real backstop
Anthropic’s best answer to all this is the IPO. The deal is big enough that Anthropic is lining up as much as $3.5 billion from Japanese investors alone, according to a regulatory filing on Monday.
Every dollar it raises is a dollar Anthropic doesn’t have to borrow to pay Amazon, Google and Broadcom.
But Blackstone, one of the lenders behind Anthropic’s chip financing, now reportedly expects Anthropic to get a junk rating even after the IPO. The IPO’s cash comes in once, while Anthropic’s $110 billion AWS commitment alone runs through 2036.
So Anthropic can’t borrow at investment grade on its own because its commitments already claim so much of its future cash. Gundlach’s “absurd” is harsh for a company one notch from the line, but the agencies have good reason to hold back.
For Anthropic’s suppliers, the IPO matters more than the rating. Amazon and Alphabet have backlogs riding on it. Broadcom has its name on Anthropic’s debt, which makes it the one I’d watch most closely.
Of course, Moody’s, S&P and Fitch haven’t rated Anthropic yet, and a big enough IPO could still change their view.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!