


Key Takeaways
- Alphabet stock fell nearly 19% in October, its worst month since its 2004 IPO, after its third-quarter Search revenue missed estimates.
- Former Stability AI CEO Emad Mostaque predicts search advertising will peak as an industry in the first quarter of next year, a call that reaches Meta Platforms but would hit Alphabet hardest.
- Google Cloud is growing much faster than Search but needs far more capital, and Alphabet’s free cash flow was negative $9.1 billion last quarter.
- At 20x forward earnings, the stock trades well below its ten-year average, but analysts still expect normalized EPS of $18.26 by 2028.
Alphabet (GOOG) just had the worst month in its history as a public company. The stock fell nearly 19% in October, including a 13% plunge the day after its third-quarter report showed Search revenue coming up short.
Then Emad Mostaque, the former CEO of Stability AI, said this may be only the start.
He was talking on Peter Diamandis’s Moonshots podcast about AI agents that shop for people. His argument was that those agents hit the main business of both Google and Meta Platforms (META). Then he made a call:
“I think search advertising will top as an industry in Q1.”
That’s a gutsy call, and it comes due quickly: the first quarter ends March 31.
Meta sells its ads in feeds, so a top in search would reach it less directly. Alphabet has much more riding on search. Search & other brought in 55.7% of its revenue in 2025.
Wall Street isn’t modeling a peak
Analysts expect Alphabet’s earnings to keep climbing. Their consensus has normalized EPS rising from $10.81 in 2025 to $18.26 by 2028:
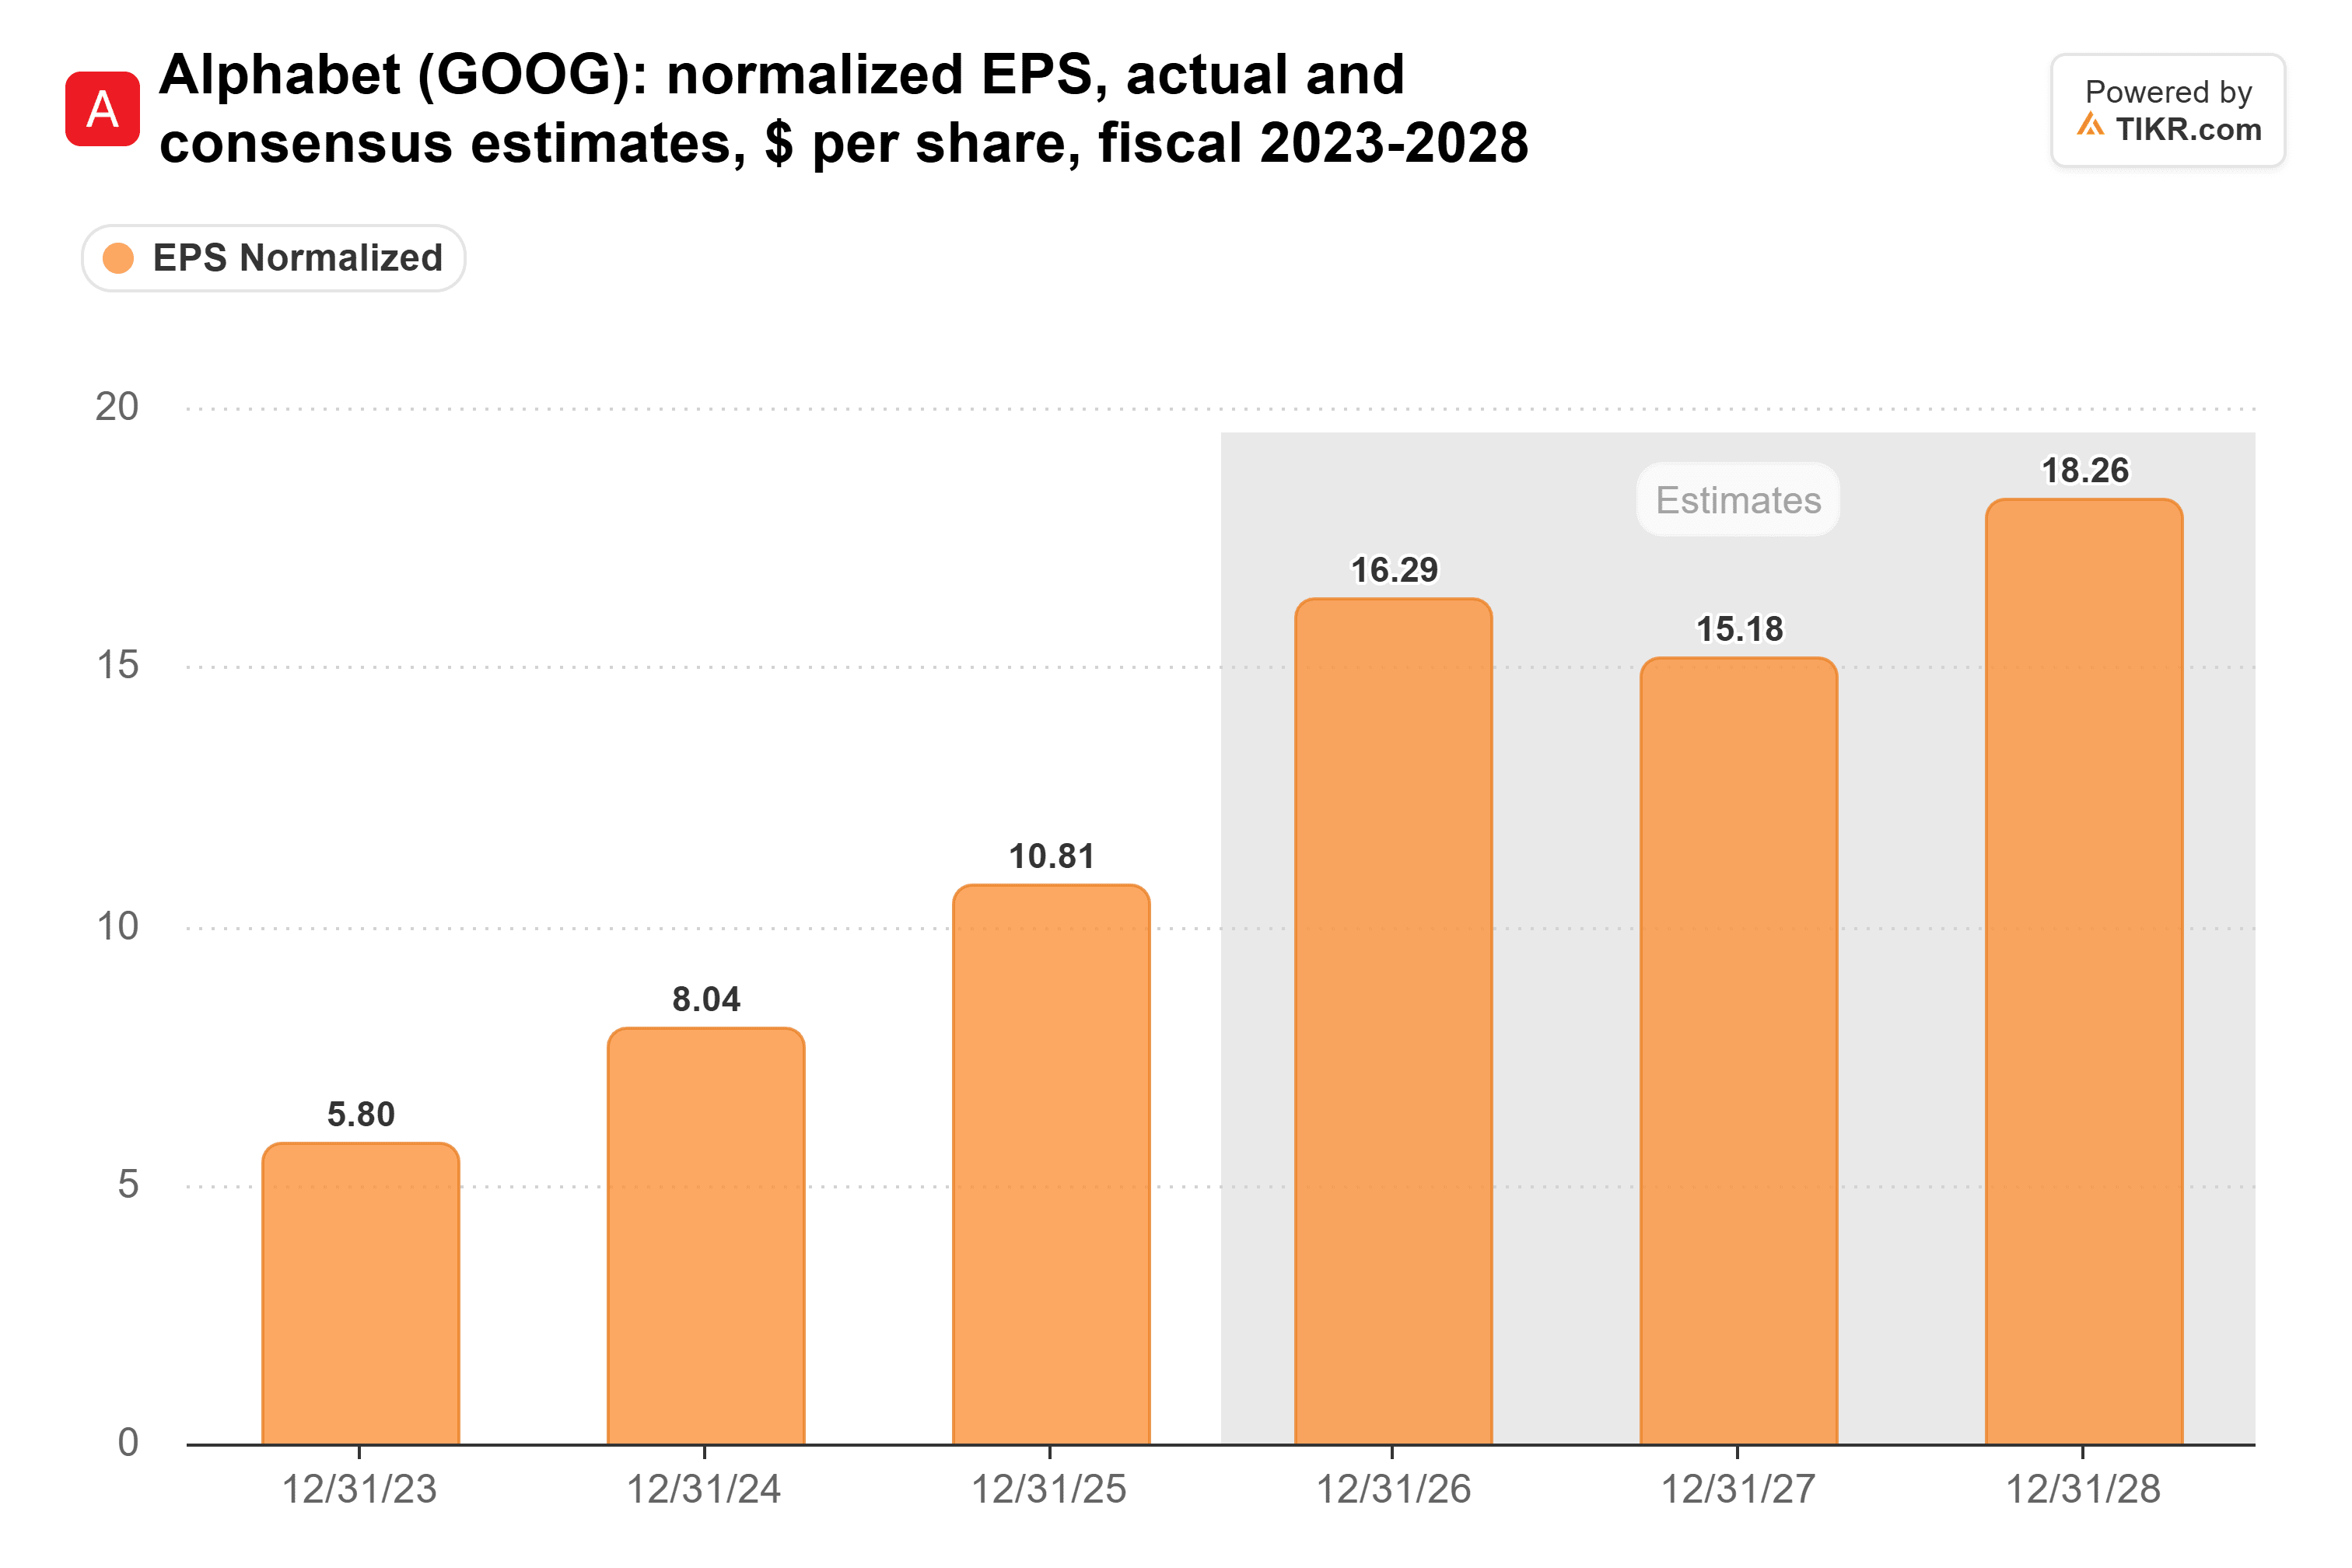
They do expect a dip in 2027, to $15.18 from $16.29, the year CFO Anat Ashkenazi expects capex “to increase significantly.” If search revenue tops out next quarter, those 2027 and 2028 numbers have further to fall.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
AI Mode earns less per search
Search revenue is still growing. Search & other rose 12% to $63.4 billion in the third quarter. On the call, CEO Sundar Pichai said query growth was “the highest it’s been in the last five years.” Going from there to a peak within months would be a sharp turn.
But growth slowed from 17% in the second quarter. Chief Business Officer Philipp Schindler blamed the slowdown partly on currency and partly on lower monetization in AI Mode.
And AI Mode is taking a fast-growing share of searches. Ranjan Roy pointed out on the Big Technology Podcast that, by Google’s own figures, the share of searches ending in AI Mode went from 2% to 8.9%.
So more people are searching, and more of those searches end in the format Google earns less from. Search ad revenue can stall that way even with queries at a five-year high.
Cloud is taking over the growth
Google Cloud revenue more than doubled in the third quarter, up 103% to $30.7 billion. Search still brings in about twice as much, but Cloud is growing more than eight times as fast.
On the same Moonshots episode, venture capitalist Dave Blundin said Alphabet’s revenue mix shows it is “so obviously transitioning away from becoming a search advertising company to becoming a hyperscaler cloud company.”
That shift changes how much Alphabet can earn. Roy put it bluntly: “there is no way a compute provider business model has the same attractive economics as search advertising.”
On reported margins, Cloud has closed much of the gap. Its operating margin was 36.2% last quarter, up from 23.7% a year earlier. Google Services ran at 41.8% in the second quarter.
The bigger gap is capital. Capex went from 9.6% of revenue in 2021 to 22.7% in 2025. Alphabet spent $51.4 billion on capex in the third quarter alone, and free cash flow came in at negative $9.1 billion. Meta also reported negative free cash flow with its third-quarter results, for the first time in years.
Search’s high margins are why Alphabet’s operating margin has held at about 32% for the past two years:
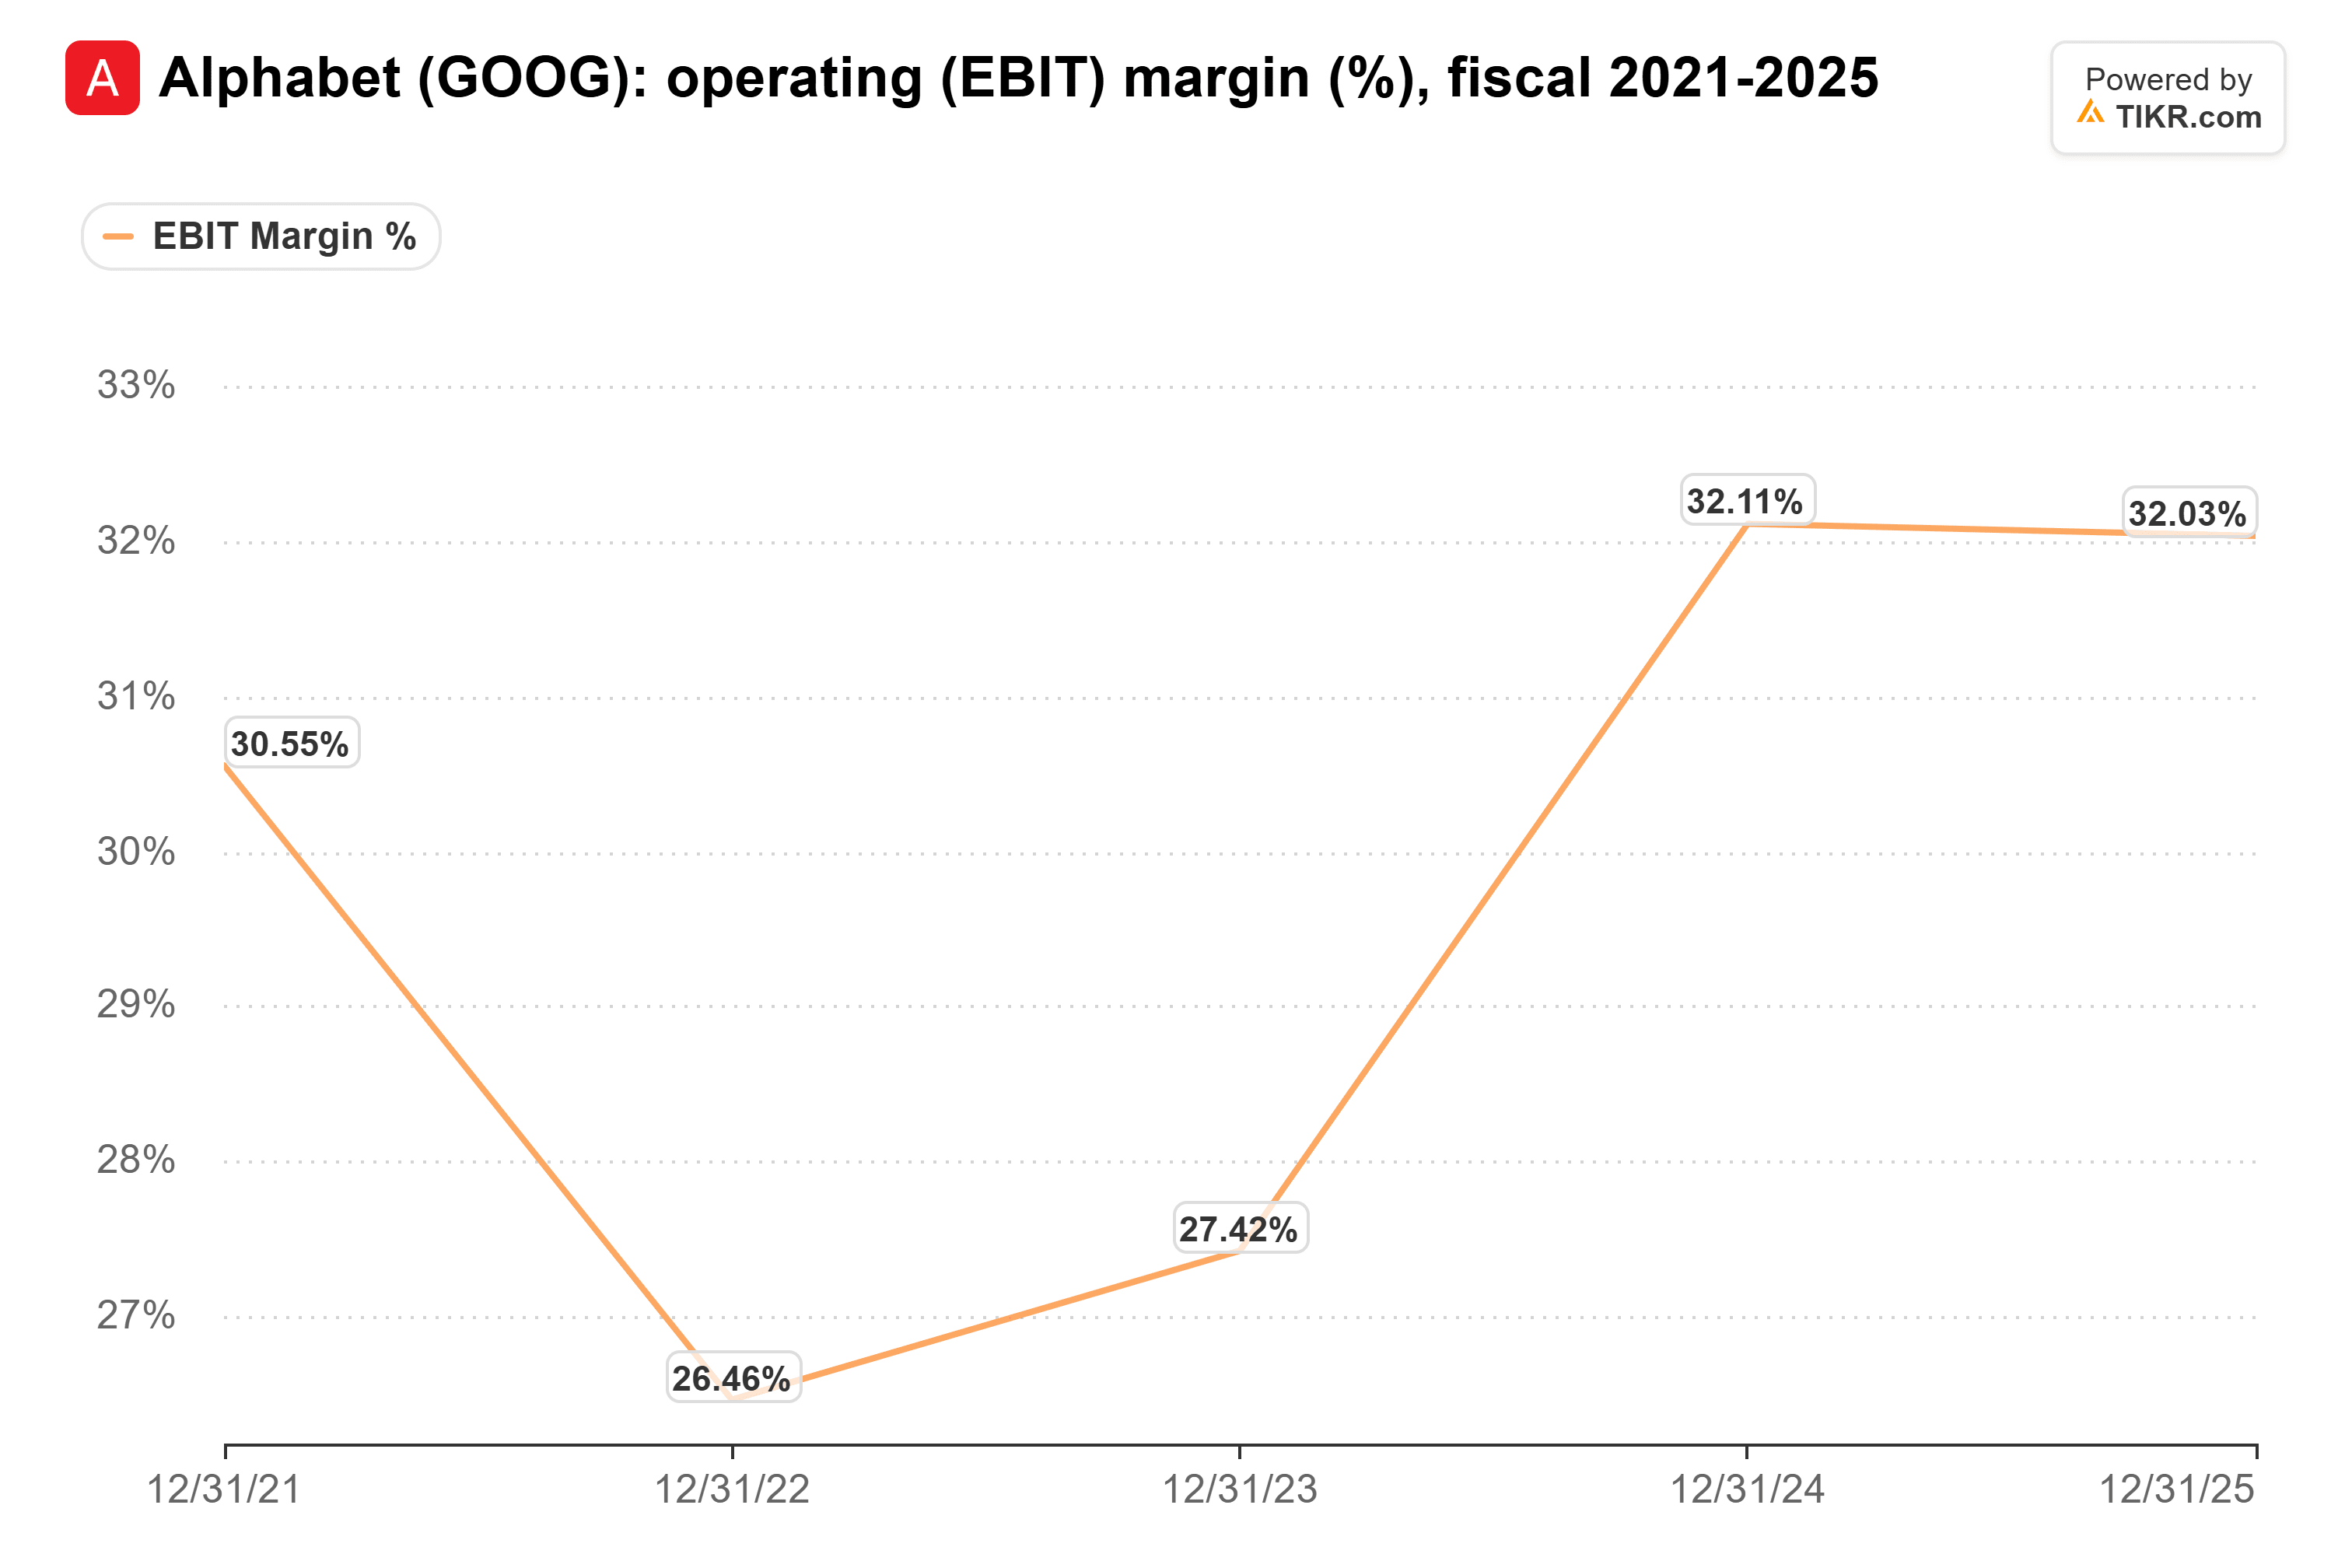
As more of the profit comes from Cloud, more of it comes with data centers to depreciate.
The stock already trades at a discount
After October, Alphabet trades at 20x forward earnings, well below its 24x average over the past ten years:
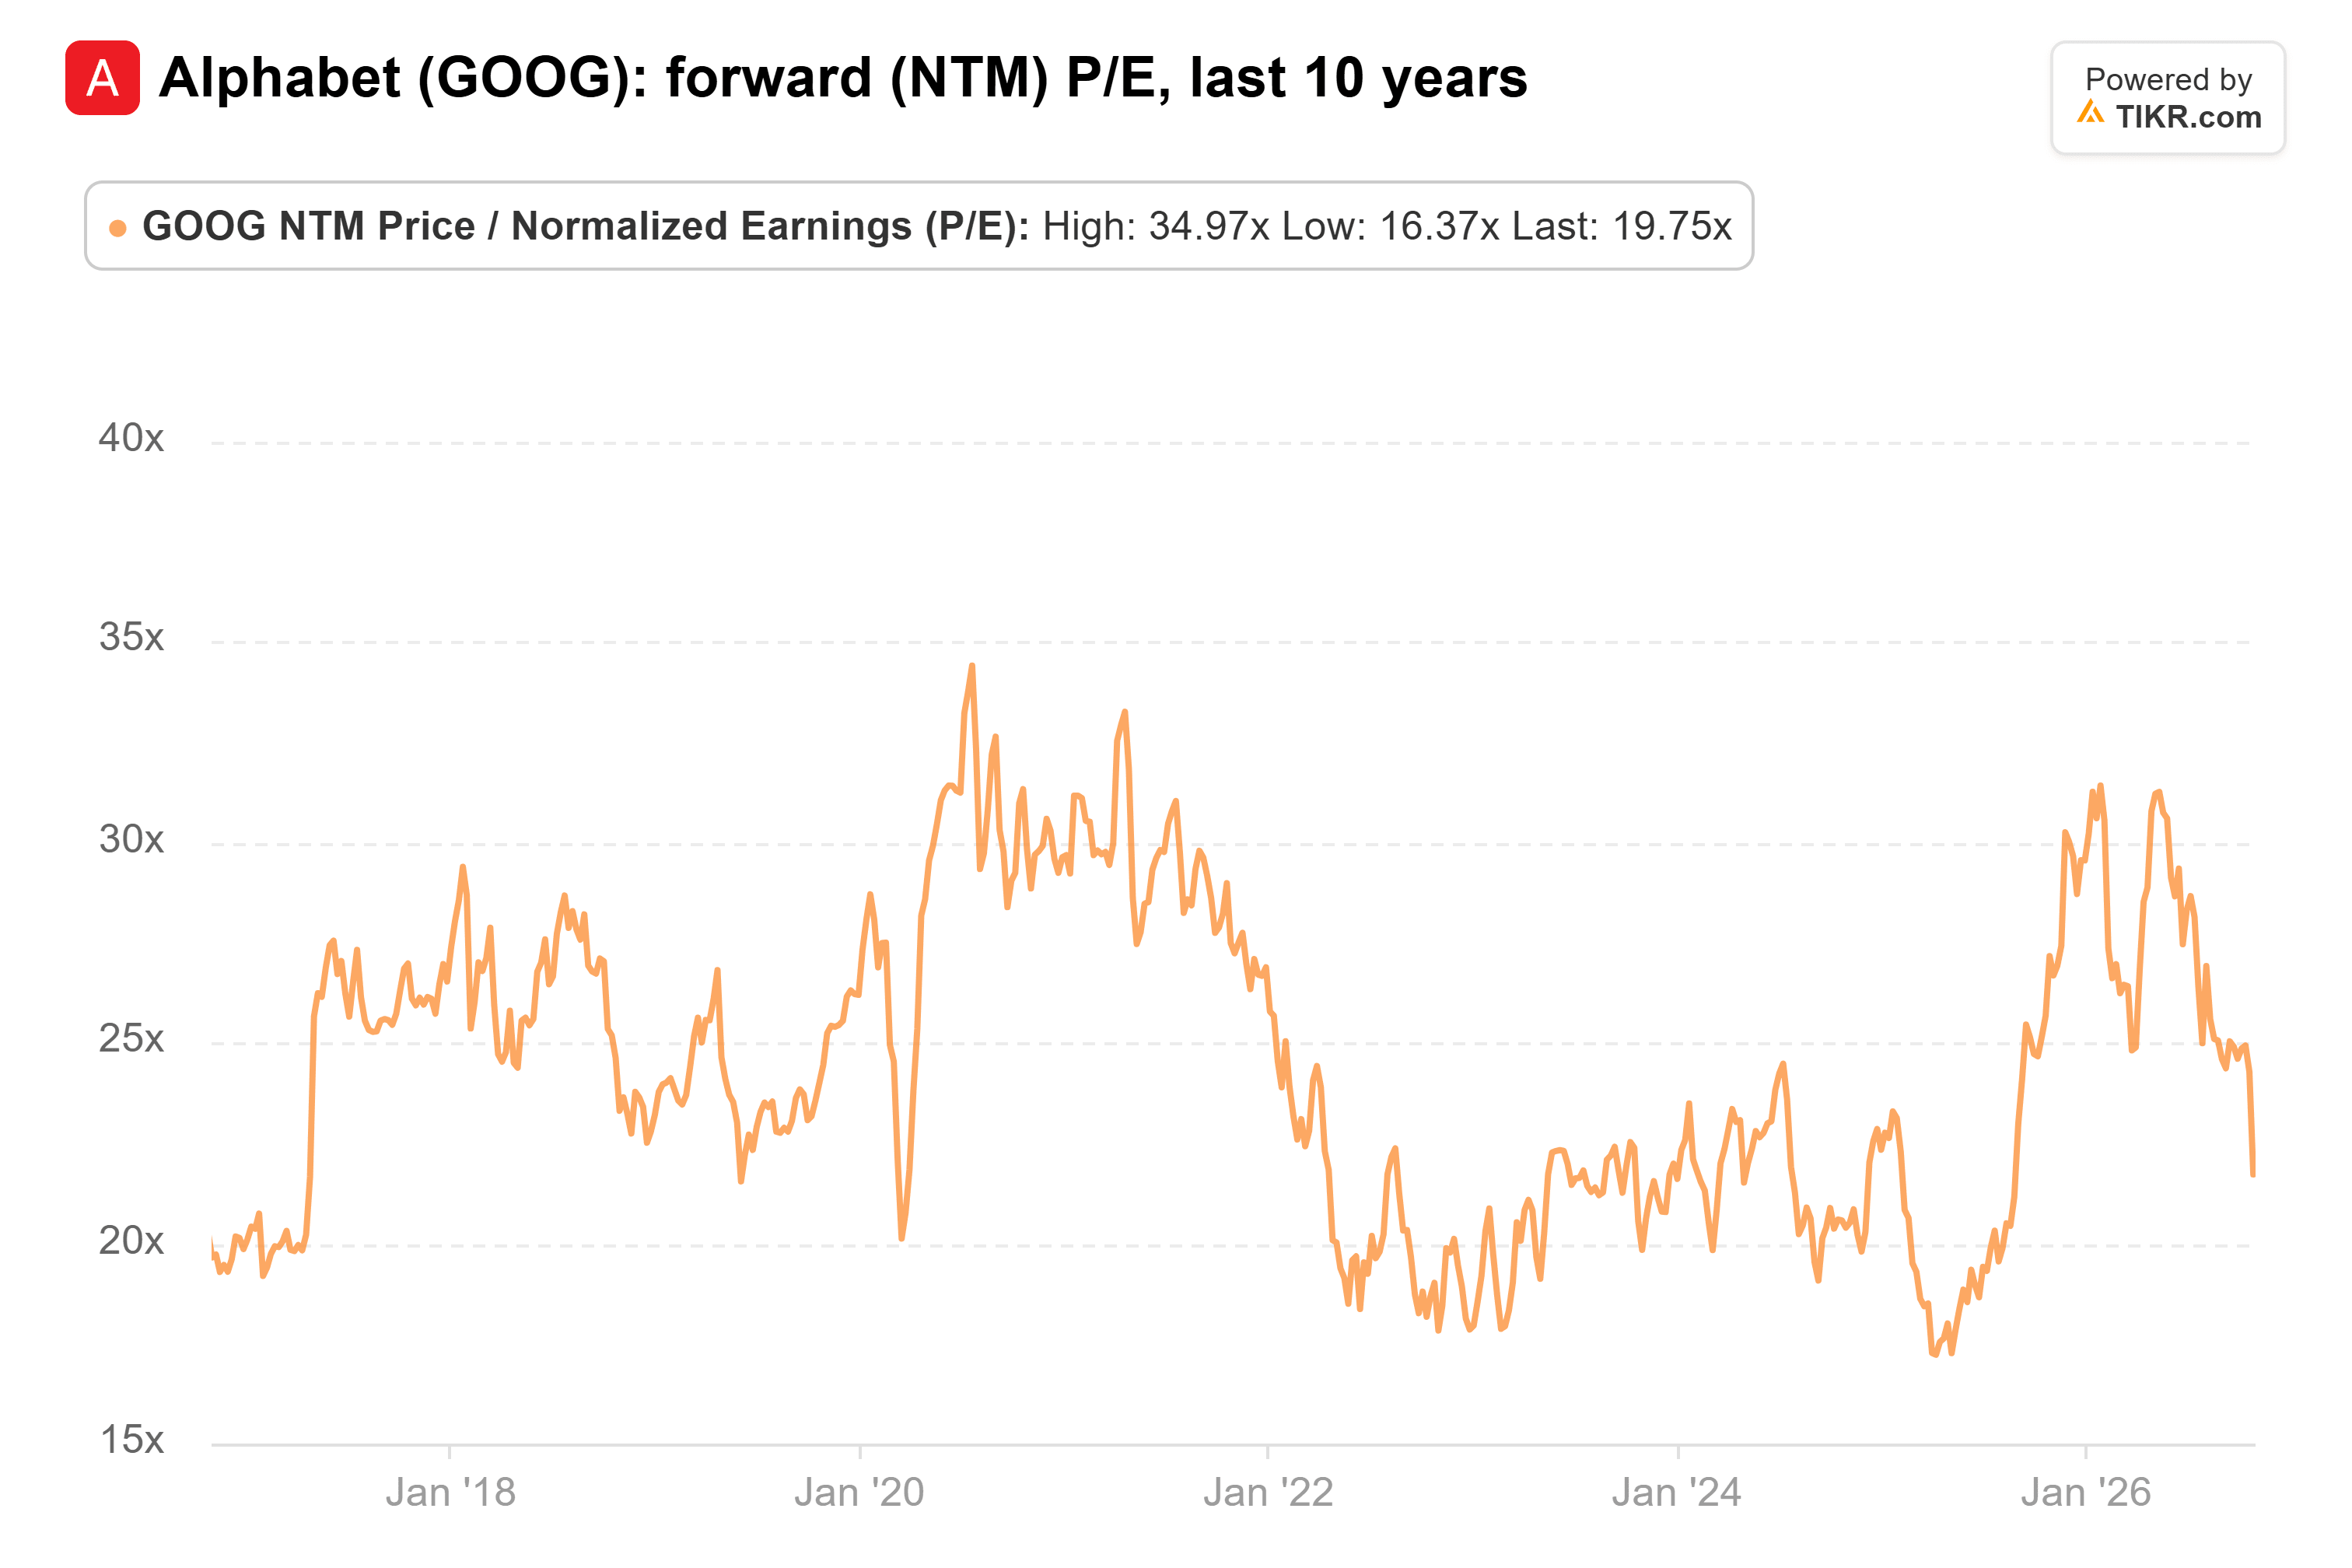
It hit 16x as recently as April 2025, so there’s room for it to get cheaper if search stalls.
Mostaque may be early
I think Mostaque’s first-quarter date is too soon. Search still grew 12% last quarter, and a peak that fast would need a sharp break.
But I think he has the direction right, and Alphabet has more riding on it than anyone because it still makes most of its money from search. The 20x multiple prices in some of that risk. But analysts’ $18.26 for 2028 still assumes search keeps carrying the company, and I’d want to see where search growth settles before calling this a bargain.
Ashkenazi has already said that lapping last year’s search acceleration “will pressure revenue growth in Q4.” Fourth-quarter results in early February will show how much, along with the 2027 capex figure. We’ll know whether Mostaque was right when Alphabet reports its first quarter, likely in late April.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





