Key Takeaways
- ServiceNow fell 27% on October 29, its worst day ever, after guiding fourth-quarter cRPO growth to 18.5% despite a third-quarter beat.
- The company raised its 2026 AI ACV target to at least $1.7 billion, up from $1 billion at the start of the year.
- CFO Gina Mastantuono called the AI-disruption narrative “false,” but the stock sits 32% below its pre-report close at 22.0x forward earnings.
- The January 27 report will show whether cRPO stabilizes once pulled-forward renewals wash out.
ServiceNow (NOW) beat on the quarter it just finished. Investors sold the quarter it hasn’t.
Shares fell 27% on October 29, the worst day in the company’s history. They kept sliding, and a 5.9% drop on Thursday, as the Nasdaq fell 5.5%, left them at $102. That’s 32% below the October 28 close, the day it reported. The one-day drop also tops April’s record fall of 17.8%.
The trigger was one line of guidance. ServiceNow expects fourth-quarter cRPO to grow 18.5%, three points slower than the 21.5% subscription revenue growth it guided for the same quarter.
CFO Gina Mastantuono pushed back on the call, calling the AI-disruption narrative “false.” The tape didn’t care, especially on a day when Alphabet’s results had already reignited fears about AI spending.
Strong quarter, softer handoff
The third quarter itself was clean:
- Subscription revenue rose 21% to $3.99 billion, 50 basis points above the top of guidance
- cRPO grew 21% in constant currency to $13.65 billion, a point above guidance
- Operating margin of 32.5% beat guidance by 150 basis points
Adjusted EPS of $1.00 missed the $1.02 consensus by two cents, while total RPO reached $29.7 billion.
Management blamed the soft cRPO guide on timing. A July 1 pricing change pulled renewals into the third quarter, and public sector demand skewed toward on-premise deals. About 50 basis points of backlog also sits outside cRPO.
On reported revenue, little looks broken…
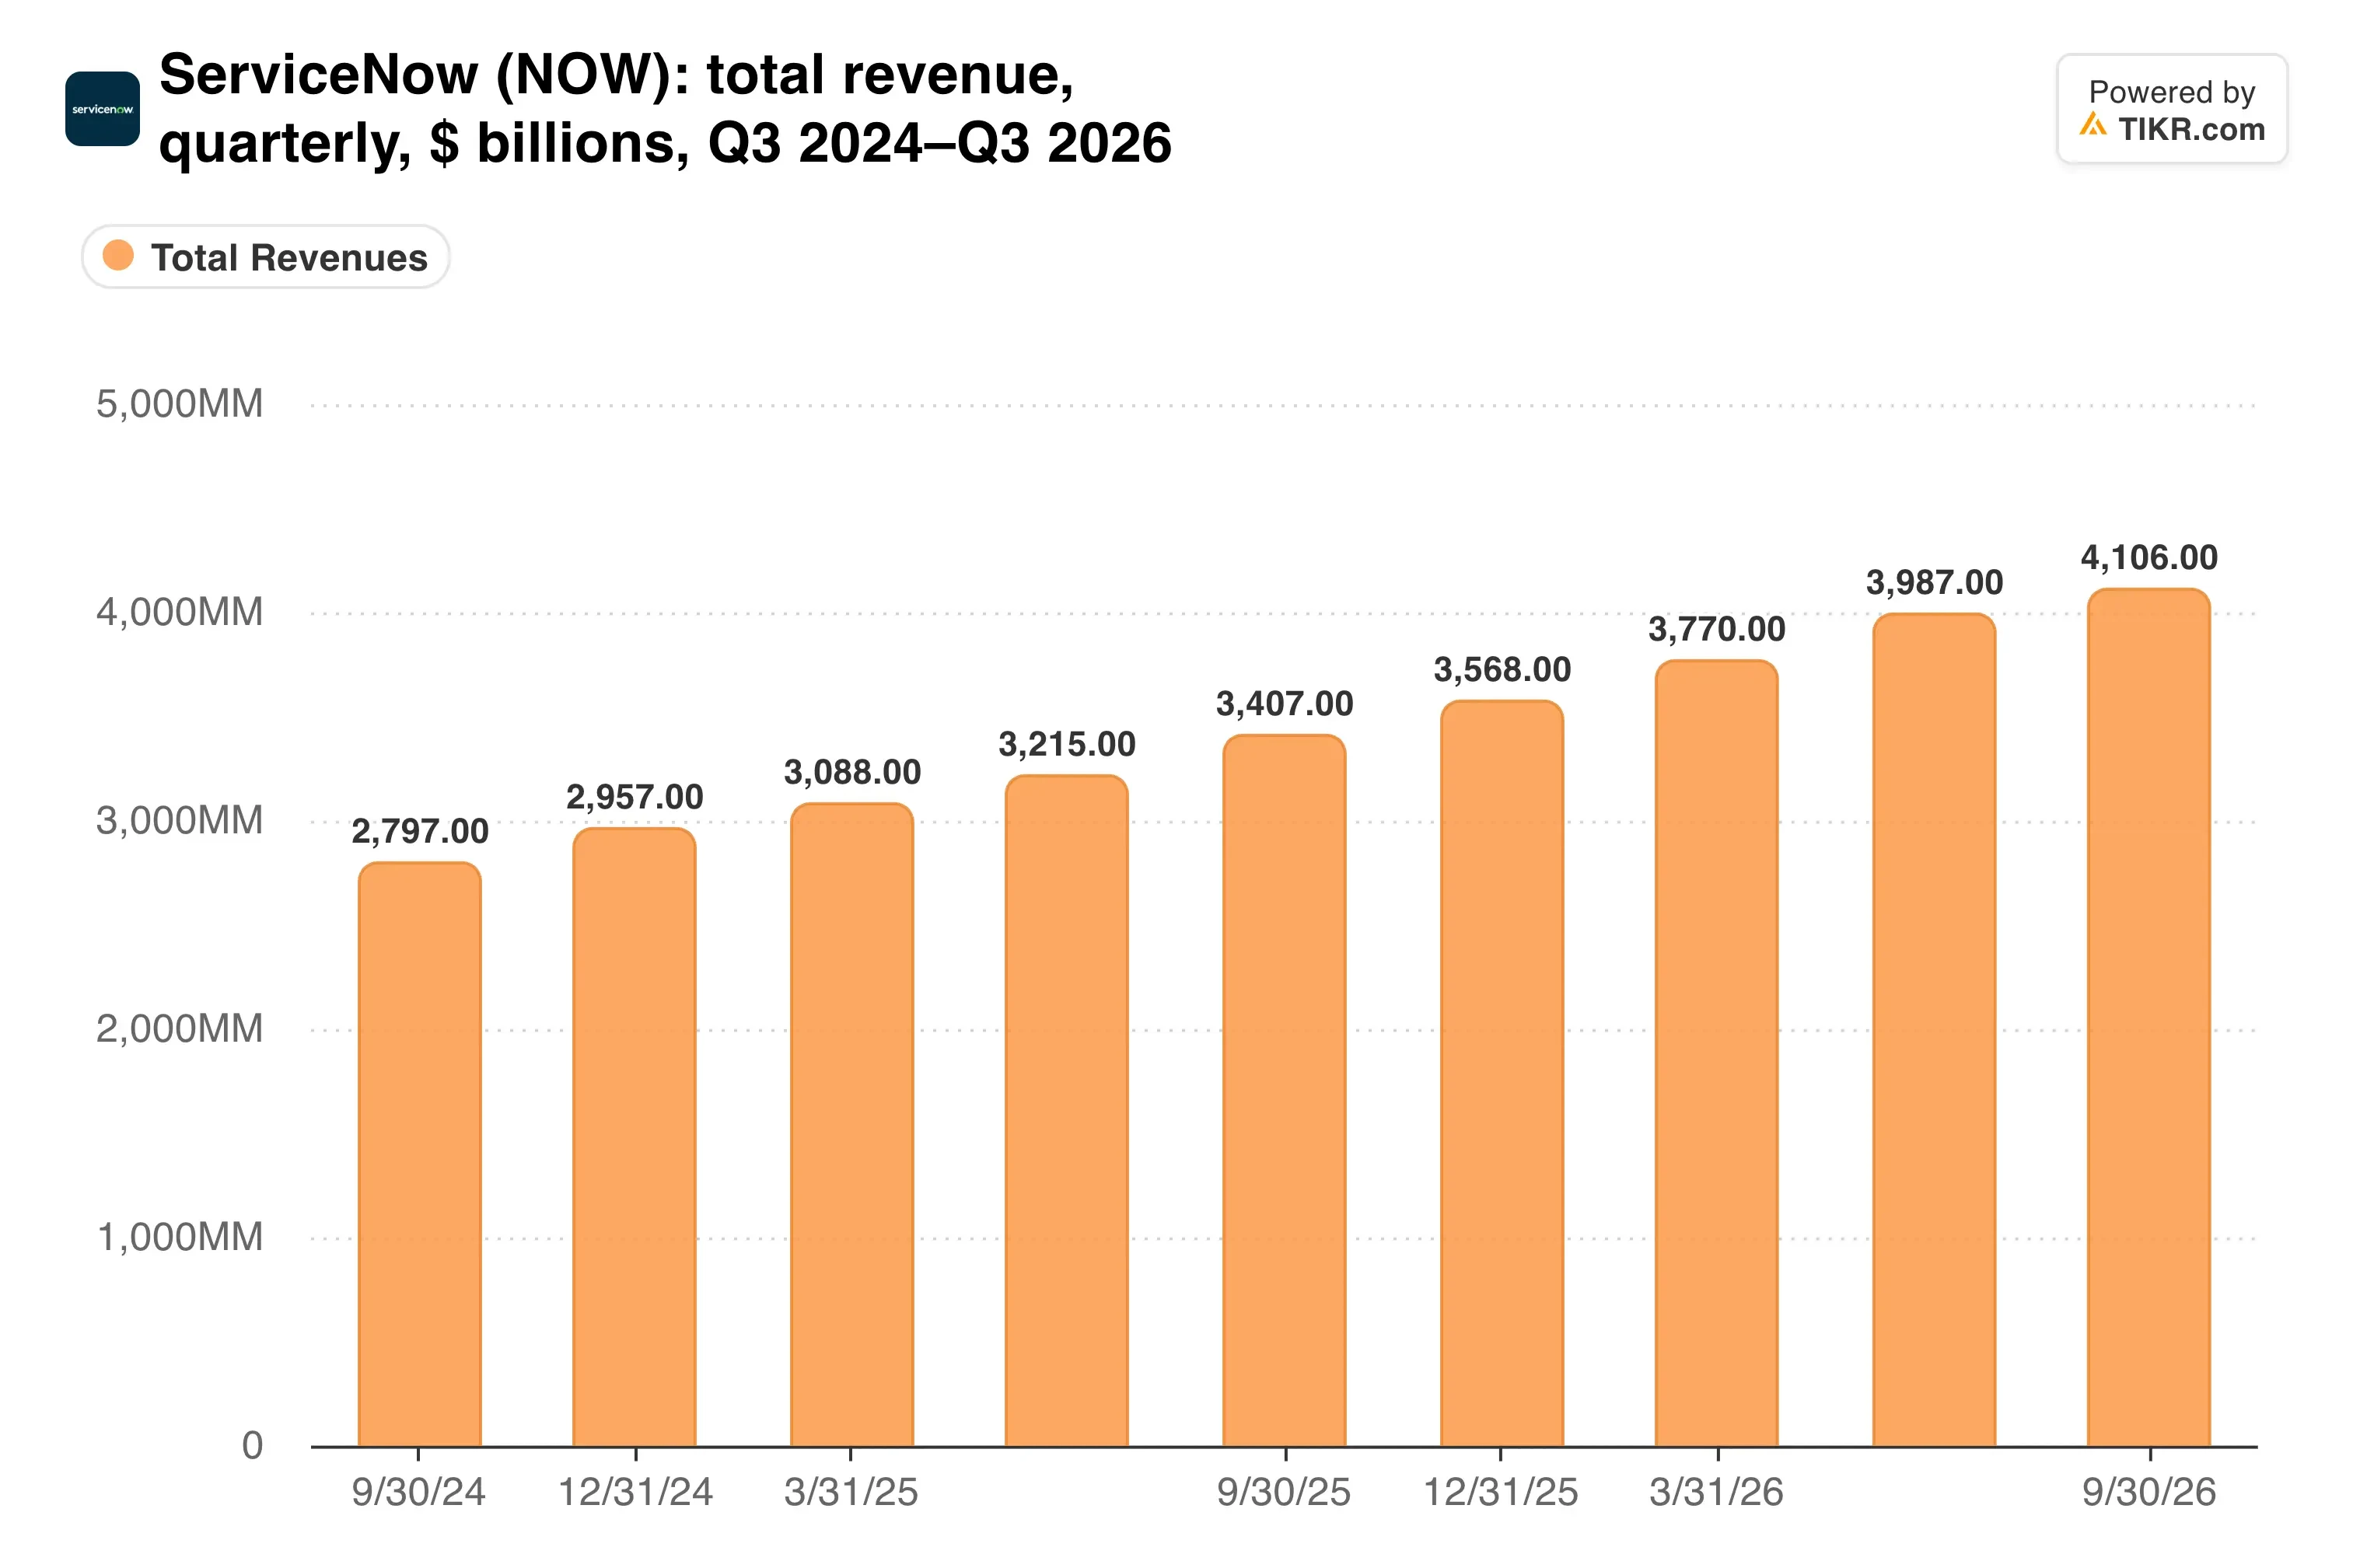
Quarterly growth has held near 20%, so the selloff is about the next four quarters.
The AI numbers keep rising
ServiceNow raised its 2026 AI ACV target to at least $1.7 billion, up from $1 billion at the start of the year. Agentic AI consumption in production rose more than 13 times year over year, and deals spanning five or more AI products grew 8.5 times.
It also deepened ties with OpenAI to embed agents in enterprise workflows. Still, AI-native rivals are scaling fast. Sierra, a private startup, added $150 million of ARR in a single quarter, almost 9% of ServiceNow’s full-year AI target.
Cash is the part of the guide that improved.

Management lifted its 2026 free cash flow margin target to 36% from 35%. Paired with 21% subscription growth, that’s a rule-of-57 profile.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
The multiple already reset
At $102, ServiceNow trades at 22.0x forward earnings and 14.6x forward EBITDA. The average target of $155 implies 51% upside, although many targets haven’t caught up to the selloff yet.
Few large software names have de-rated this hard:

The stock now sits closer to its 52-week low of $81 than its high of $176, for a business still guiding to 21% subscription growth.
The risk is that cRPO is telling the truth. If the slowdown reflects AI agents eating into seat-based renewals, the pull-forward explanation won’t hold for long.
My take: The selloff looks bigger than the guidance. A three-point gap between cRPO and revenue growth, with a specific pricing explanation attached, doesn’t justify losing nearly a third of the market value in a week. I’d start a small position here and add only once the backlog confirms the story.
The January 27 fourth-quarter report is the test. cRPO needs to land at or above 18.5%, and the first 2027 subscription guide must hold near 20%. ServiceNow also presents at BMO’s technology conference on November 12, which may offer an early read.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!