Key Takeaways
- Scott Galloway said on Prof G Markets that Alphabet and Microsoft would “still be fine” even if AI proves as overhyped as the railroads, while neoclouds like CoreWeave and Nebius are “levered trades to AI.”
- Advertising brought in $294.7 billion of Alphabet’s 2025 revenue, and analysts expect its normalized EPS to grow from $10.81 in 2025 to $18.13 in 2028.
- The catch is the spending: Alphabet’s capex has topped its operating cash flow for two straight quarters, and it has borrowed and sold stock to cover the gap.
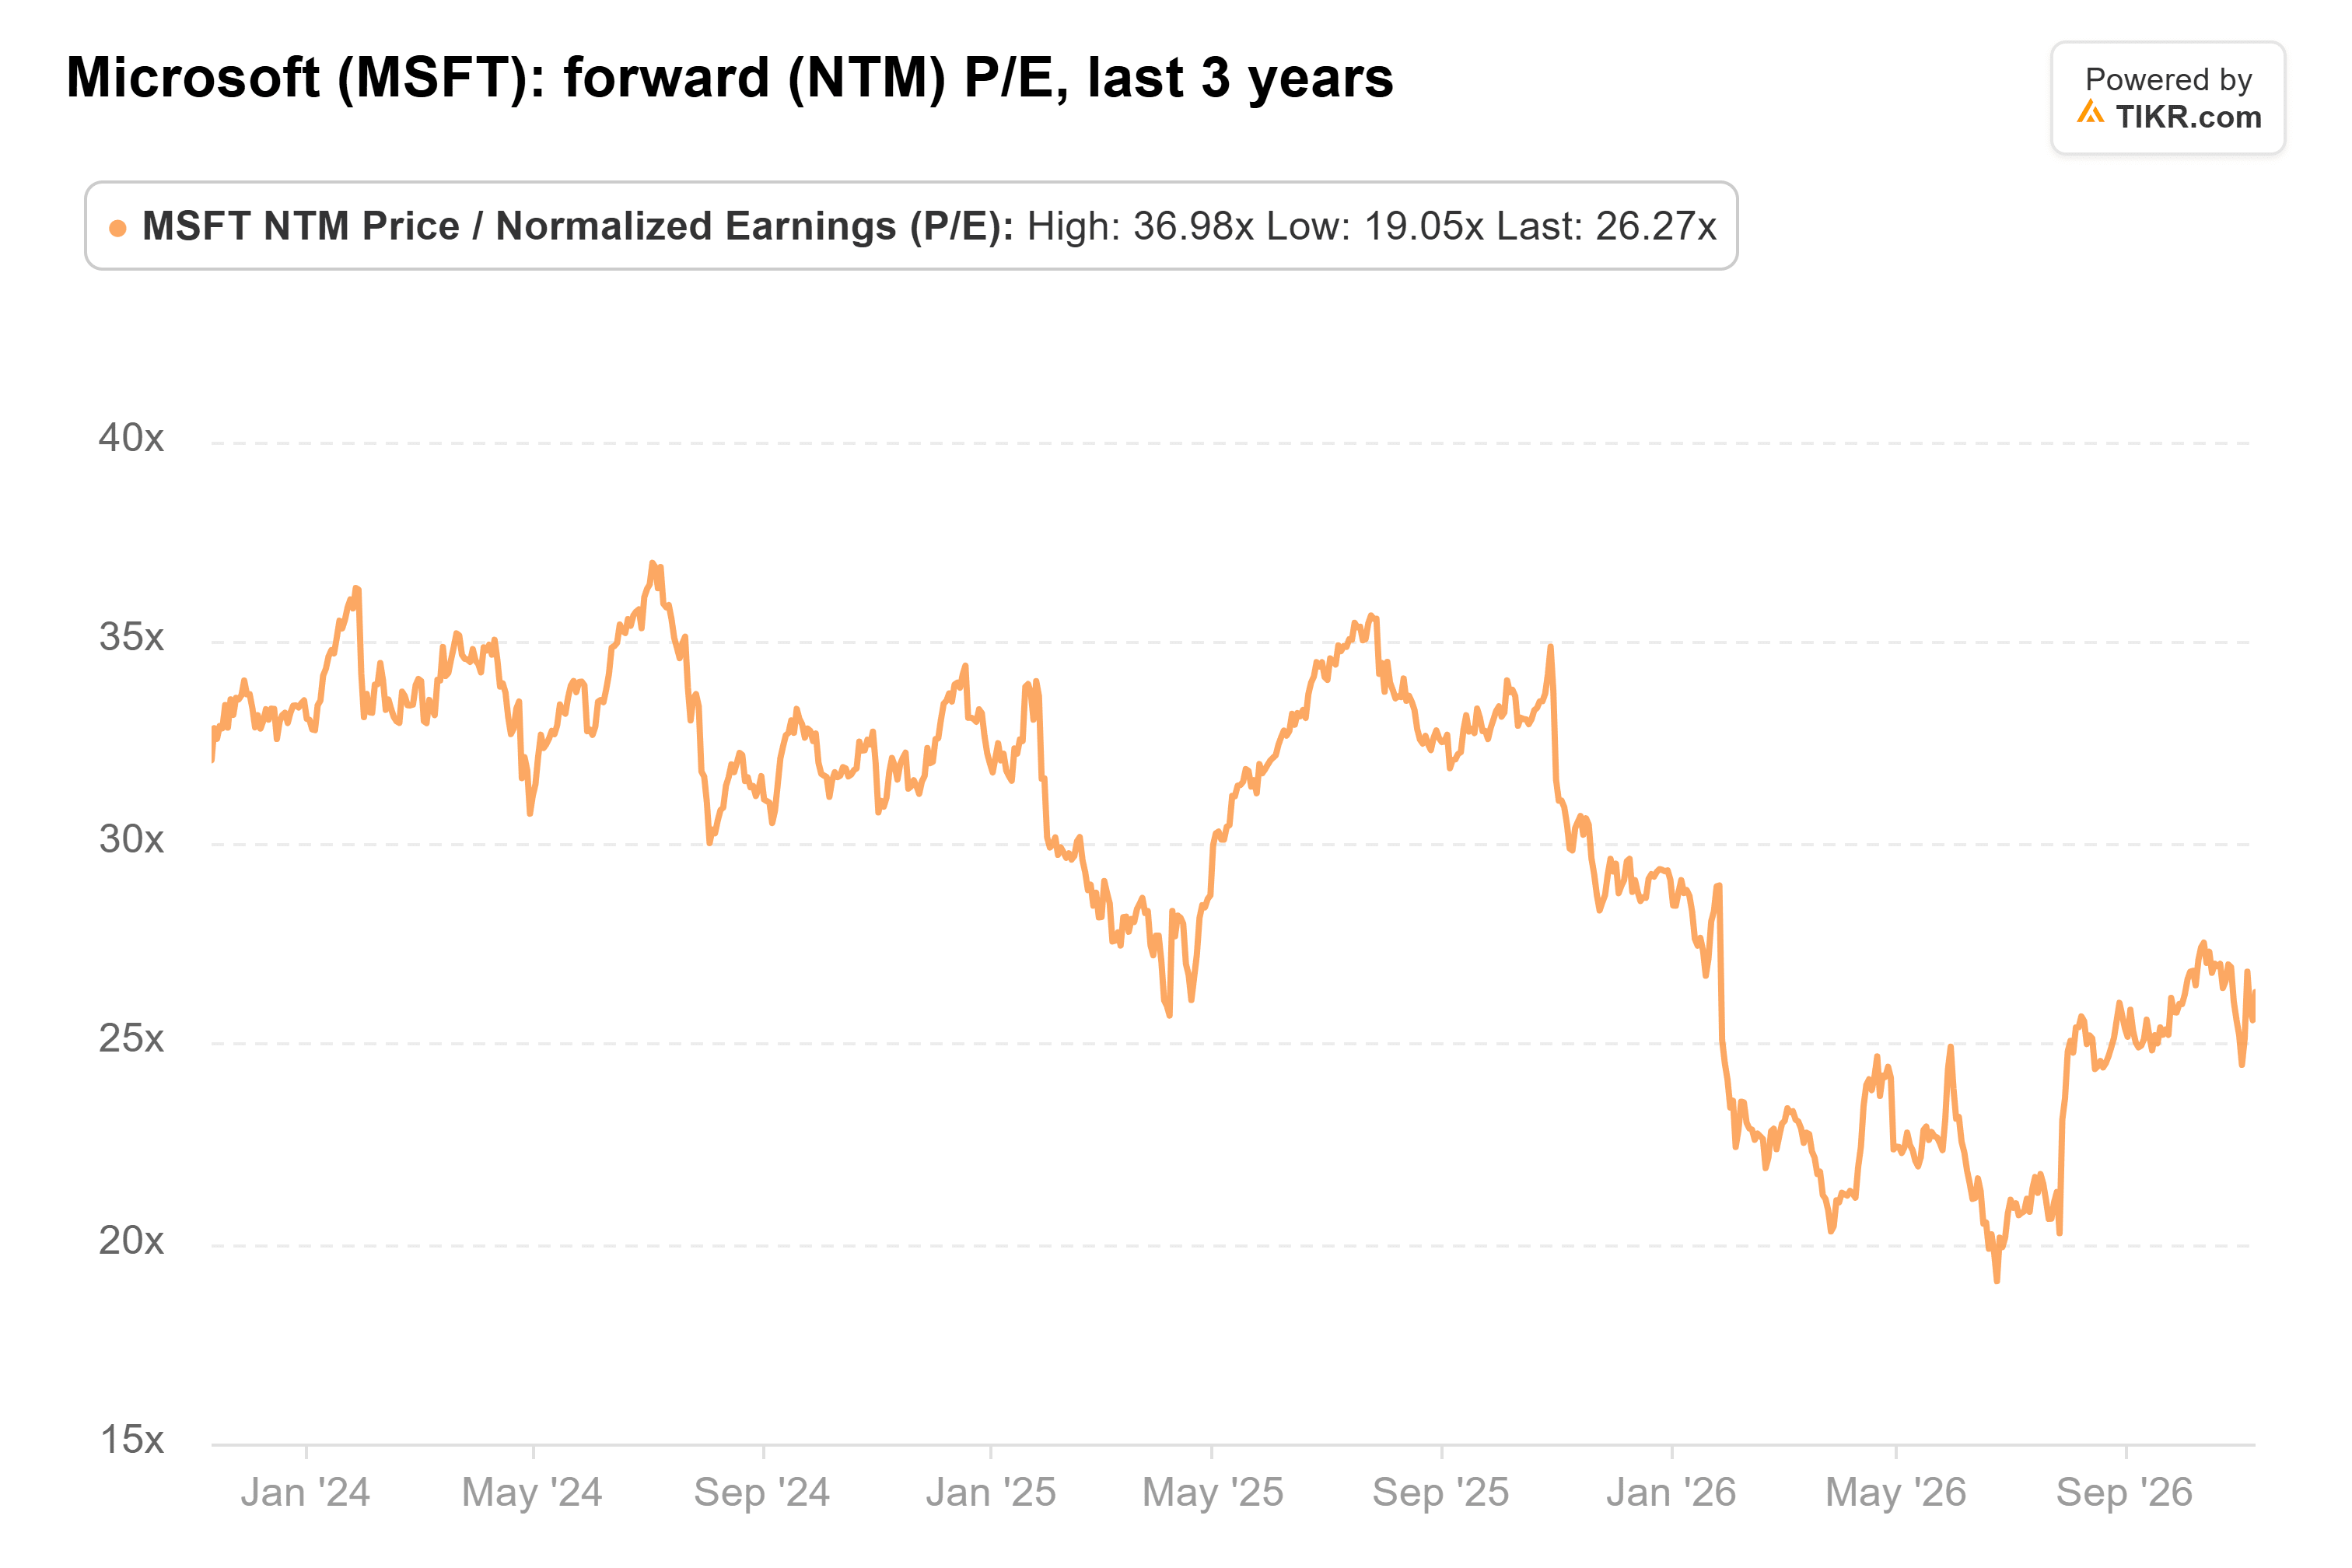
- A bust would leave both companies standing but cost them their valuation multiples, and Microsoft’s forward P/E has already fallen to 26x.
Voters just turned on data centers. All but one of the 41 local ballot measures on them in last week’s midterms went against the industry, per Ballotpedia, and AI stocks have been sorting themselves into winners and losers ever since.
Scott Galloway has a simple read on who’s losing. On Monday’s episode of Prof G Markets, he called the neoclouds “basically levered trades to AI,” moving about three times as far as AI does in either direction. Think CoreWeave (CRWV) and Nebius (NBIS).
In his view, Alphabet (GOOG) and Microsoft (MSFT) are a different story:
“AI could end up being vastly overhyped and be like the railroads, and they would still be fine. People are still going to be buying Google search ads and YouTube ads and PowerPoint.”
That’s about as bearish as you can get on AI and still want to own the stocks.
The ads are still paying the bills
Galloway has a point about the ads. Advertising brought in $294.7 billion of Alphabet’s $402.8 billion of revenue in 2025, and that’s the business he expects people to keep paying for whatever happens to AI. Analysts expect Alphabet’s normalized EPS to keep climbing too, from $10.81 in 2025 to $18.13 in 2028:

And those estimates already have consensus depreciation nearly quadrupling, from $21.1 billion in 2025 to $77.9 billion in 2028, as all that AI hardware lands on the income statement.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Alphabet is spending more than it brings in
The spending is the part that should make shareholders nervous. Creative Planning’s Charlie Bilello noted on X that big tech is moving “from asset-light to asset-heavy business models,” with capex at record highs of 39% of revenue at Microsoft and 34% at Alphabet. Alphabet’s capex has more than tripled since late 2024 and has topped its operating cash flow for two quarters running:
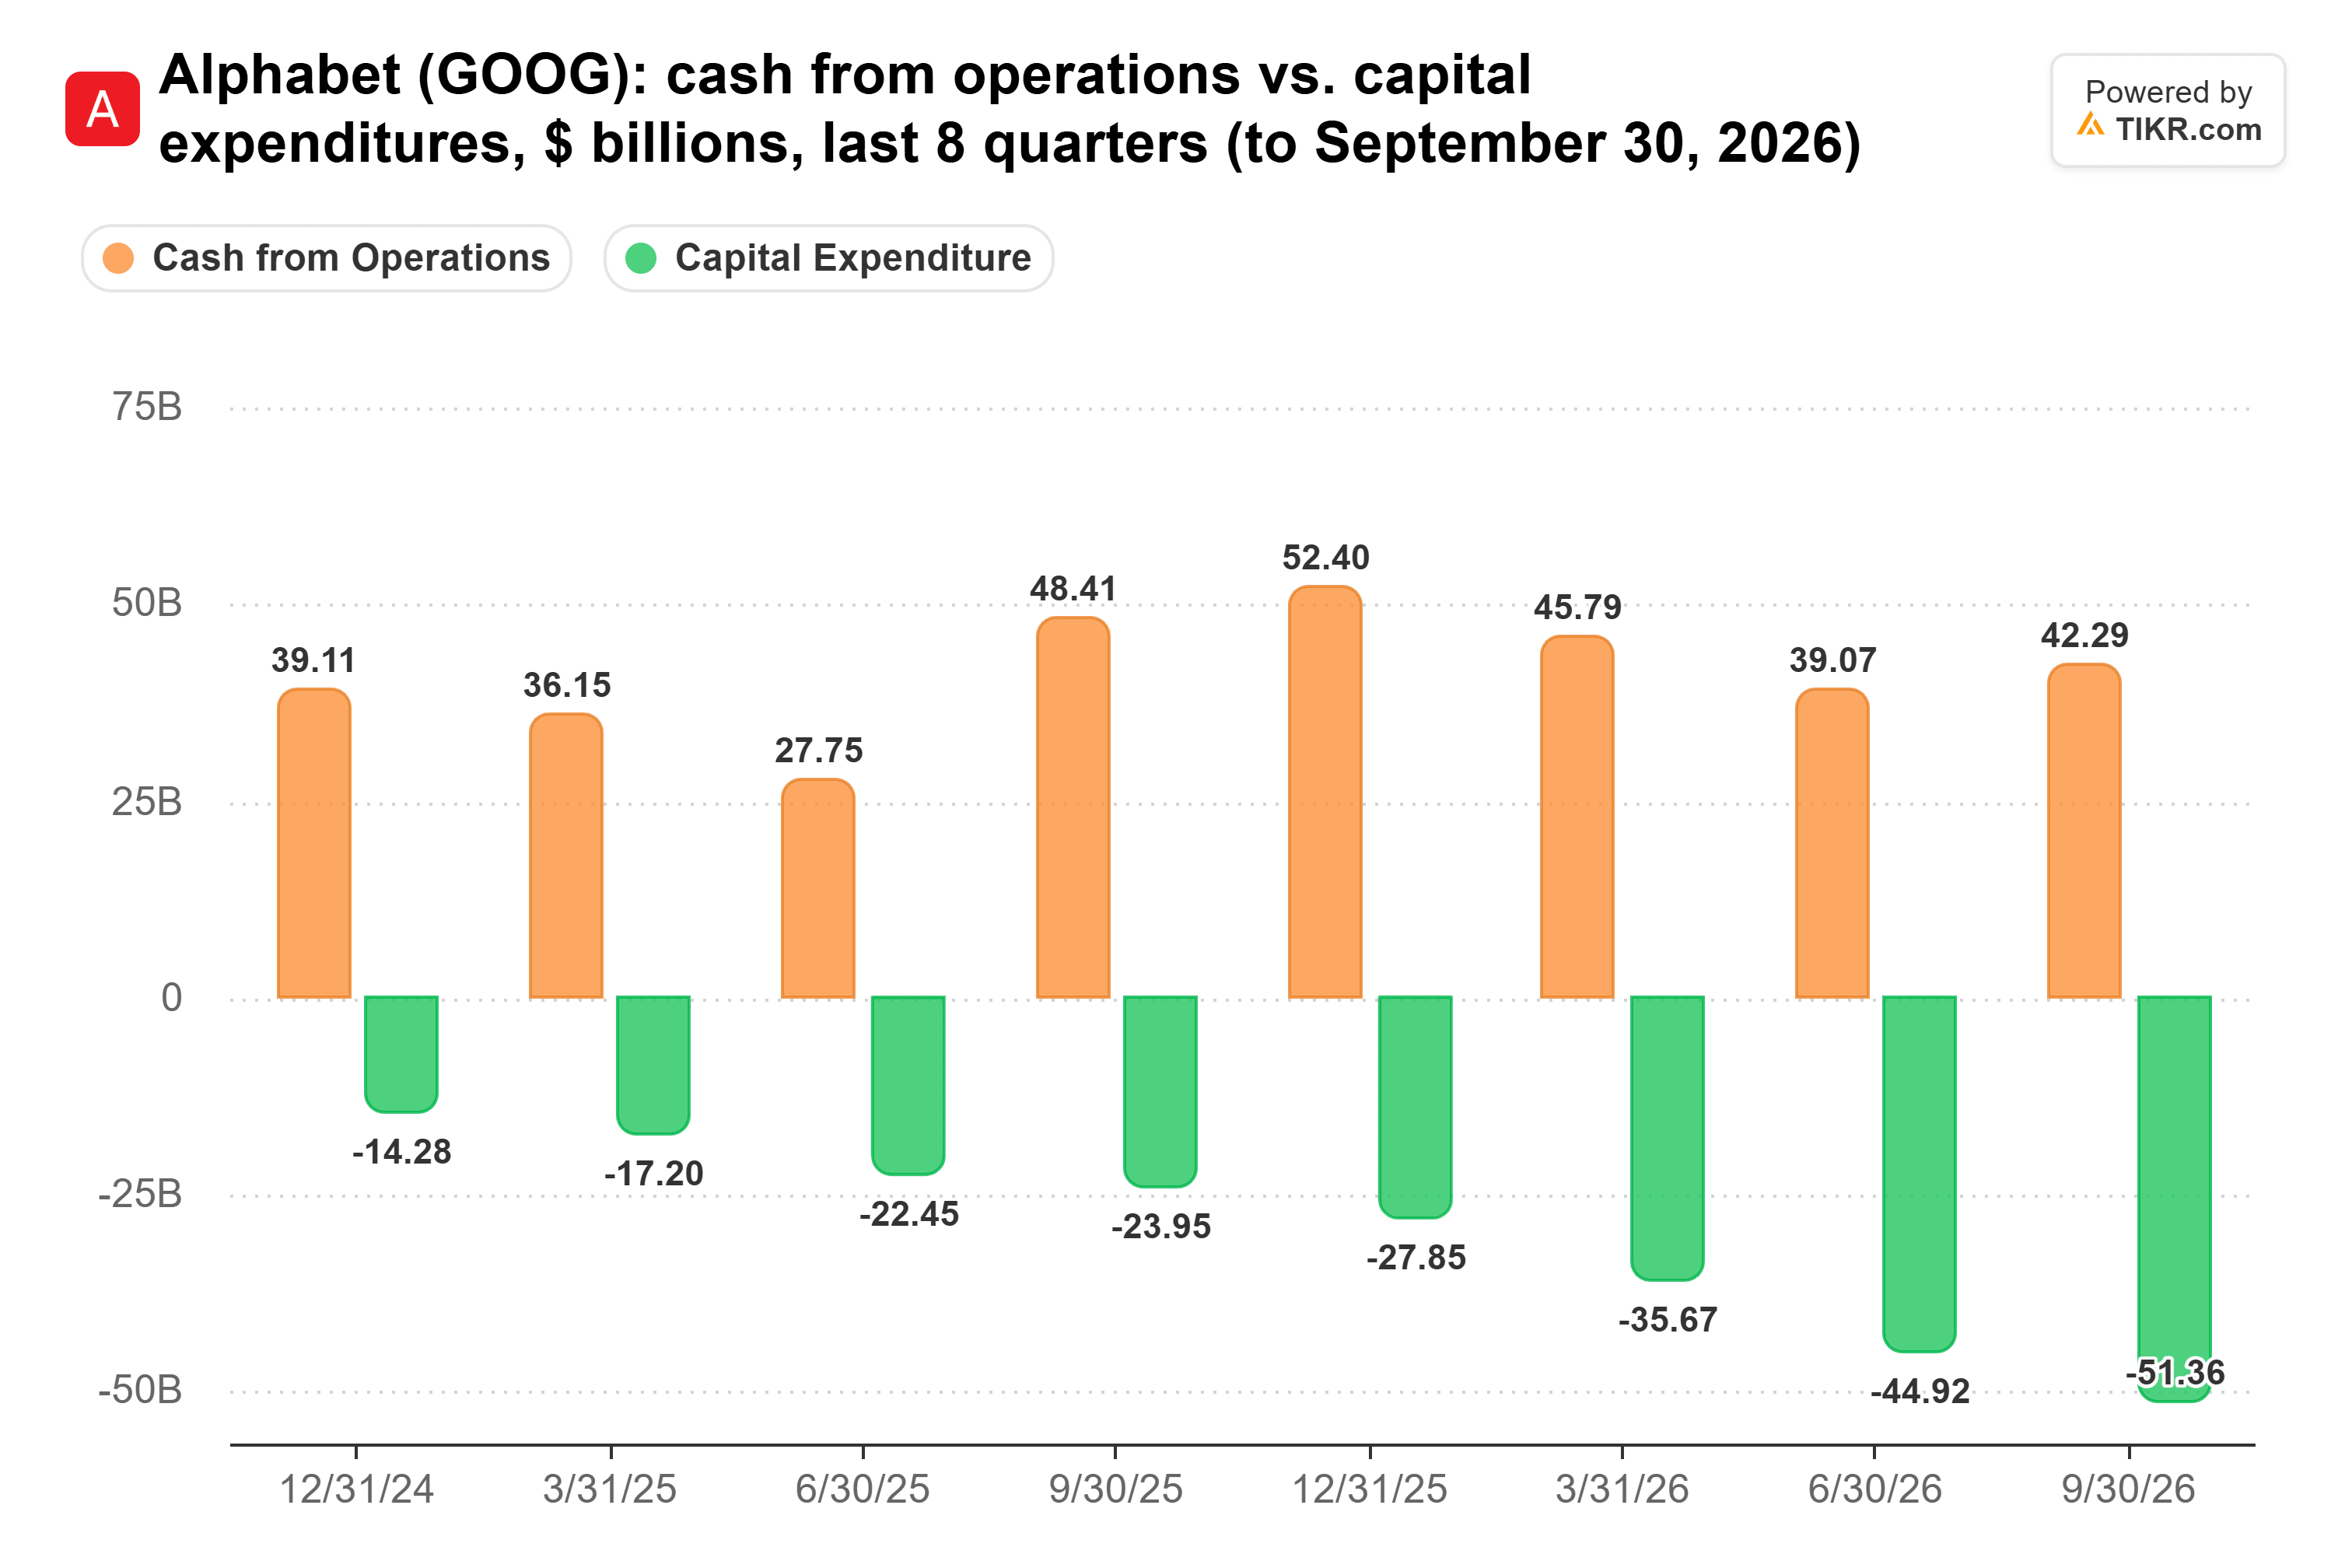
That left free cash flow at negative $9.1 billion in the third quarter (a $5.2 billion EU fine payment was part of the hit). To keep building, Alphabet doubled its long-term debt to $101.1 billion at face value in the first half of 2026, sold $49.6 billion of new stock in June, and hasn’t bought back a share this year.
And Alphabet can’t switch off all of that spending in a bust. It had $707.0 billion of fixed or guaranteed commitments at June 30, 2026, mostly long-term supply agreements for its infrastructure.
A bust would show up in the multiple
Still, Galloway is right about the difference. If AI falls short, Alphabet can slow the building it hasn’t committed to, and it brought in $42.3 billion of operating cash flow last quarter. For CoreWeave and Nebius, AI computing is the whole business, so a bust would hit their revenue as well as their spending plans.
For Alphabet and Microsoft shareholders, the damage would come through what investors are willing to pay for those earnings. Microsoft’s forward P/E has already fallen to 26x, down from 37x in July 2024 and below its 3-year average of 30x:
The way I see it, a railroad-style bust would cost Alphabet and Microsoft their premium multiples and a few years of free cash flow, and it would cost CoreWeave and Nebius a lot more than that. So if you want AI exposure that can survive the hype fading, the giants are the safer way to get it.
Of course, Alphabet’s building isn’t slowing yet. Analysts expect its capex to reach $308.0 billion in 2027, and the company’s own 2027 figure could come with its fourth-quarter results in early February.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!