

Key Takeaways
- Sandisk fell 14% today after a top phone chipmaker said its handset chip revenue dropped 26%, citing memory prices.
- That report confirms what Sandisk’s own phone and PC numbers already showed.
- Micron and Seagate fell too, though phones matter far less to Seagate’s hard drives.
- Sandisk trades at its lowest forward P/E of the past year, while analysts still expect its earnings to more than triple in fiscal 2027.
Sandisk (SNDK) is down 14% today after a top phone chipmaker said its handset chip revenue fell 26% to $5.14 billion in the quarter to Sept. 27.
Memory stocks sold off with it: Micron (MU) is down 10%, and Seagate (STX) has dropped 12%.
Memory gets the blame
On its fourth-quarter call, the chipmaker said that handset revenue “reflected the impact of industry-wide memory dynamics on the global smartphone market.” (Losing Apple hurt too.)
Memory has gotten expensive enough to shrink the phone market.
Sandisk’s own numbers were already showing it. In the quarter to Oct. 2, its Edge revenue, from phones, PCs and cars, rose 320% from a year earlier on 20% fewer exabytes shipped. Price did all the work, and Edge and consumer products made up 56.5% of revenue.
Wall Street hasn’t cut yet
Analysts still expect Sandisk’s normalized EPS to more than triple to $227.80 in fiscal 2027:
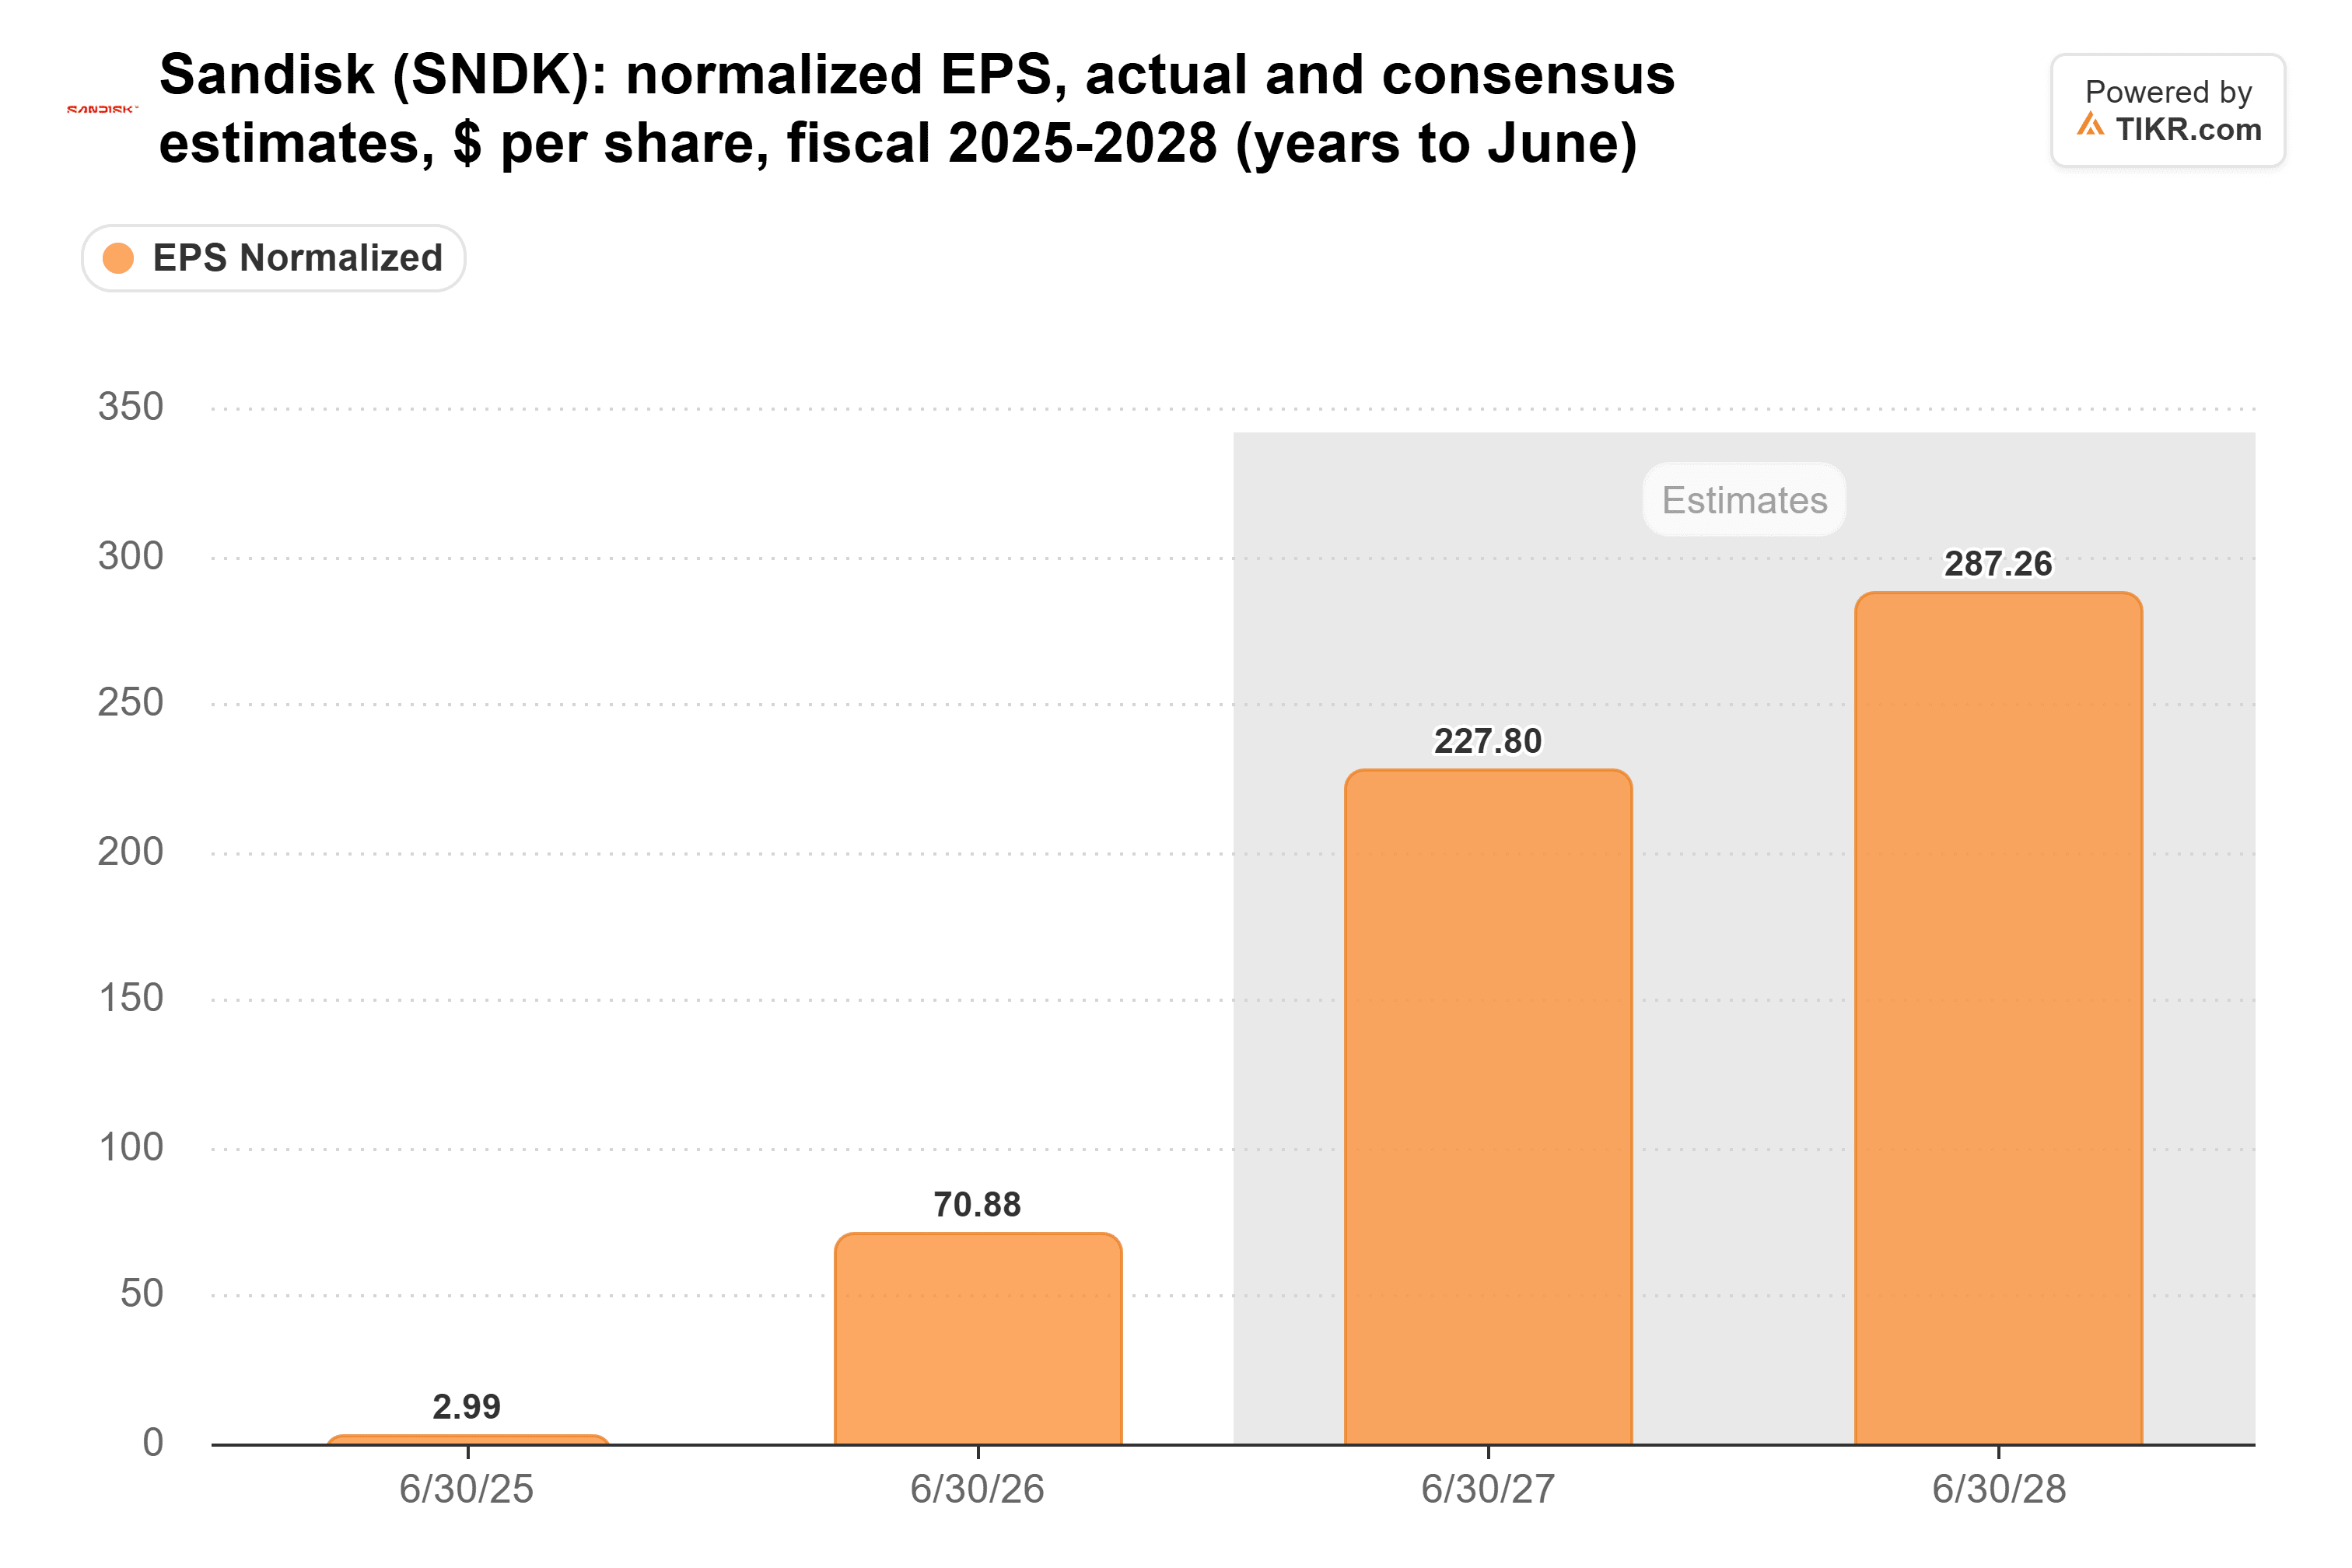
The quarter at Qualcomm (QCOM) gives them reason to trim the Edge side. The cushion is Sandisk’s multiyear contracts. Management says their floor prices still yield a gross margin of about 80%, near the 85.1% adjusted margin it just reported.
Sandisk trades at 4.4x forward earnings, the low of its past year and well under its 10.8x average:
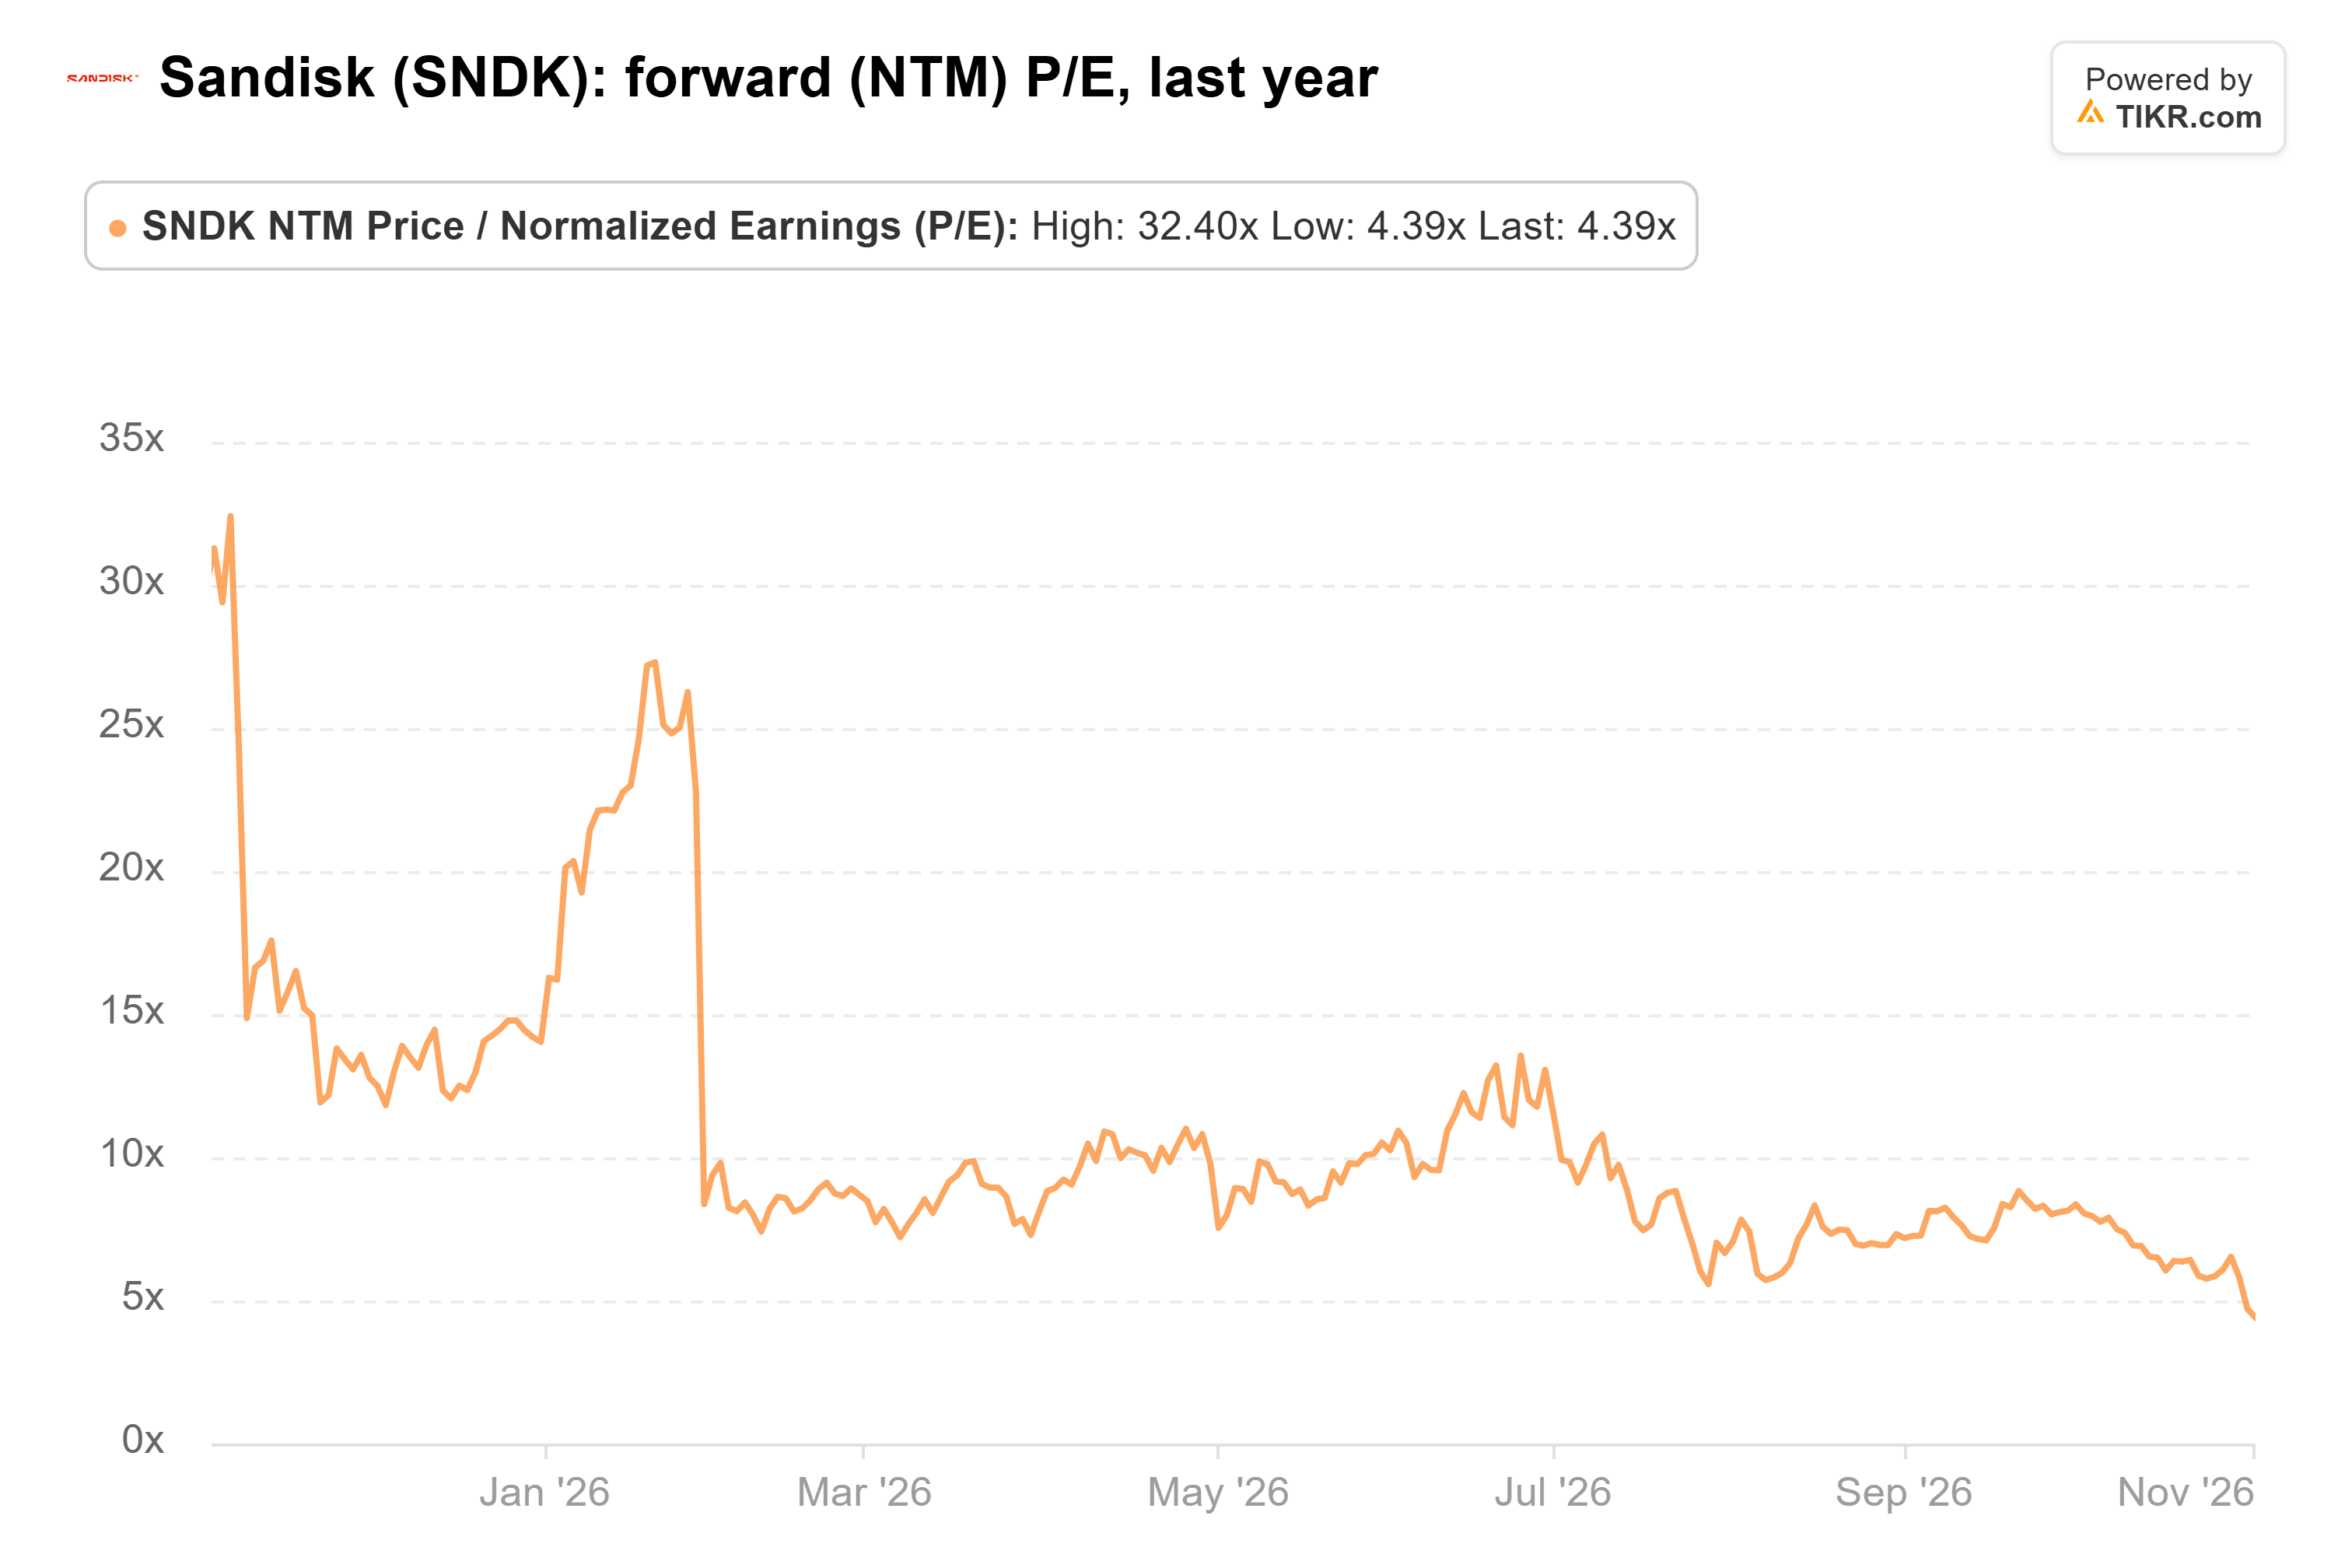
At today’s price, it’s even lower.
TIKR tracks 25 analysts on Sandisk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
Micron sells into the same phones
Micron’s Mobile and Client unit, which sells to phone and PC makers, brought in $13.11 billion of its $54.23 billion of revenue in the quarter to Sept. 3. Its report in mid-December will show whether handset makers are still paying up.
Seagate’s drop is harder to explain. Phones don’t run on hard drives, and Seagate guided fiscal second-quarter revenue to $4.8 billion, up from $4.2 billion last quarter. To me, that looks like investors selling all of storage at once.
A lot of bad news is in the price
Qualcomm’s warning is real, but Edge takes the biggest hit, and data center went from 11.7% of Sandisk’s revenue to 43.5% in a year. Investors are also pricing in a much steeper drop in earnings than analysts have. The way I see it, the selloff has run ahead of the damage.
Of course, Kioxia, Sandisk’s joint-venture partner, said last week its NAND price gains are slowing. If flash prices have peaked, those estimates have a long way to fall. Sandisk reports its fiscal second quarter in late January, after its 8-for-1 split on Nov. 20. That report will show whether it can still raise prices.
So what is Sandisk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



