Salesforce (CRM) shares rose about 2.4% by late morning on Monday, October 12, according to Reuters, after Bank of America analyst Tal Liani upgraded the stock two notches, from Underperform to Buy. He raised his price target to $285 from $160, about 24% above Friday’s close of $229.13.
Going straight from BofA’s lowest rating to its highest is rare. Liani didn’t just adjust his numbers. He reversed his view on AI.
BofA Changed Its Mind on AI
Liani had worried that AI agents would let customers bypass software vendors. After talking with chief information officers, he now thinks large companies won’t replace the platforms that hold their core data and workflows. “If anything, AI should deepen dependence on these platforms,” he wrote.
His evidence is Agentforce. Its annual recurring revenue exceeded $1.5 billion in fiscal Q2 2027, up more than 240% year over year, though Salesforce widened the metric that quarter to include Slackbot and Headless 360. About half of Agentforce bookings came from customers buying more usage credits.
The Discount Is the Story
The new target rests mostly on a higher multiple. Liani’s fiscal 2028 revenue growth forecast moved only to 9.9% from 9.5%. But he now applies an enterprise-value multiple of 16 times estimated calendar 2027 free cash flow, up from 9 times.
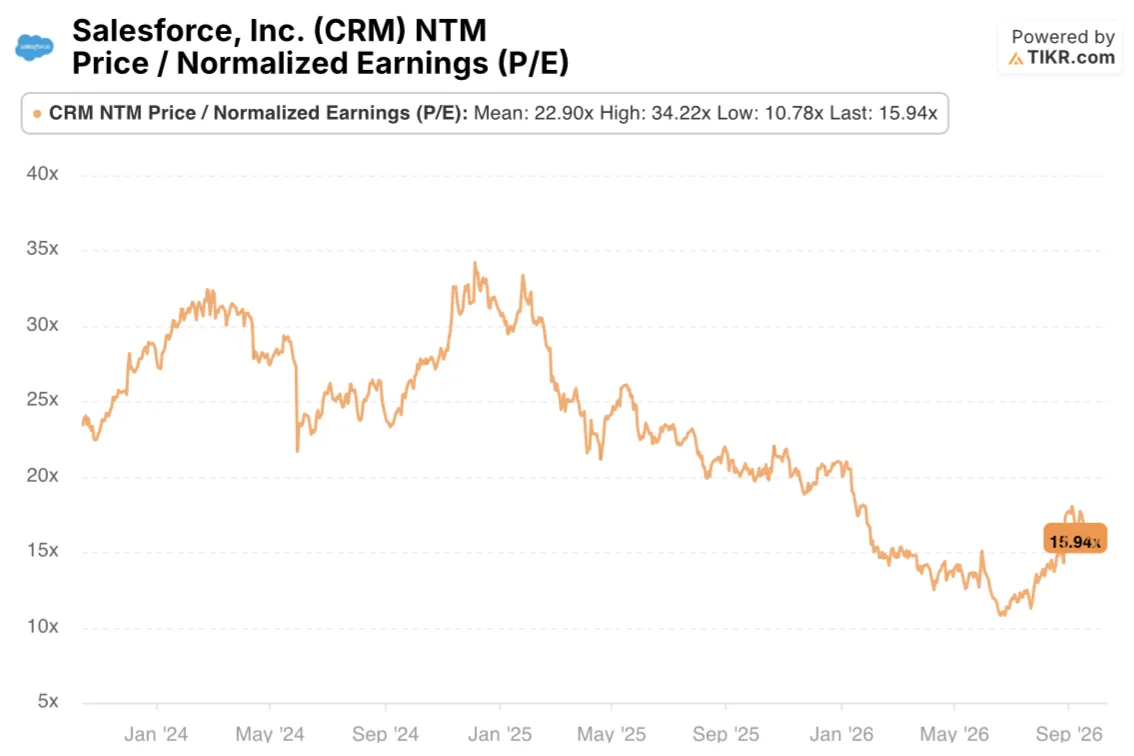
TIKR data shows how far the stock had already de-rated. Salesforce trades at 15.94 times forward normalized earnings, against a three-year average of 22.90 times and a peak of 34.22 times around the start of 2025. It bottomed at 10.78 times in mid-2026. Even at BofA’s $285 target, the multiple would stay below that average.
Two Ways to Read the Salesforce Upgrade
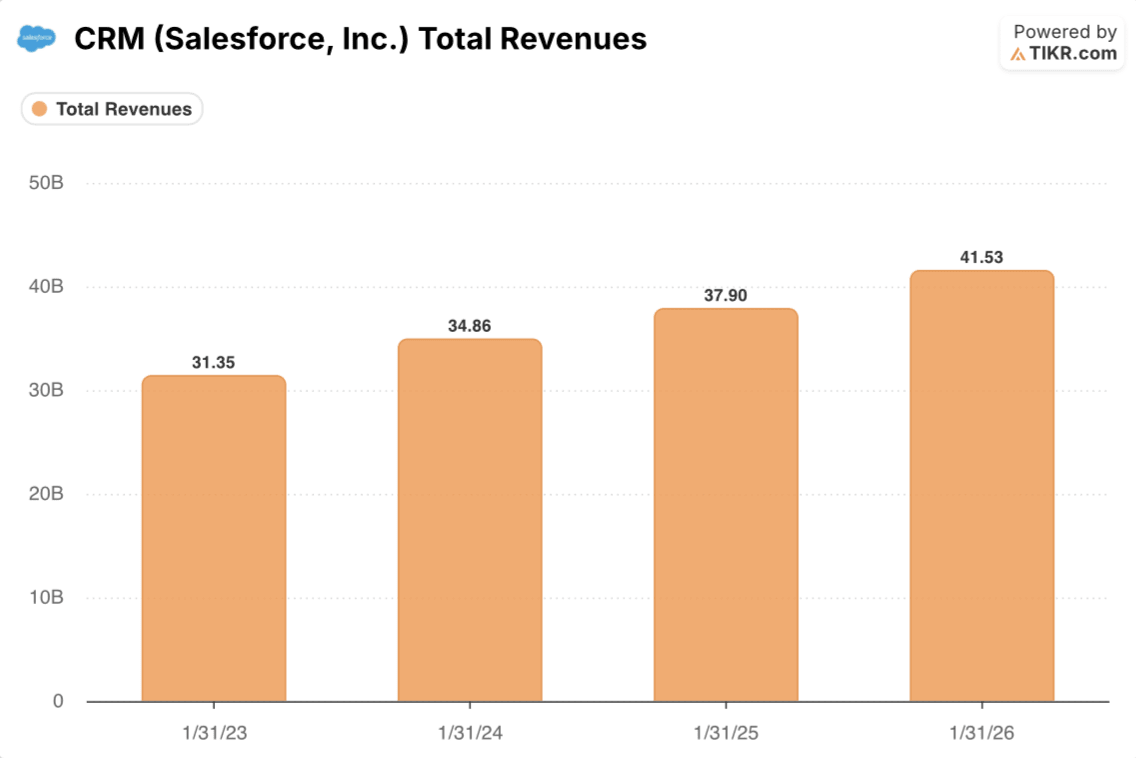
The bull case is that the stock is priced for disruption that hasn’t shown up in the numbers. Revenue grew 9.6% in fiscal 2026 to $41.53 billion and reached $43.94 billion over the last 12 months. If AI makes customers more dependent on Salesforce, a multiple this far below average is too cheap.
The bear case is that Agentforce is still small. Its roughly $1.5 billion annual recurring revenue figure is equivalent to about 3.4% of Salesforce’s trailing revenue, but that comparison measures scale—not Agentforce’s actual contribution to reported sales. The stock has already bounced hard off its mid-2026 low.
The argument reaches beyond Salesforce. ServiceNow (NOW) faces the same fear that AI will replace software, so if CIOs keep their core platforms, it benefits too.
BofA’s reversal makes the valuation case easier to argue, but the AI revenue behind it is still hard to see in the reported numbers. Until Agentforce lifts Salesforce’s total revenue growth above the 9.6% it managed in fiscal 2026, the stock has a case for a higher multiple, not a full return to its 22.90 times average.
Want to see where Salesforce’s multiple sits today? Pull up the same P/E history and revenue charts on TIKR for free and compare them with ServiceNow’s. Learn more here.
So what is Salesforce stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CRM stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Salesforce, Inc. for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!