Rollins (ROL) shares were down about 7% before Thursday’s open (trading at about $31) after the Orkin owner’s third-quarter results missed on revenue and earnings. Revenue rose 6.2% to $1.09 billion, short of the $1.11 billion analysts expected, and adjusted EPS of $0.34 came in a penny light.
Management blamed customer acquisition. The income statement points at insurance. And the same morning, rival Rentokil Initial (RTO) jumped about 8% on a $200 million buyback, which makes the gap between the two stocks the more useful question.
Where Rollins’ Margin Actually Went
CFO Will Harkins said residential customer acquisition “remained under pressure,” and Rollins is shifting marketing money from its traditional digital playbook toward channels that show up in AI-driven discovery. Residential organic growth slowed to 2.3%, from 3.6% in the second quarter, in a business that makes up 46% of revenue.
The cost lines tell a different story. Selling and marketing slipped as a share of revenue, to 13.4% from 13.5%. Insurance and claims costs roughly doubled to $36.8 million from $18.1 million, or about 160 basis points of revenue. That covers more than the entire 140-basis-point drop in operating margin, to 20.5%. (The release doesn’t say whether that cost repeats.)
Rollins Stock Is Already 40% Below Its Average Multiple
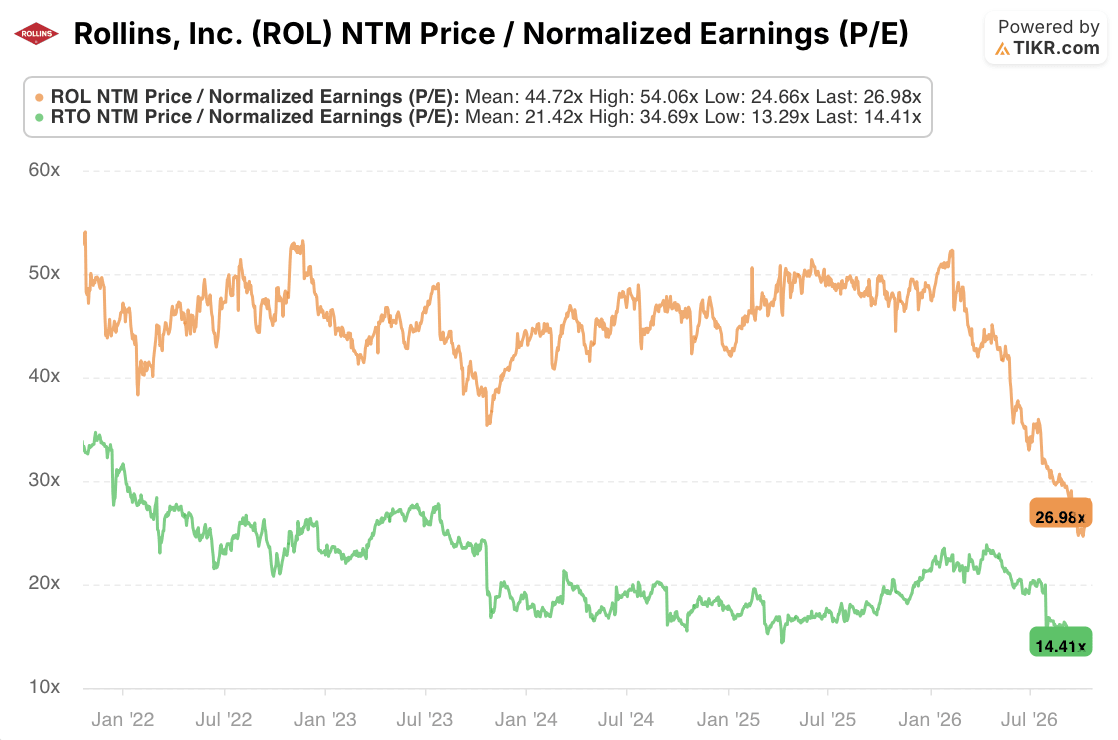
Rollins trades at 26.98 times NTM normalized earnings, against a five-year average of 44.72 times and a low of 24.66 times. Thursday’s drop, with estimates unchanged, would take it to about 25 times, right at that floor.

Most of the de-rating is already done. The multiple was above 50 times at the start of 2026.
TIKR Tracks 19 Analysts on Rollins. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Rollins, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Rollins’ Analyst Ratings
Rentokil Is the Cheaper Way to Own the Same Problem
Rentokil, which owns Terminix, trades at 14.41 times, below its own 21.42-times average. On those readings, Rollins carries an 87% premium. Adjust both for Thursday’s moves (Rollins down about 7%, Rentokil up about 8%) with estimates unchanged, and the premium shrinks to about 61%. Their five-year average multiples sit about 109% apart.
The growth gap is wider than the headline numbers suggest. Rollins grew 4.4% organically, against 3.2% for Rentokil’s whole North America business, but that figure includes faster-growing business services. Rentokil’s North America Pest Control Services business, the closer match to Rollins, grew 2.4% organically. Rentokil also said its residential lead flow improved to about a 1% decline in September after a weaker July and August. Rollins gave no such sign.
The cash doesn’t rescue Rollins either. Free cash flow rose 28.8% to $235 million, but $63 million came from the timing of a tax refund. Without it, free cash flow fell about 6%.
Rollins’ 6% Floor Looks Like the Next Thing to Go
In July, Rollins cut its 2026 outlook to at least 6% organic growth. With 5.5% through nine months, hitting that floor needs about 7.6% in the fourth quarter, against 4.4% in the third. Wednesday’s earnings release didn’t repeat the target.
That’s why 25 times doesn’t look like a floor to me. Rollins is near its cheapest multiple in five years and still outgrows Rentokil’s pest business, but it keeps a substantial premium while its biggest margin hit sits in a cost line management hasn’t explained. For Rollins holders, the number that matters is fourth-quarter organic growth: anything near 4% means the 6% target goes, and the multiple likely follows it.
So what is Rollins stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ROL stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!