Key Takeaways
- Qualcomm stock fell about 11% this week after its earnings guidance for the December quarter came in below expectations.
- CEO Cristiano Amon says supply is the only thing limiting the company’s $5 billion data center revenue target for fiscal 2027.
- Most of that $5 billion comes from two hyperscalers. One of them is Amazon, and Qualcomm puts the potential revenue from its AWS agreement at up to $60 billion over 10 years.
- At 17x forward earnings, close to its three-year average while earnings fall, the stock prices in little of the data center ramp. Shrinking margins are the main risk.
Qualcomm (QCOM) stock fell about 11% this week. Its earnings guidance for the December quarter disappointed, and rising chip costs overshadowed its non-handset growth.
But CEO Cristiano Amon wants investors looking at a different part of the business. On CNBC’s Halftime Report on Thursday, he was asked about data centers:
“I tell you right now, regardless of all this noise, I think the $5 billion commitment we made, it’s not demand bound, it’s all supply bound. If I have more supply, I’ll probably do better than $5 billion.”
That’s about as confident as a CEO gets on a down day.
On Wednesday’s fourth-quarter call, CFO Akash Palkhiwala added a useful detail. Qualcomm is “very well positioned from a supply perspective to execute on the $5 billion target.” Supply only limits growth above $5 billion.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Amazon is the anchor customer
Qualcomm guides data center revenue above $650 million in the December quarter. Palkhiwala expects the business to end fiscal 2027 at about a $7 billion annual run rate, and management’s target for fiscal 2029 is more than $15 billion.
On the call, Amon said most of fiscal 2027’s $5 billion comes from two hyperscalers, and one of them is Amazon (AMZN). Qualcomm’s custom accelerators for Amazon Web Services started shipping in October, and its connectivity chips for AWS ramp later in November.
Palkhiwala also put the AWS agreement’s potential revenue at up to $60 billion over the next 10 years. That’s the deal Qualcomm signed in September. Spread evenly, it comes to $6 billion a year from Amazon alone, which is more than the whole fiscal 2027 target (assuming Amazon reaches the top of that range). Amazon also holds a warrant for up to 25 million Qualcomm shares, so it has a stake in this going well.
Analysts aren’t counting on much of it yet
Going into the report, analysts expected Qualcomm’s total revenue to grow only from $43.2 billion in fiscal 2026 to $44.8 billion in fiscal 2027:
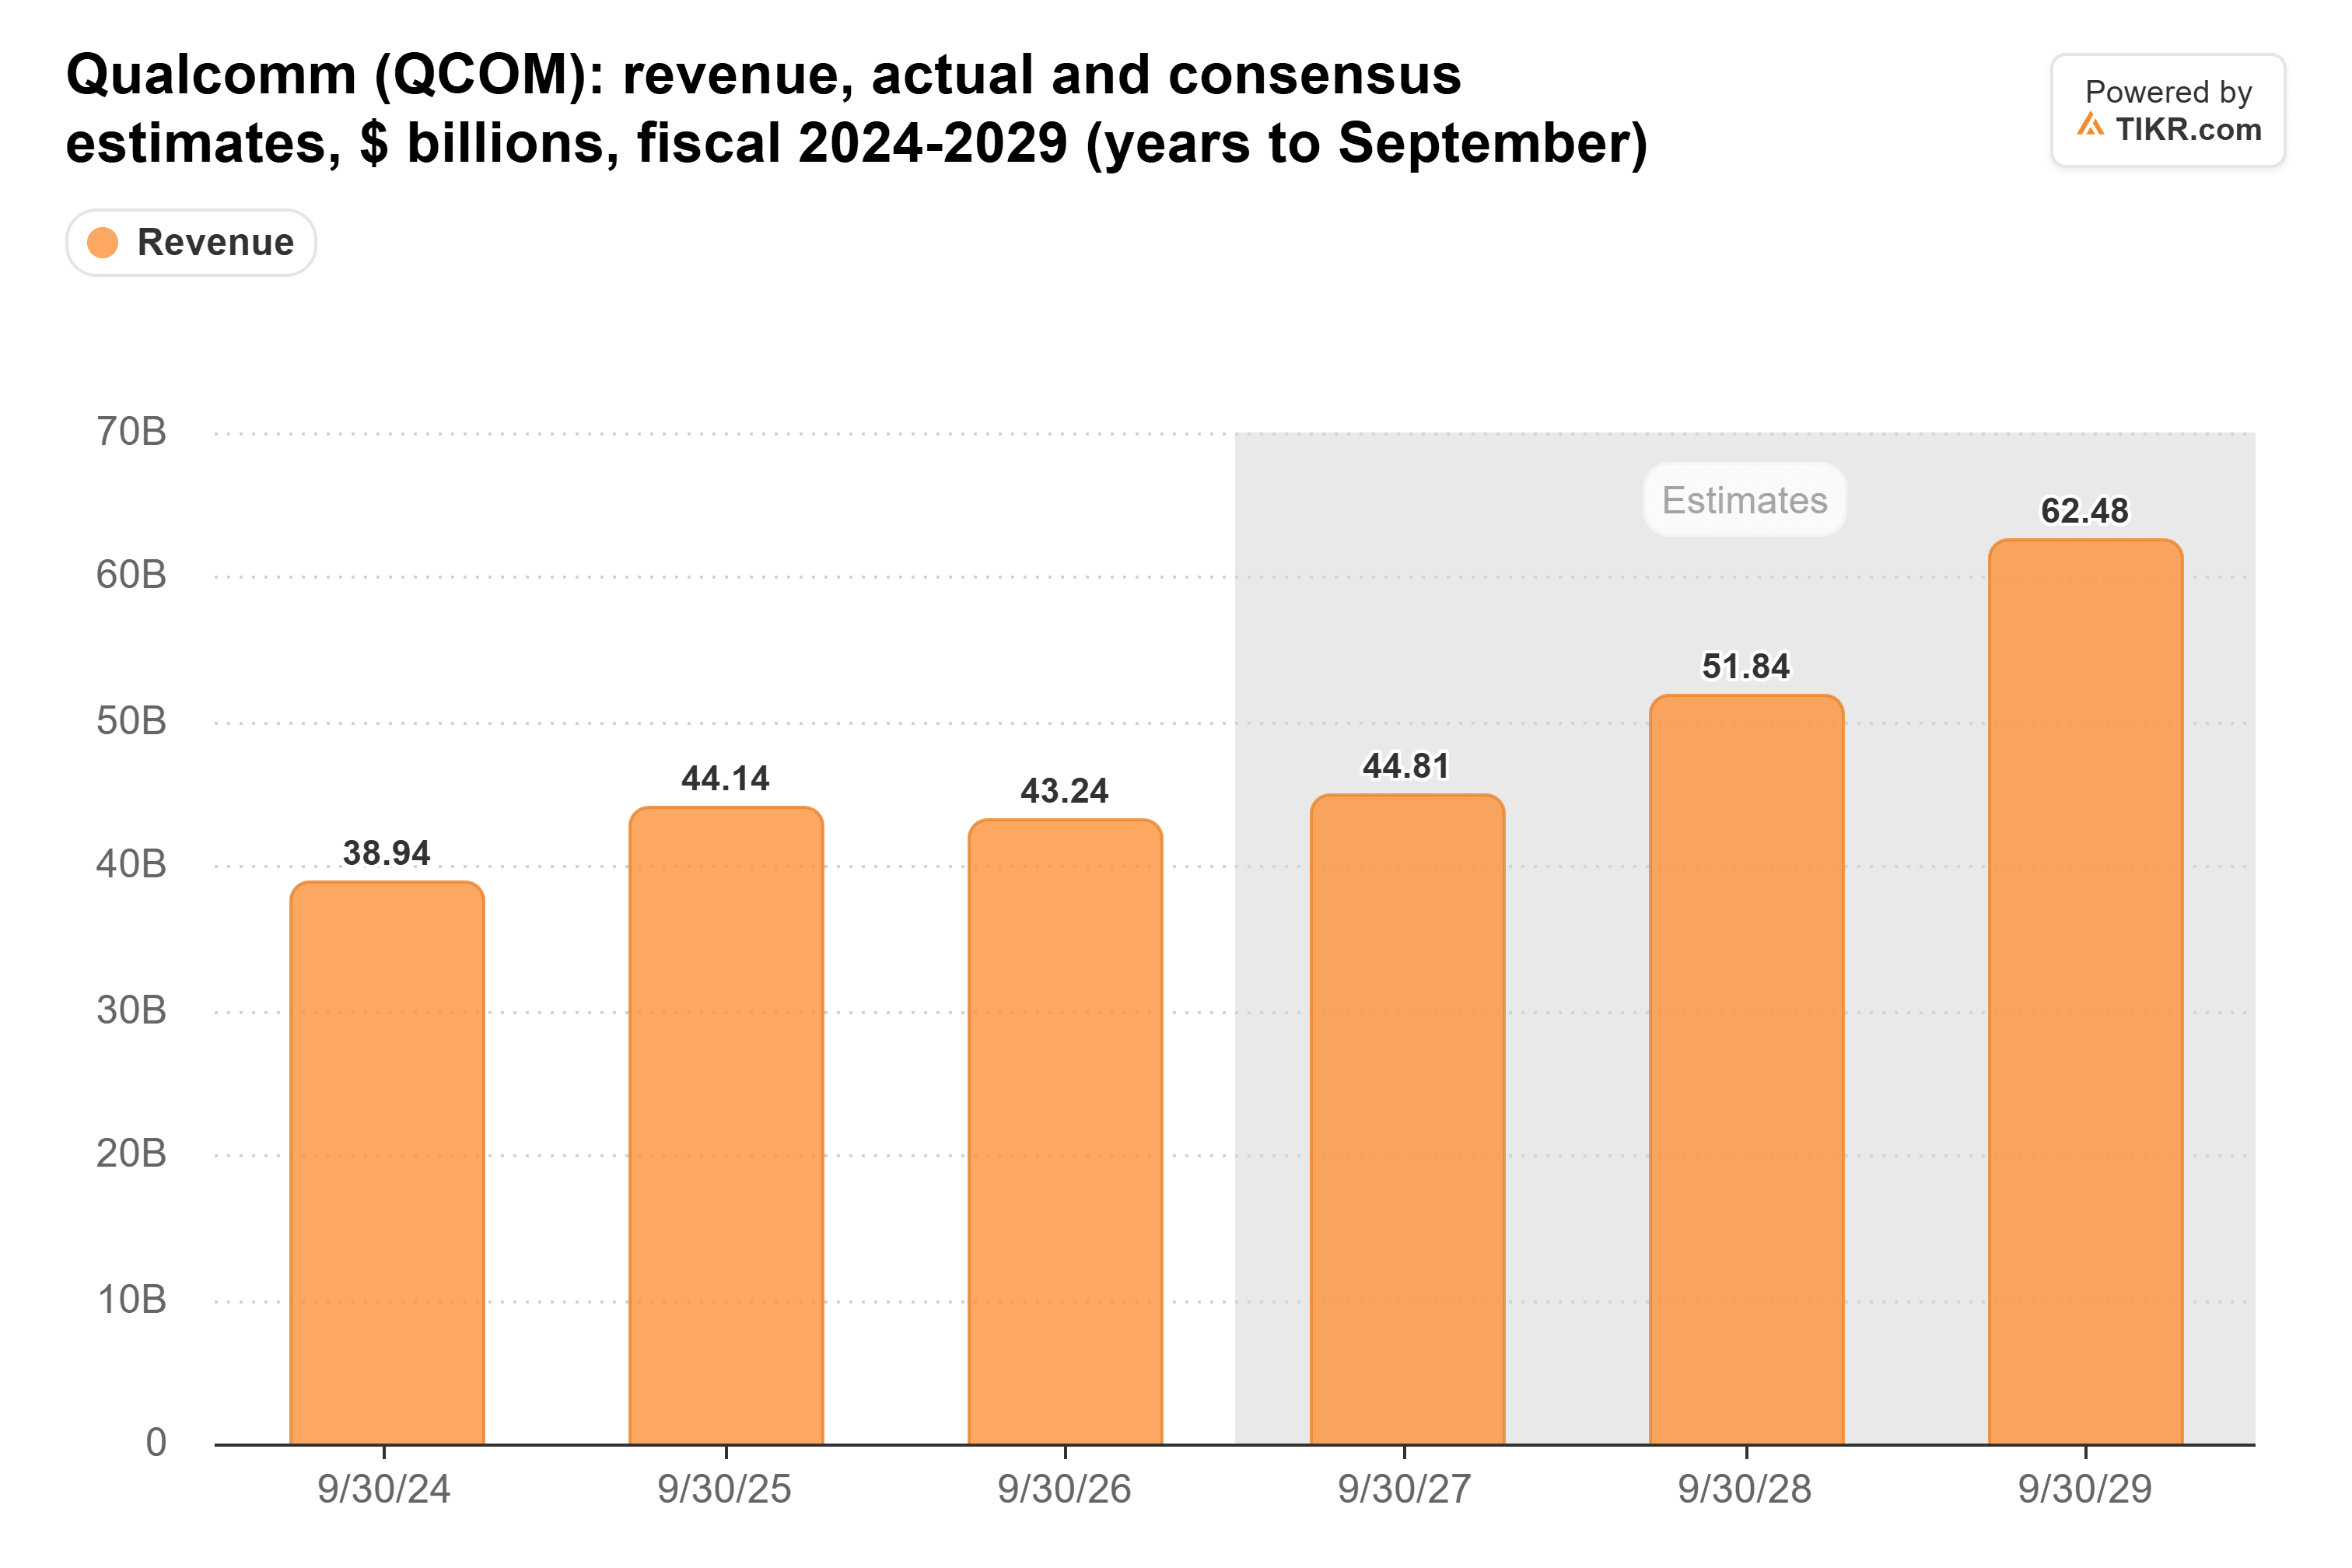
That’s $1.6 billion of growth in a year when data centers alone are supposed to add $5 billion. Part of the gap is Apple’s switch to its own modems, which Amon says investors already understand. I suspect the gap also means analysts aren’t giving Qualcomm full credit for the ramp. Nothing in this week’s report gives them a reason to cut that part of their estimates, since management kept both data center targets.
An average multiple on falling earnings
Qualcomm trades at 17x forward earnings. That’s a bit above its three-year average of 16x and well below the 26x it reached in May:
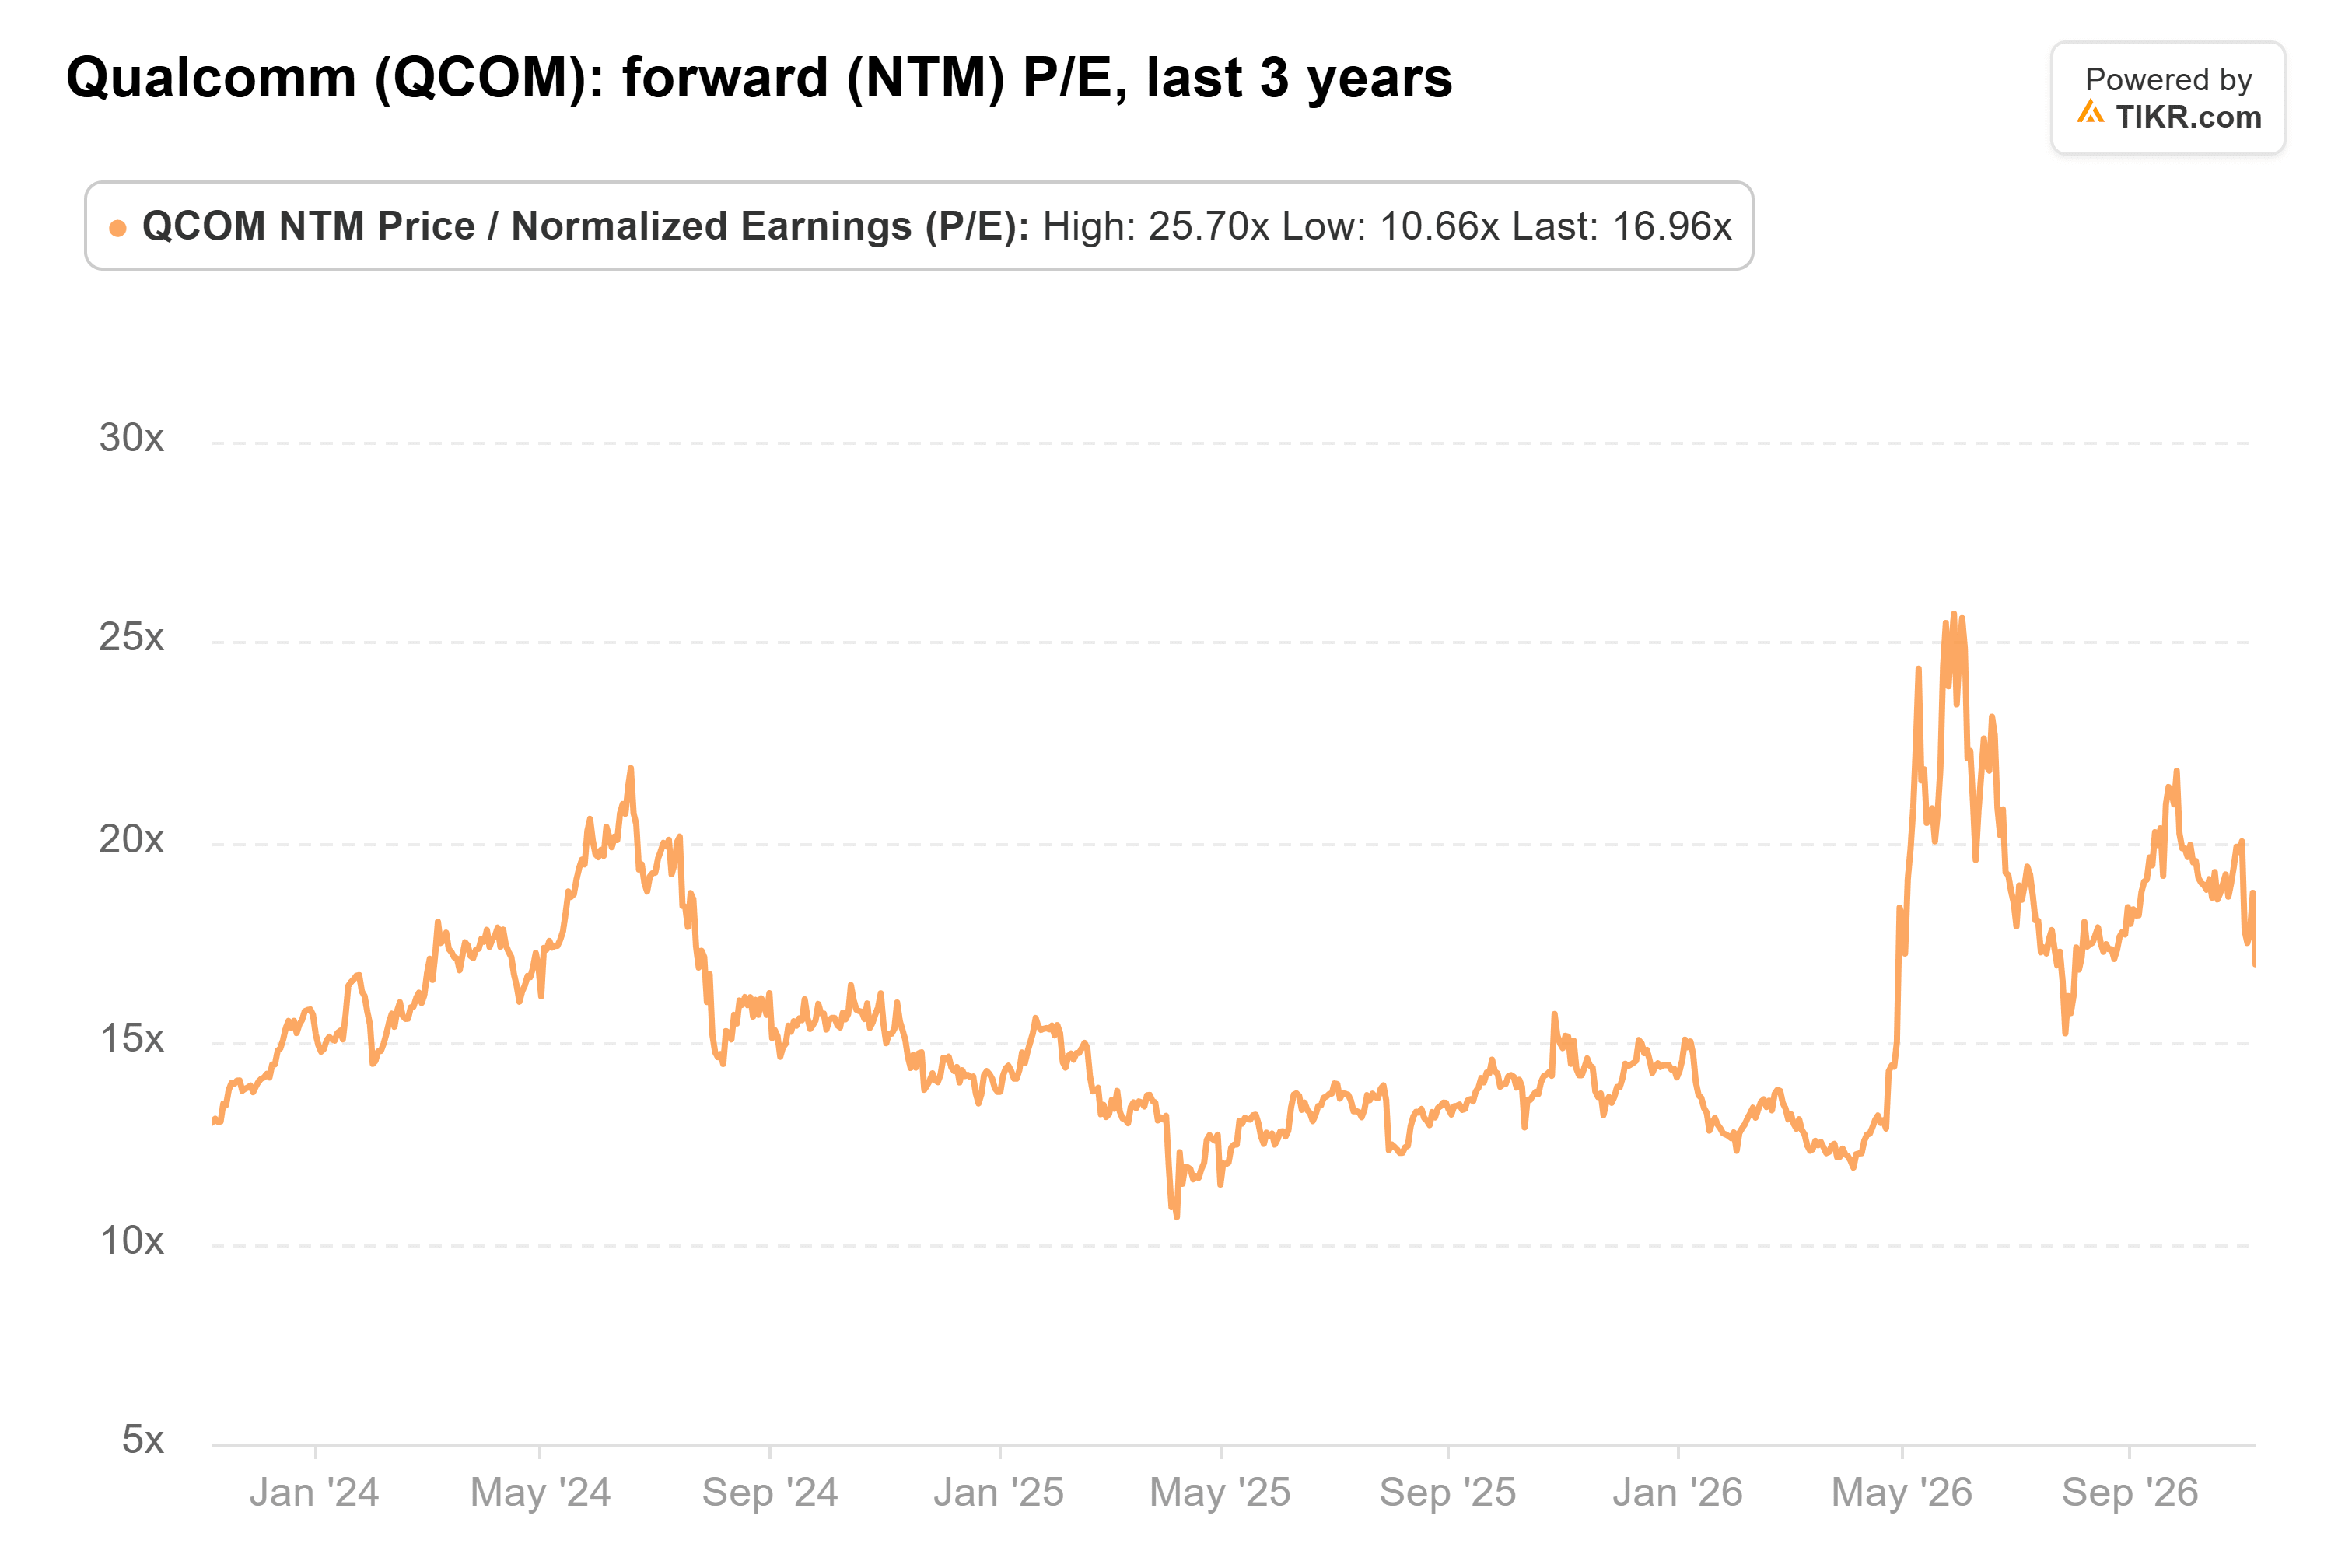
And those earnings are going backward. Analysts expect adjusted EPS of $10.17 in fiscal 2027. That’s below the $10.54 Qualcomm earned in fiscal 2026, and further below the $12.03 of fiscal 2025. So the market is paying a normal multiple on lower earnings, and very little for a business that management says could bring in more than $15 billion of revenue by fiscal 2029.
Tight supply is already costing Qualcomm
Of course, a business limited by supply depends on the same tight market for wafers, packaging and memory that has been raising Qualcomm’s costs. Amon didn’t say which parts are holding back the data center ramp. But you can see the cost pressure in Qualcomm’s operating margin, which fell from 30.5% in the quarter to December 2024 to 13.1% in the quarter to September 2026:
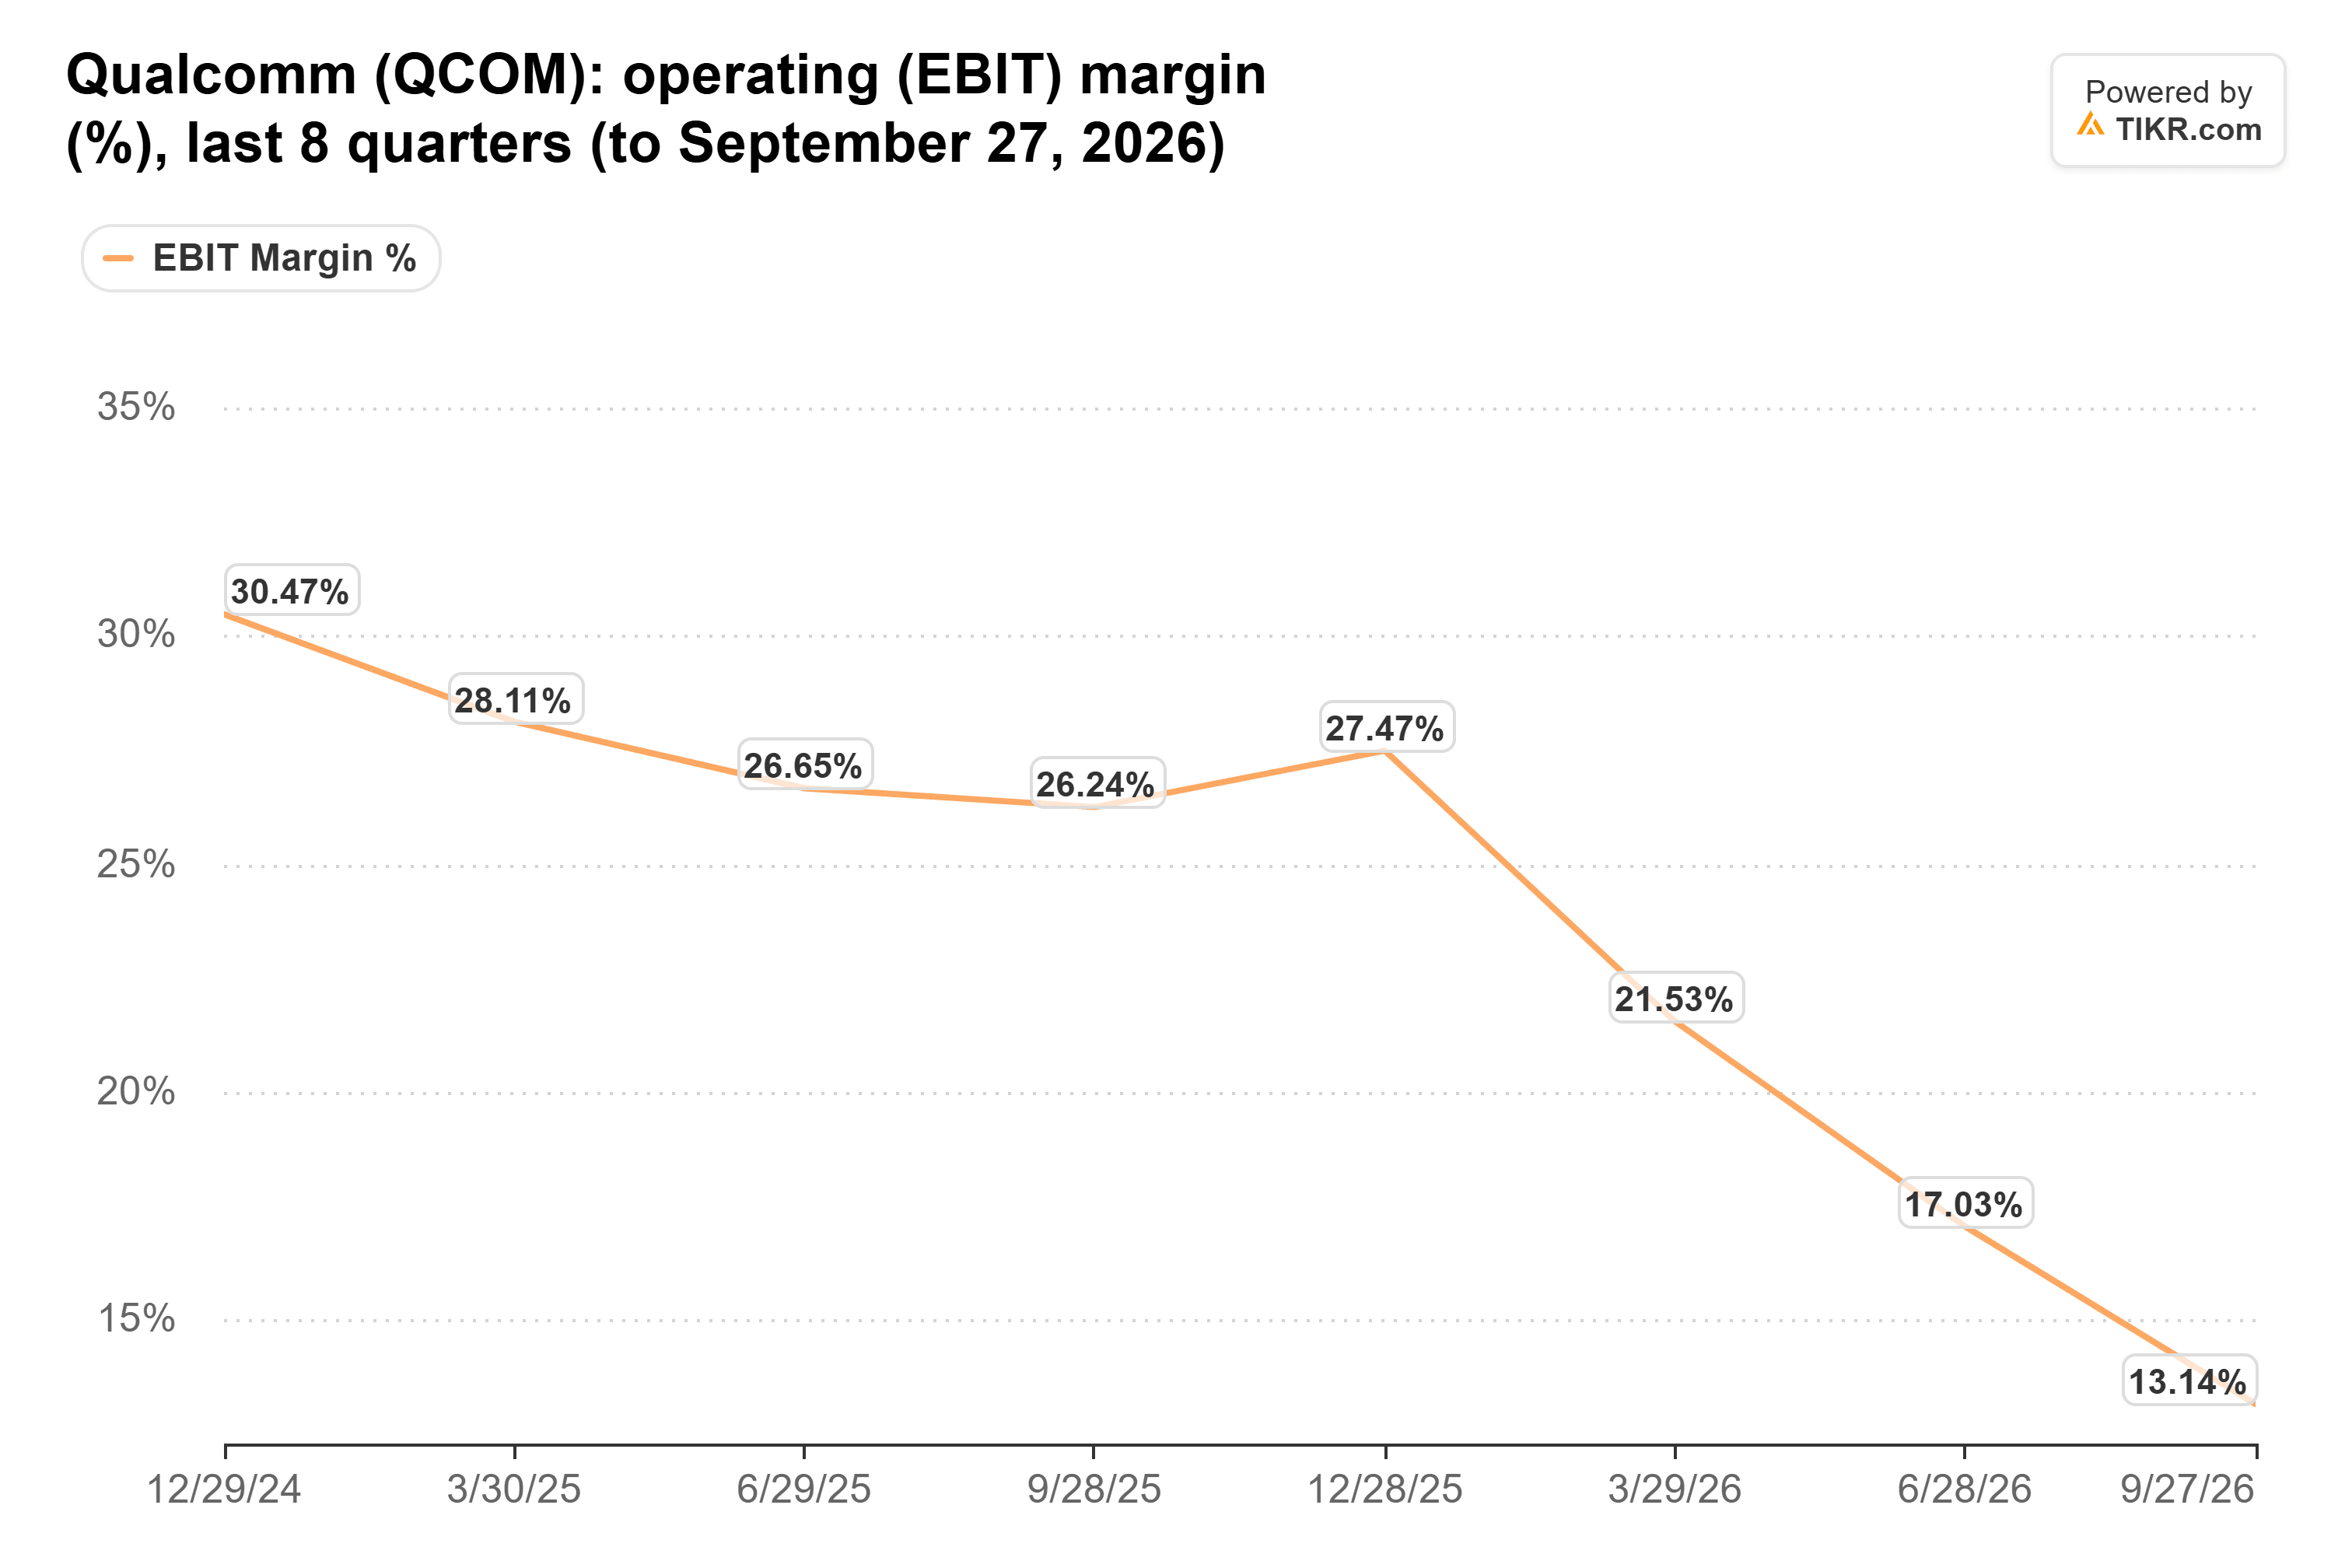
Qualcomm is raising prices across its products to cover higher chip costs. Palkhiwala said the full benefit won’t show up in the chip unit’s gross margins until the second half of fiscal 2027. Data centers also add to the pressure in the short term. The chip unit’s guided margin of 20% to 22% for the December quarter includes about 3 points of drag from adding the data center business, which is spending ahead of its revenue. Palkhiwala expects the custom chips to lower the unit’s gross margins but raise its operating margins.
If supply stays tight for longer, Qualcomm could hit $5 billion and still see its margins lag.
I’d take a supply problem
The way I see it, this week’s selloff priced Qualcomm as a handset company with a margin problem. That’s fair for the next couple of quarters. But Amon says he’d sell more data center chips if he had more supply, and he has an Amazon agreement worth up to $60 billion behind him. That deserves more credit than an average multiple on falling earnings gives it.
The first real test is the December-quarter report in early 2027. Look for data center revenue above $650 million, and for signs that the price increases are lifting the chip unit’s margins.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!