Key Takeaways
- Booking Holdings stock is down 20% this year, even after a 16% jump in the past week on its third-quarter results.
- Booking returned $10.5 billion to shareholders in the first nine months of 2026, $9.5 billion of it through buybacks.
- The dividend took just under 14% of free cash flow in 2025, so most of the cash goes to buybacks, and a lower share price means each dollar buys back more stock.
- The main risk is AI agents steering travelers to book directly with hotels, which would shrink the free cash flow that pays for the buybacks.
Booking Holdings (BKNG) is down 20% this year, and it’s been buying back its own stock hand over fist the whole way down.
Shares jumped 16% in the past week after Booking’s third-quarter report on Nov. 3. Adjusted EPS rose 17% to $4.66, and room nights grew 7%, up from 4% in the second quarter.
Wall Street still can’t agree on the stock. Cantor Fitzgerald kept its Hold rating and cut its target to $150, while B. Riley Securities rated it a Buy with a $265 target. For me, the better case for the stock is what Booking does with its cash.
Plenty of cash to hand back
Booking’s free cash flow rose from $7 billion in 2023 to $9.09 billion in 2025, and analysts expect $11.7 billion by 2028:
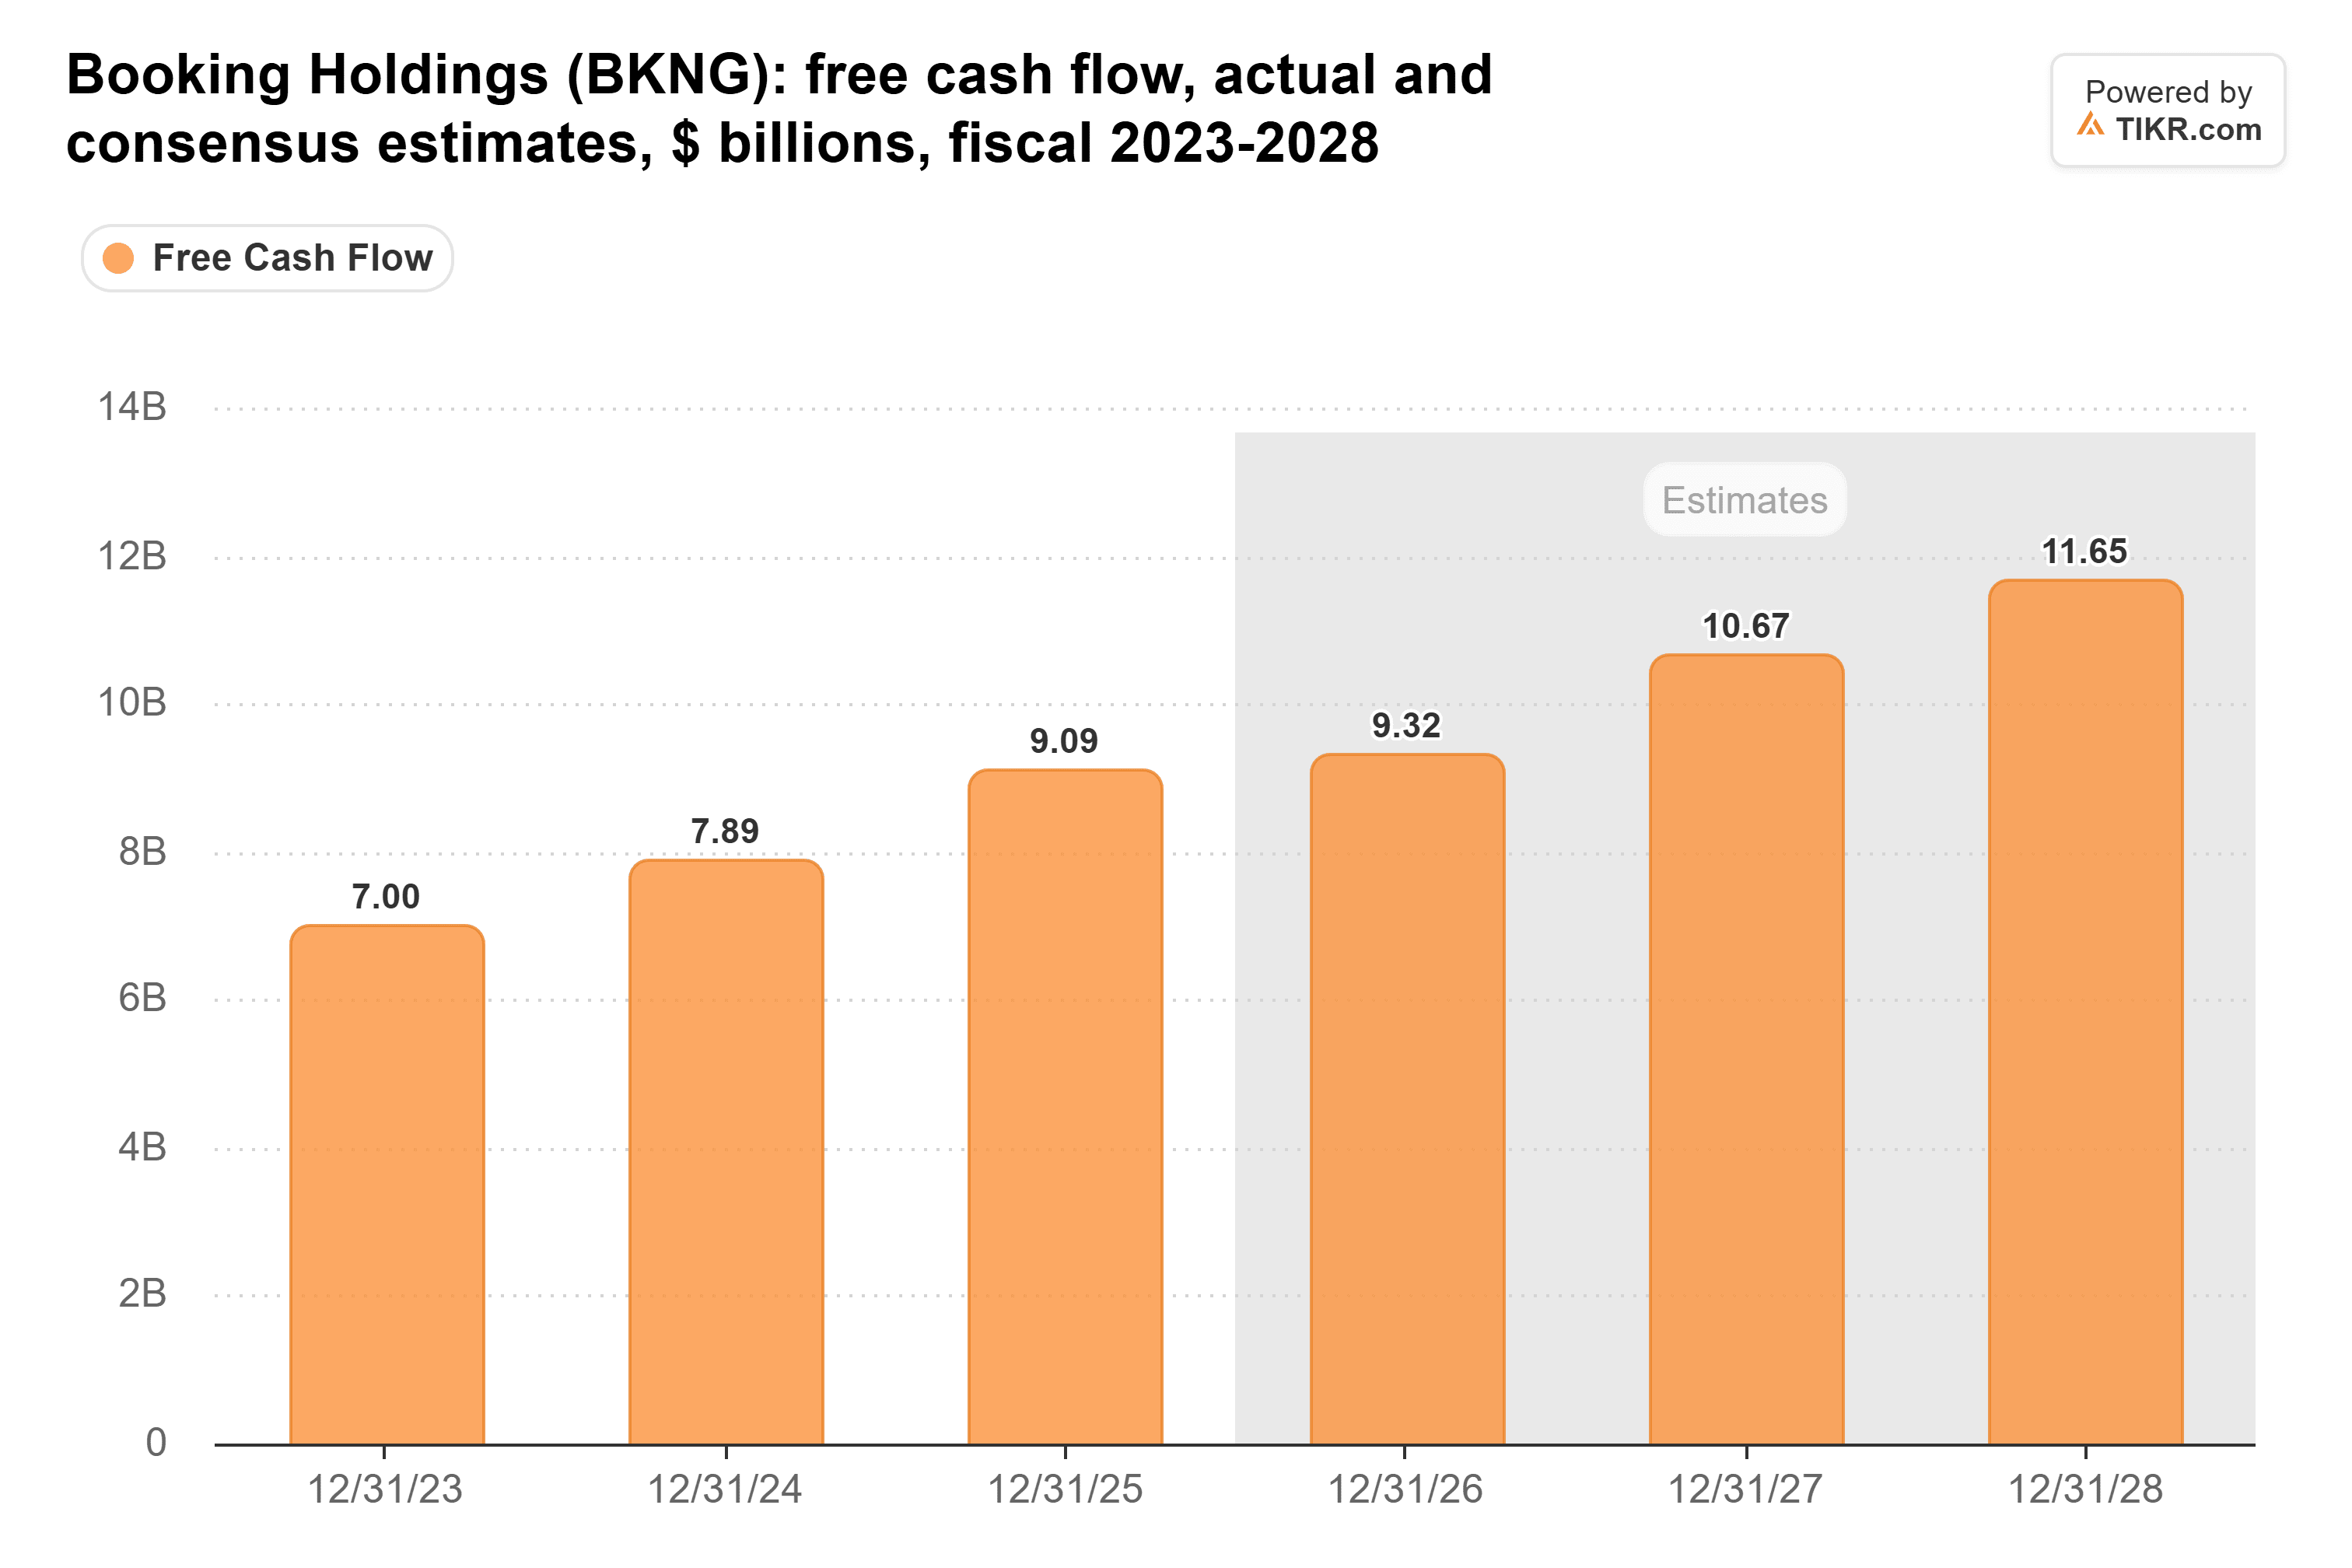
The third quarter’s $1.1 billion of free cash flow looks light next to that. Booking says a $3.6 billion seasonal unwind of deferred merchant bookings caused it, and with room-night growth speeding up, I don’t see a reason for analysts to cut those estimates.
Booking started paying a dividend in 2024, and it uses up only a small share of that cash. The dividend cost $1.25 billion in 2025, just under 14% of free cash flow:

That leaves most of the cash for buybacks.
TIKR tracks 37 analysts on Booking Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Booking Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Booking Holdings’ Analyst Ratings
Every buyback dollar goes further now
And Booking is spending it. The company returned $10.5 billion to shareholders in the first nine months of 2026, including $9.5 billion of repurchases, it said in its third-quarter prepared remarks. That’s more than 8% of its $127.2 billion market value at the last close.
This isn’t new for Booking. Its diluted share count fell 35% from 2016 to 2025:
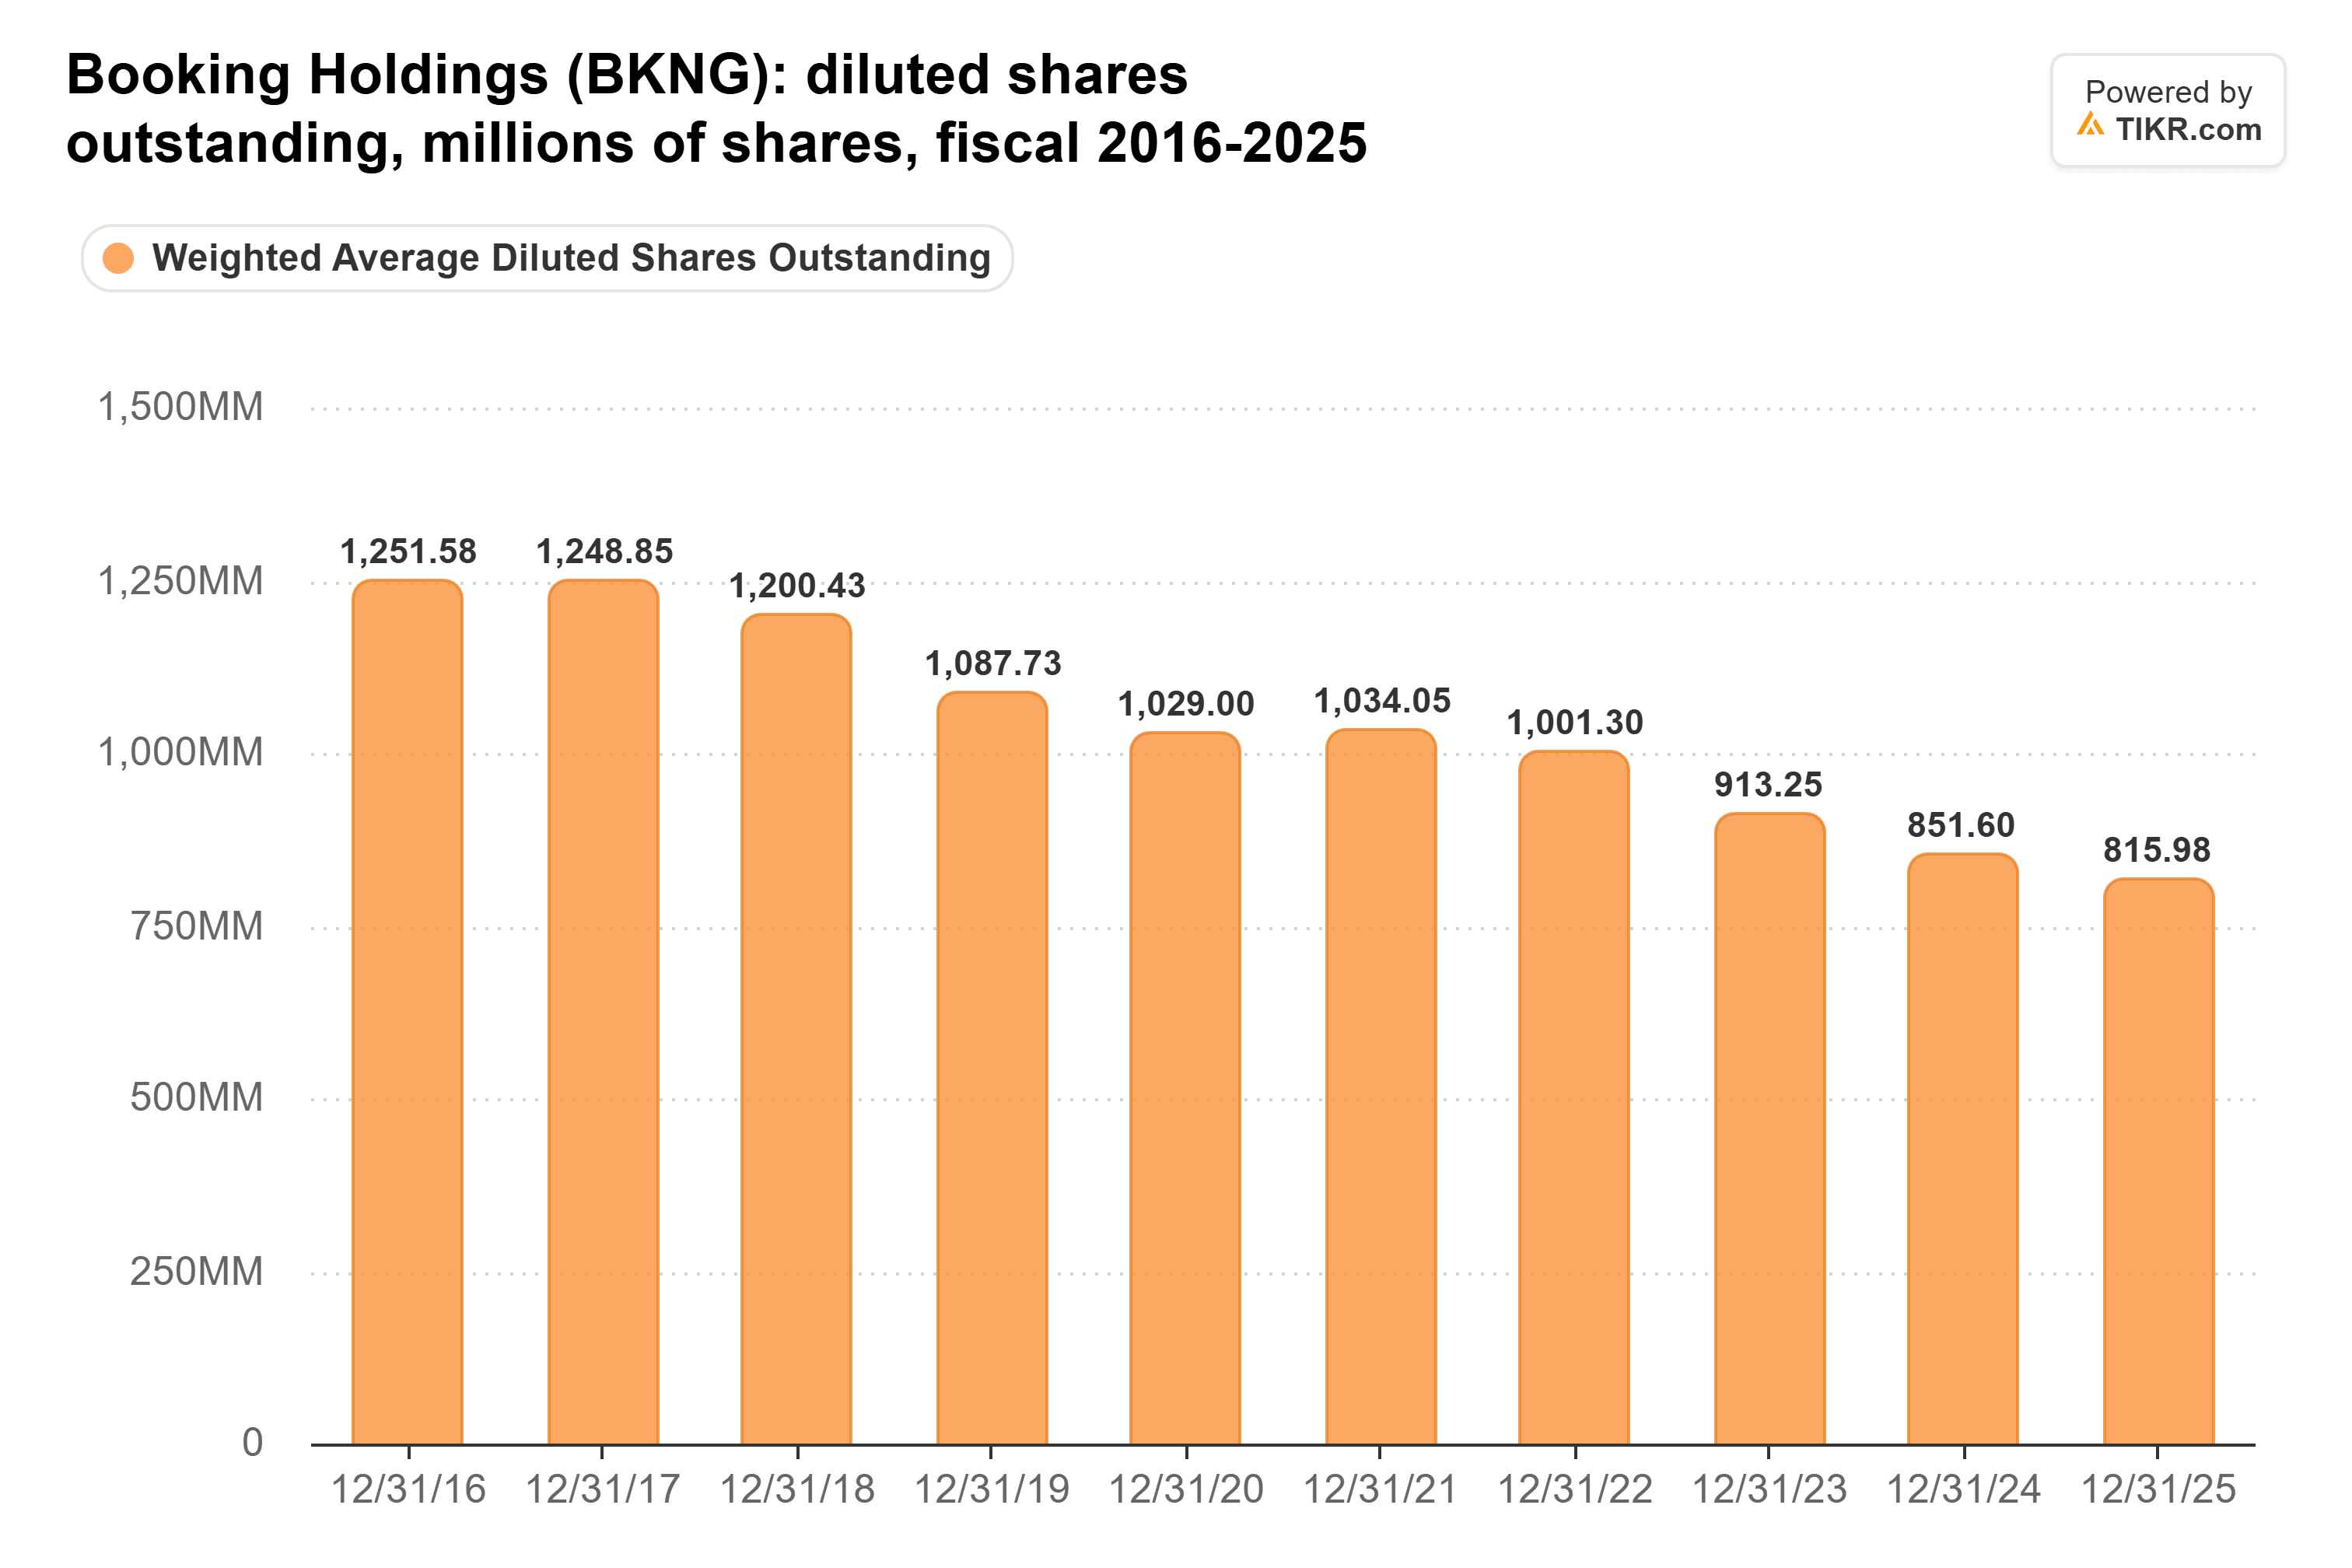
You can see it in earnings per share. In the third quarter, adjusted EPS grew 17% while adjusted EBITDA grew 9%, and Booking credits a 7.5% drop in its average share count for part of the gap. Because of this year’s drop, each buyback dollar now buys about a quarter more stock than it would have in January.
Booking can’t keep up this exact pace on free cash flow alone. What it has returned in nine months is already more than the $9.32 billion of free cash flow analysts expect for all of 2026, and cash and investments fell to $16.2 billion at the end of the third quarter, from $17.7 billion three months earlier.
Still, say Booking spent only what analysts expect it to generate this year, minus a dividend bill like 2025’s $1.25 billion. That’s about $8 billion, enough to buy back roughly 6% of the company at the last close.
AI agents could shrink the pool
The cash flow is the risk. Morgan Stanley’s Stephen Grambling explained why on the Thoughts on the Market podcast: hotels pay online travel agencies commissions of 10-20% for a branded hotel, or 20-30% for an independent one, while “Booking directly through a hotel’s website costs the brand closer to only 5%.”
Morgan Stanley looked at hotel searches across eight US destinations. Traditional search engines sent travelers to official hotel websites 13% of the time. AI searches sent them there 97% of the time. If AI agents push more travelers to book direct, Booking’s take rate and free cash flow both shrink, and today’s buybacks would be paying up for a business in decline.
But Grambling’s team also found something else. When the AI agent was told a traveler belonged to an online travel agency’s loyalty program, its results shifted entirely to that platform. Booking has a big loyalty program of its own: Level 2 and Level 3 Genius members made up a share of Booking.com’s room nights in the high 50s (percent) over the trailing twelve months, up from the mid 50s a year earlier.
Booking is buying itself on sale
Right now, Booking is handing back more cash than it makes. At this year’s lower price, that cash is buying back more of the company than it would have in January.
The way I see it, with room-night growth speeding up and analysts expecting free cash flow to keep climbing, the buyback alone makes Booking worth holding while analysts argue over the stock.
Of course, the next few reports will show us whether AI search starts eating into room nights, and whether Booking slows its buybacks to a pace its free cash flow can cover. The fourth-quarter report, due early next year, is the next check.
So what is Booking Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Booking Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Booking Holdings for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!