Key Takeaways
- Grand Theft Auto VI sold an estimated $2.36 billion of digital copies on its first day, and Scott Galloway predicts Netflix and Disney will blame it for weaker viewership.
- Netflix’s growth already comes from price increases and ads, since its view hours grew just 2% in the first half of 2026.
- Analysts expect Netflix’s revenue to grow about 11% in 2027, and the stock trades at 16x forward earnings, its low for the last three years.
- Take-Two stands to collect the hours, and Roku’s next report will show whether TV viewing actually dipped.
Take-Two Interactive (TTWO) may have just had the biggest launch in entertainment history.
Sensor Tower estimates that Grand Theft Auto VI sold 24.6 million digital copies worth about $2.36 billion through its first day, including pre-orders.
On the latest episode of Pivot, NYU Stern professor Scott Galloway said the streaming business has “sort of hit a wall” because it “stopped taking share” from linear TV last year. His prediction for the next round of calls from streamers like Netflix (NFLX) and Disney (DIS): “they’re gonna blame Grand Theft Auto for a decline in viewership.”
I’d bet he’s right about the excuse. I just don’t think it changes much for Netflix’s stock. We’ll get a cleaner read on viewing soon from Roku (ROKU).
TIKR tracks 51 analysts on Netflix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
Netflix already grows without more viewing
Galloway’s starting point checks out at Netflix. Its view hours grew just 1.5% in 2025 and 2% in the first half of 2026. Revenue still grew 11.8% in the third quarter, and management expects $51.1 billion for the year, up 13%. Price increases and ads make up the difference: Netflix raised U.S. prices 8% to 13% in March, and it expects about $2.7 billion of ad revenue this year.
Analysts expect revenue to grow about 11% in 2027, to $56.6 billion:
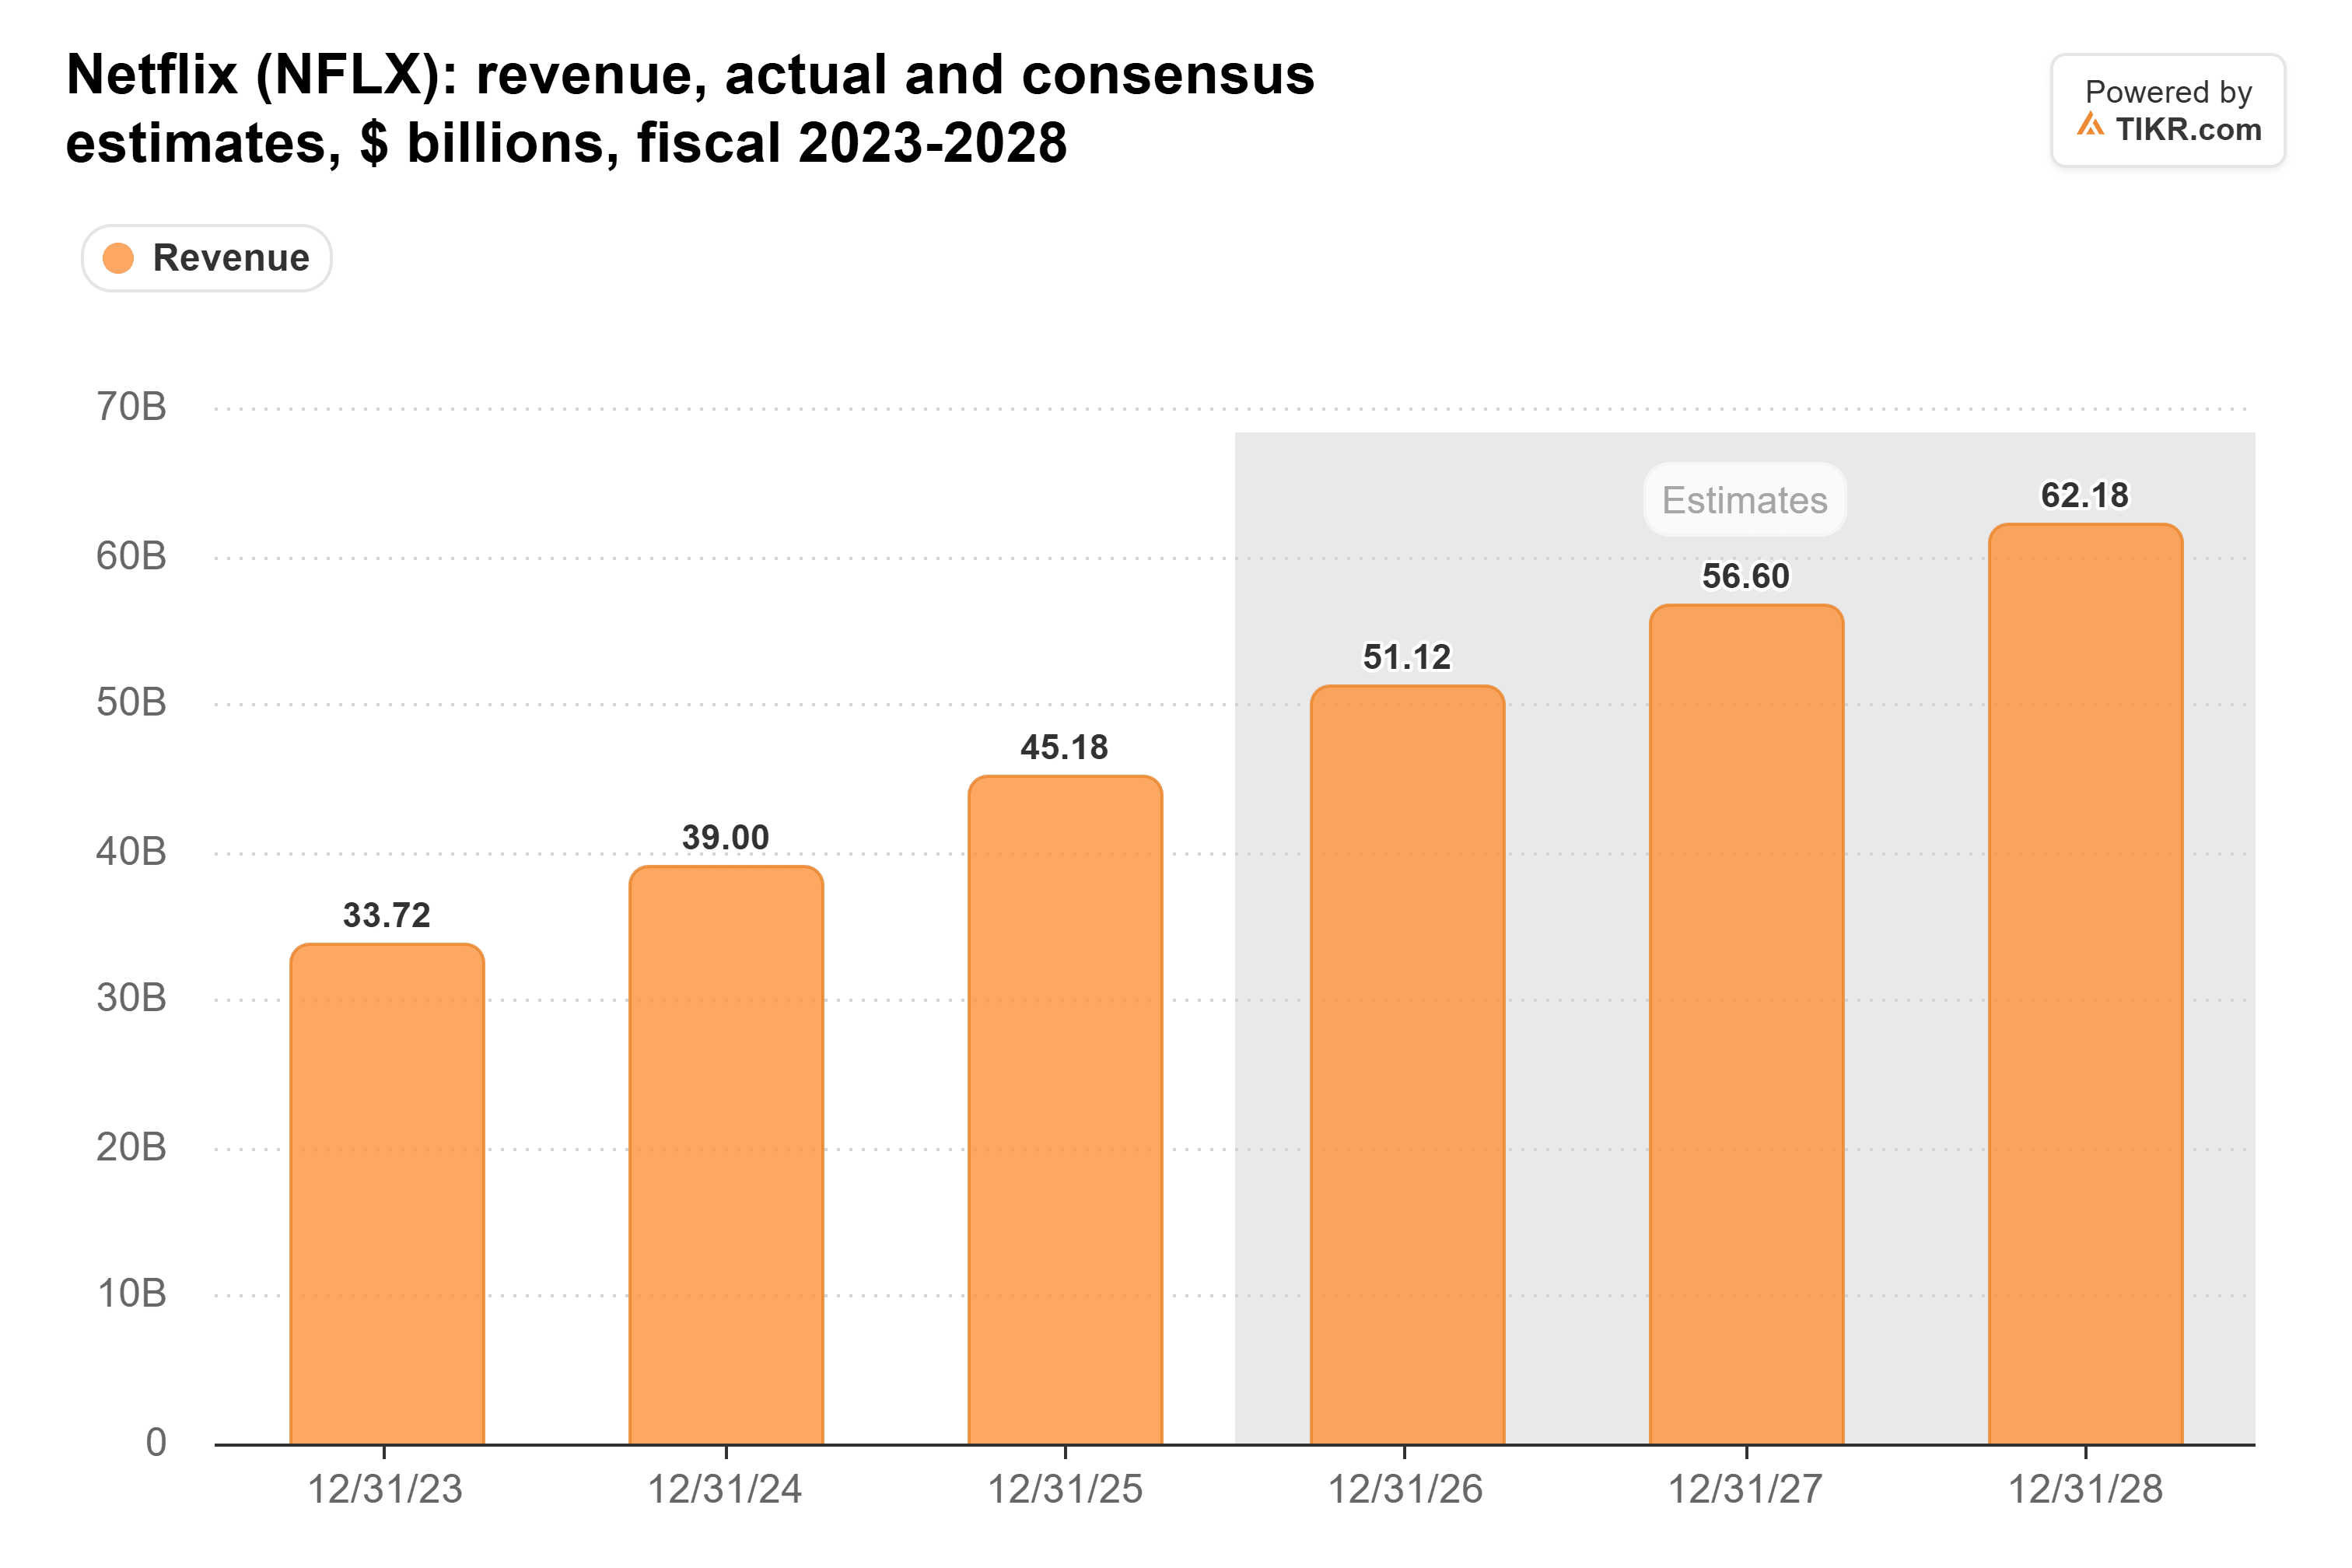
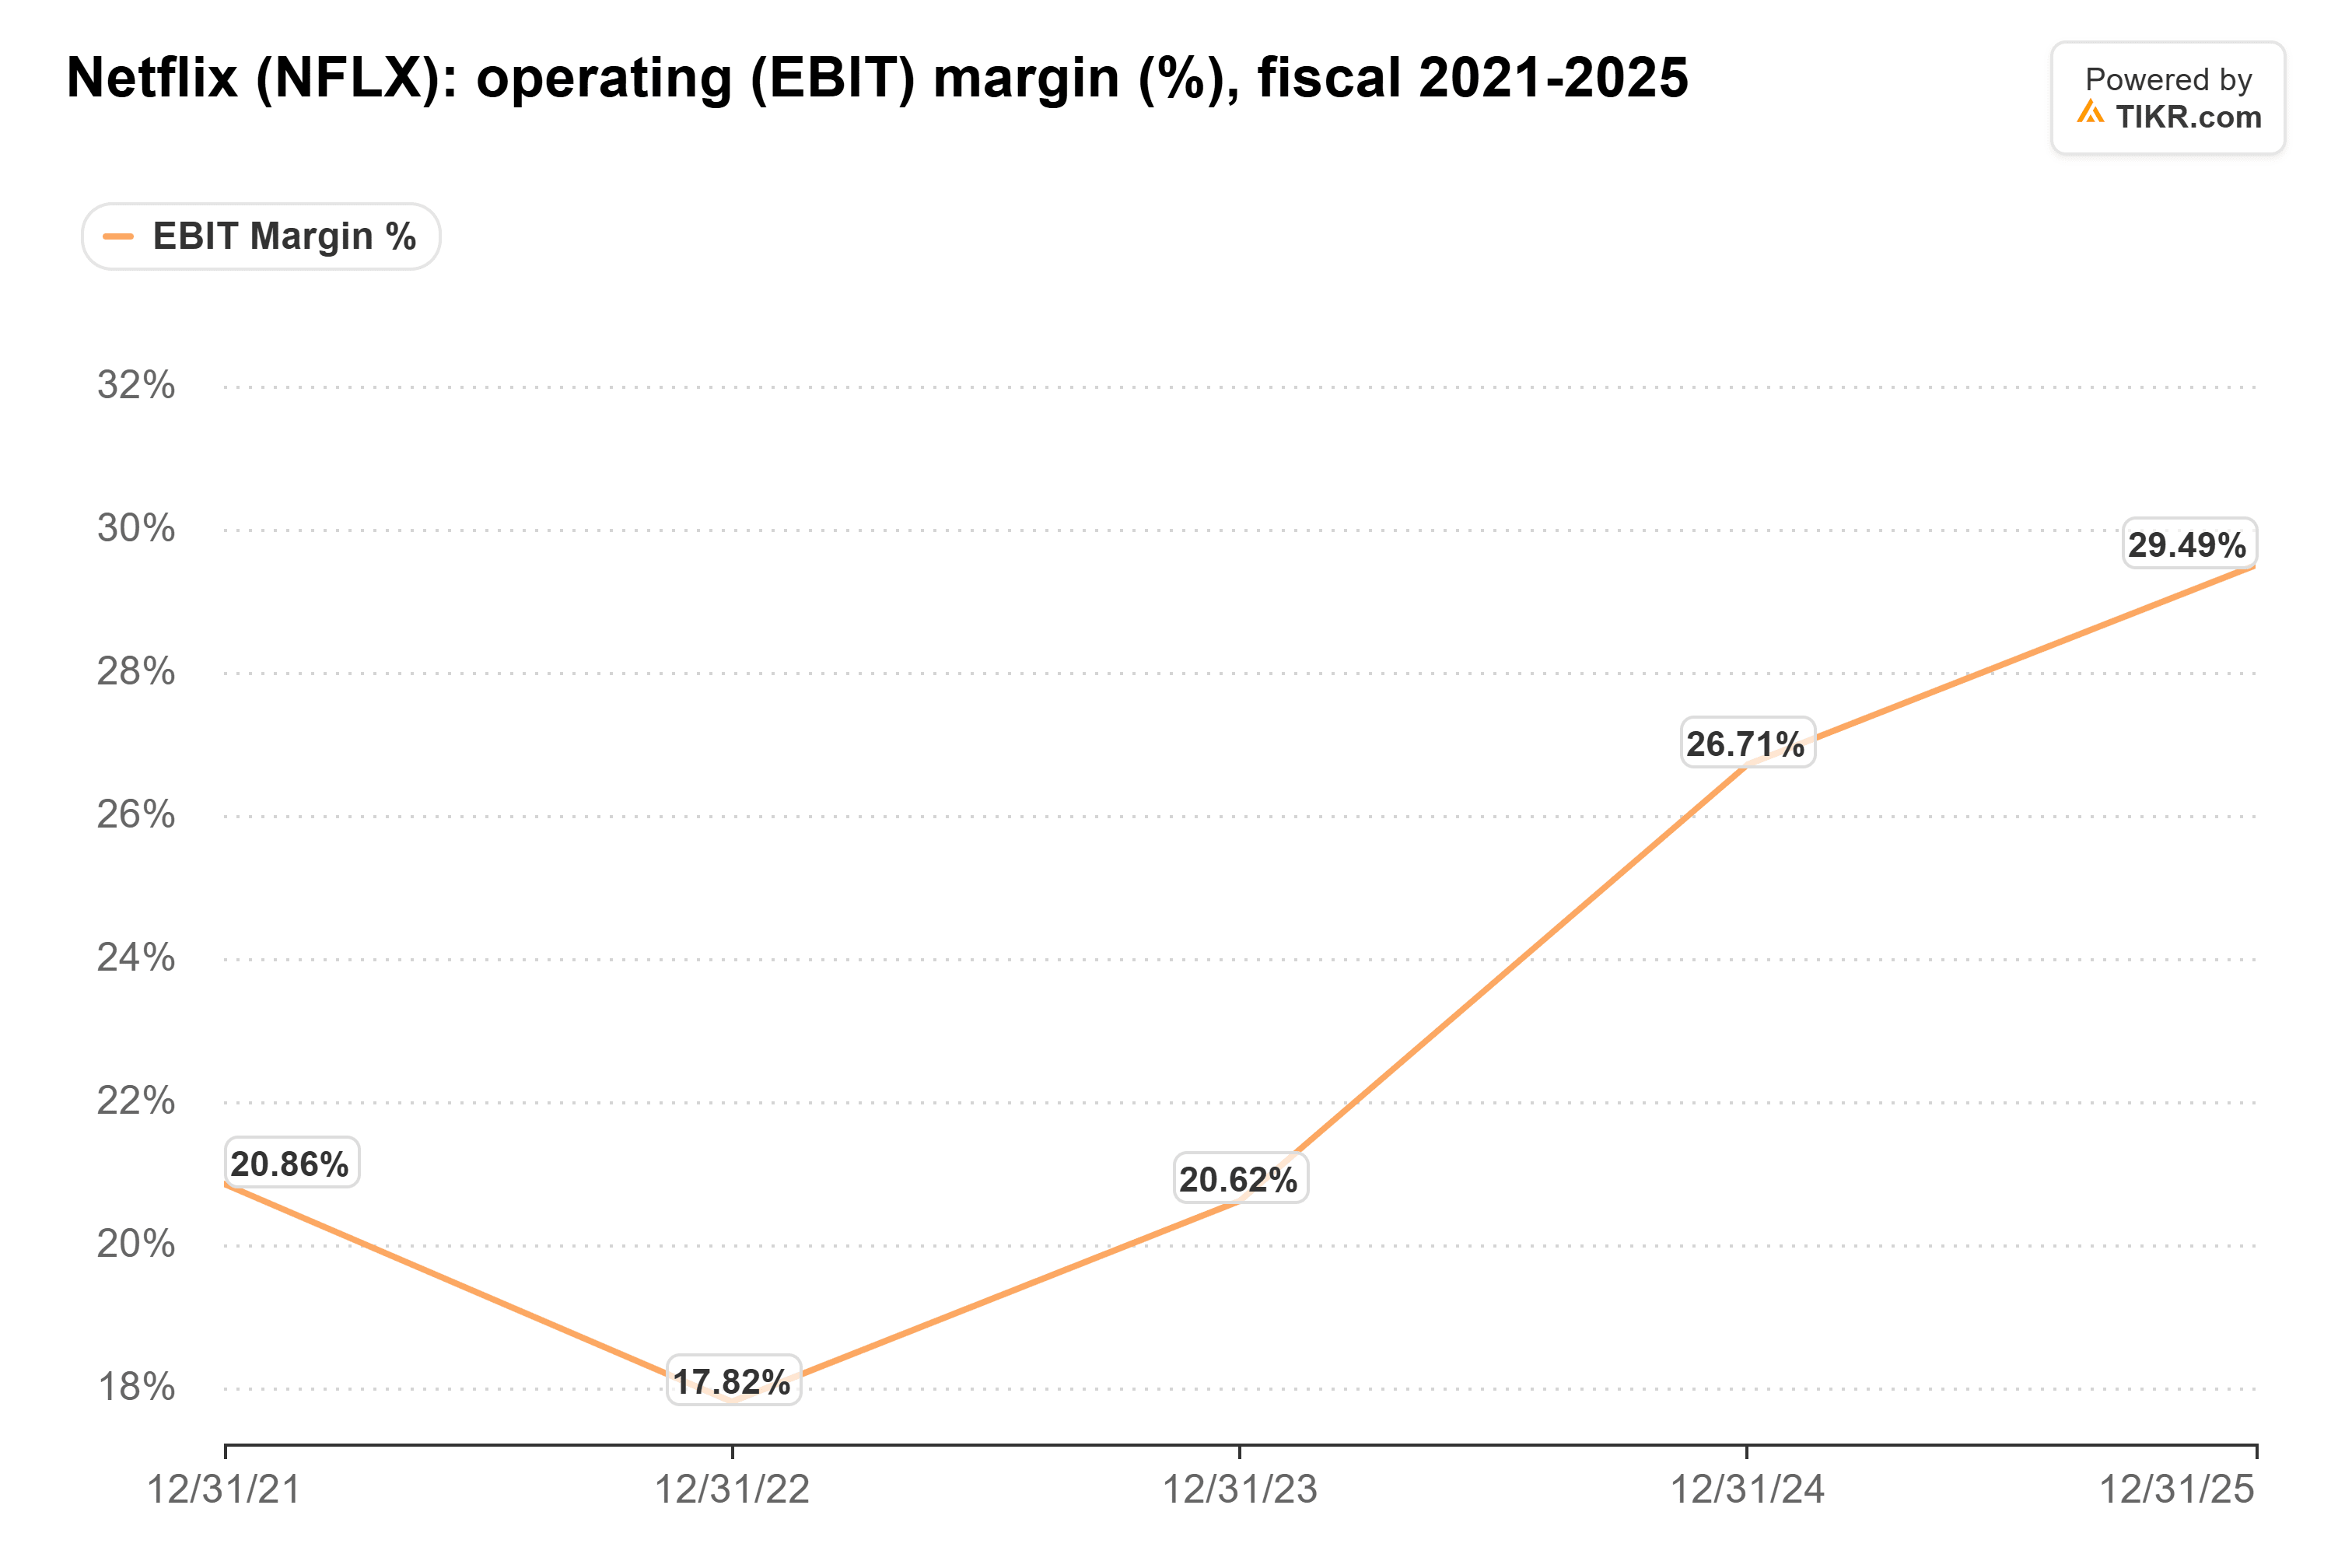
That’s a bar Netflix can clear on pricing and ads, whatever GTA does to December’s viewing. Growing this way has also been profitable. Netflix’s operating margin rose from 20.6% in 2023 to 29.5% in 2025, and most of that gain came from content costs shrinking as a share of revenue:
Price increases still need people watching
Members still put up with a bigger bill because they use the service. So far they’re paying up, and churn improved year over year in the third quarter. But if a game takes a few evenings a week through the holidays, Netflix will have a harder time pushing through its next increase.
Disney is in a different position. Its Disney+ and Hulu business posted an 11.5% operating margin in fiscal 2026, far below Netflix’s. That leaves Disney a lot of room to earn more from the subscribers it already has, even if they watch a bit less.
Take-Two gets paid for the hours
If players stick around, Take-Two gets paid for it. In its Nov. 9 results release, it guided to $3.35 billion to $3.5 billion of net bookings for the December quarter. The bigger prize is ongoing spending: in-game purchases and other recurrent spending made up 81% of net bookings last quarter, before GTA VI launched. A long-running online mode for GTA VI is also what would keep players away from Netflix well past the holidays.
The stock already expects less viewing
Netflix shareholders aren’t paying for an engagement boom. The stock trades at 16x forward earnings, its lowest point of the last three years and about half its 33x average over that stretch:
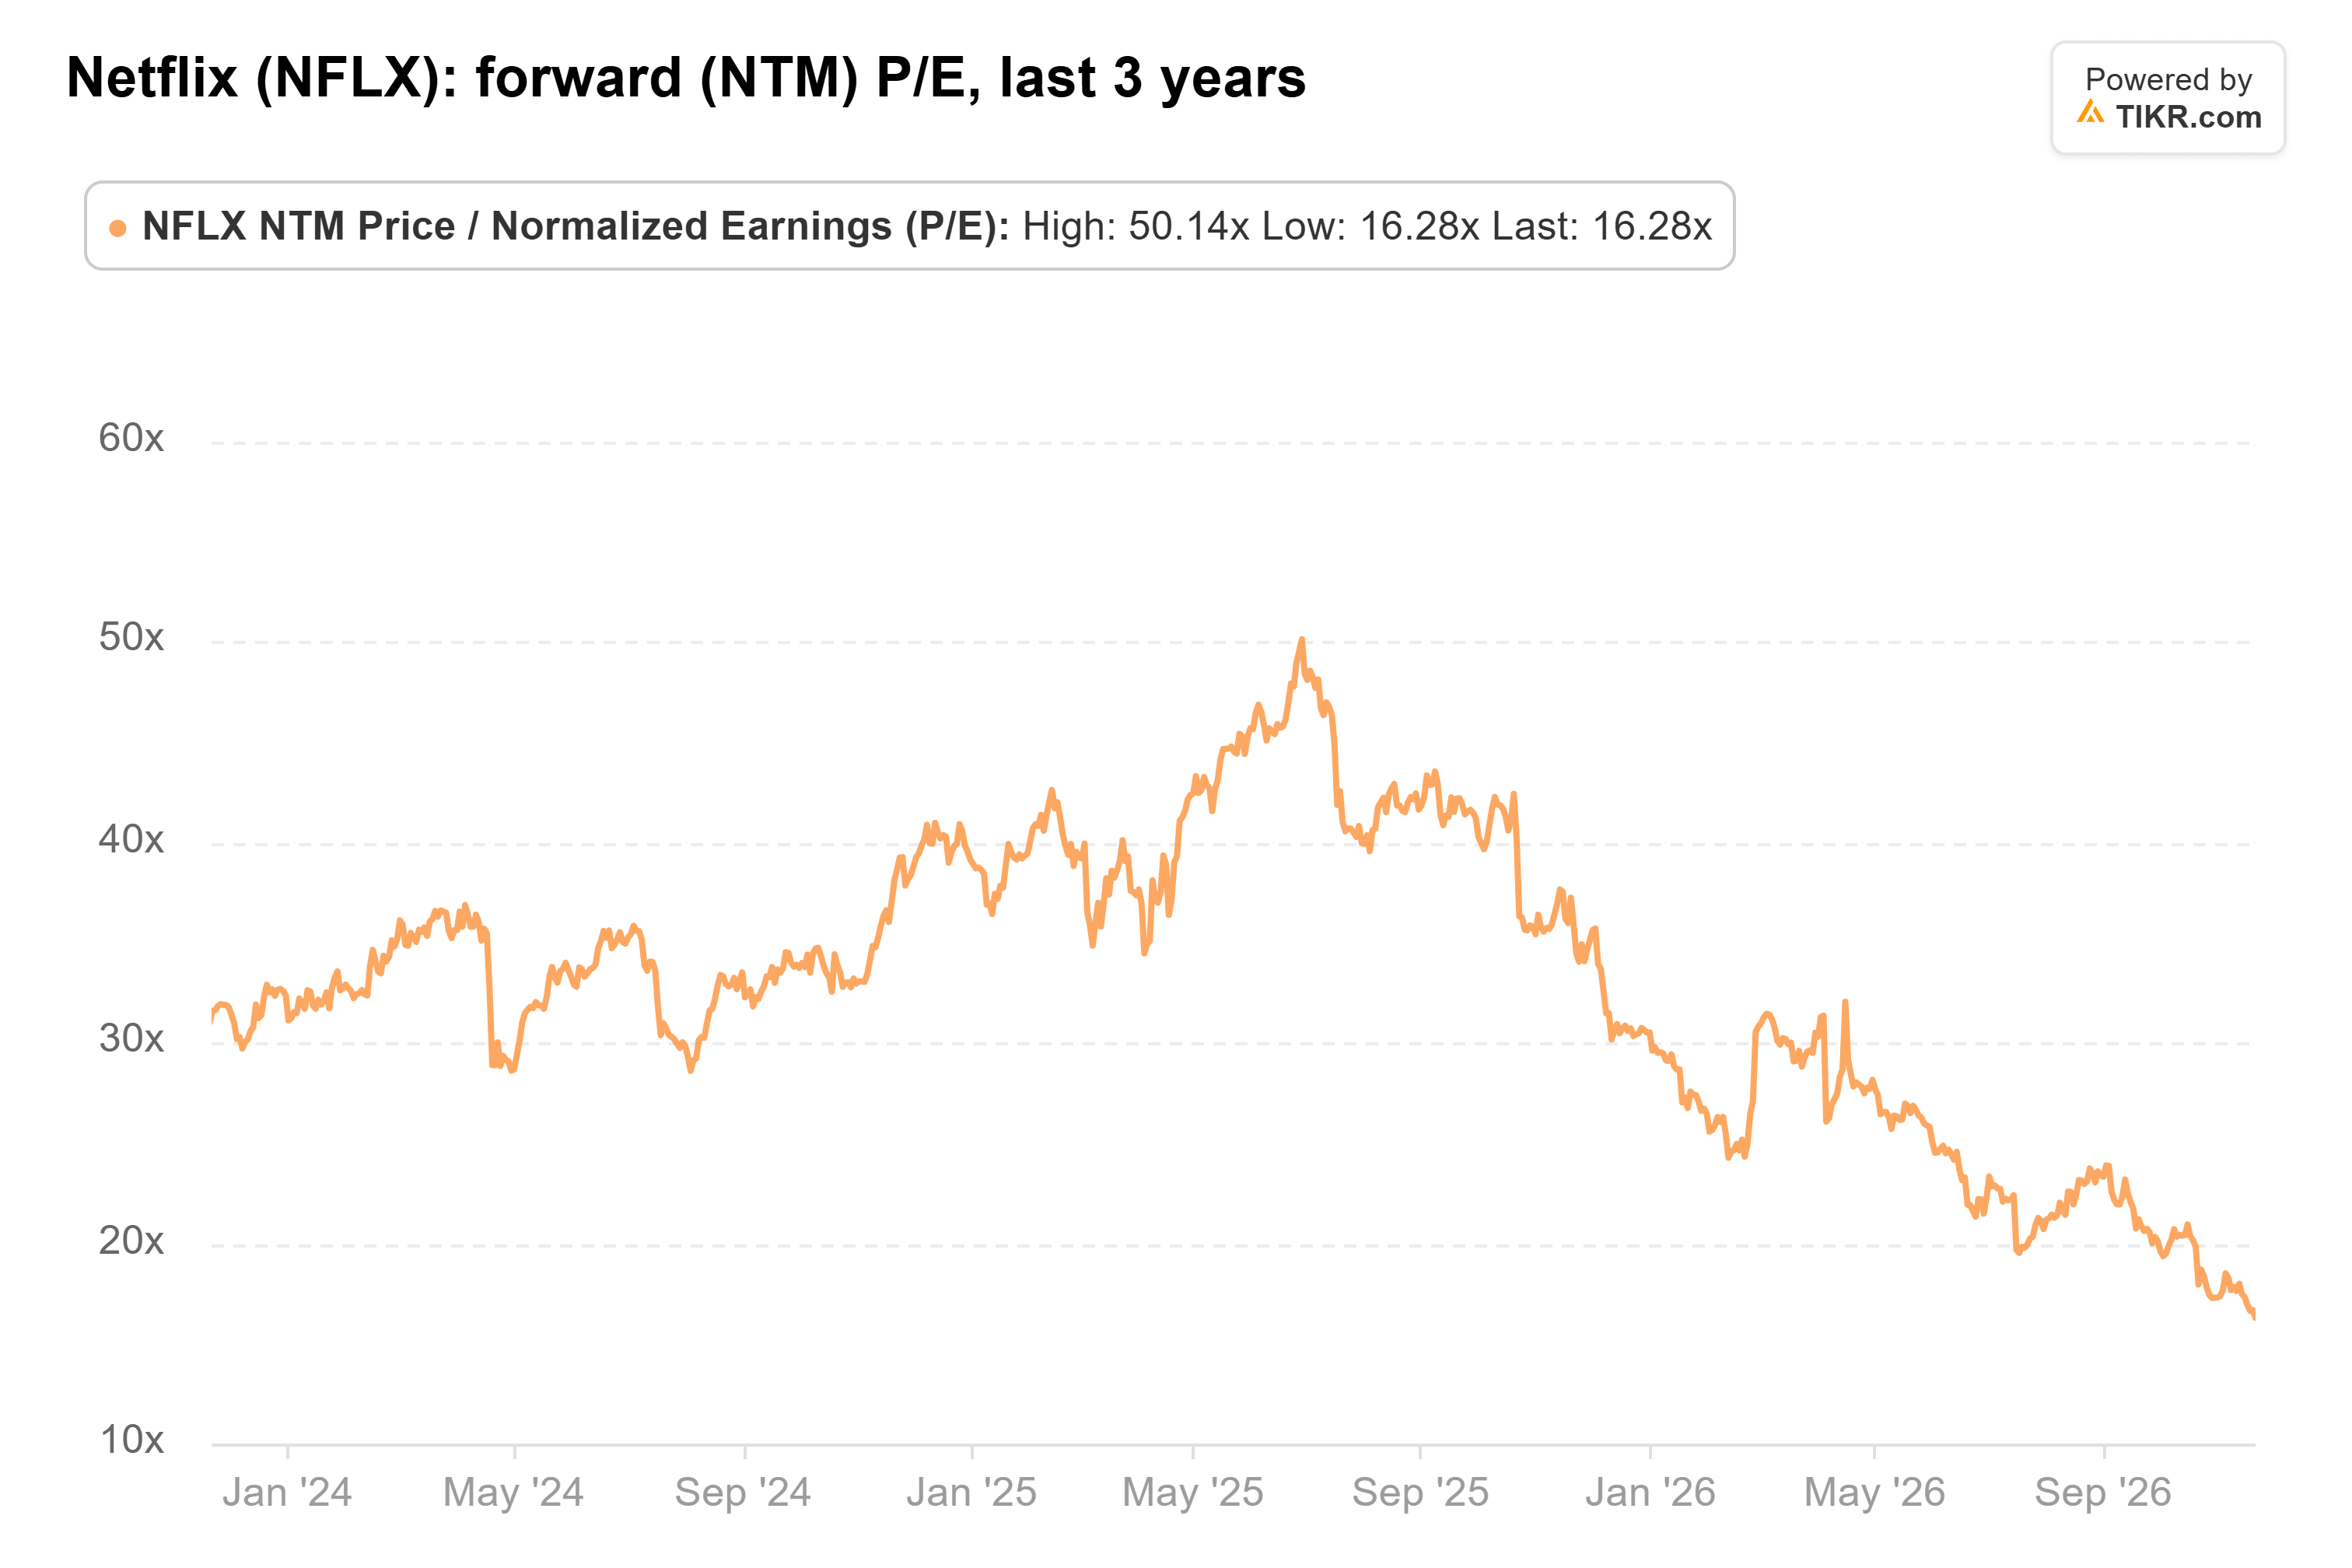
The way I see it, Netflix’s stock moves on revenue and margin, and the company hasn’t needed more hours to grow either one for a while.
As for viewing, Roku reports streaming hours every quarter: 39.9 billion in the third quarter, up 9% year over year. Its fourth-quarter report, expected in February, will cover GTA VI’s first six weeks. Netflix’s own test comes in January. A 2027 revenue guide of 11% or more, with an operating margin near the 33% analysts expect, would show that price and ads are still carrying the business. A guide under 10% would mean the lost hours have caught up with it.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!