Key Takeaways
- Netflix hit a new 52-week low this week, 48% below its high a year ago, while guiding 2026 revenue to a record $51.1 billion.
- Analysts expect 10.8% revenue growth and a 33.3% operating margin in 2027; the stock is priced as if they’re wrong.
- Netflix’s content cash is outrunning amortization, Disney wants higher streaming margins, and Spotify expects slower growth in revenue per user.
- The selloff looks overdone, and January’s 2027 guidance will test that.
Netflix (NFLX) hit a new 52-week low on Nov. 17. At $59.82, the stock sits 48% below its $115.25 high from Nov. 18, 2025.
That’s a lot of pessimism for a company guiding to record revenue. The bet is that Netflix’s price increases are running out of road. That hits Spotify (SPOT), which leans on them too, and matters for Walt Disney (DIS), still chasing the margins Netflix already earns.
Netflix’s Slowdown Is Real, and So Is the Guide
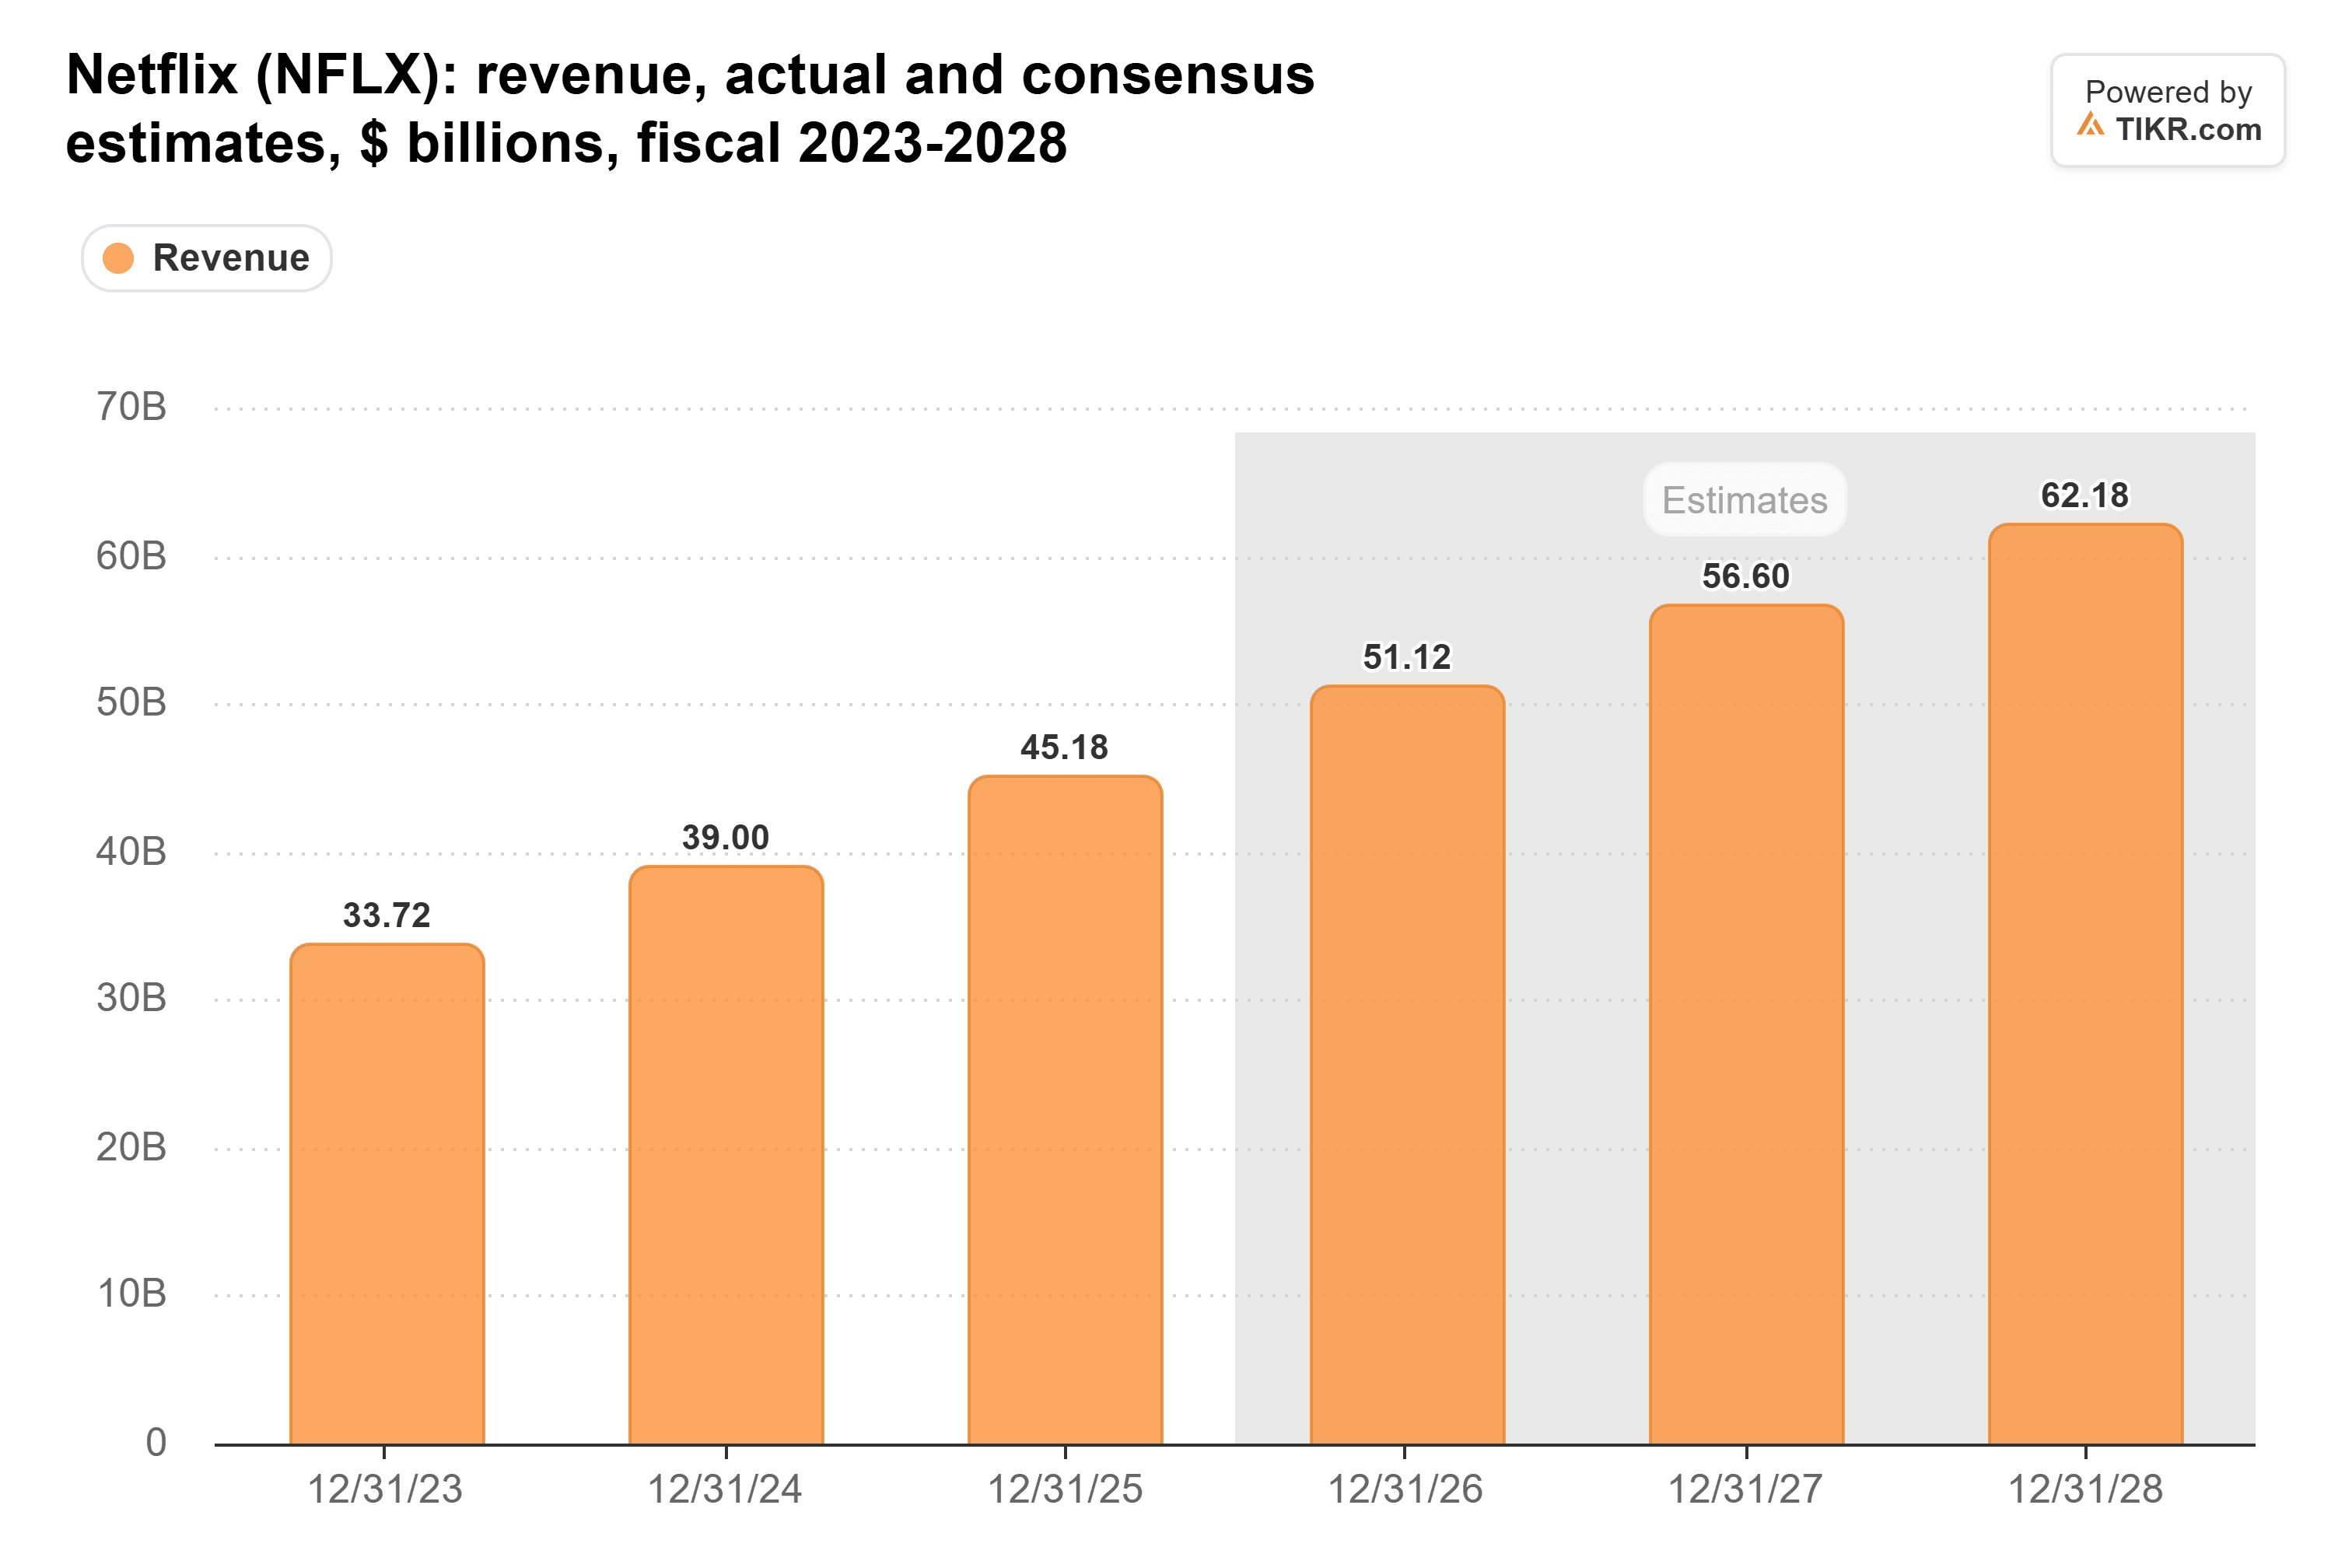
Revenue growth slowed from 17.6% in the fourth quarter of 2025 to 11.8% in the third quarter of 2026, with 11.5% guided for the fourth. U.S. and Canada revenue grew 11%, inside the 8% to 13% range of March’s U.S. price increases. Churn still improved year over year, so members took the higher prices and stayed.
Analysts expect 10.8% growth in 2027 and 9.9% in 2028:
Spotify guides Premium revenue per user to grow 4.5% to 5% in the fourth quarter, down from 7.5% at constant currency. Yet Spotify trades at about 39x forward earnings, more than double Netflix. That’s a wide gap for two companies pulling the same lever.
Earnings Keep Climbing if the Margin Holds
Consensus has earnings per share rising to $4.51 by 2028:
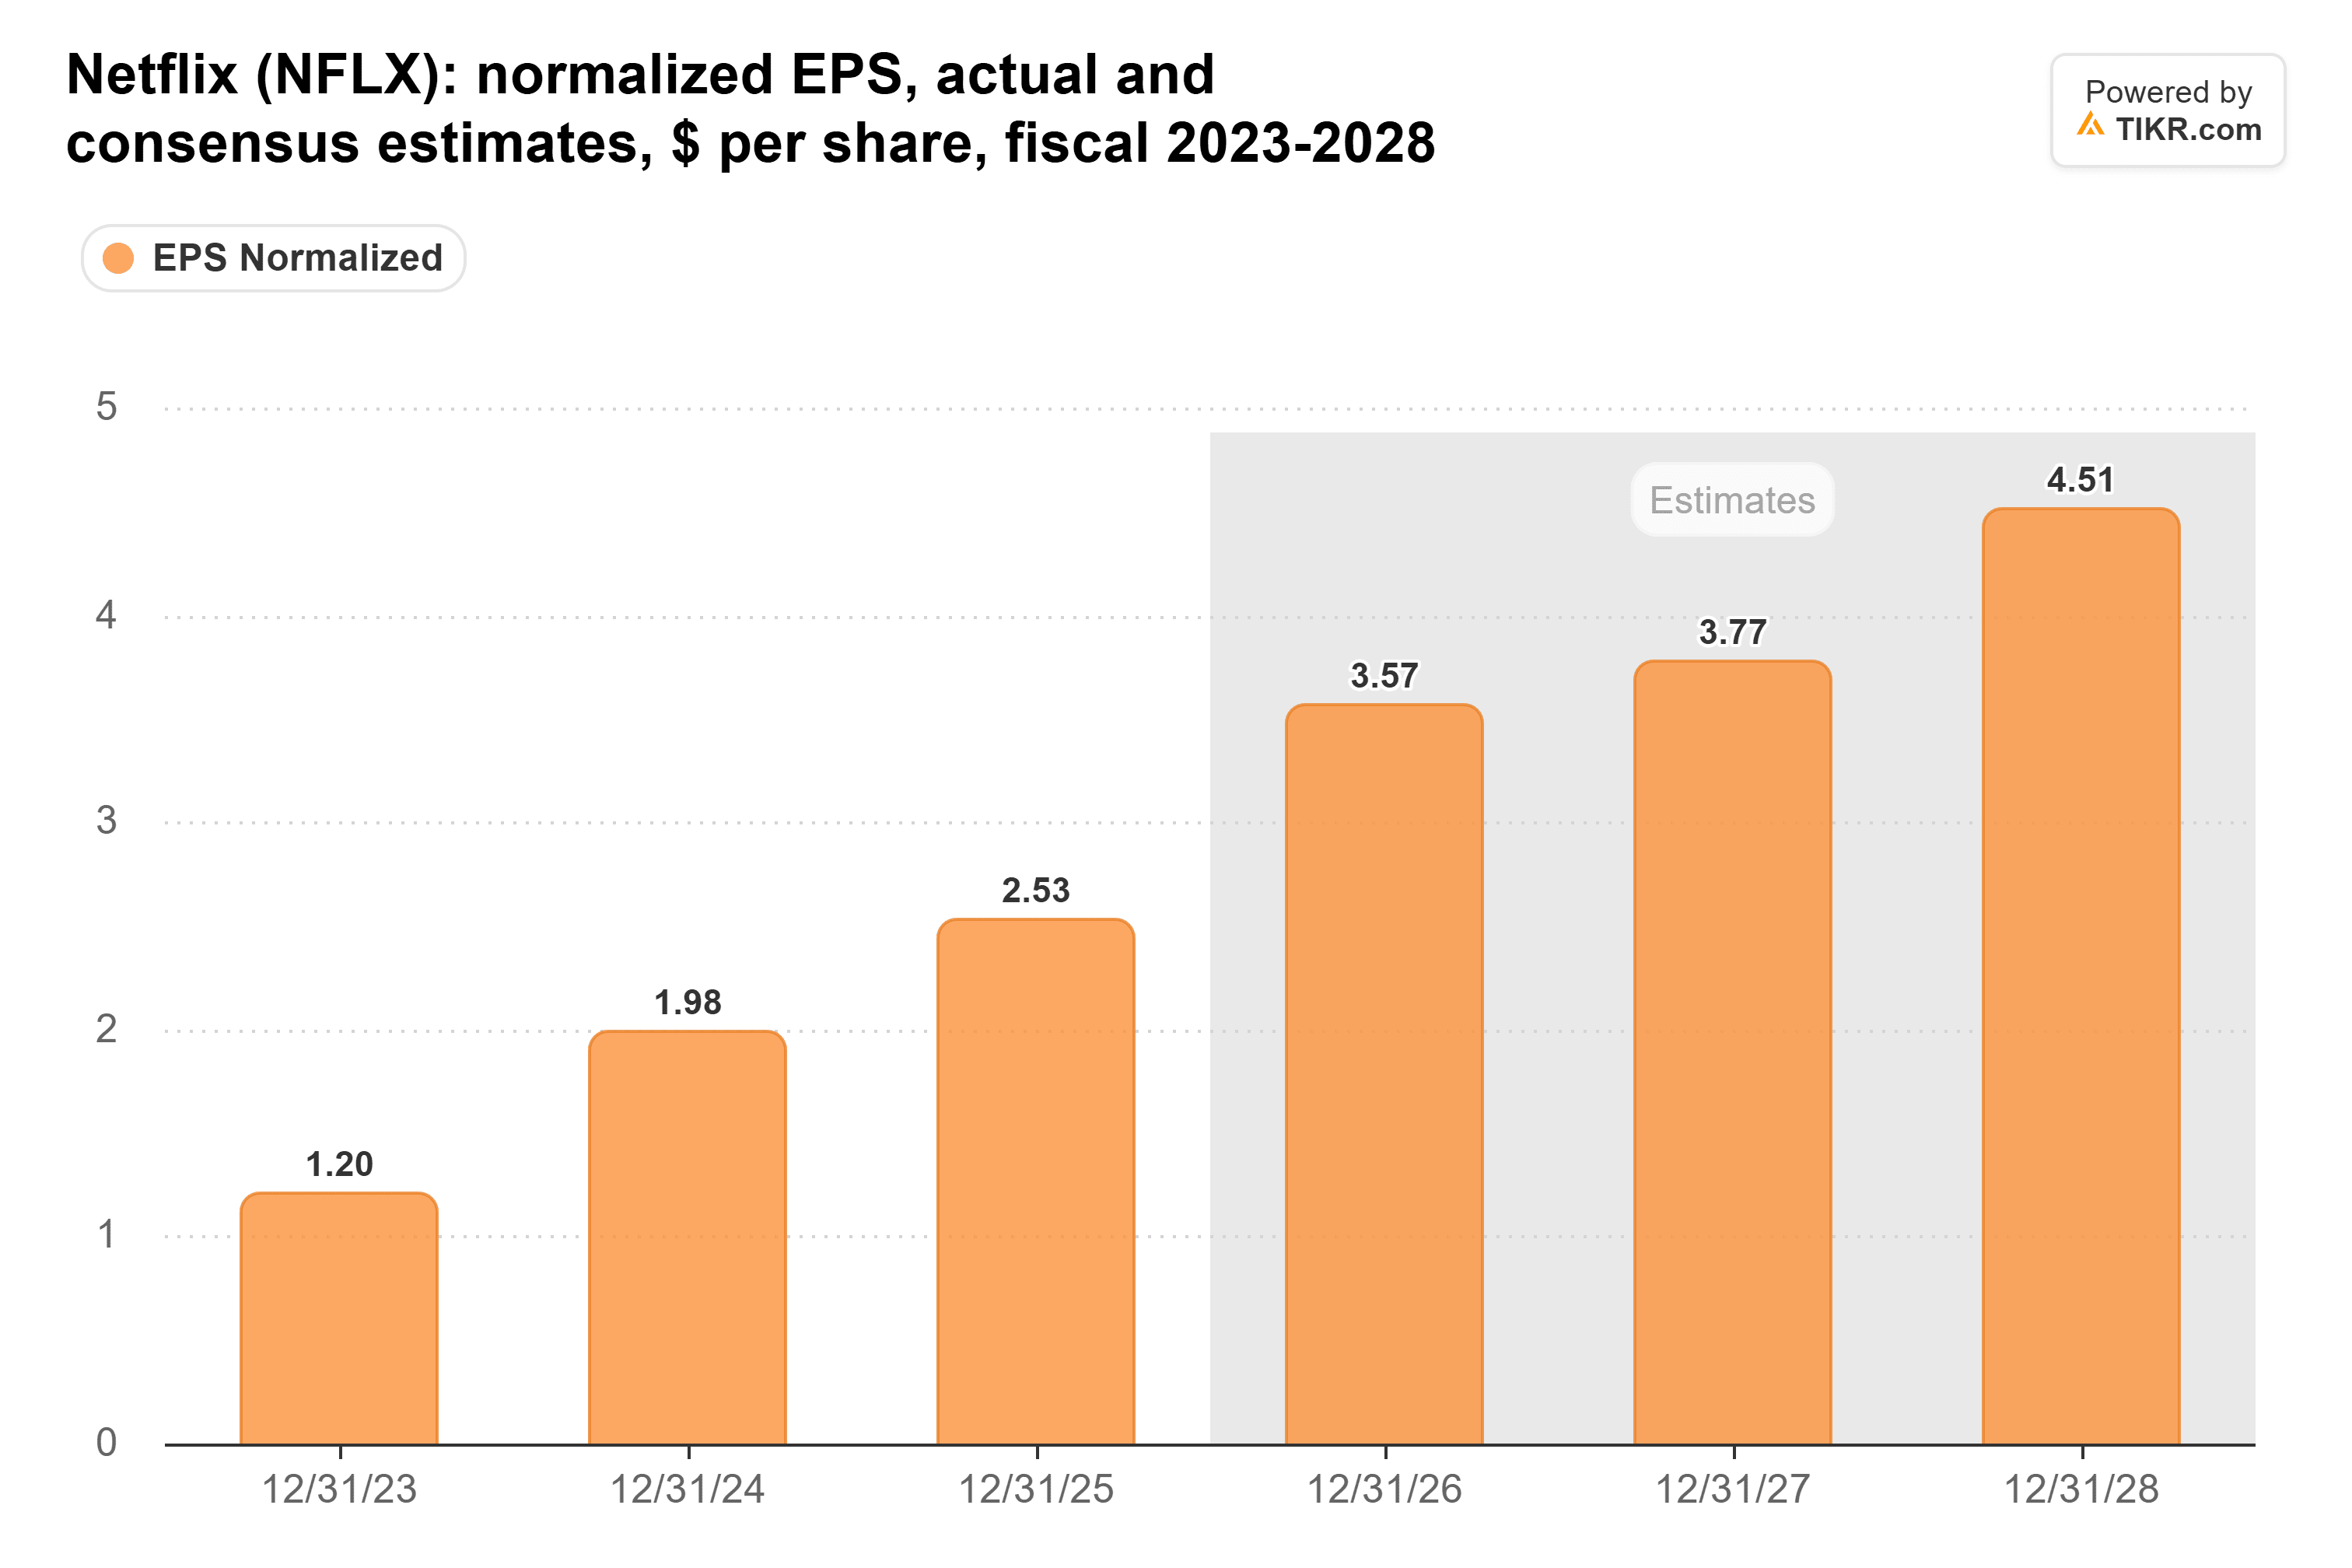
The 2026 estimate of $3.57 includes the one-time $2.8 billion Warner Bros. Discovery termination fee from the first quarter, so 2027’s growth looks smaller than it is. Analysts expect operating income to rise 17% in 2027, to $18.9 billion, on a 33.3% margin, up from this year’s 31.5% guide.
TIKR Tracks 51 Analysts on Netflix. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
The margin is the weak spot. Netflix paid $15.0 billion for content in the first nine months of 2026, up 18.5%, while amortization rose 9.5% to $12.8 billion. Most of it hits expenses within four years of each title’s release.
Disney shows how hard that margin is to earn. Its Disney+ and Hulu subscription business posted an 11.5% operating margin for fiscal 2026. Bloomberg Intelligence senior media analyst Geetha Ranganathan asked on a Bloomberg podcast this week: “can we get to those 30% margins that Netflix has shown us? I mean, that’s the big question.”
Netflix’s Price Assumes the Estimates Miss
The selloff pushed Netflix’s forward P/E to the bottom of its five-year range:
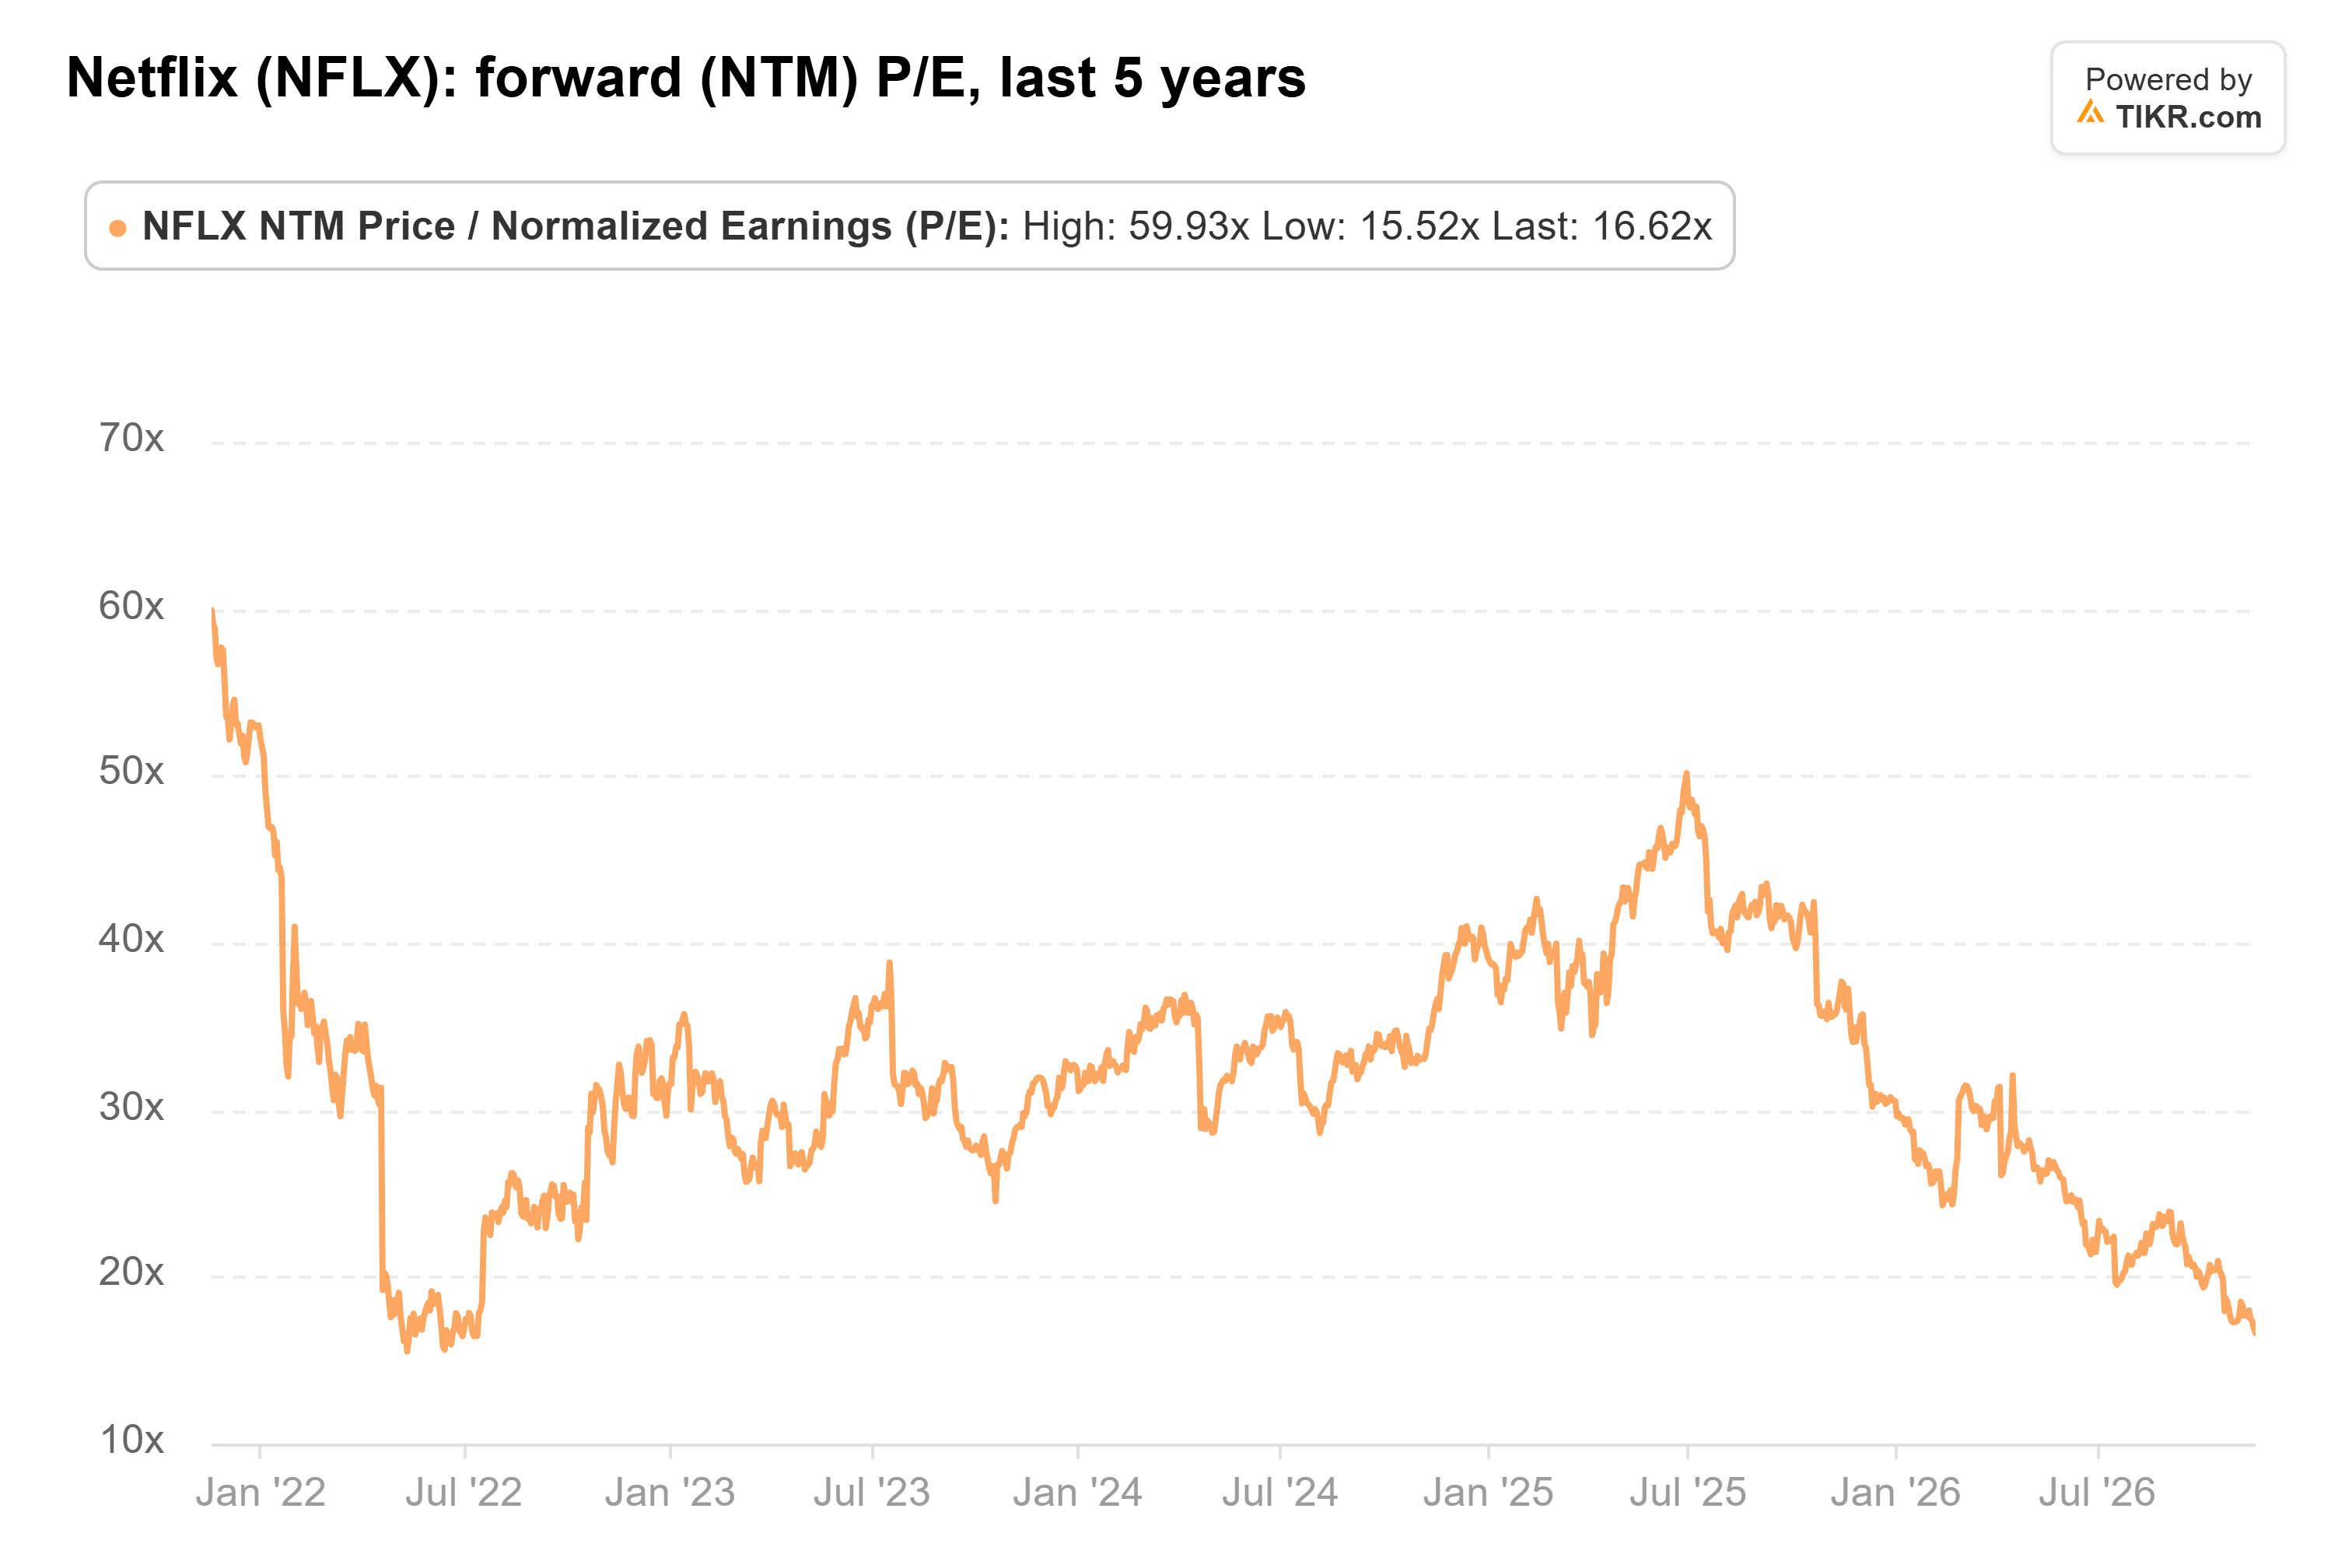
Netflix trades at about 17x forward earnings, against a five-year average of 32x and a low of about 16x in May 2022. On the 2028 estimate of $4.51, it’s about 13x. Cheap for a business growing revenue near 10% a year.
January Settles It
I think the selloff has gone further than the numbers justify. The revenue guide has held all year, at $51.1 billion now, inside January’s $50.7 billion to $51.7 billion range. Even a 2027 margin short of 33.3% wouldn’t make it expensive.
A 2027 revenue guide of 11% or more, with a margin at or above 33.3%, would back the bull case. A revenue guide below 10%, or a margin near 32%, would mean the sellers had it right.
So What Is Netflix Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!