Key Takeaways
- One investor’s reverse DCF finds Apple’s near-record price needs 16.9% annual free cash flow growth for 10 years, three times its five-year revenue growth.
- That only works if fiscal 2026’s 15% revenue growth becomes normal, or margins rise far above 28.4%.
- Apple blames memory prices for its falling gross margin, while Micron and Sandisk guide to margins of about 85% or more.
- Analysts expect about 11% annual free cash flow growth through fiscal 2029; at 37x forward earnings, the stock is priced for more.
Apple (AAPL) has become the stock investors hide in. It’s the only Magnificent Seven stock near its record close, set on Nov. 13.
One investor on r/ValueInvesting worked out what that safety costs: Apple’s price needs free cash flow to grow 16.9% a year for 10 years.
That’s a tall order while memory makers like Micron (MU) and Sandisk (SNDK) squeeze Apple’s margin.
Wall Street Sees About 11%
The poster used trailing free cash flow, a 9% discount rate and no growth after year 10. Rerun on Apple’s $136.1 billion of fiscal 2026 free cash flow, 16.9% a year lands right at its roughly $5.1 trillion market value.
Analysts aren’t close:
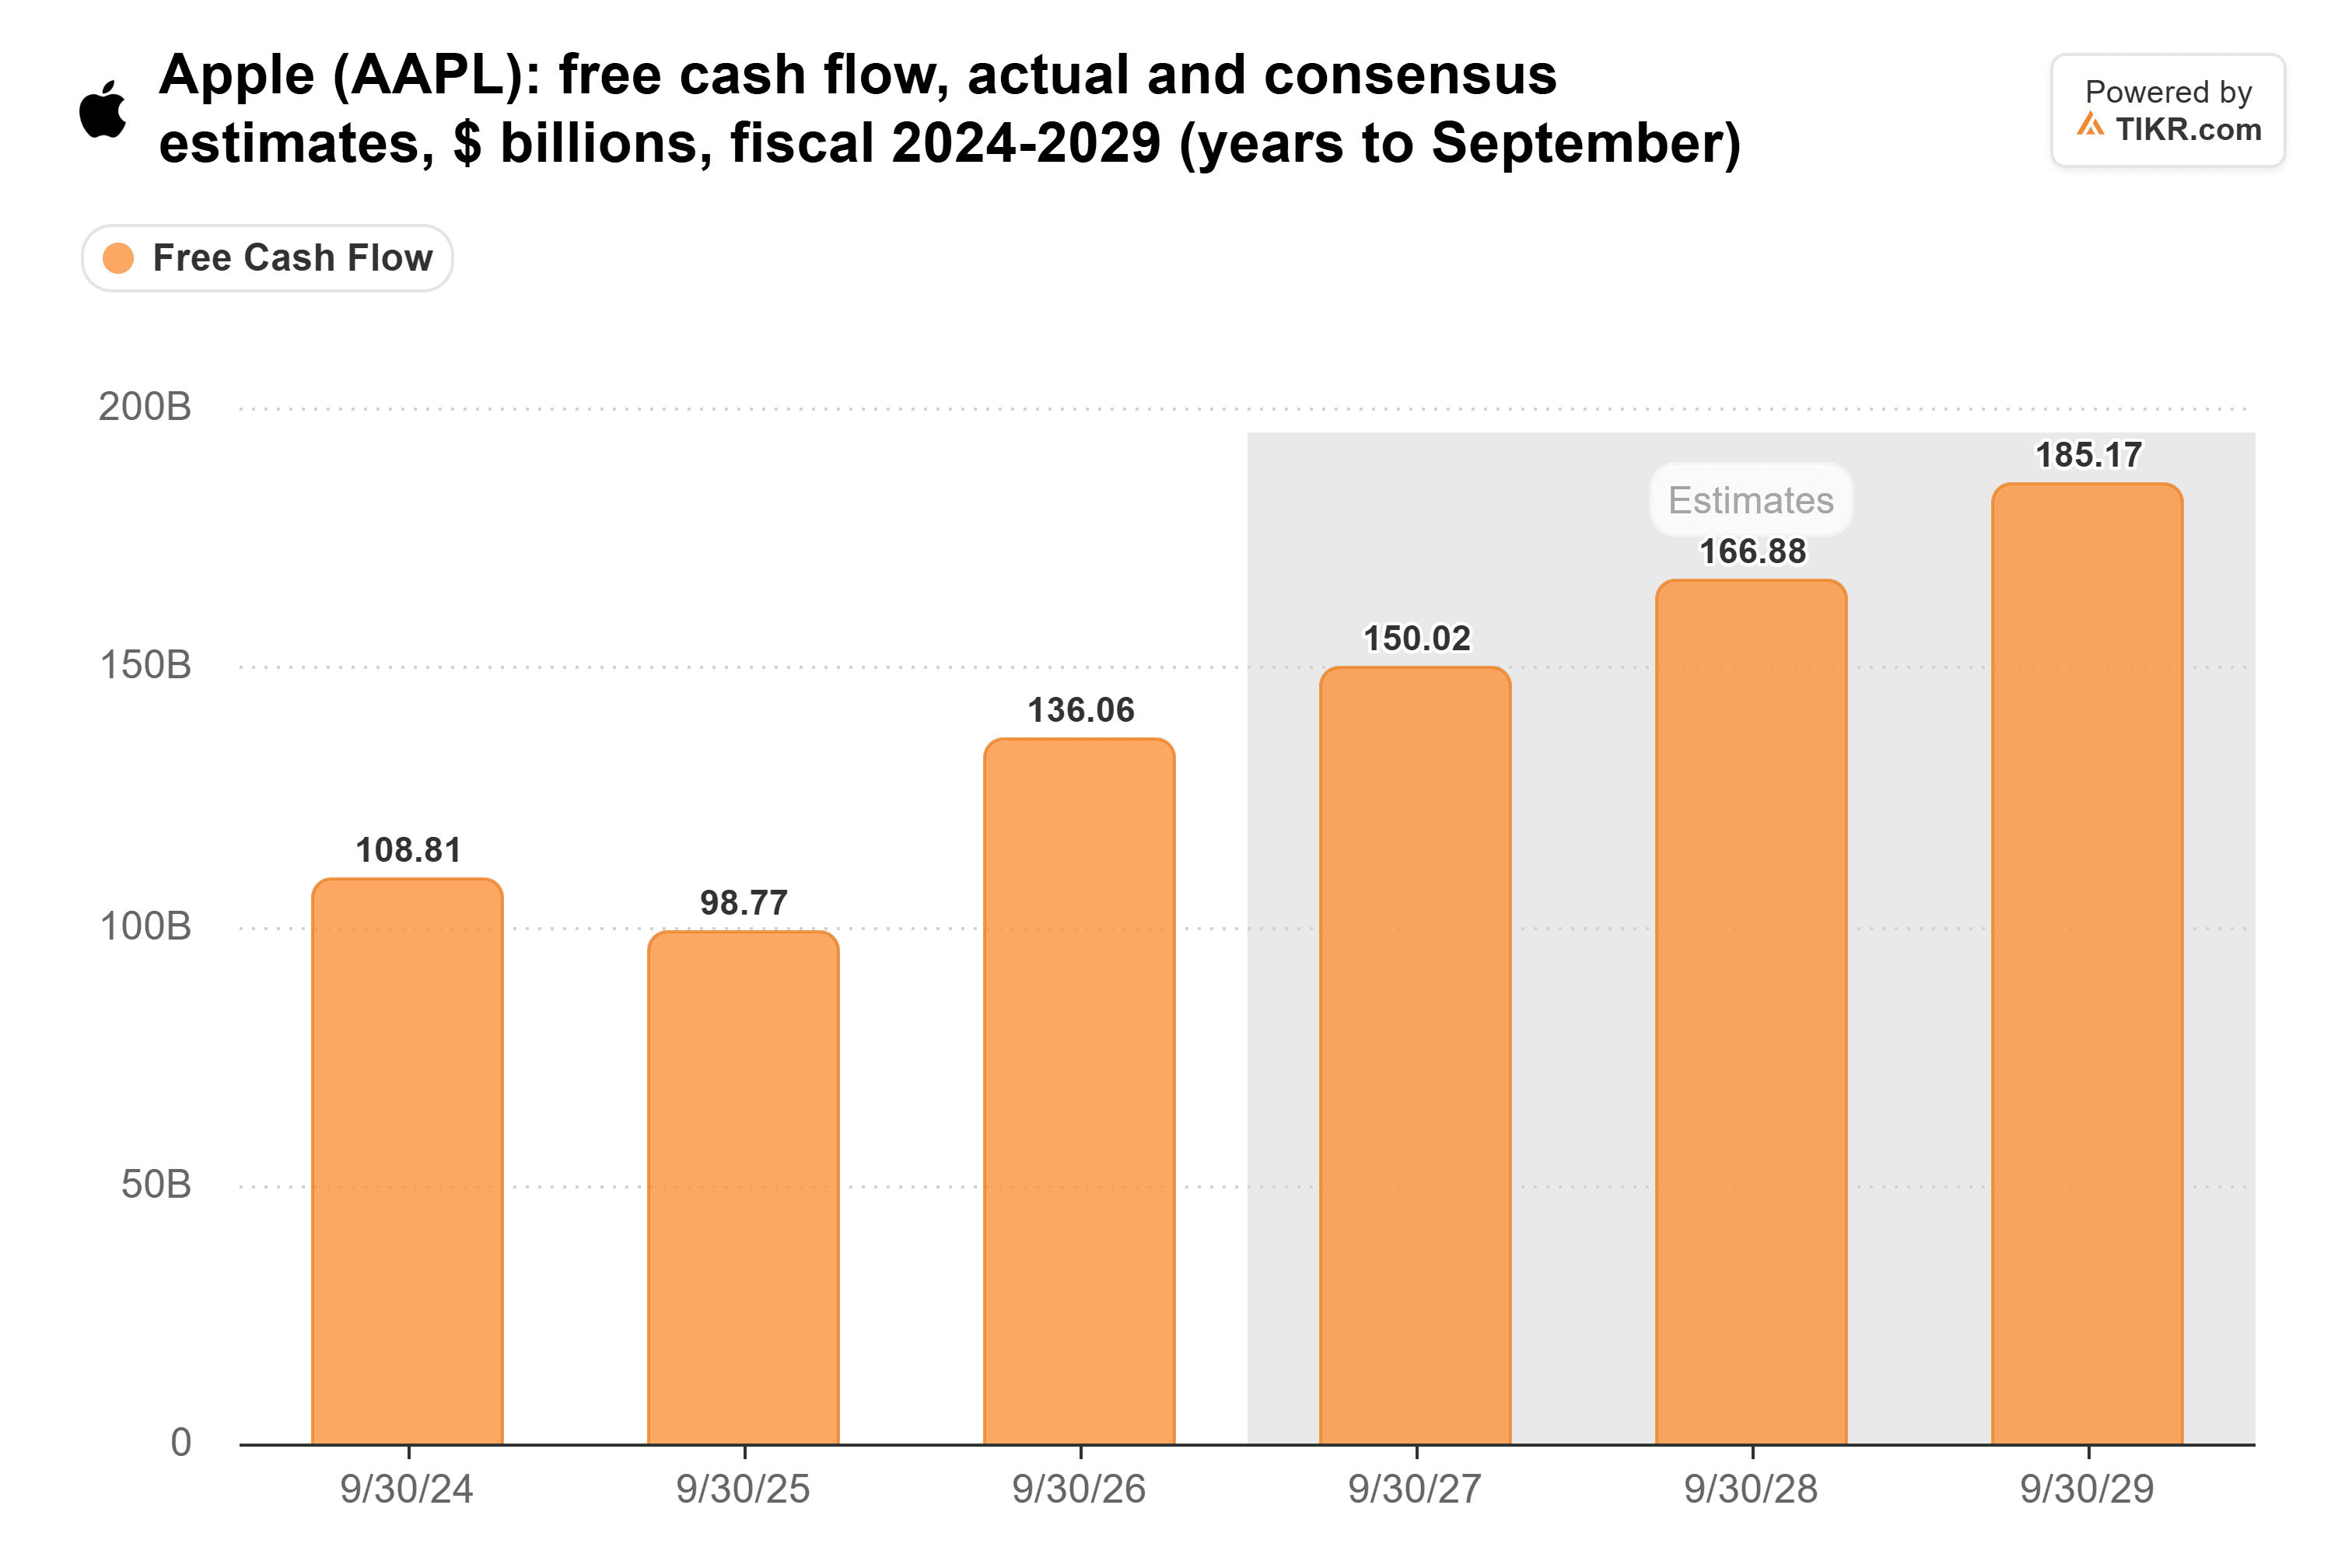
Consensus has free cash flow reaching $185 billion in fiscal 2029, about 11% a year. At 16.9%, fiscal 2029 would need about $217 billion.
Fiscal 2026 Has to Be Apple’s New Normal
Revenue has grown in fits and starts:
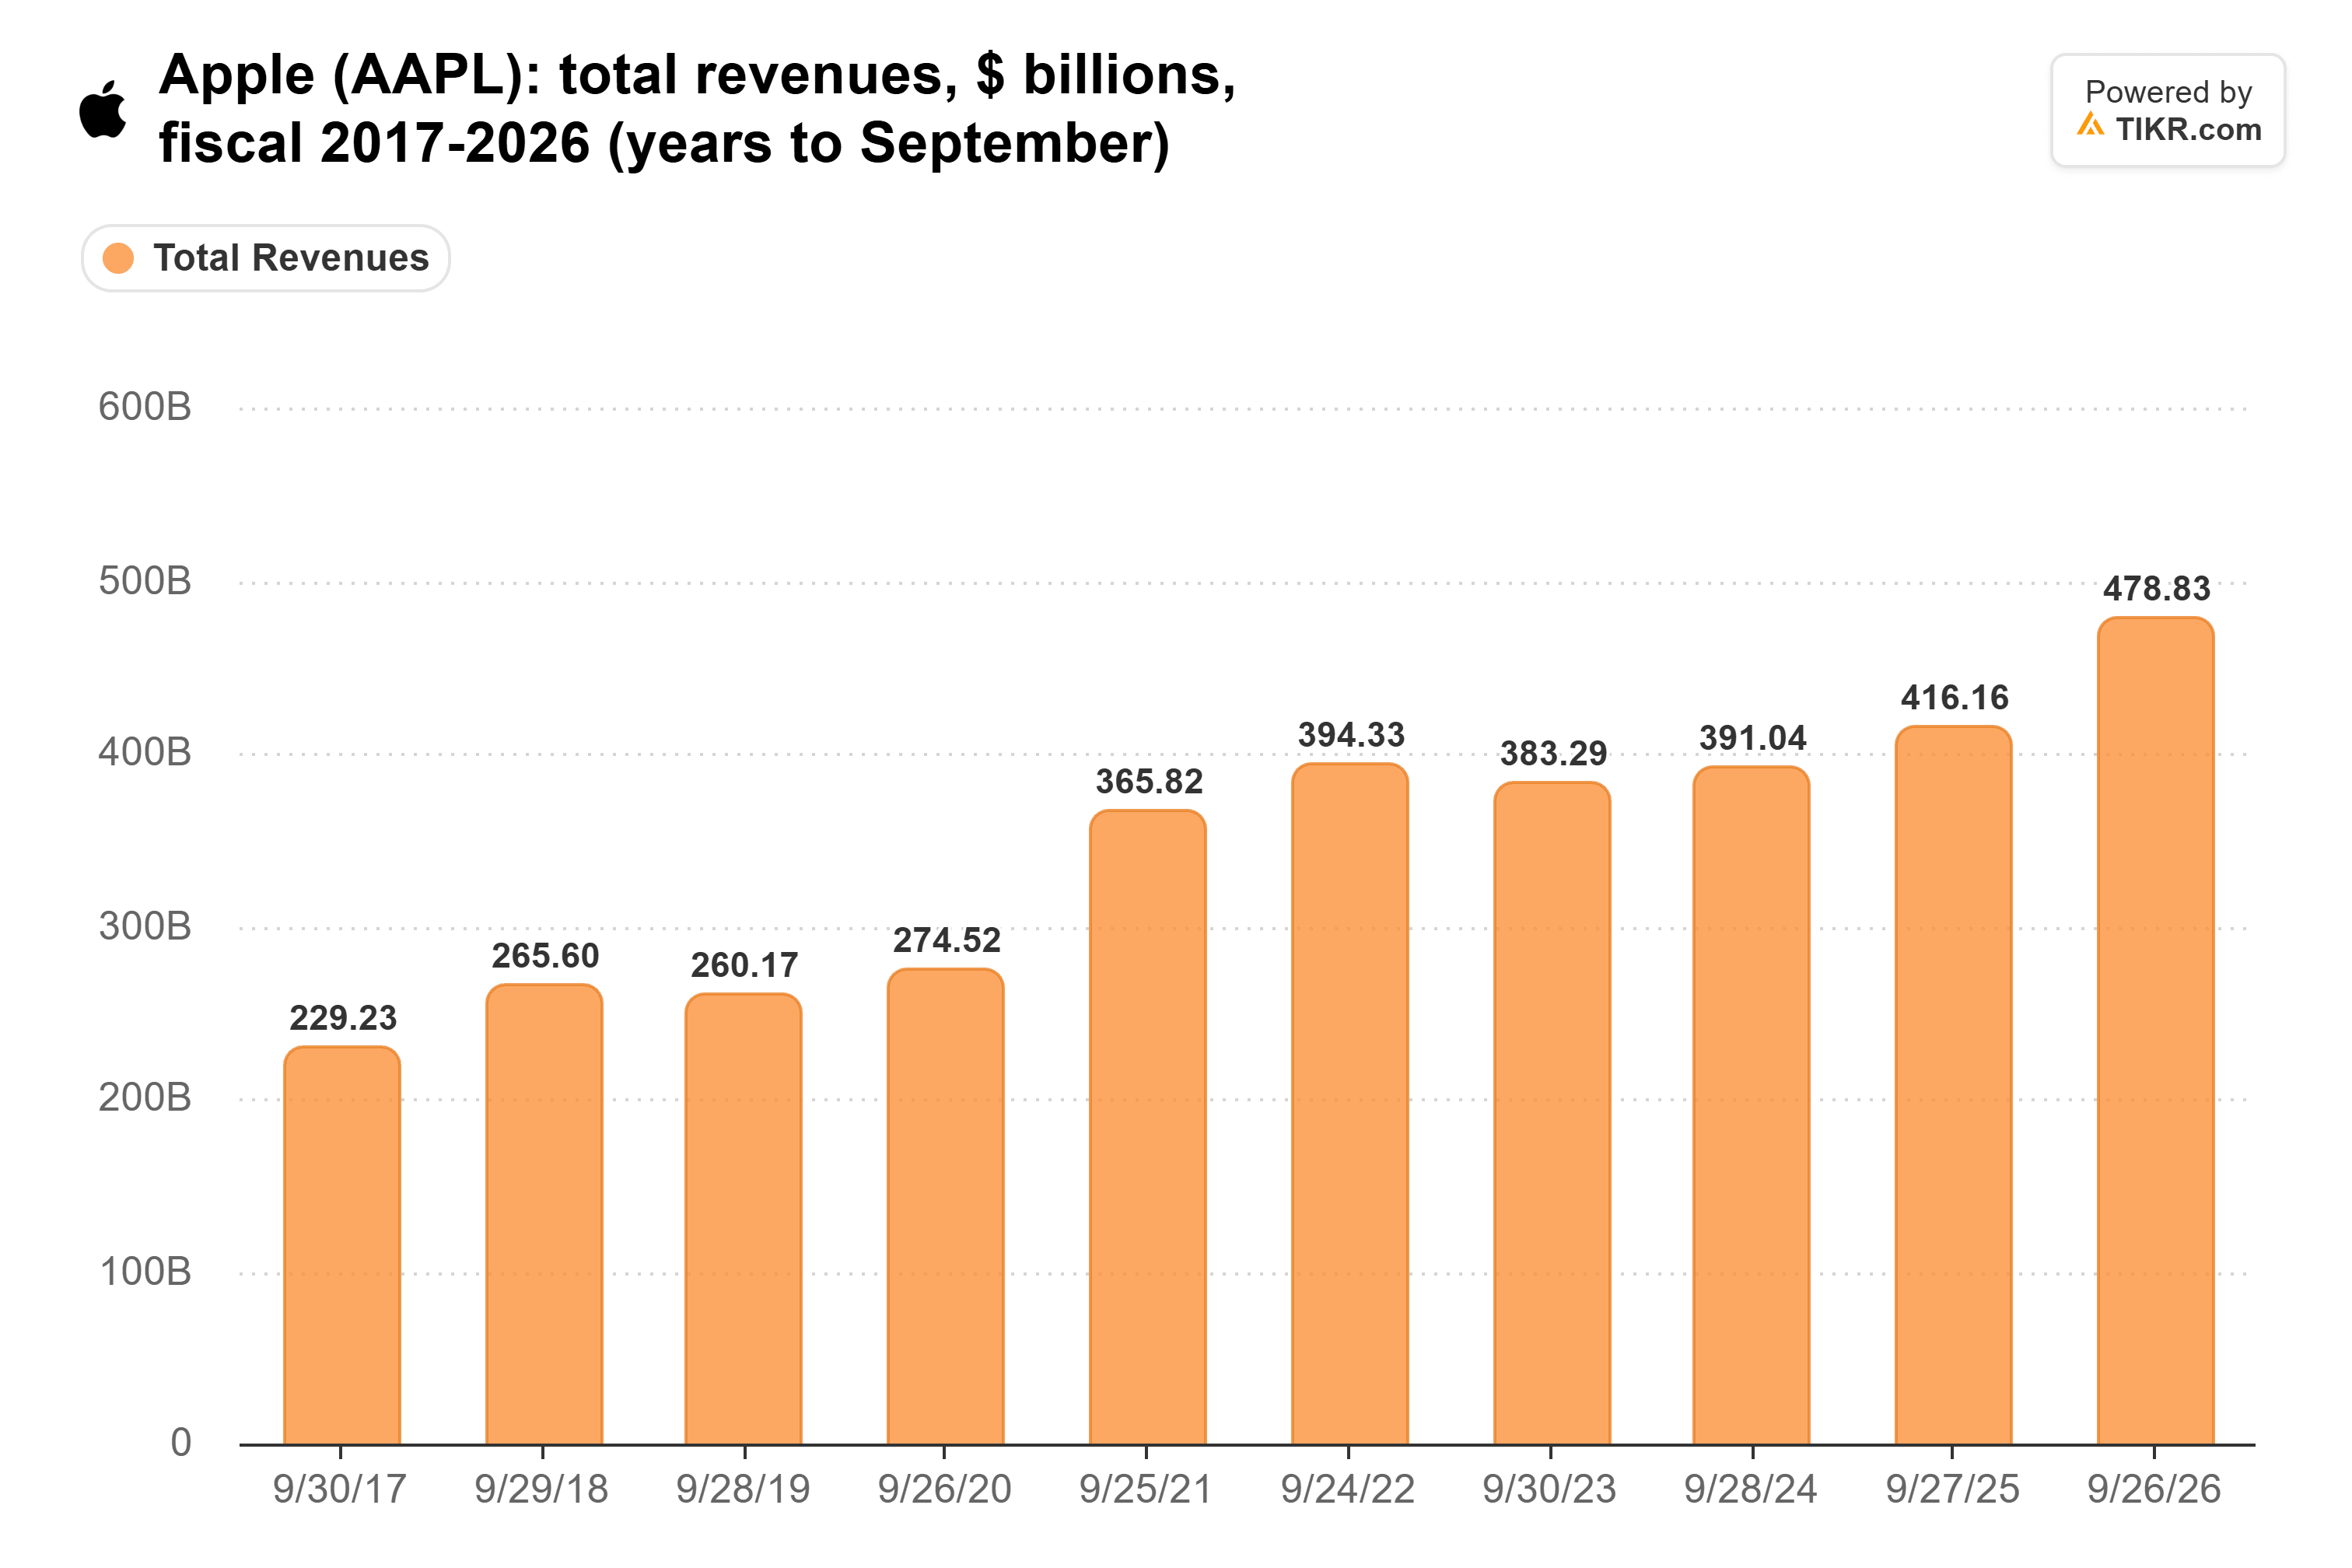
From $366 billion in fiscal 2021 to $479 billion in fiscal 2026, revenue grew 5.5% a year. At that pace, Apple’s free cash flow margin would need to climb from 28.4% to about 79% by year 10. Nobody expects that from a phone maker.
Fiscal 2026 alone grew revenue 15.0%. At that pace, the margin only needs to reach about 33%. Barring a margin miracle, today’s price bets that pace holds for a decade.
The trouble is what drives growth now. UBS expects December-quarter iPhone revenue to rise 12% even as units fall 3%, so revenue per iPhone rises 15.5%. Free cash flow’s 38% jump flatters the trend, too, since a one-time EU tax payment held down fiscal 2025 and capex fell 29%.
TIKR Tracks 45 Analysts on Apple. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Memory Makers Hold the Pricing Power
In July, CFO Kevan Parekh said memory explained more than 100% of Apple’s gross margin decline, excluding tariff refunds. On Nov. 2, Apple guided December-quarter gross margin to 45% to 46%, below the 48.1% it earned in the June quarter before tariff refunds.
Apple’s lost margin shows up at its suppliers. Micron’s Mobile and Client unit, which sells to phone and PC makers, earned a 90% gross margin last quarter, up from 36% a year earlier. Micron and Sandisk both guide to non-GAAP gross margins of about 85% or more. Until those guides come down, Apple’s margin climb runs uphill.
Paying 37x for Apple’s Safety
Apple trades at 37x forward earnings, close to its 10-year high of 38x in October and well above its 25x average:
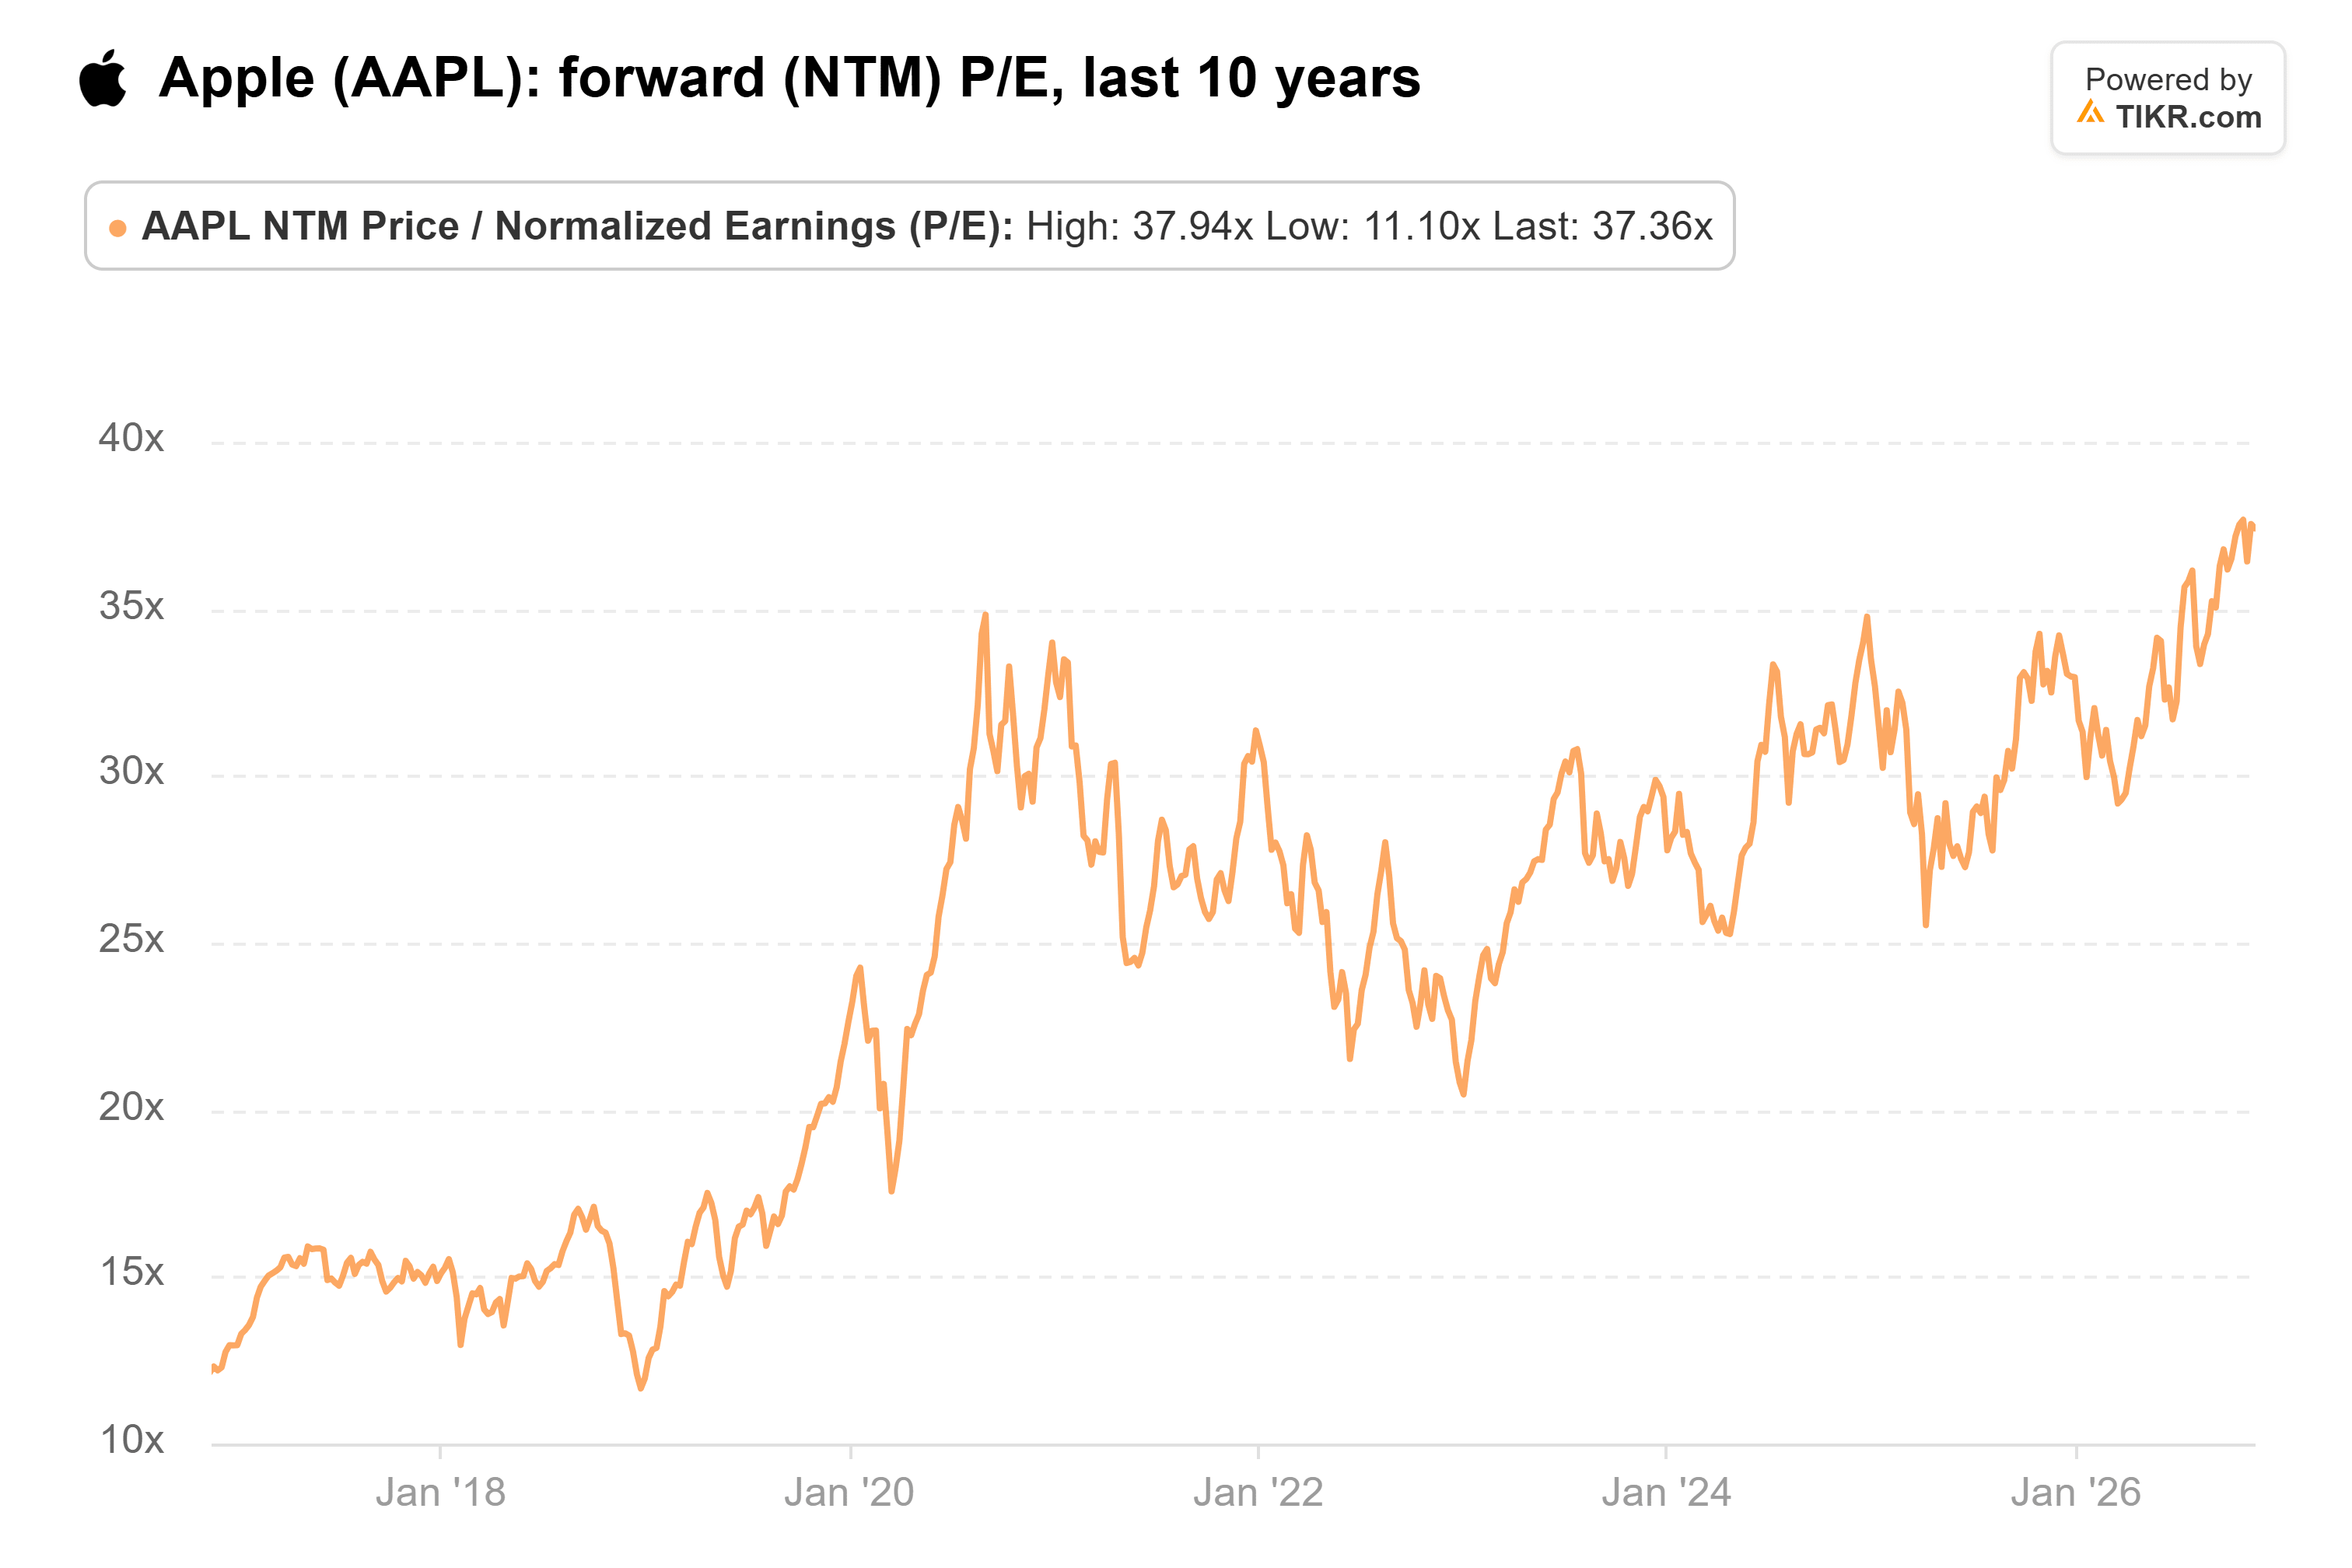
Stretch the growth period to 15 years, though, and Apple needs 12.5% a year, within two points of what analysts expect.
This is a great business priced as if its best year in a while is the floor. I’d wait for a better price.
Micron’s report, expected in mid-December, is the first check. Watch its mobile memory pricing commentary. Then Apple’s December quarter needs revenue at the top of its 7% to 10% guide, with gross margin holding, to make the bet look reasonable.
So What Is Apple Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!