Key Takeaways
- Nvidia raised its fiscal 2028 revenue growth outlook to about 75%, from 70%, while analysts expect about 69%.
- D.A. Davidson’s Gil Luria calls the 75% a proxy for the whole AI ecosystem and expects Microsoft, Amazon and Alphabet to raise capex 25% to 50% next year.
- Nvidia trades at 9.3x fiscal 2028 consensus EPS. If revenue grows only 25% and EPS falls in step, it would trade at about 12.6x.
Nvidia (NVDA) just raised the bar again. On its third-quarter call on Nov. 17, interim CEO Colette Kress lifted the company’s fiscal 2028 outlook to about 75% revenue growth, from 70%.
Nvidia fell 2.9% to $150.96 on Nov. 18. On that day’s Prof G Markets podcast, D.A. Davidson analyst Gil Luria explained why he thought growth could fall short of Nvidia’s outlook:
“When we say Nvidia is going to grow 75% next year, that’s a proxy for the whole ecosystem. Maybe we don’t grow 75%. Maybe we grow 25% to 50%.”
He tied that slower pace to the biggest buyers, expecting Microsoft (MSFT), Amazon (AMZN) and Alphabet (GOOG) to spend “25 to 50% more CapEx” next year. Last quarter, Amazon’s cash capex was $75.9 billion, Alphabet’s $51.4 billion and Microsoft’s $45.2 billion, including finance leases.
Nvidia’s 75% Is Everyone’s Number
Part of that ecosystem runs on debt. “Remember, it’s the borrowing that makes bubbles,” Luria said, pointing to tighter credit for neoclouds like CoreWeave. CoreWeave has said it will avoid unsecured debt at current yields and borrow against customer contracts instead.
In August, Kress pointed to expectations of about $1.3 trillion of capex from the top five hyperscalers in 2027, up from about $800 billion this year. That’s growth of more than 60%, above the top of Luria’s range.
Luria doesn’t expect a pullback, “because again, the demand is there.” Still, Alphabet’s free cash flow was negative $9.1 billion last quarter, partly because of a $5.2 billion European Commission fine.
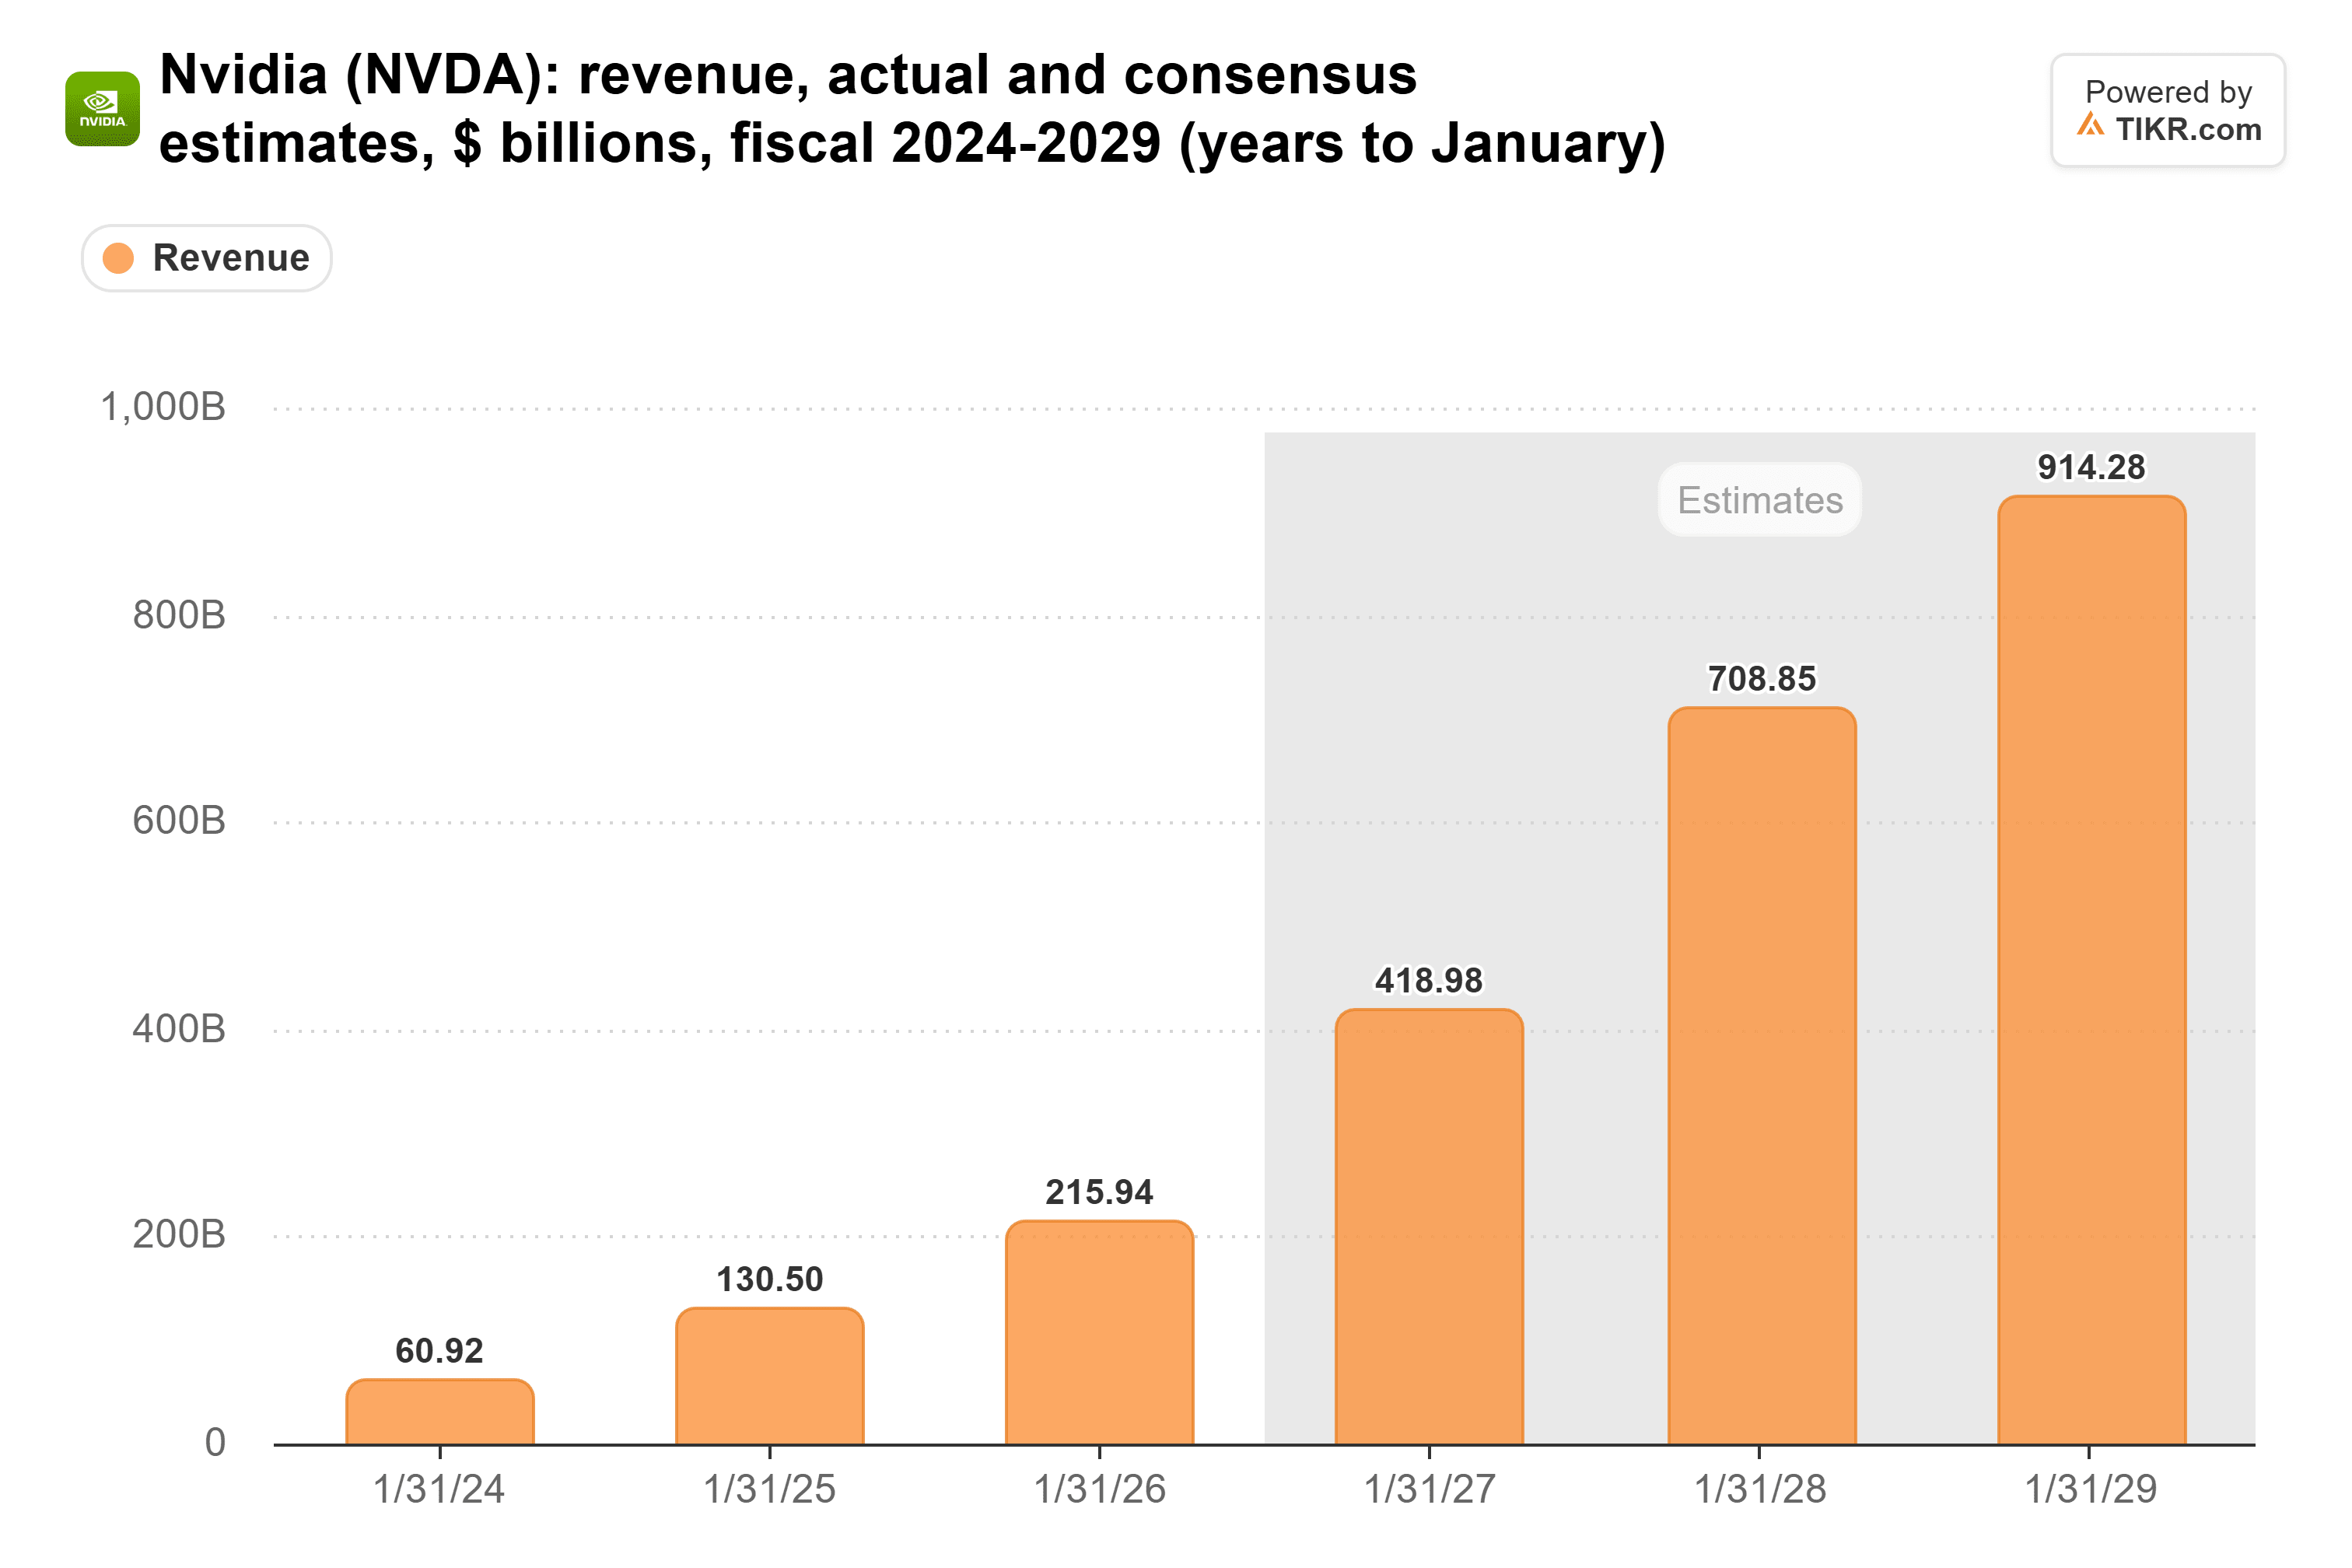
Analysts expect $709 billion of revenue in fiscal 2028, about 69% more than the $419 billion they expect for fiscal 2027:
TIKR Tracks 63 Analysts on Nvidia. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Even 25% Looks Priced In
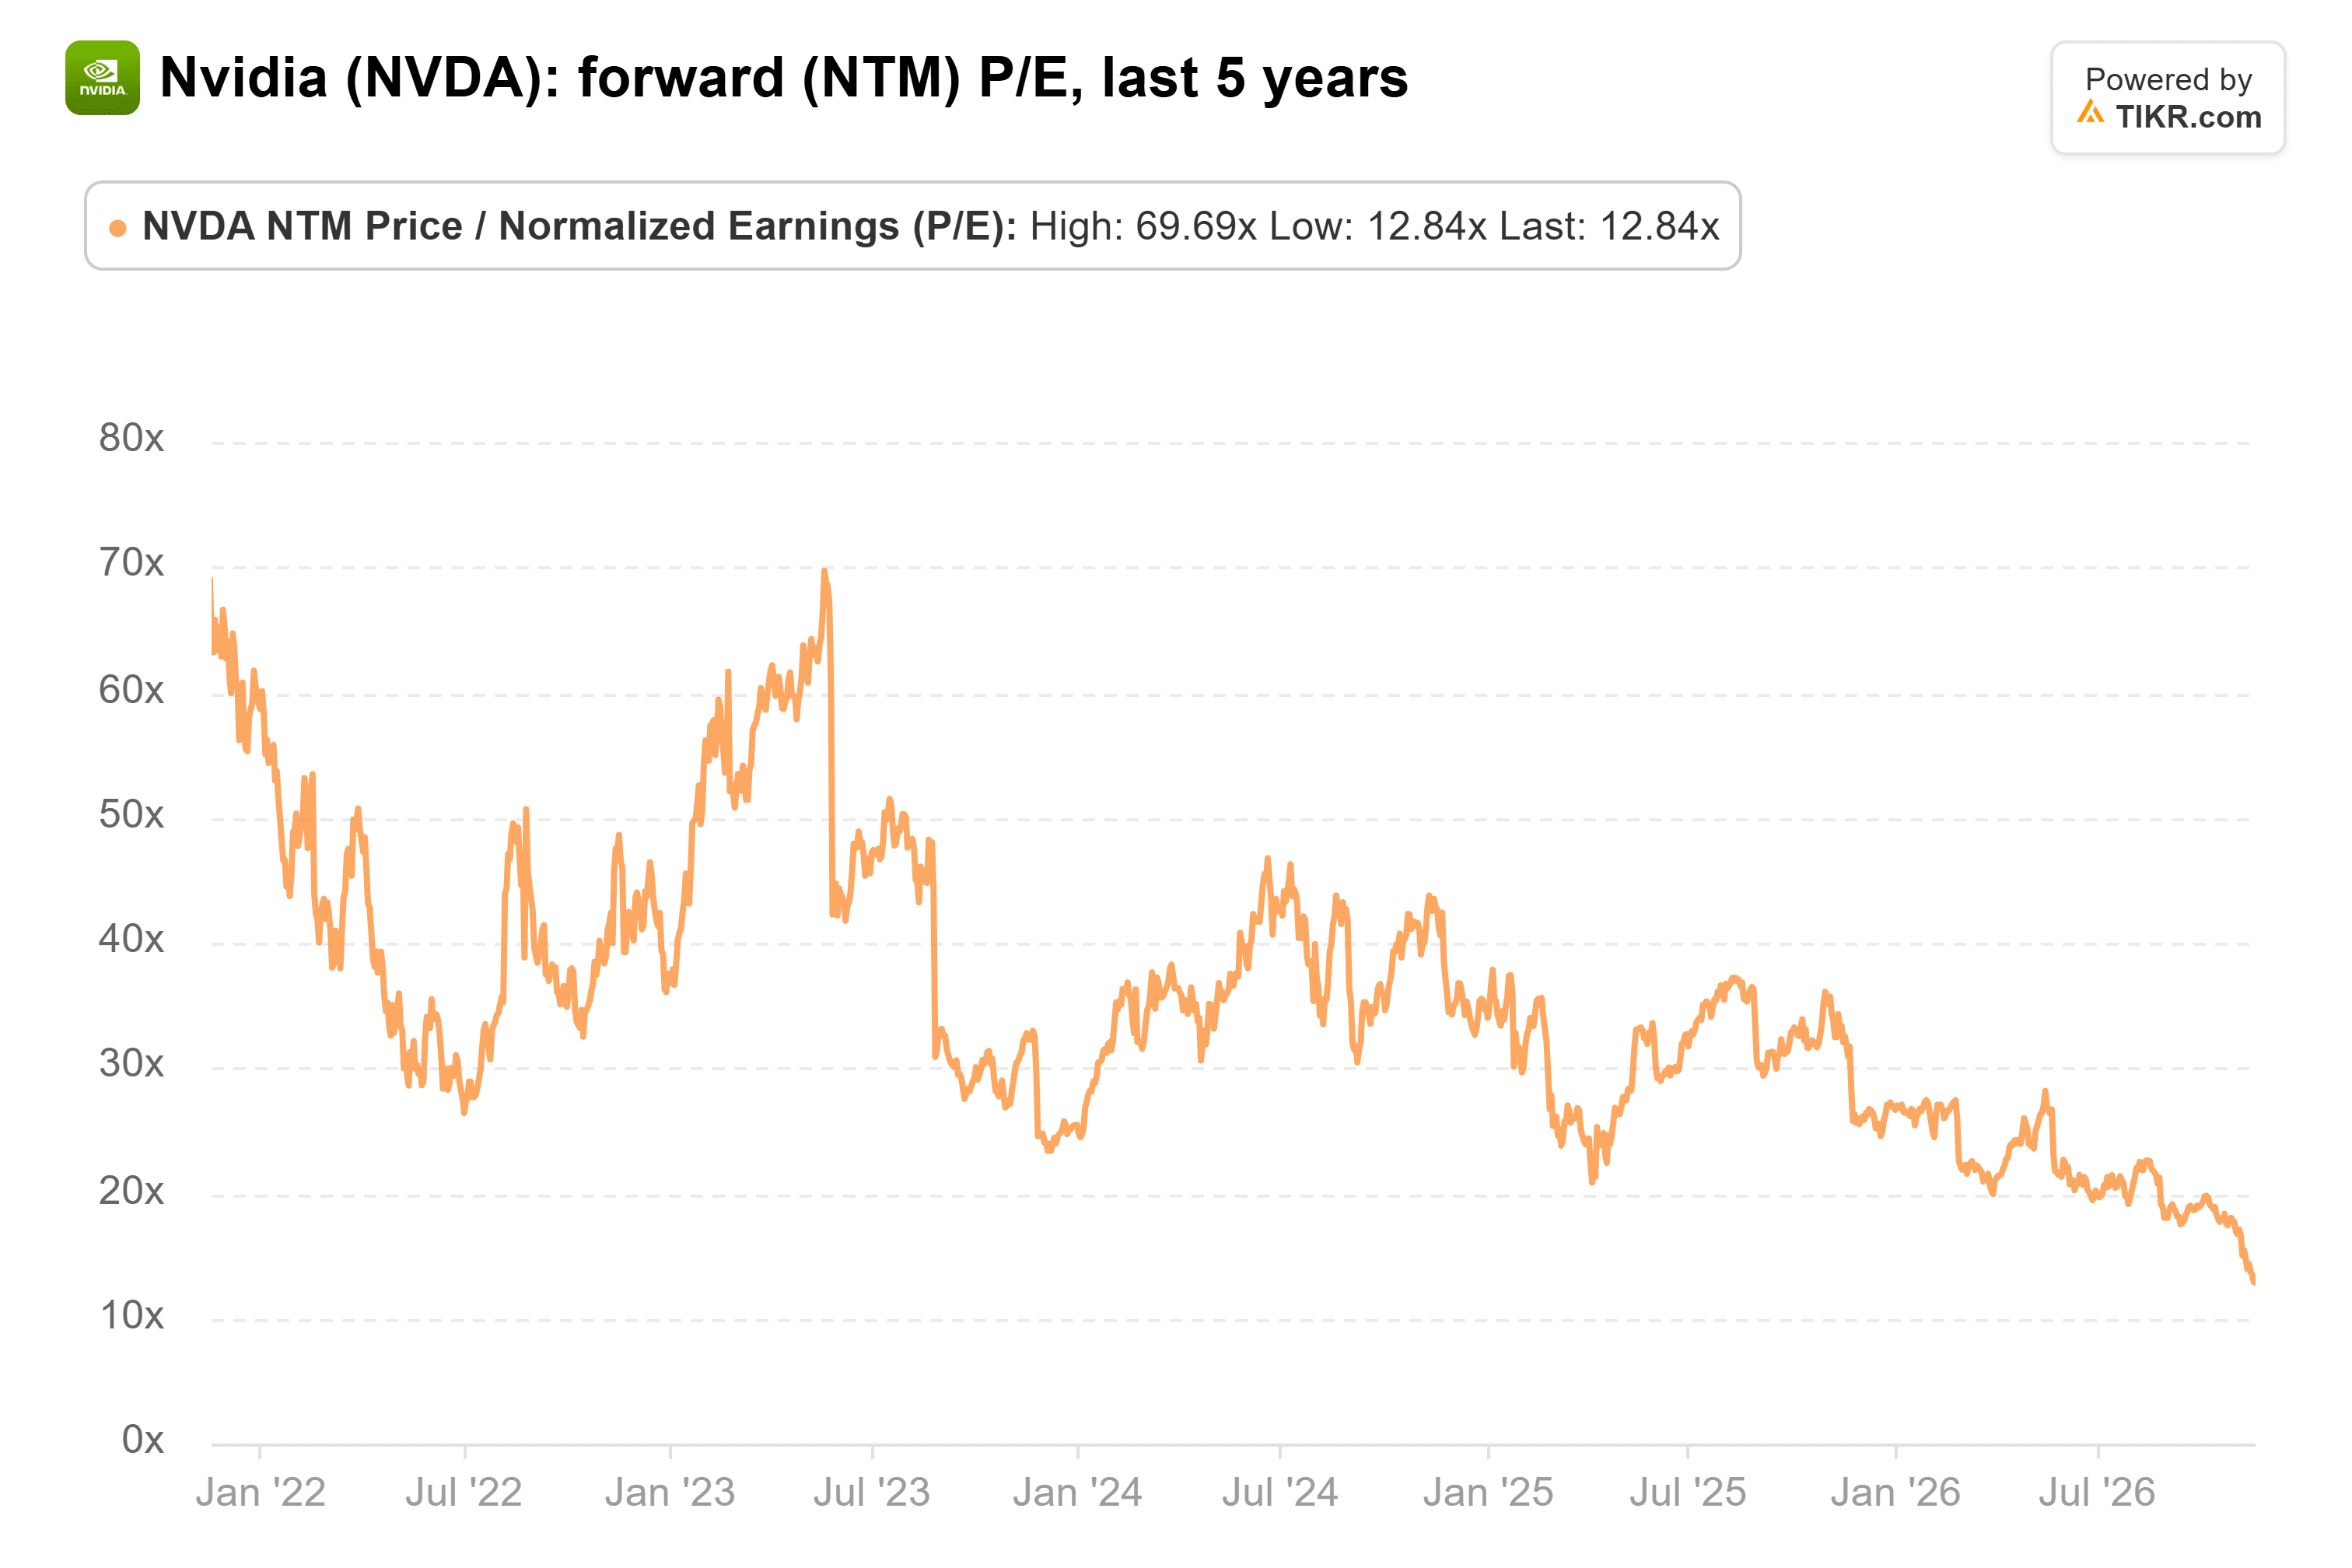
On Nov. 17, Nvidia traded at 12.8x next-12-month earnings, its lowest in five years and far below its 36x five-year average:
Analysts expect normalized EPS to climb to $16.24 in fiscal 2028, from $9.66 in fiscal 2027, and to $21.44 in fiscal 2029:
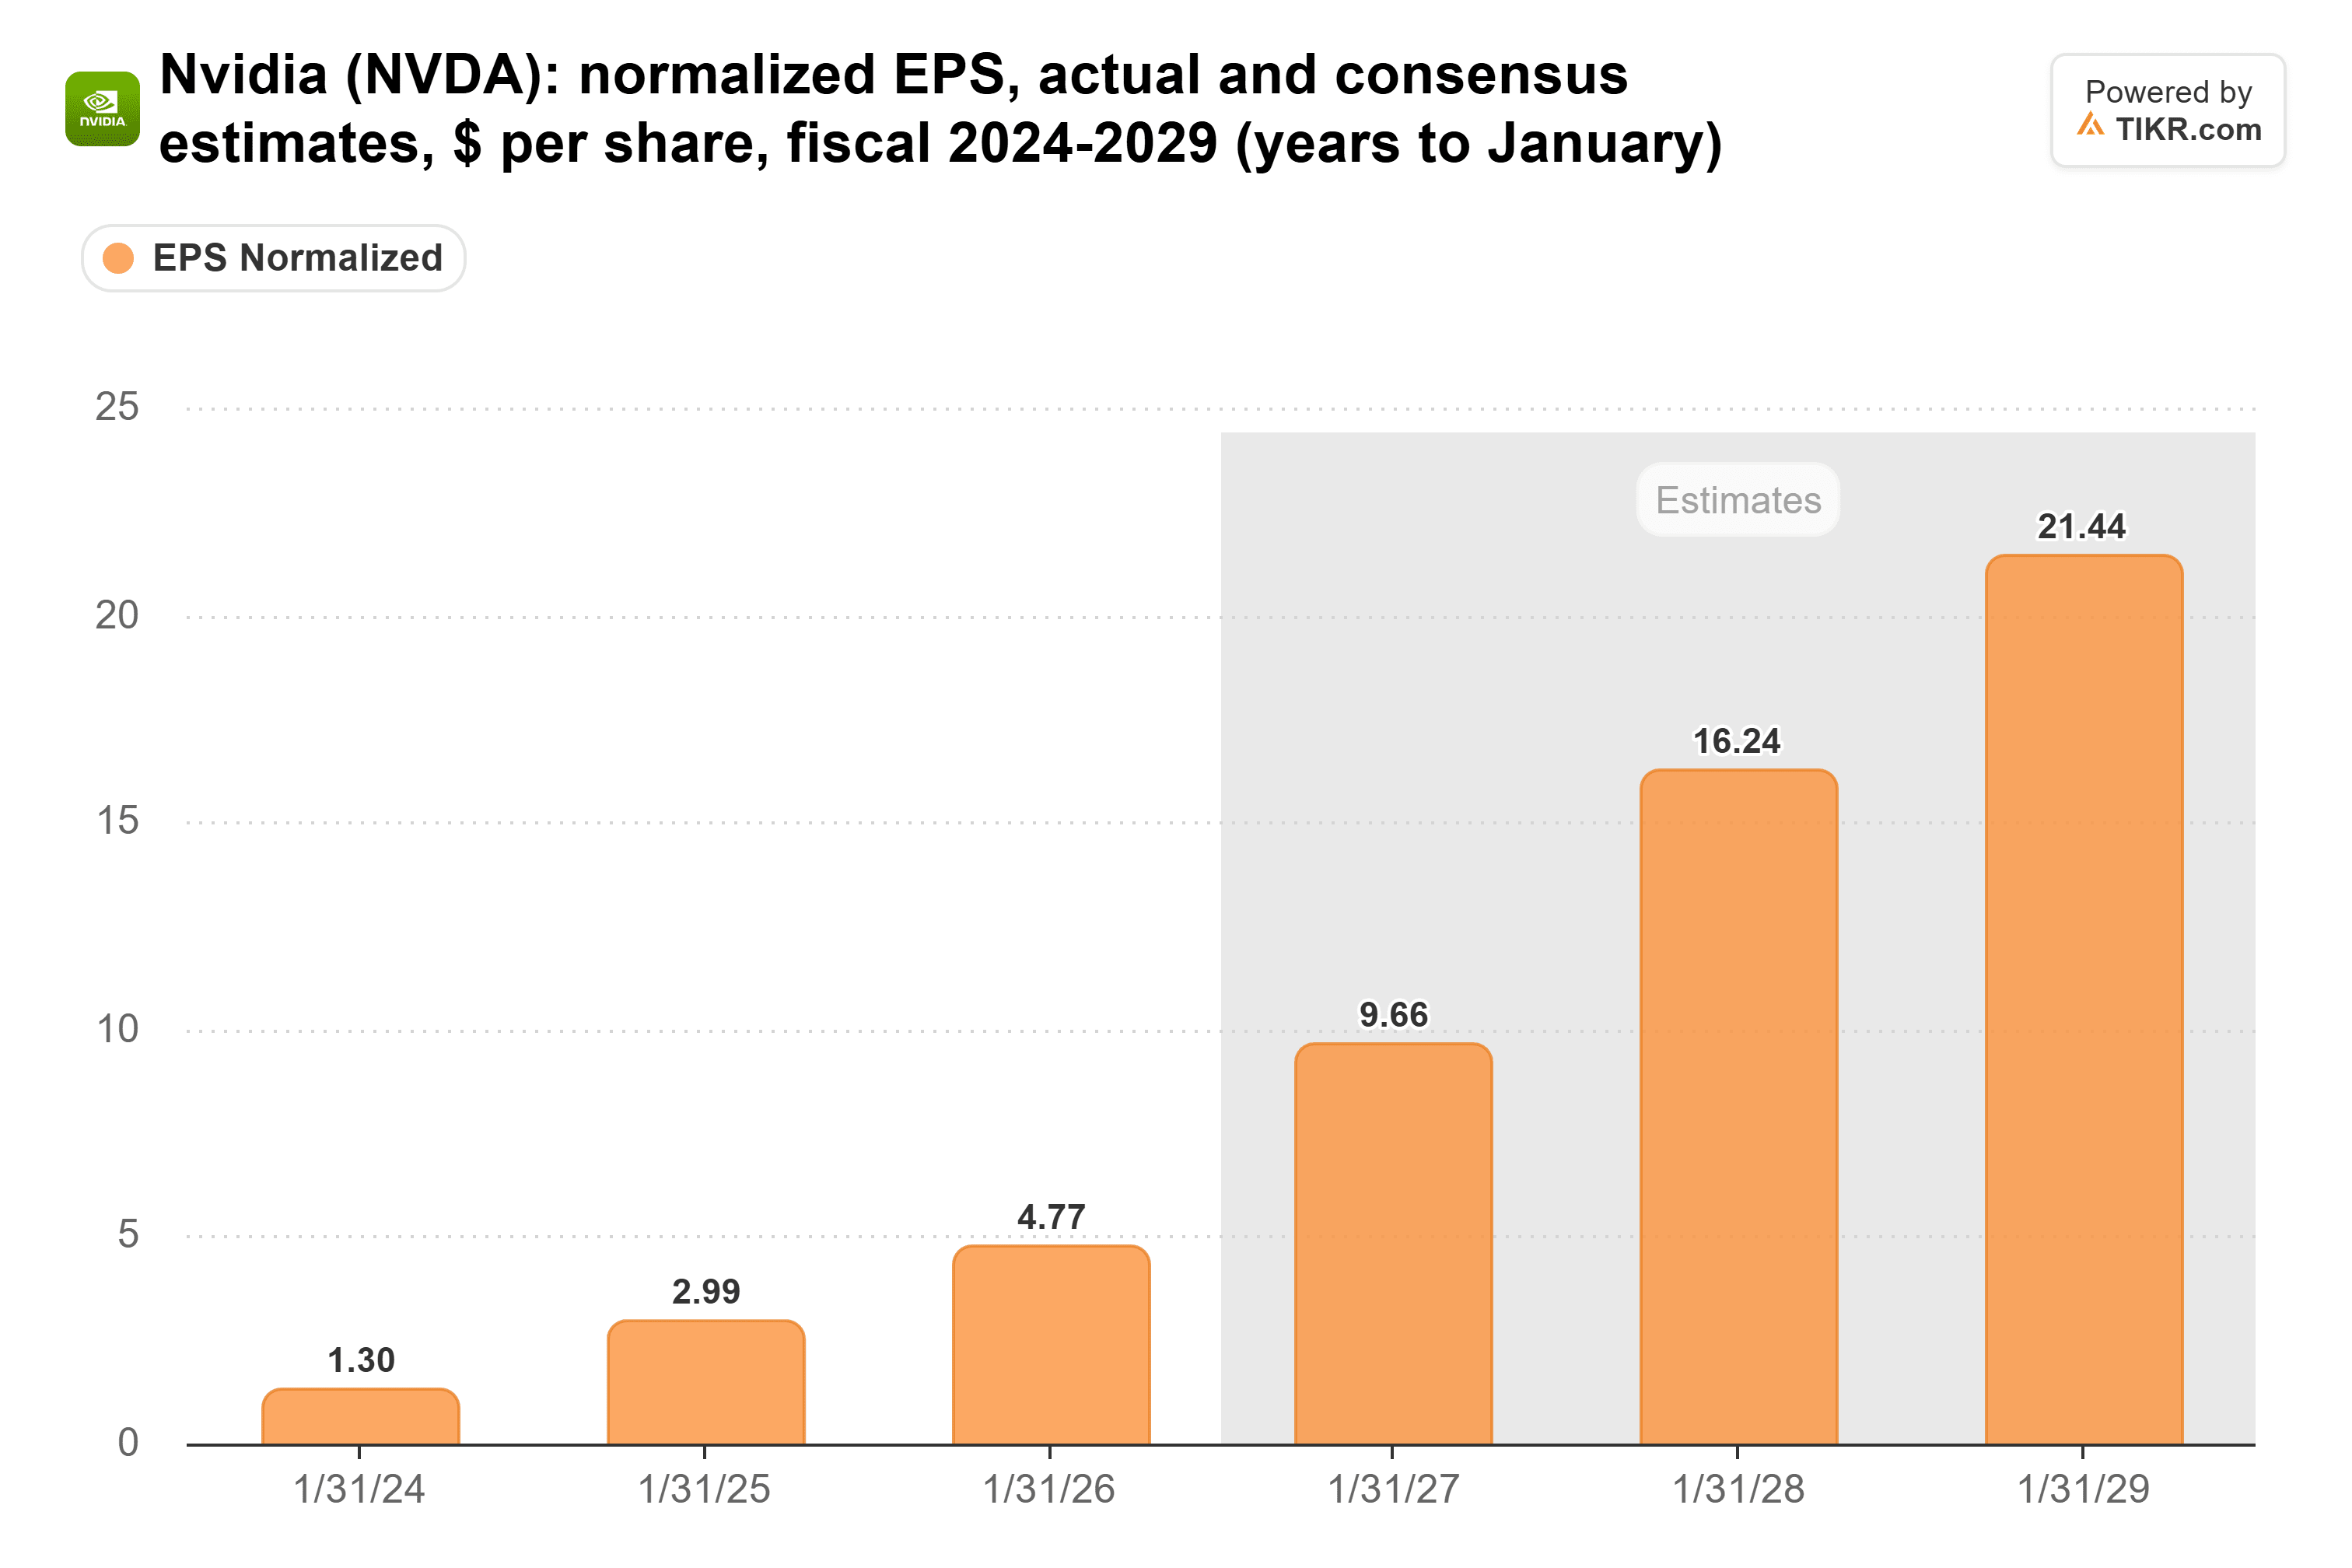
At $150.96, the stock trades at 9.3x that fiscal 2028 figure. Now run Luria’s numbers on the same $419 billion base. Growth of 50% gets you about $629 billion in fiscal 2028, and 25% gets you about $524 billion, 11% and 26% below consensus. Cut EPS by the same amounts and you get about $14.40 and $12.00, still 24% to 49% above fiscal 2027.
On those earnings, today’s price works out to about 10.5x and 12.6x. Thinner margins would push those multiples a bit higher.
Luria reached the same place: “It looks like that’s already in the stock.”
What Could Break Nvidia’s Math
The risk is that the borrowing Luria warns about lands on Nvidia’s own balance sheet. Its days sales outstanding rose to 64 in the October quarter, from 60, which Nvidia tied to Rubin shipment timing and longer payment terms for certain investment-grade customers.
At about 9x next year’s earnings, Nvidia doesn’t need Kress’s 75% to work from here.
The big three’s 2027 capex plans come next. If they guide below 25% growth, even Luria’s slow case starts to look generous.
So What Is Nvidia Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nvidia could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!