

Key Takeaways
- Intuit shares fell 13% after it cut its fiscal 2027 revenue growth guidance to 8%-9%, as Credit Karma’s outlook dropped to 3%-7% growth from 11%-13%.
- Management blamed higher rates and a faster-than-expected shift to AI tools. That’s a lasting problem for Credit Karma and a risk for Upstart, which gets many borrowers through it.
- Intuit is also selling Mailchimp for less than a third of what it paid, while rival Klaviyo keeps growing.
Intuit (INTU) is down 13% today. It cut its fiscal 2027 revenue outlook to 8%-9% growth, from 9%-10%, and all of the cut came from Credit Karma. That reaches Upstart (UPST), which gets many of its borrowers through Credit Karma, and Klaviyo (KVYO), whose email rival Mailchimp is being sold at a steep loss.
Credit Karma ran into AI
Revenue rose 12% to $4.4 billion, and adjusted EPS jumped 56% to $2.91. But Credit Karma grew just 9%, and Intuit now sees 3%-7% for the year. CEO Sasan Goodarzi blamed higher rates and a shift in how people shop: “These AI tools and agents are becoming new front doors for discovery, much like search engines, mobile devices and app marketplaces before them.”
If someone asks a chatbot which card to get, Credit Karma may never see them.
Bad for Upstart, an opening for Klaviyo
Upstart’s originations rose 44% to $4.1 billion last quarter, but CEO Paul Gu warned that “Macro is putting pressure on our near-term outlook.” Credit Karma’s personal loans still grew last quarter. If AI keeps pulling loan shoppers elsewhere, I’d expect Upstart to pay more to find them.
Mailchimp goes to Bending Spoons for $3.68 billion, against the $12 billion Intuit paid in 2021. Mailchimp’s revenue fell 1% last quarter, while Klaviyo’s grew 25%. Klaviyo’s next report should show whether Mailchimp customers start moving over.
TIKR tracks 34 analysts on Intuit. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intuit, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intuit’s Analyst Ratings
The estimates still have to come down
Analysts expect Intuit’s revenue to reach $25.2 billion by fiscal 2028:
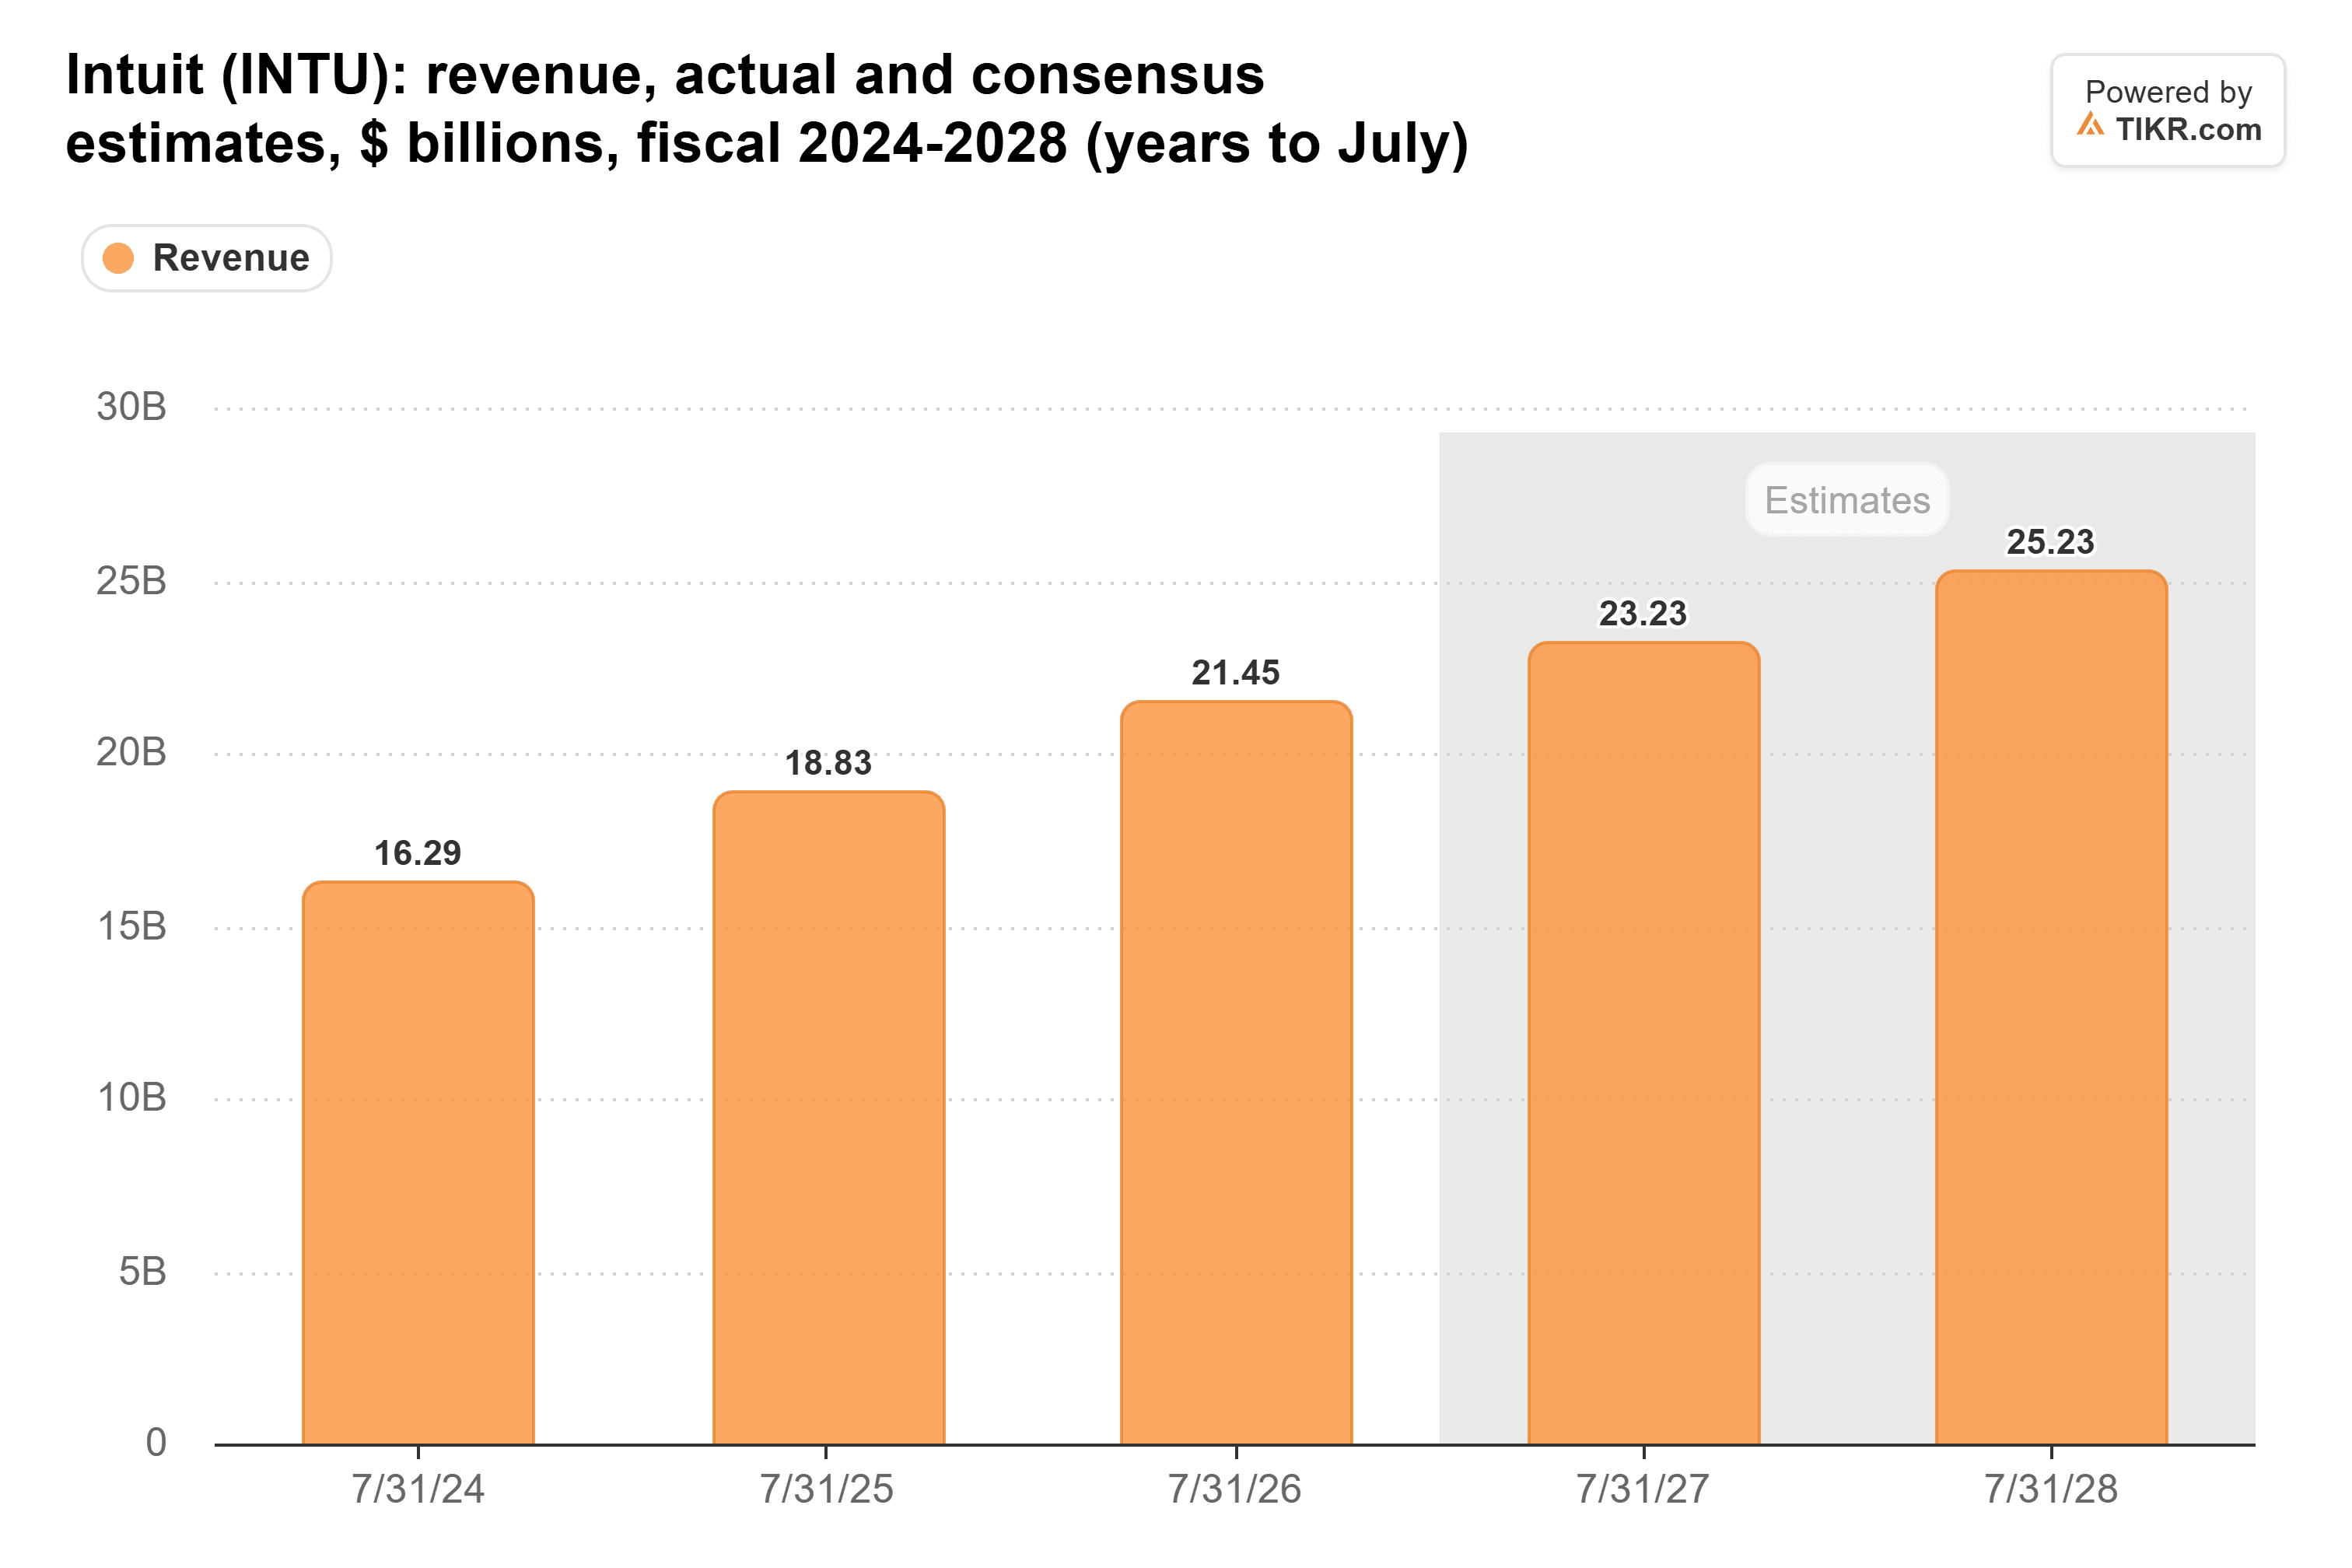
Those figures still include about $1.26 billion a year of Mailchimp revenue, so they’ll fall once the sale closes. Even so, Intuit traded at 13x forward earnings before today’s drop, against a five-year average of 30x:
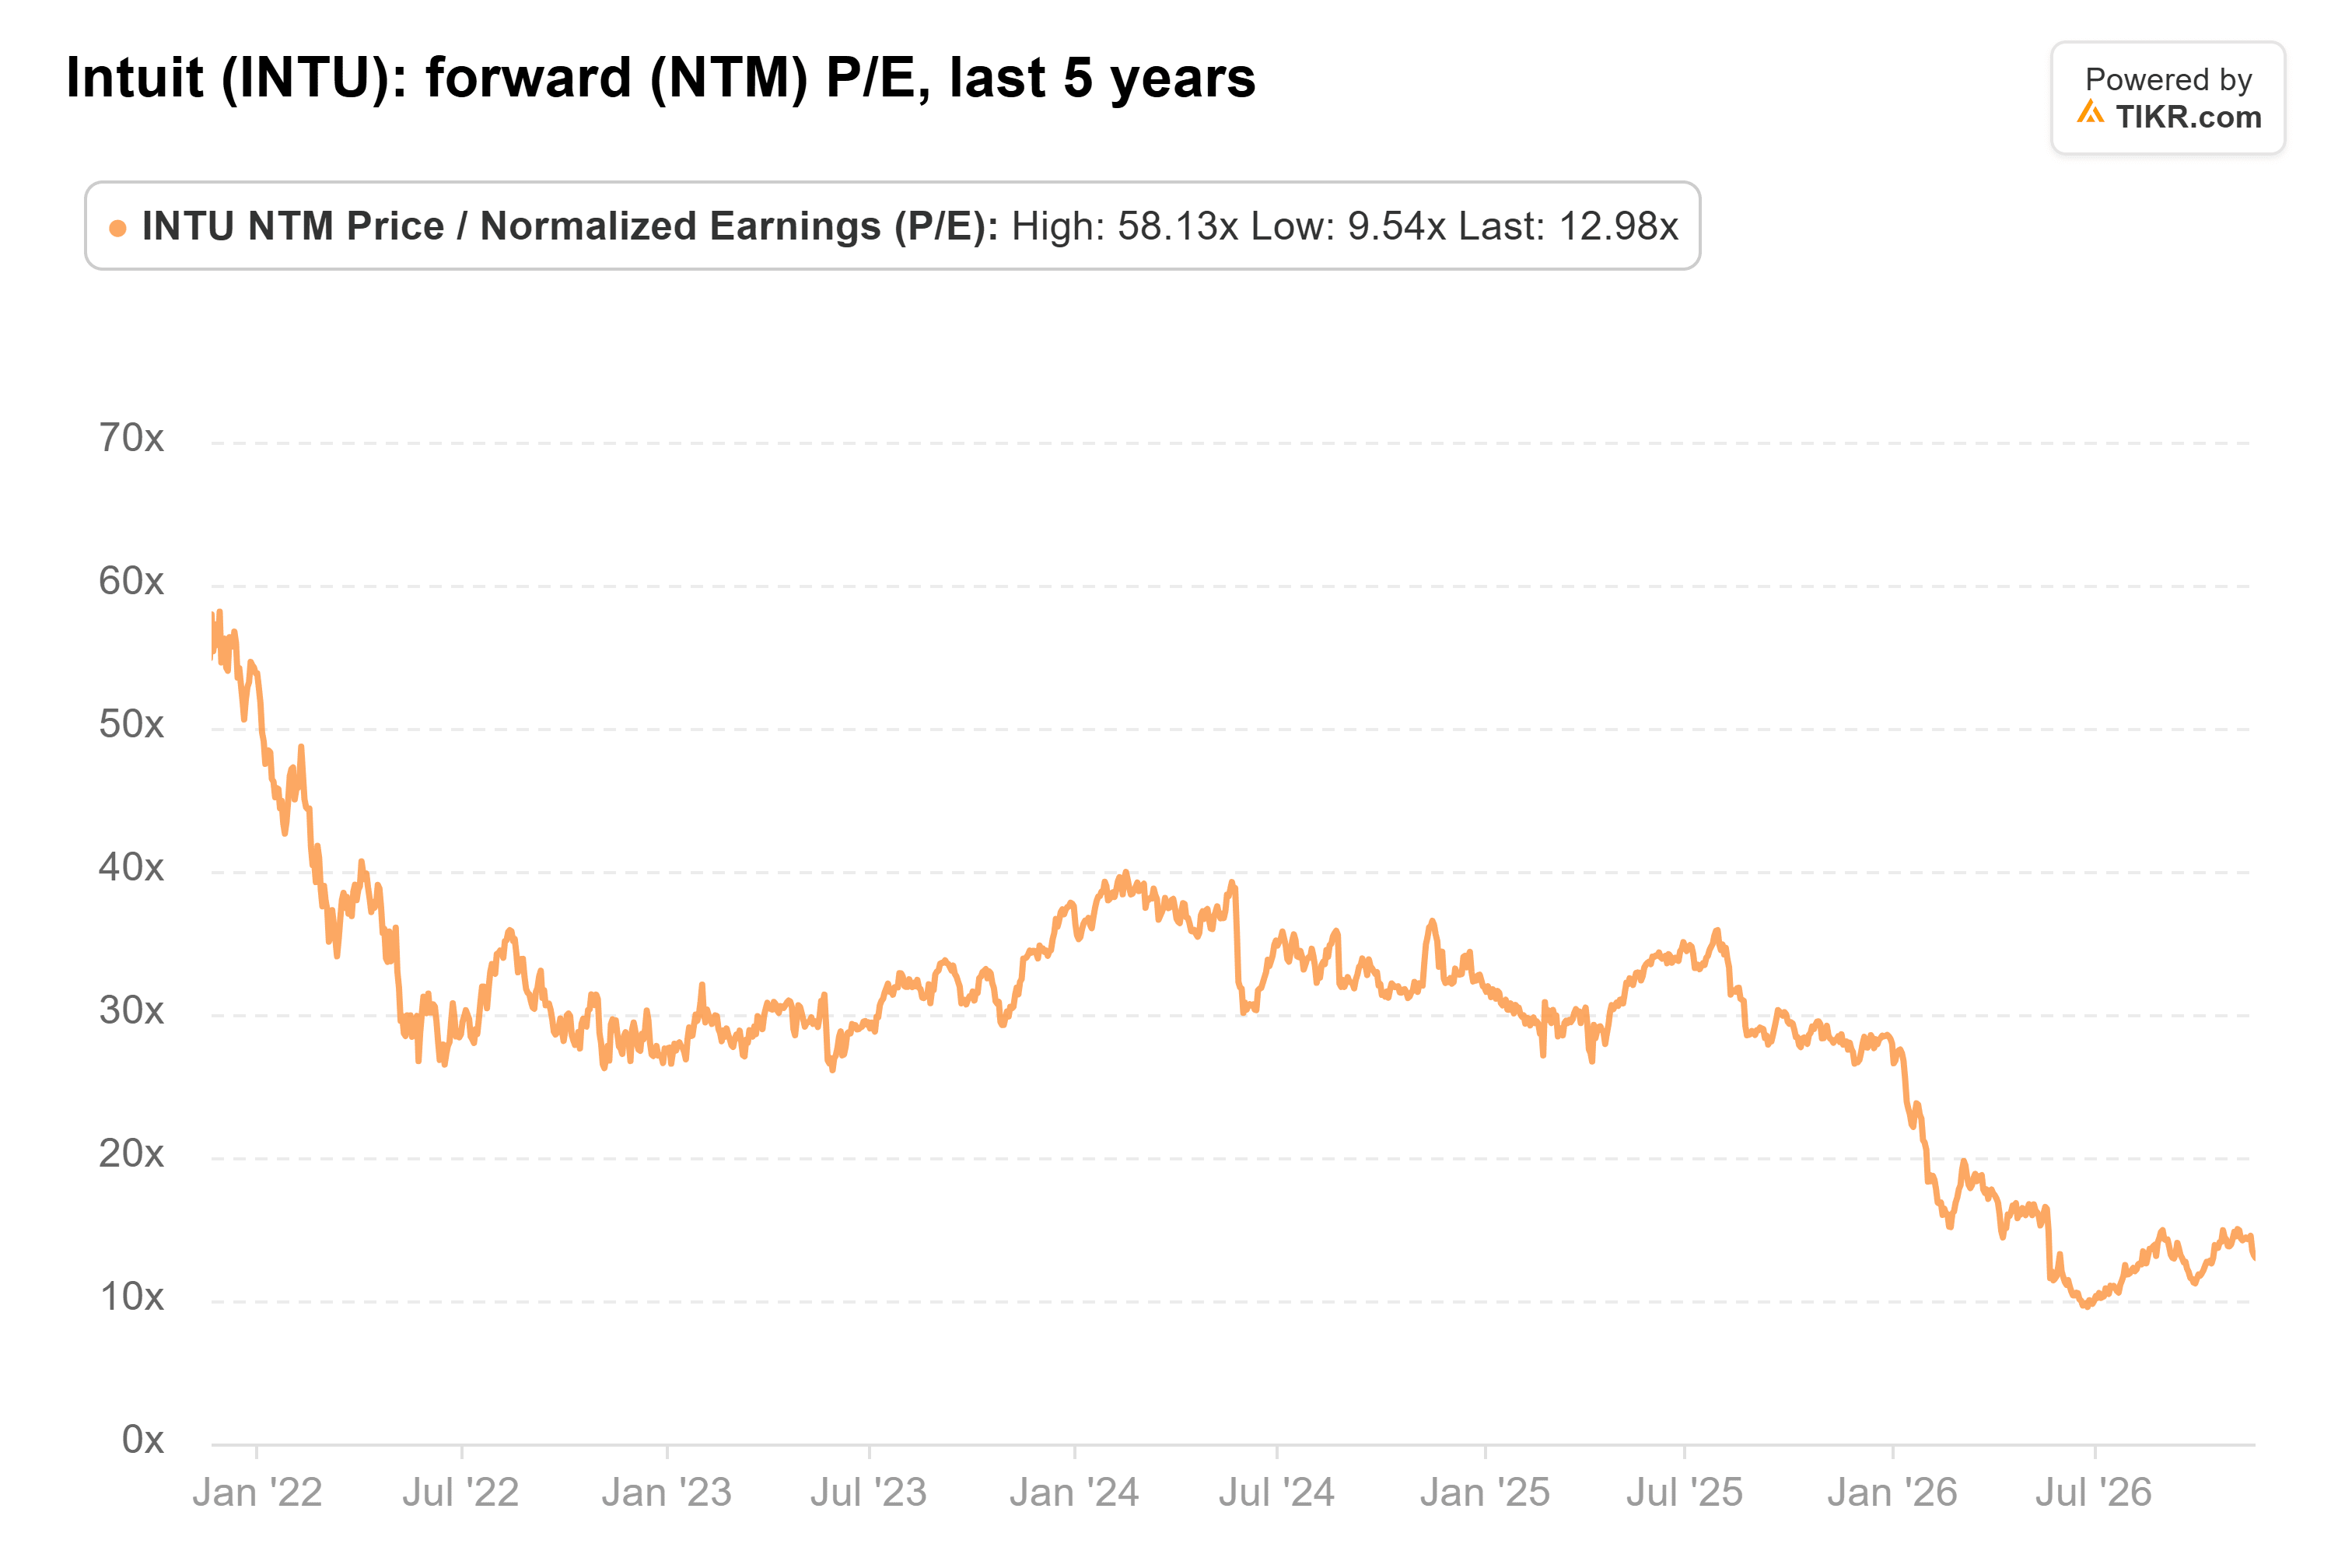
The way I see it, Credit Karma is one of the first real AI casualties in software. But QuickBooks Online Accounting revenue still grew 19%, and at this multiple the market is pricing Credit Karma’s problem as if it were all of Intuit’s. To back that up, second-quarter results in late February need revenue of at least $4.93 billion, the bottom of the guidance range.
So what is Intuit stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intuit could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


