Key Takeaways
- PDD Holdings stock is down 39% over the past year, and its third-quarter results are due in mid-to-late November.
- PDD’s operating margin fell to 21.6% in 2025 from 27.5% in 2024, even though revenue grew 9.7%.
- Analysts expect EPS to fall in 2026 and then grow faster than sales in 2027 and 2028, so the consensus already counts on margins recovering.
- At 7.1x forward earnings, just above its five-year low of 6.6x, the stock is priced for a squeeze that didn’t show up in the first half of 2026.
PDD Holdings (PDD) stock has bounced 9% in the past month, but it’s still down 39% over the past year as of its Nov. 4 close of $82.15. Its third-quarter results come out in mid-to-late November, and the number that matters most is margin: how much profit PDD keeps from each dollar of sales.
That’s where the damage happened. Revenue grew 9.7% in 2025, to RMB431.8 billion, while operating profit fell 14%, to RMB93.1 billion.
Wall Street expects profit to catch back up
Analysts see revenue growing 7.9% in 2026, 11.0% in 2027 and 9.4% in 2028. Consensus normalized EPS, in yuan per American depositary share, falls this year and then climbs through 2028:

So EPS falls 5.3% in 2026 while sales grow 7.9%, then rises 20.4% in 2027 and 16.6% in 2028. From 2025 to 2028, that’s 33% EPS growth against 31% for revenue. In other words, analysts expect margins to dip this year and then climb back to roughly where they were in 2025, not to 2024’s peak.
The margin already took one hit
PDD’s operating margin rose every year from 7.3% in 2021 to 27.5% in 2024, then fell to 21.6% in 2025:
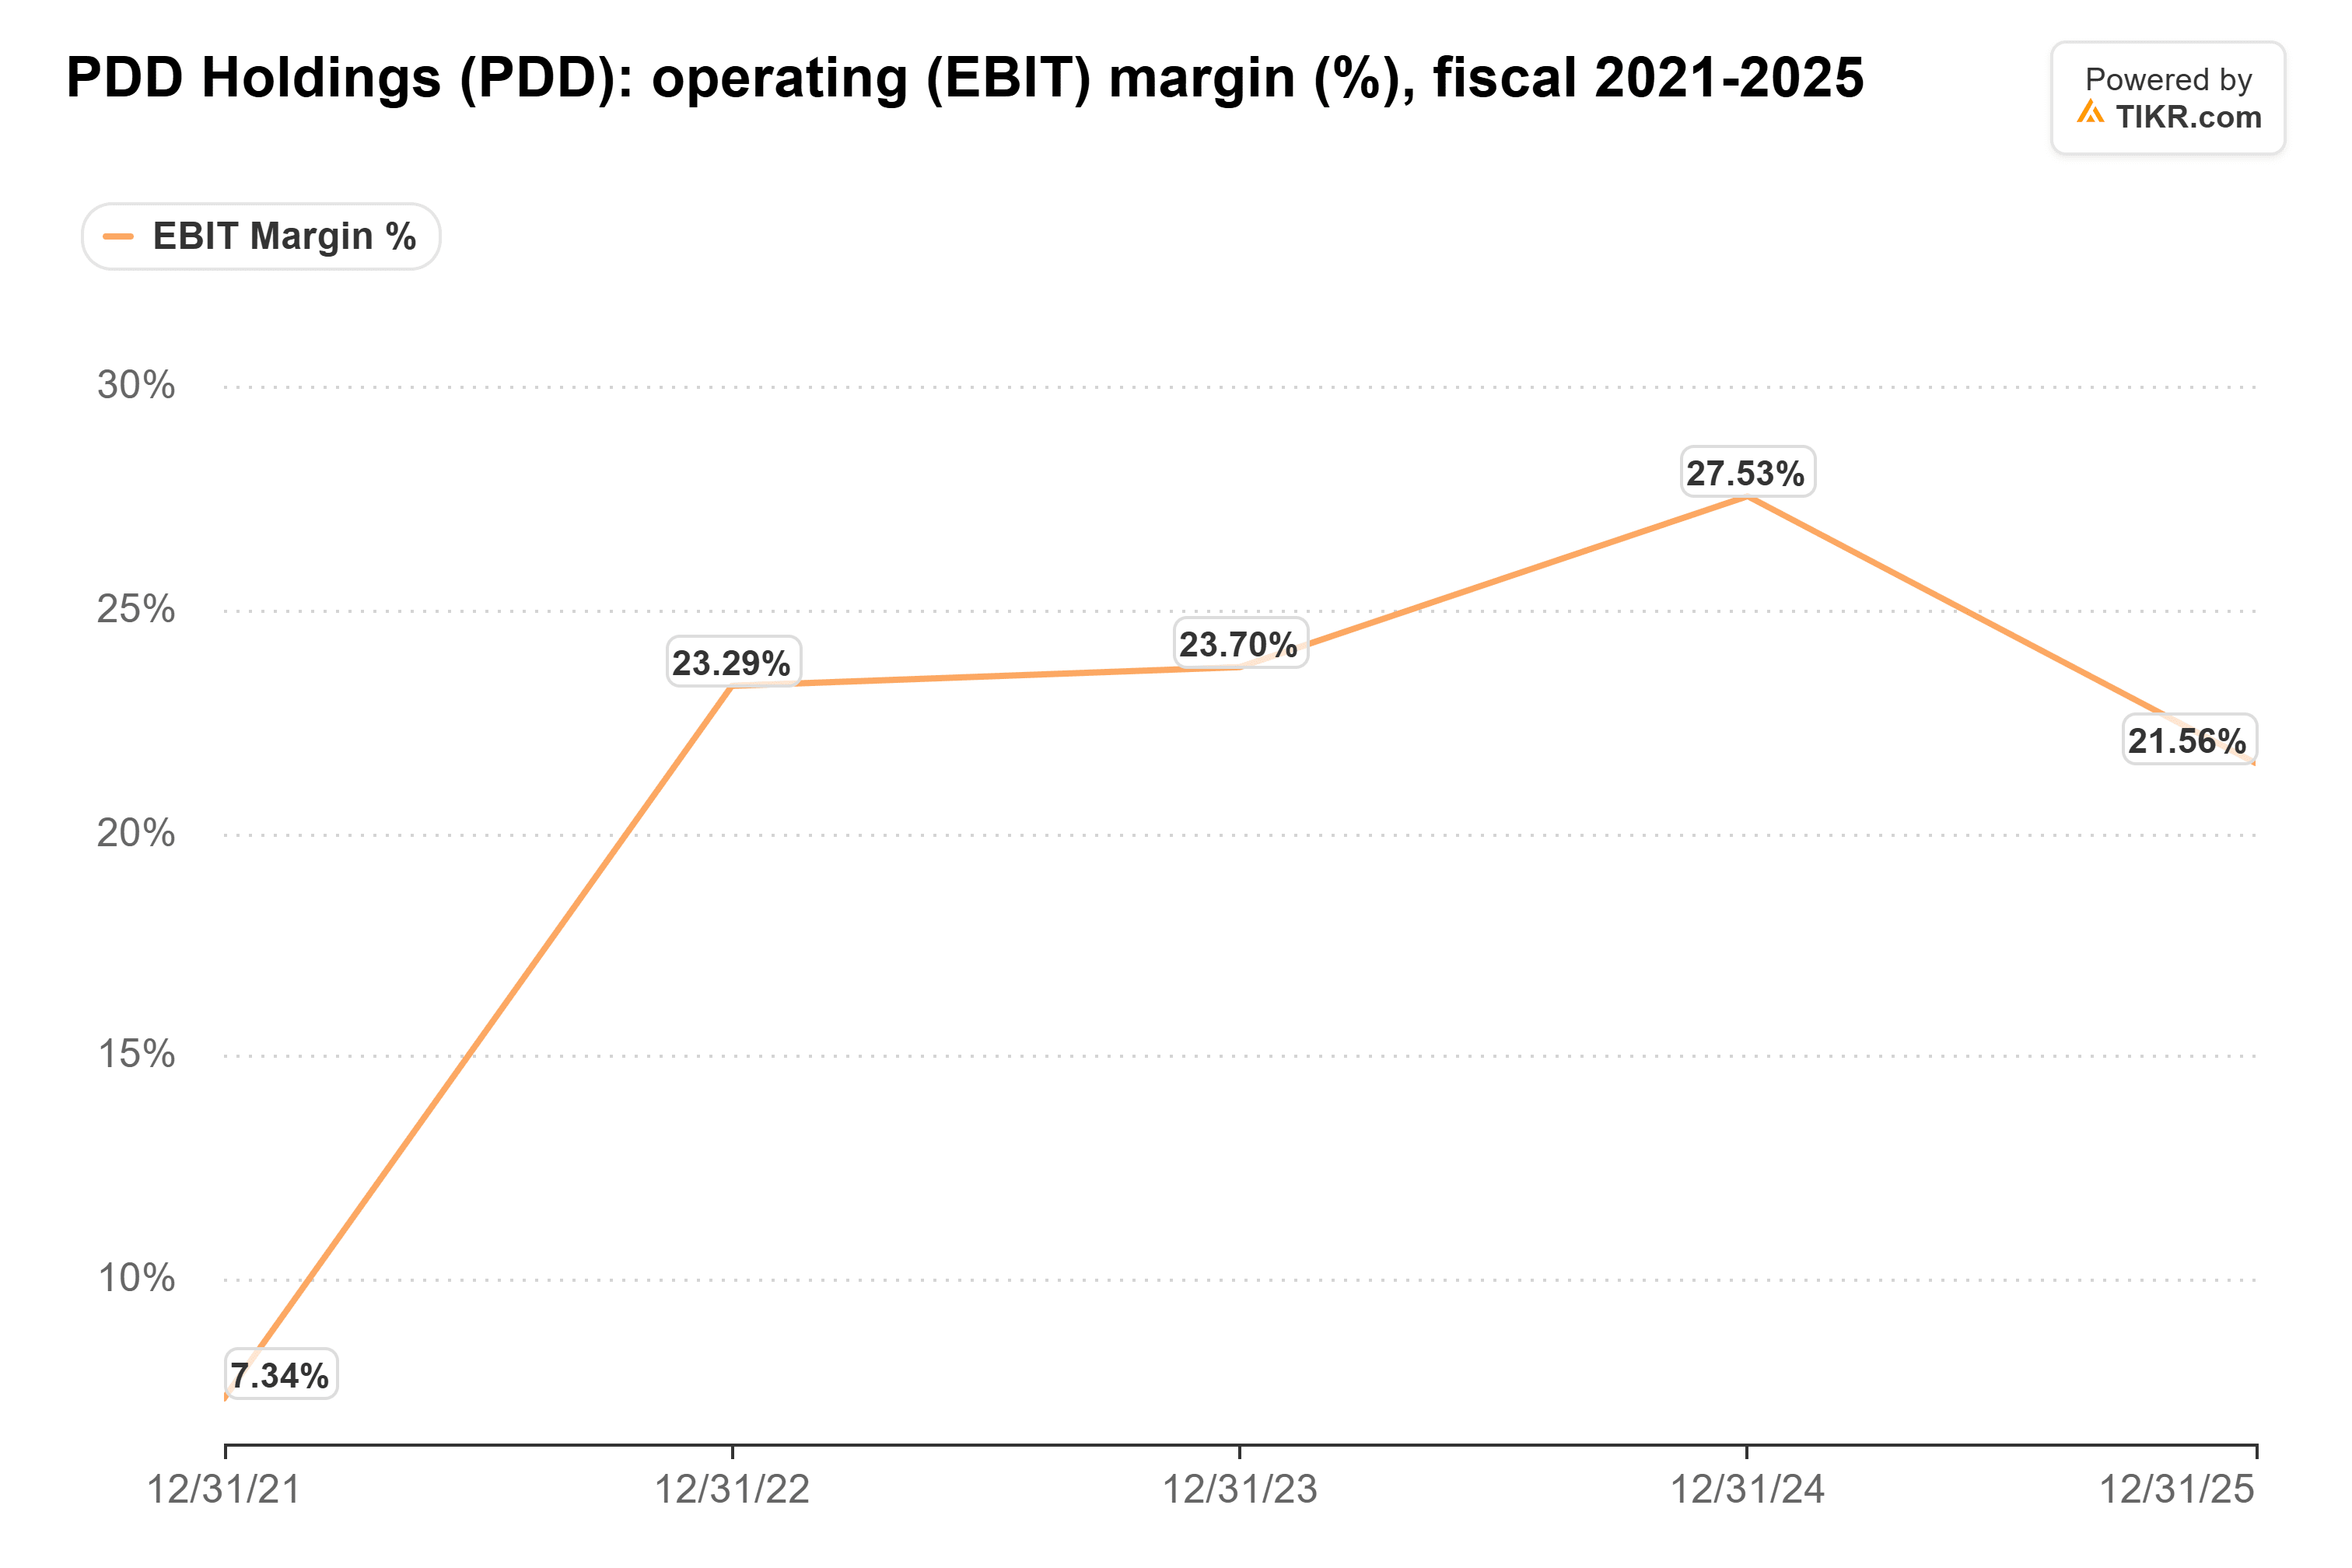
Of the RMB38.0 billion in extra revenue PDD brought in during 2025, only RMB3.1 billion reached gross profit.
The squeeze has stalled since then. The operating margin was 21.7% in the first half of 2026, up from 21.0% a year earlier, and gross margin hit 57.3% in the second quarter, up from 55.9%. Net income still fell 13% in the half, because of a RMB9.4 billion “other” loss below the operating line.
TIKR tracks 35 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
The stock is priced for a squeeze anyway
Analysts have cut their EPS estimates for 2026 through 2028 by about a fifth since Sept. 30, 2025, and investors pay far less for what’s left. PDD’s forward P/E sits near the bottom of its five-year range:

At 7.1x as of Nov. 2, it sits just above its five-year low of 6.6x. The five-year average of about 21x is skewed by a spike above 300x in late 2021, when profit was thin.
Free cash flow fell to RMB105.8 billion in 2025 from RMB121.0 billion:

The seven analysts who estimate it expect it to jump to RMB133.4 billion in 2027. They only get there if margins recover. Meanwhile, PDD plans to spend RMB100 billion over three years on its own brands, and management said in August that the rollout was going slower than it expected. VP of Finance Jun Liu made the priority clear in the Aug. 24 earnings release: “At this stage, our priority is helping merchants thrive and strengthening the broader industry ecosystem.”
PDD’s Temu has also faced an EU duty on low-value parcels since July 1. In the US, Texas settled its Temu suit for $3 million on Oct. 16, and six other states’ suits were still unresolved as of late October. Temu has denied wrongdoing.
What November has to show
Analysts expect third-quarter revenue of around RMB116 billion, up about 7%, after four straight quarterly revenue misses. Two other lines may matter more.
One is online marketing, which grew just 3.5% in the second quarter. PDD doesn’t report profit by line, but its cost growth has come mainly from fulfillment fees, which track Temu’s transaction-heavy business, so ad revenue likely carries the richer margin. The other is gross margin in the first full quarter under the EU duty.
PDD is priced as if its margin keeps shrinking, but it steadied in the first half of 2026. If gross margin holds near 57% in the third quarter and ad growth picks up, the discount looks too steep.
Of course, the own-brand push is still early, and heavier spending could pull the margin lower before it pays off.
So what is PDD Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!