Key Takeaways
- Nike stock is down 36% this year, and Truist downgraded it to Sell on Nov. 5 with a $29 price target.
- Nike’s $2.2 billion of free cash flow in fiscal 2026 didn’t cover the $2.4 billion it paid in dividends, and its buybacks have nearly stopped.
- Analysts don’t expect earnings to get back above the $1.64 annual dividend through fiscal 2028. Until then, $8.4 billion of cash and short-term investments is covering the gap.
- Investor Day on Nov. 16 and 17 and the next dividend declaration will show whether the 24-year raise streak keeps going.
Nike (NKE) stock is down 36% this year, and Truist thinks it has further to fall.
On Nov. 5, the firm downgraded Nike to Sell from Hold and kept its $29 price target. It said the stock’s 19% rally over the past month came from money rotating into the sector, and that the business itself hasn’t improved.
Truist listed the problems: retro Jordan launches sitting on shelves, little sense of when sales in Greater China will bottom out, and tough comparisons after World Cup sales and big shipments to U.S. wholesale partners. Greater China’s revenue already fell 26% currency-neutral in the fiscal first quarter.
So for anyone holding through the slump, the 4.1% yield (at the Nov. 4 close) is what pays you to wait. Is the business still paying for it?
Earnings already sit below the dividend
Nike pays $0.41 a share each quarter, or $1.64 a year. Management’s guidance for fiscal 2027 (the year to May) is adjusted EPS of $1.15 to $1.35. Analysts don’t see earnings getting back above the dividend through fiscal 2028:
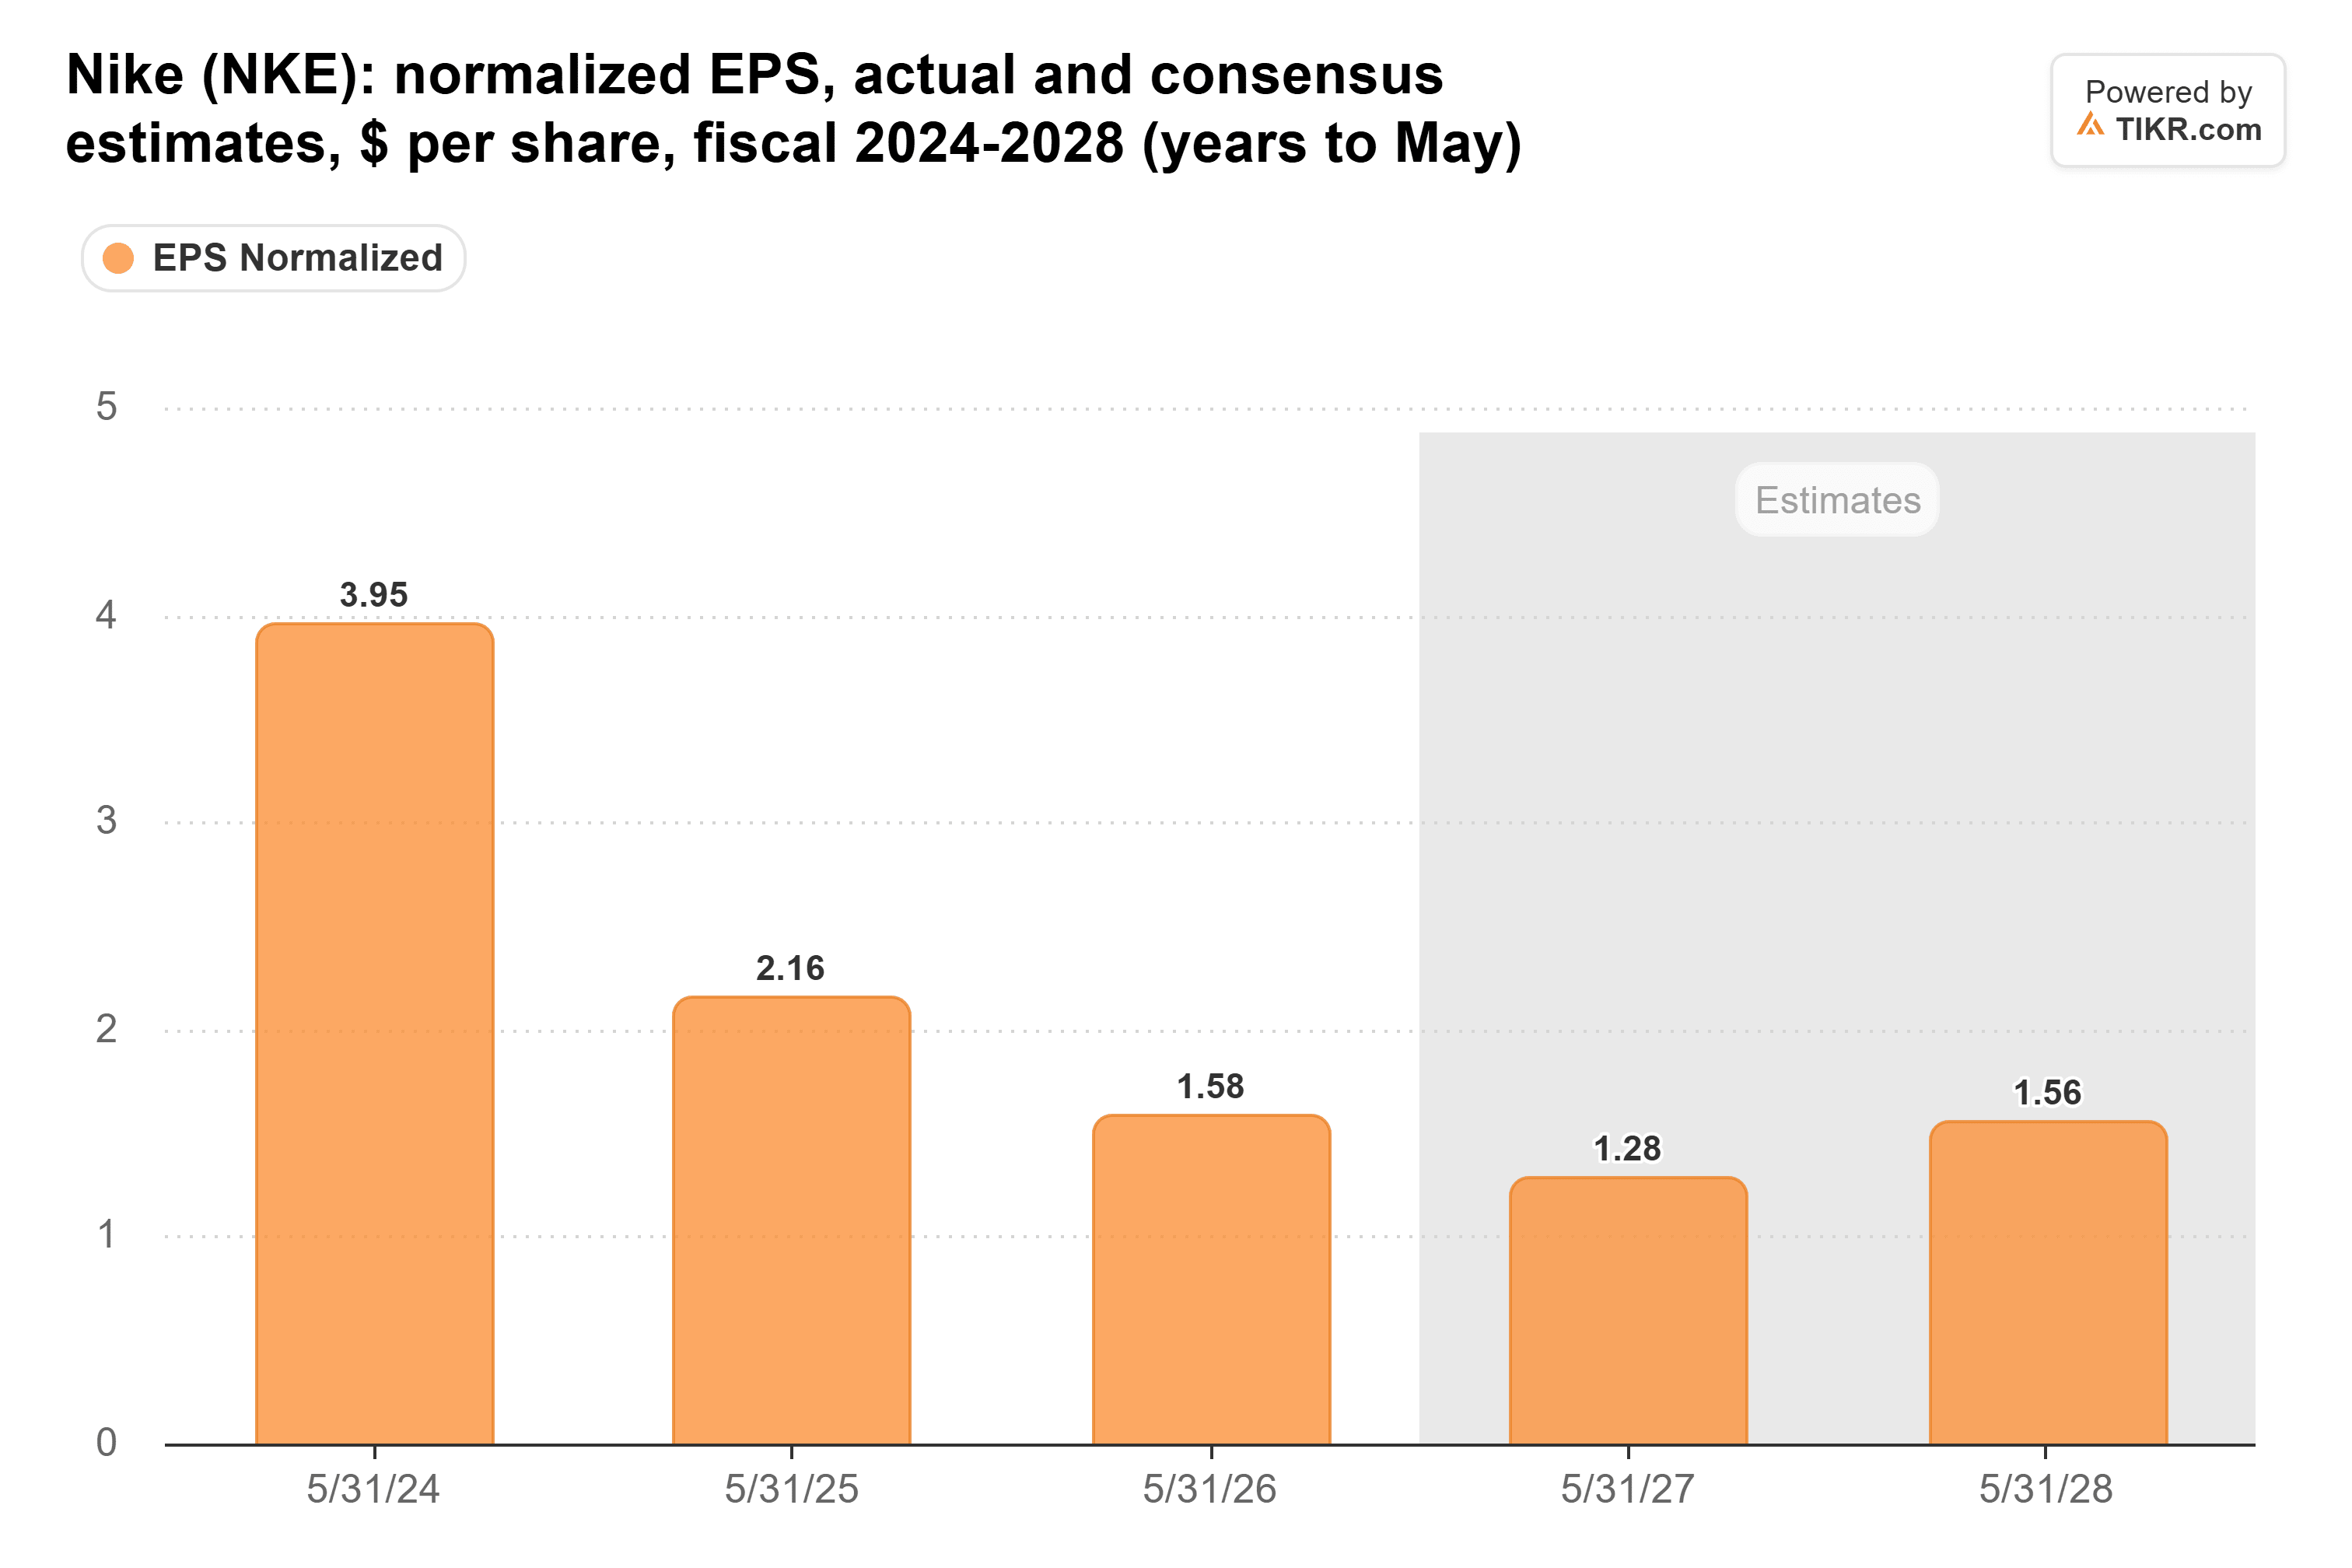
And that $1.28 consensus for fiscal 2027 has dropped 25% in three months. Truist is more cautious still, having cut its fiscal 2028 estimate to $1.30 from $1.40.
The stock isn’t cheap on those earnings, either. On Monday, Nov. 2, Nike traded at 30x forward earnings, right around its five-year average:
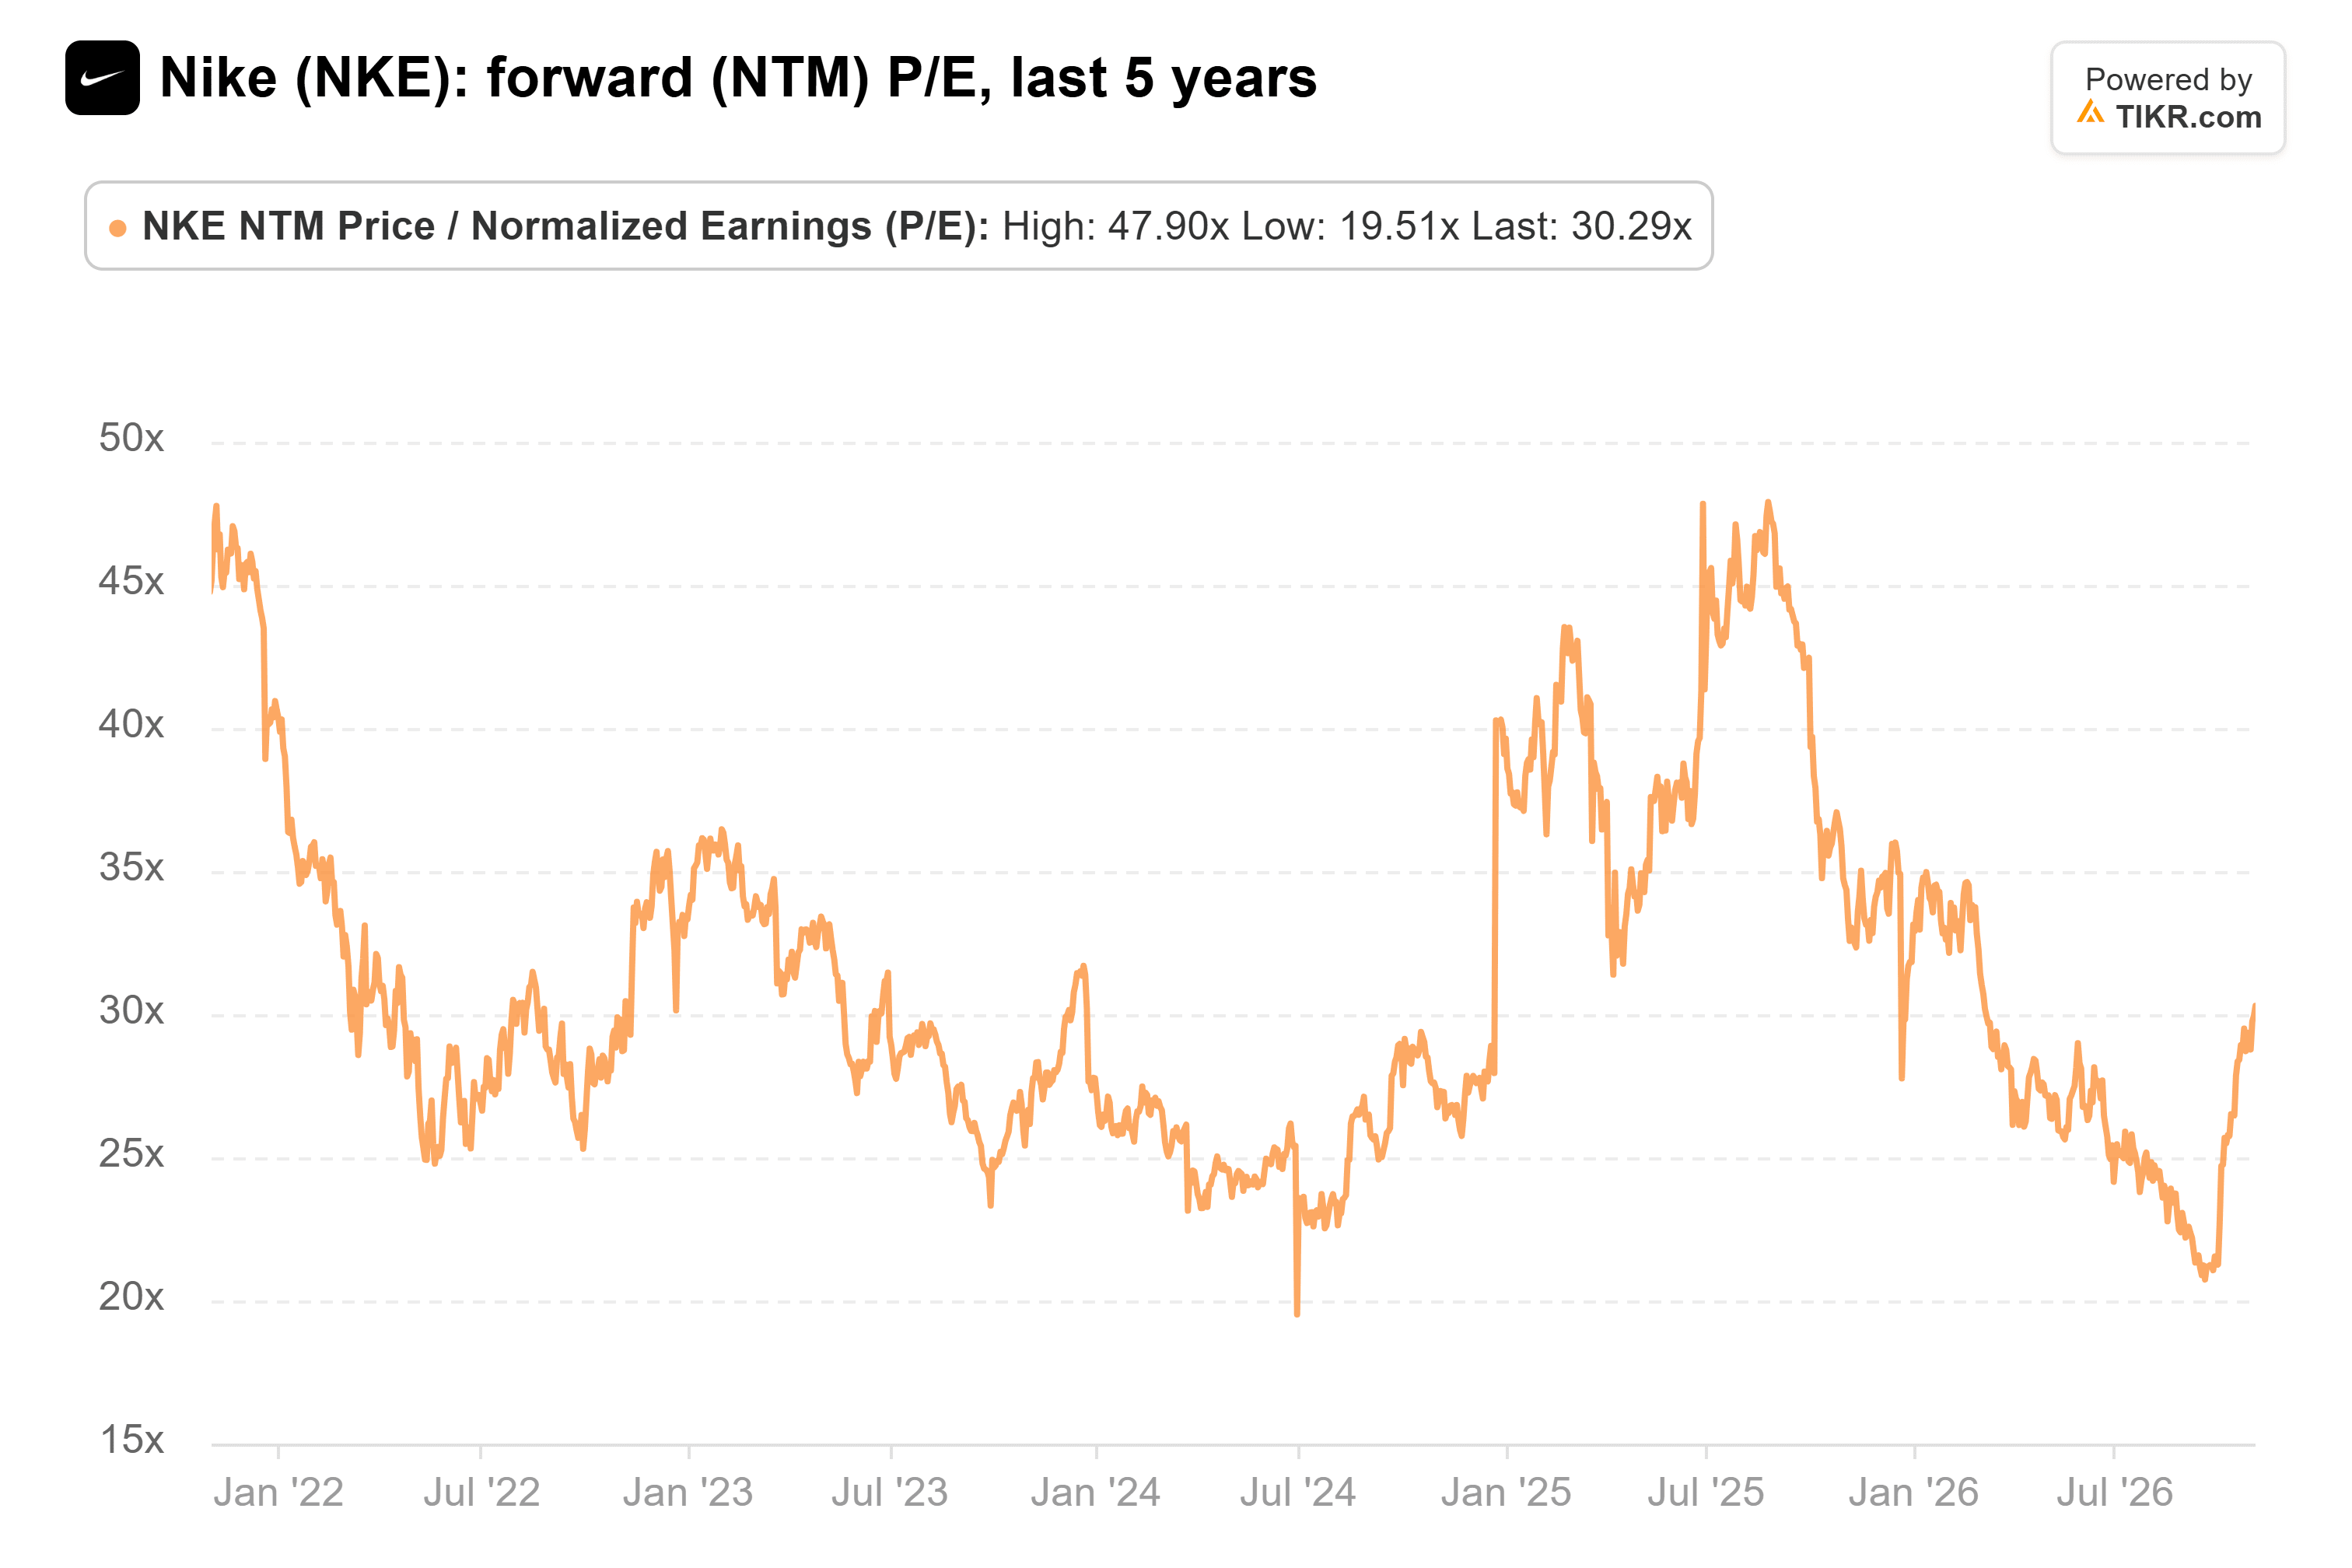
So the price already assumes a recovery. While you wait for it, the dividend is what you get paid.
TIKR tracks 43 analysts on Nike. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nike, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nike’s Analyst Ratings
Free cash flow came up short last year
Nike pays its dividend out of free cash flow, and for most of the past decade it had plenty left over:

That changed in fiscal 2026. Nike’s $2.2 billion of free cash flow fell short of $2.4 billion in dividends, a cash payout ratio of about 110%. The only other shortfall in that 10-year stretch came in fiscal 2020, when the pandemic hit.
The new fiscal year started off worse. In the first quarter, Nike brought in $135 million of operating cash flow, spent $199 million on capex and paid $610 million in dividends.
That’s why the buybacks have all but stopped. Nike spent $32.3 billion buying back its own stock over the 10 fiscal years through May 2026, and only $122 million of that came in fiscal 2026.
The cash pile is paying it for now
On Aug. 31, Nike had $8.4 billion of cash and short-term investments. That’s more than its $7.9 billion of debt, which includes $1 billion that came due on Nov. 1 and another $1 billion due March 27, 2027.
CFO Dave Denton was firm about the dividend on the Oct. 1 fiscal first-quarter call: “Under all scenarios, we have support for maintaining and ultimately growing the dividend over time.”
S&P sees it differently. On Oct. 5 it cut Nike’s credit rating to A from A+ with a negative outlook, and it expects Nike to burn about $1.2 billion a year after paying dividends.
Analysts expect free cash flow to recover to $2.7 billion this fiscal year. That would cover roughly $2.4 billion of dividends with little to spare. But those estimates assume the same recovery Truist doubts. Analysts also expect a $1.64 dividend this fiscal year and just $1.66 next year, so they aren’t counting on much of a raise.
Covered, with little to spare
Nike’s free cash flow didn’t cover the dividend last fiscal year. This year it only will if the recovery arrives on schedule.
A company with $8.4 billion of cash and short-term investments and a 24-year streak of raises is unlikely to cut its dividend soon. But until free cash flow recovers, the balance sheet is paying part of that yield, and the dividend alone isn’t a reason to buy Nike until the business covers it again.
More answers are close. Nike’s Investor Day is Nov. 16 and 17, and last year’s dividend raise was announced on Nov. 20. A raise would make 25 straight years, while holding at $0.41 would end the streak. Second-quarter results, expected in mid-December, will then show whether cash flow has turned the corner.
So what is Nike stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nike could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!