Key Takeaways
- Palo Alto Networks stock rose 14% in the past week after AI helped find software flaws and an Evercore survey showed firmer security budgets, which lifted cybersecurity stocks, CrowdStrike among them.
- The case for bigger security budgets in the AI era is real, but the stock already trades at a rich forward multiple and about level with Wall Street’s average target.
- The main risk is that AI’s biggest players sell defense themselves, as Amazon did with AWS Continuum on Oct. 23.
- Next-generation security ARR in the fiscal first-quarter report, due in November, is the test, and until then the stock looks like a hold.
Palo Alto Networks (PANW) stock is up 14% in the past week, while the S&P 500 went nowhere. The whole cybersecurity group ran, CrowdStrike (CRWD) up 11% among them.
Palo Alto itself put out little news. The rally is a bet that flaws found by AI mean bigger security budgets, and CEO Nikesh Arora warned on the All-In podcast that “you’re basically handing a nuclear sort of bomb to the hands of anybody who wants it.” But Amazon (AMZN) launched its own AI defense tool the same day.
A security scare turned into a spending case
The week built in steps:
- Oct. 21: PHP disclosed critical flaws, found with AI’s help, in code that runs about 70% of websites, and security stocks jumped.
- Oct. 22: Deutsche Bank named Palo Alto and CrowdStrike among three standouts set to gain from rising AI token usage.
- Oct. 23: Evercore ISI’s channel partner survey found security budgets firming and named CrowdStrike and Palo Alto the leading winners from AI-driven spending.
- Oct. 23, midday: Palo Alto put Unit 42 Continuous Frontier AI Defense and Prisma AIRS on OpenAI’s new marketplace.
That last one matters: Prisma AIRS passed $100 million of ARR within four quarters of release.
TIKR tracks 55 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
Arora says the attacks are only speeding up
Arora told the All-In hosts that flaws like PHP’s will come faster than once every 10 days, so defense is about how fast you find intruders and throw them out.
Amazon CEO Andy Jassy agrees. “AI has taken the gap between finding a vulnerability and someone using it from weeks down to minutes,” he wrote on X, launching AWS Continuum, an autonomous defense tool.
So AI’s builders want a share of that spending, too. Arora’s answer, from a Goldman Sachs conference in September: the industry gets about $30 to $40 per endpoint, and a frontier model checking a laptop’s daily traffic would cost more than $40 a year. “LLMs do not sit in enforcement points,” he said. AI can find the holes, and Palo Alto still gets paid to plug them.
The run already prices in a lot
Palo Alto’s forward P/E was back to 96x on Oct. 27, up from about 82x in mid-October and far above its five-year average of 57x.
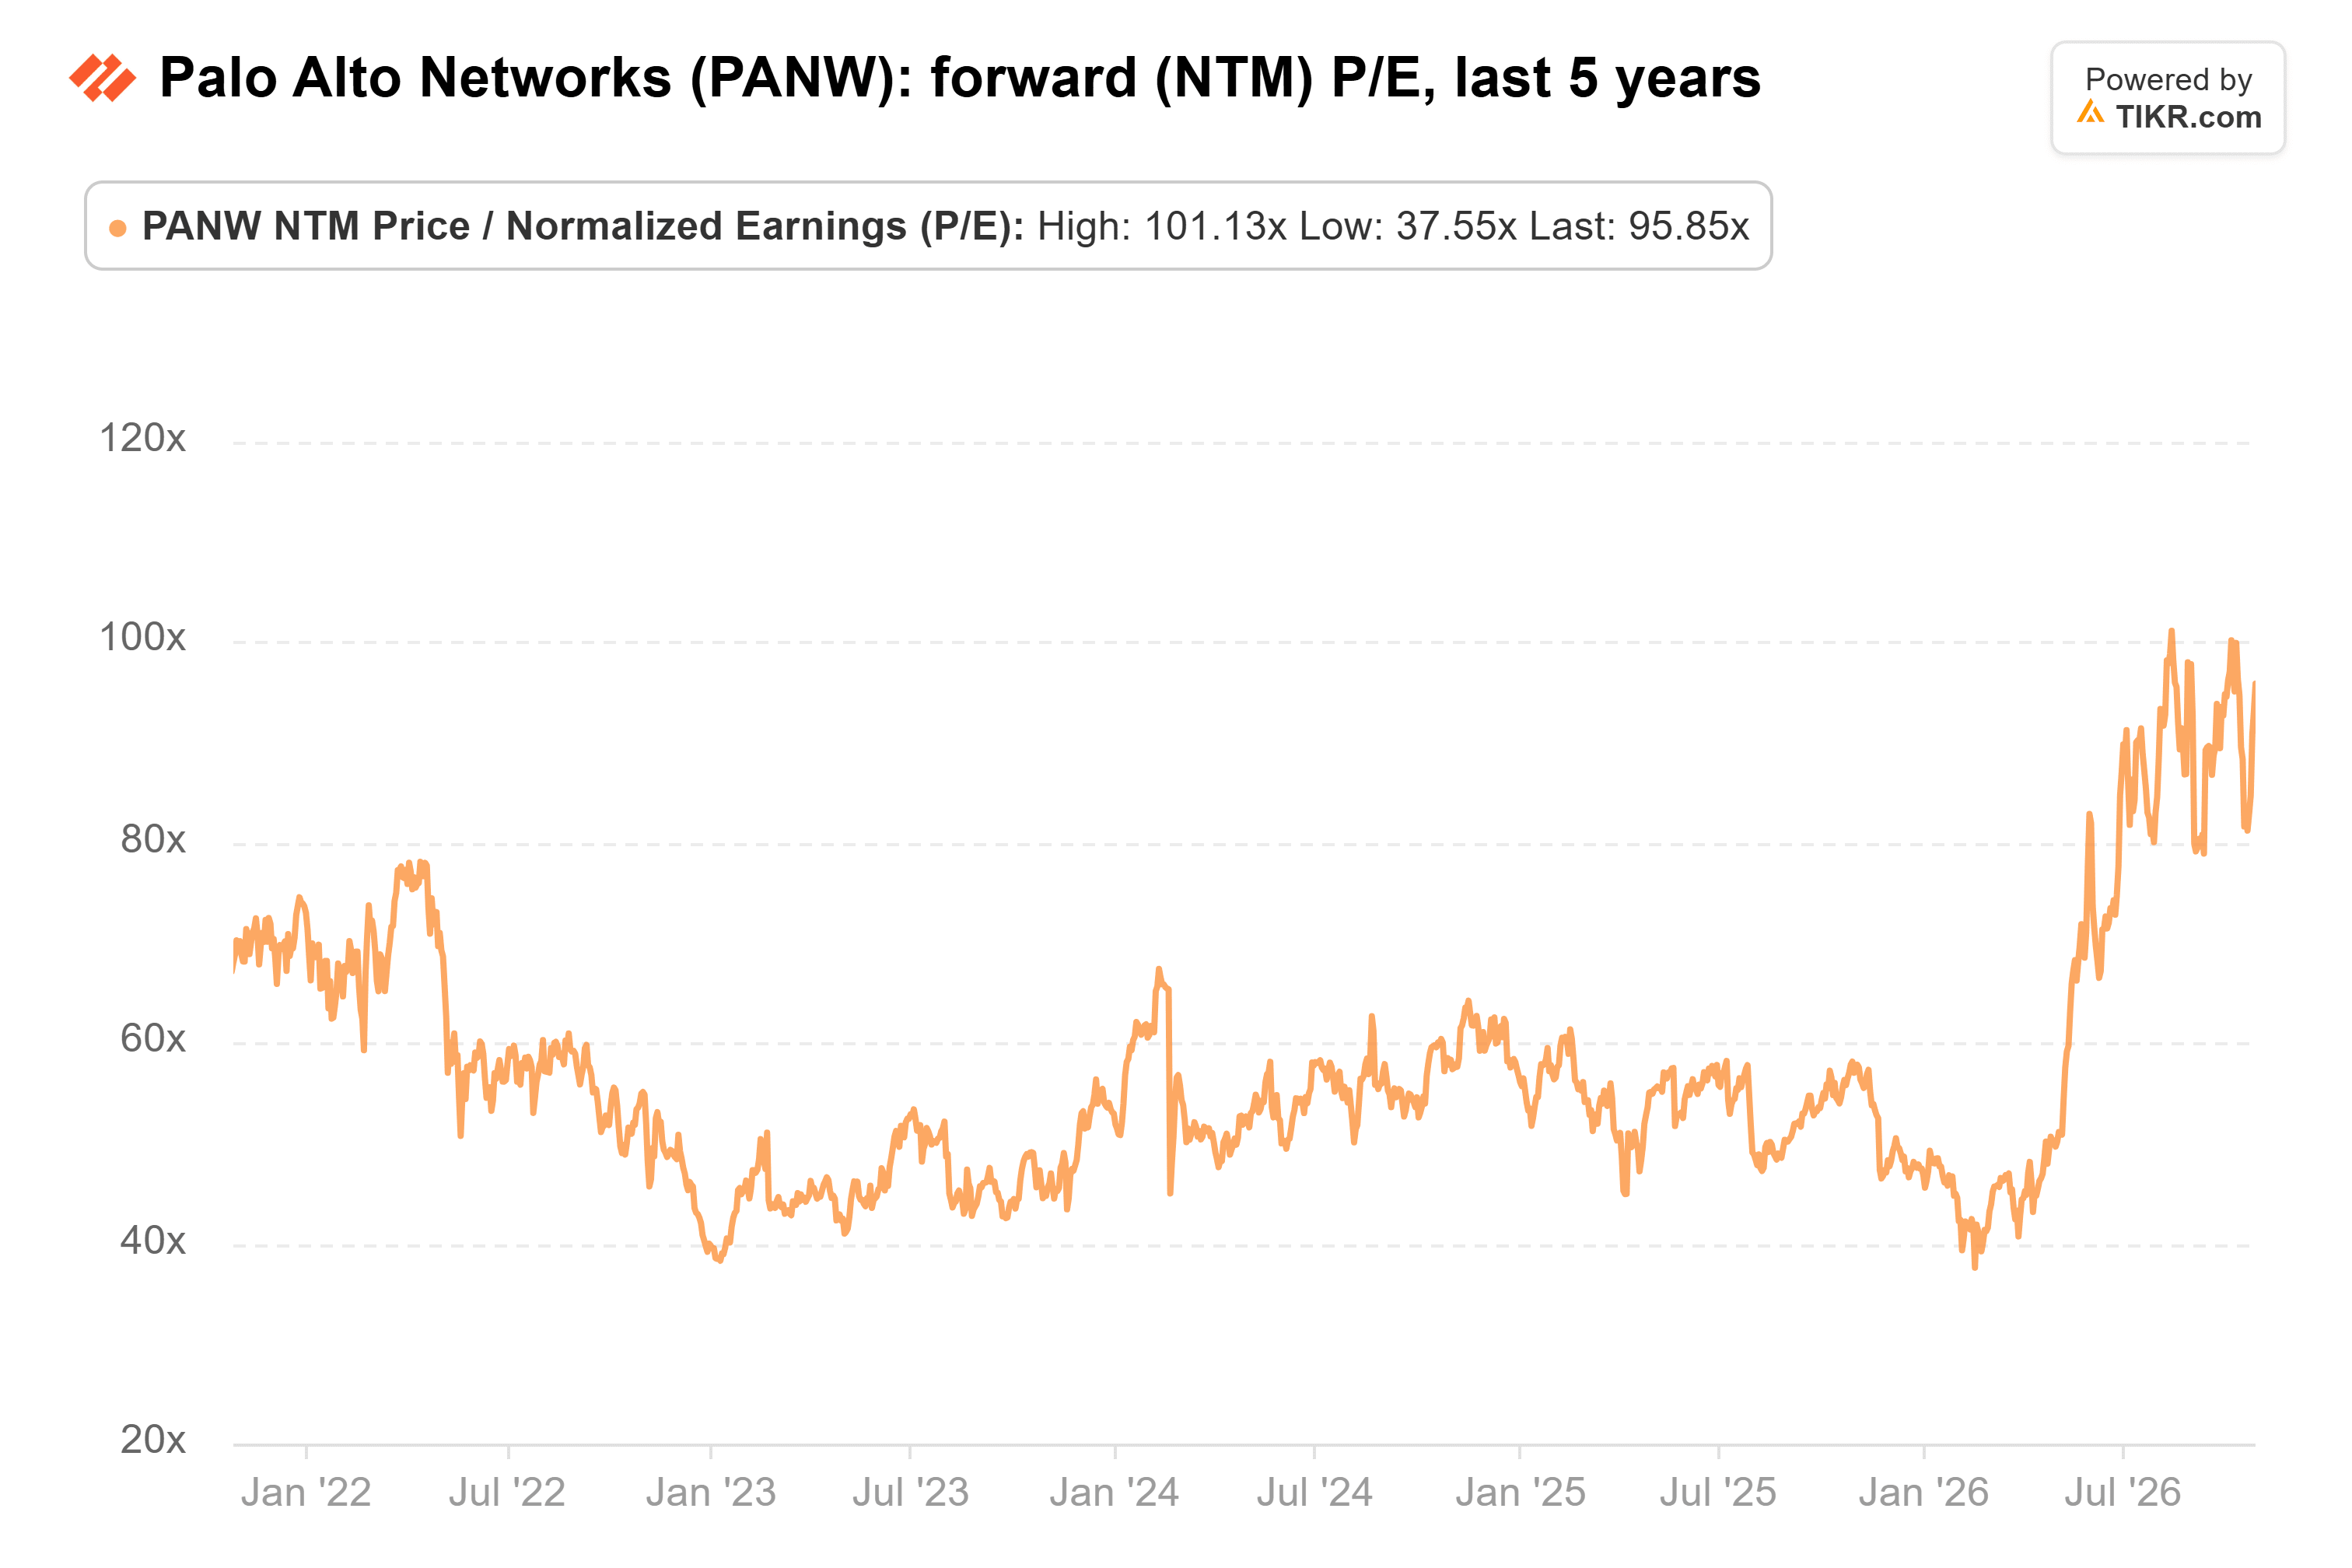
The stock also closed Oct. 28 just under the $399 average analyst target. That’s a lot to pay when management guides fiscal 2027 non-GAAP EPS up just 8% to 9%, as the shares issued for CyberArk spread profit thinner.
The Street expects 23% revenue growth in fiscal 2027 (the year to July), helped by a full year of CyberArk.
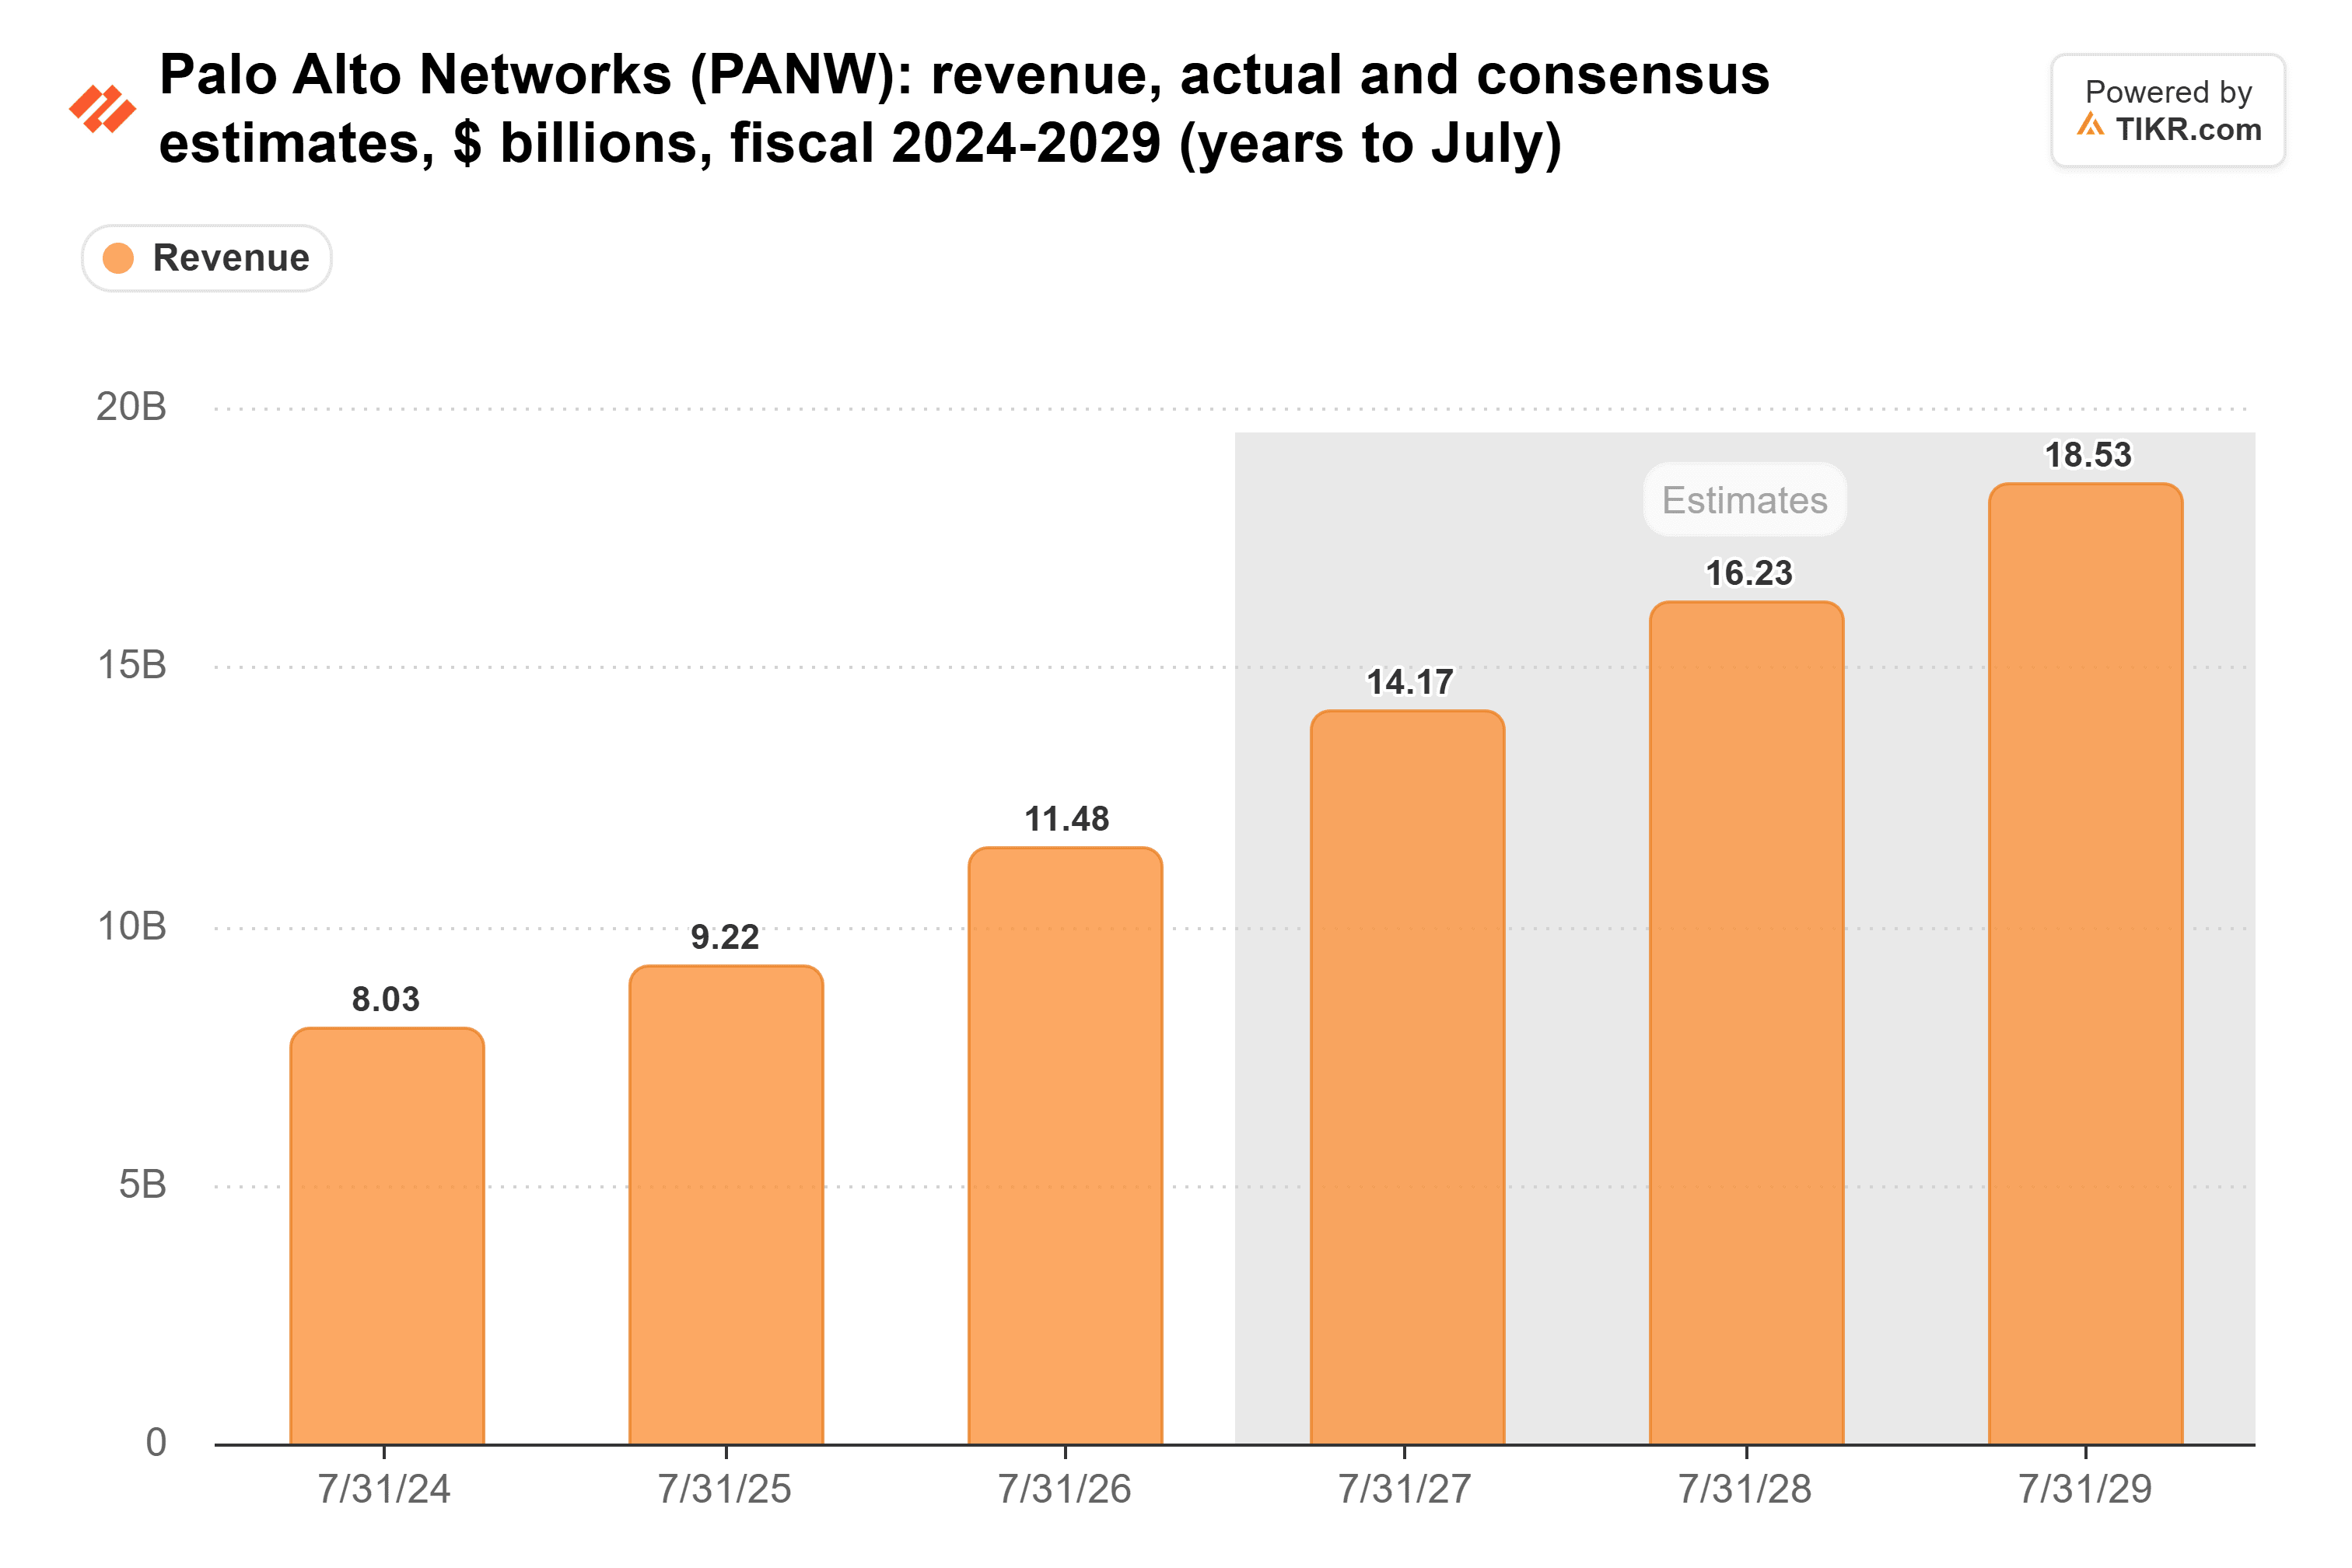
Counting the acquisitions for all of fiscal 2026, management’s own guidance works out to about 15% growth. Nothing Palo Alto reported this week should move the estimates.
CrowdStrike, the other leader in Evercore’s survey, is in the same boat at a richer price. Its net new ARR rose 51% to a record $333 million in its fiscal second quarter (to July 31), and it raised its full-year outlook for net new ARR growth to 34%. But it traded at about 161x forward earnings in mid-October, before this week’s run.
The November report has to back it up
Fiscal first-quarter results are due in mid-to-late November. Management guides next-generation security ARR of $9.54 billion to $9.56 billion, and the end of one big AI customer’s move onto Chronosphere lands in that quarter.
My take: I’d hold Palo Alto here and wait for the report. If ARR clears the top of guidance without leaning on that one customer, a pullback would be a buy.
Of course, another big flaw found by AI before then could keep the group running.
So what is Palo Alto Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Palo Alto Networks for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!