


Key Takeaways
- Palantir stock is down 10% in 2026, even though the company raised its full-year revenue guidance three times, from 61% growth to 91%.
- The stock fell because investors now pay far less for each dollar of expected earnings, even as analysts kept raising their estimates.
- Third-quarter contract value grew just 6%, and the Democrats’ midterm sweep raised fears of a smaller Pentagon budget.
- The forward P/E is well below its five-year average, so the stock looks like a buy for patient investors. Palantir’s first 2027 guidance in February is the next test.
Palantir Technologies (PLTR) stock is down 10% in 2026, even though its revenue growth sped up every quarter this year.
It started the year guiding to 61% revenue growth. It now expects 91%.
Three raises in nine months
Palantir set its first 2026 revenue guide in February and raised it with every report since:
- Feb. 2: $7.18-$7.20 billion, or 61% growth
- May 4: $7.65-$7.66 billion, or 71% growth
- Aug. 3: $8.15-$8.16 billion, or 82% growth
- Nov. 2: $8.53 billion, or 91% growth
The cash guide went up too, with adjusted free cash flow guidance rising from $3.93-$4.13 billion to $4.8-$5.0 billion. In the third quarter, revenue grew 96% to $2.31 billion. U.S. commercial revenue of $984 million also passed U.S. government revenue for the first time. Investors loved the August raise and sent shares up 29% the next day.
TIKR tracks 33 analysts on Palantir. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palantir, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palantir’s Analyst Ratings
Then bookings slowed and Congress flipped
Shares hit a 52-week high in October and are down 25% from it. The first blow came in the third-quarter report: the value of new contracts Palantir signed grew just 6% to $2.92 billion. U.S. commercial remaining deal value rose only 4% from the second quarter. Management blamed shorter Sovereign AI contracts. Either way, that’s a long way from the record $4.26 billion of contract value Palantir signed in the fourth quarter of 2025.
On Nov. 5, Palantir fell 10% after the Democrats won both chambers of Congress. Investors worried about a smaller Pentagon budget and slower AI data-center spending. Palantir is exposed to that: U.S. government revenue was $953 million, or 41% of third-quarter revenue.
Anthropic also set its IPO price range. By one investor’s math, that range would value the AI lab at less than Palantir relative to sales. Yet Anthropic’s S-1 shows first-half revenue about 14 times what it was a year earlier. Analysts already expect Palantir’s own growth to slow sharply after this year:
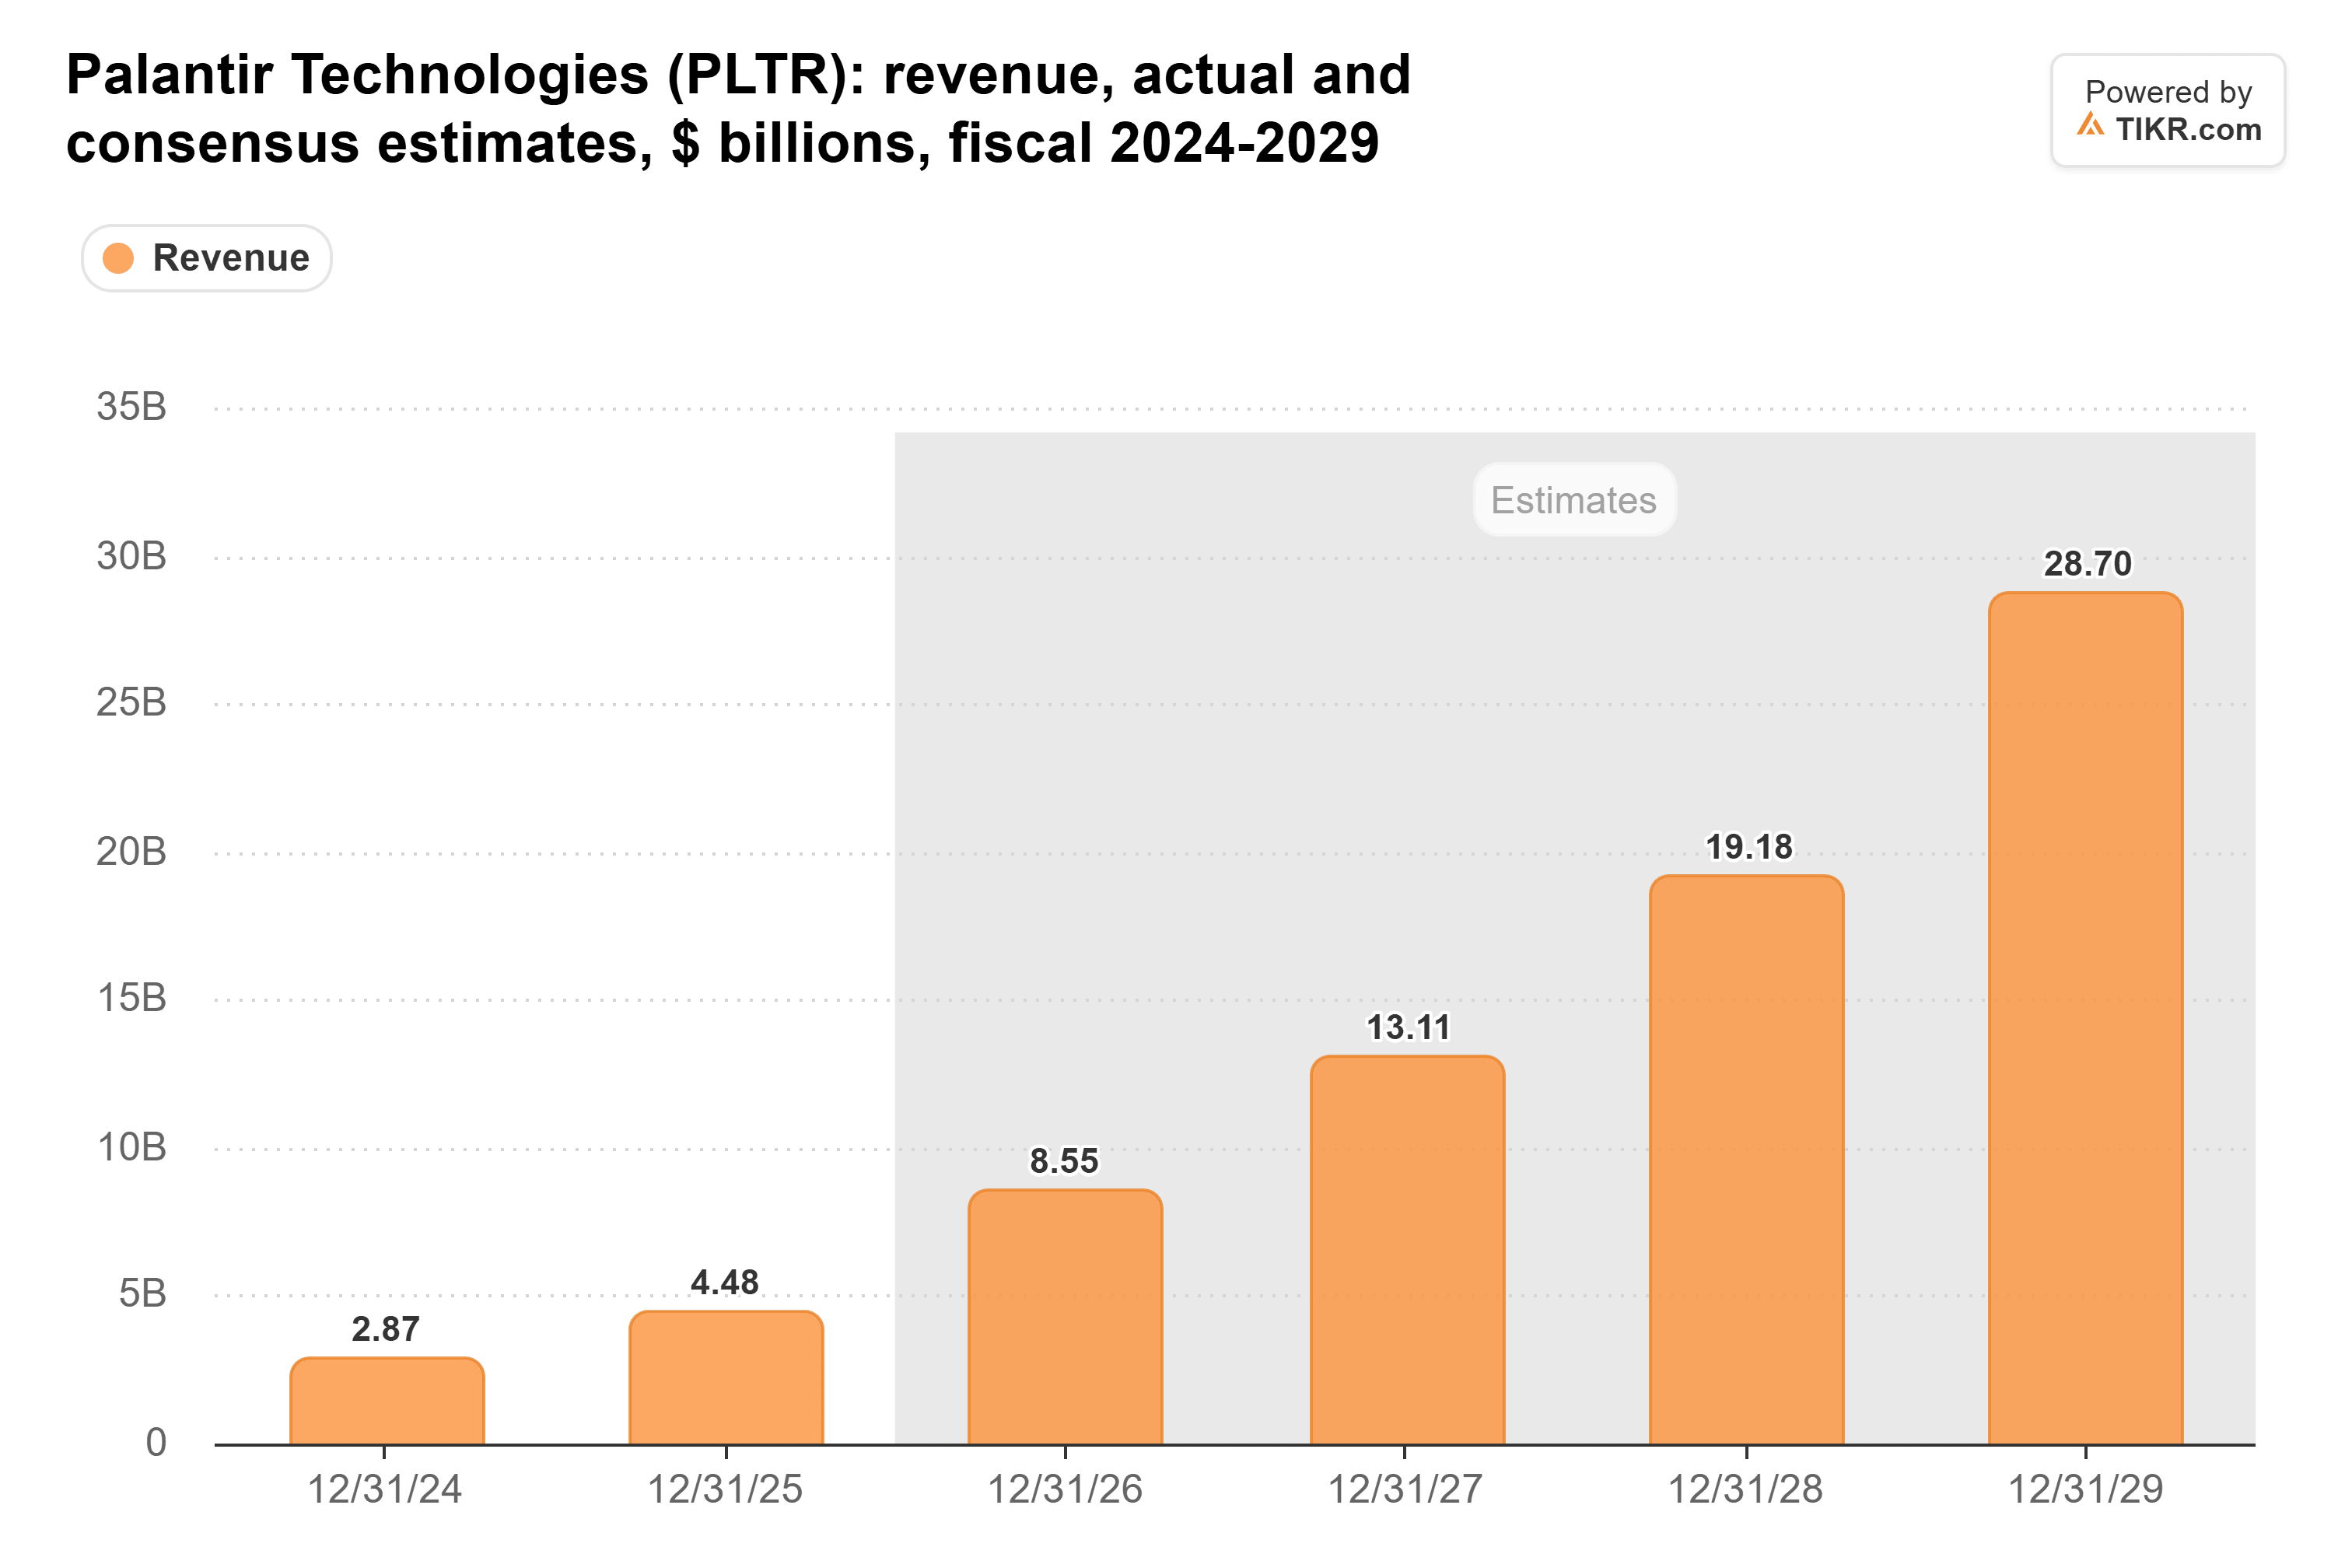
That’s about 91% growth this year, then 53% in 2027 and 46% in 2028.
Time to load up, with one eye on February
Earnings estimates kept climbing through all of it. Consensus normalized EPS for 2026 now stands at $1.70. Palantir’s margins keep rising because revenue is growing much faster than headcount, and its GAAP operating margin hit 47% in the third quarter.
Investors now pay far less for each dollar of those earnings. Palantir’s forward P/E is down to 73x, against a five-year average of 102x and a peak of 270x in October 2025:
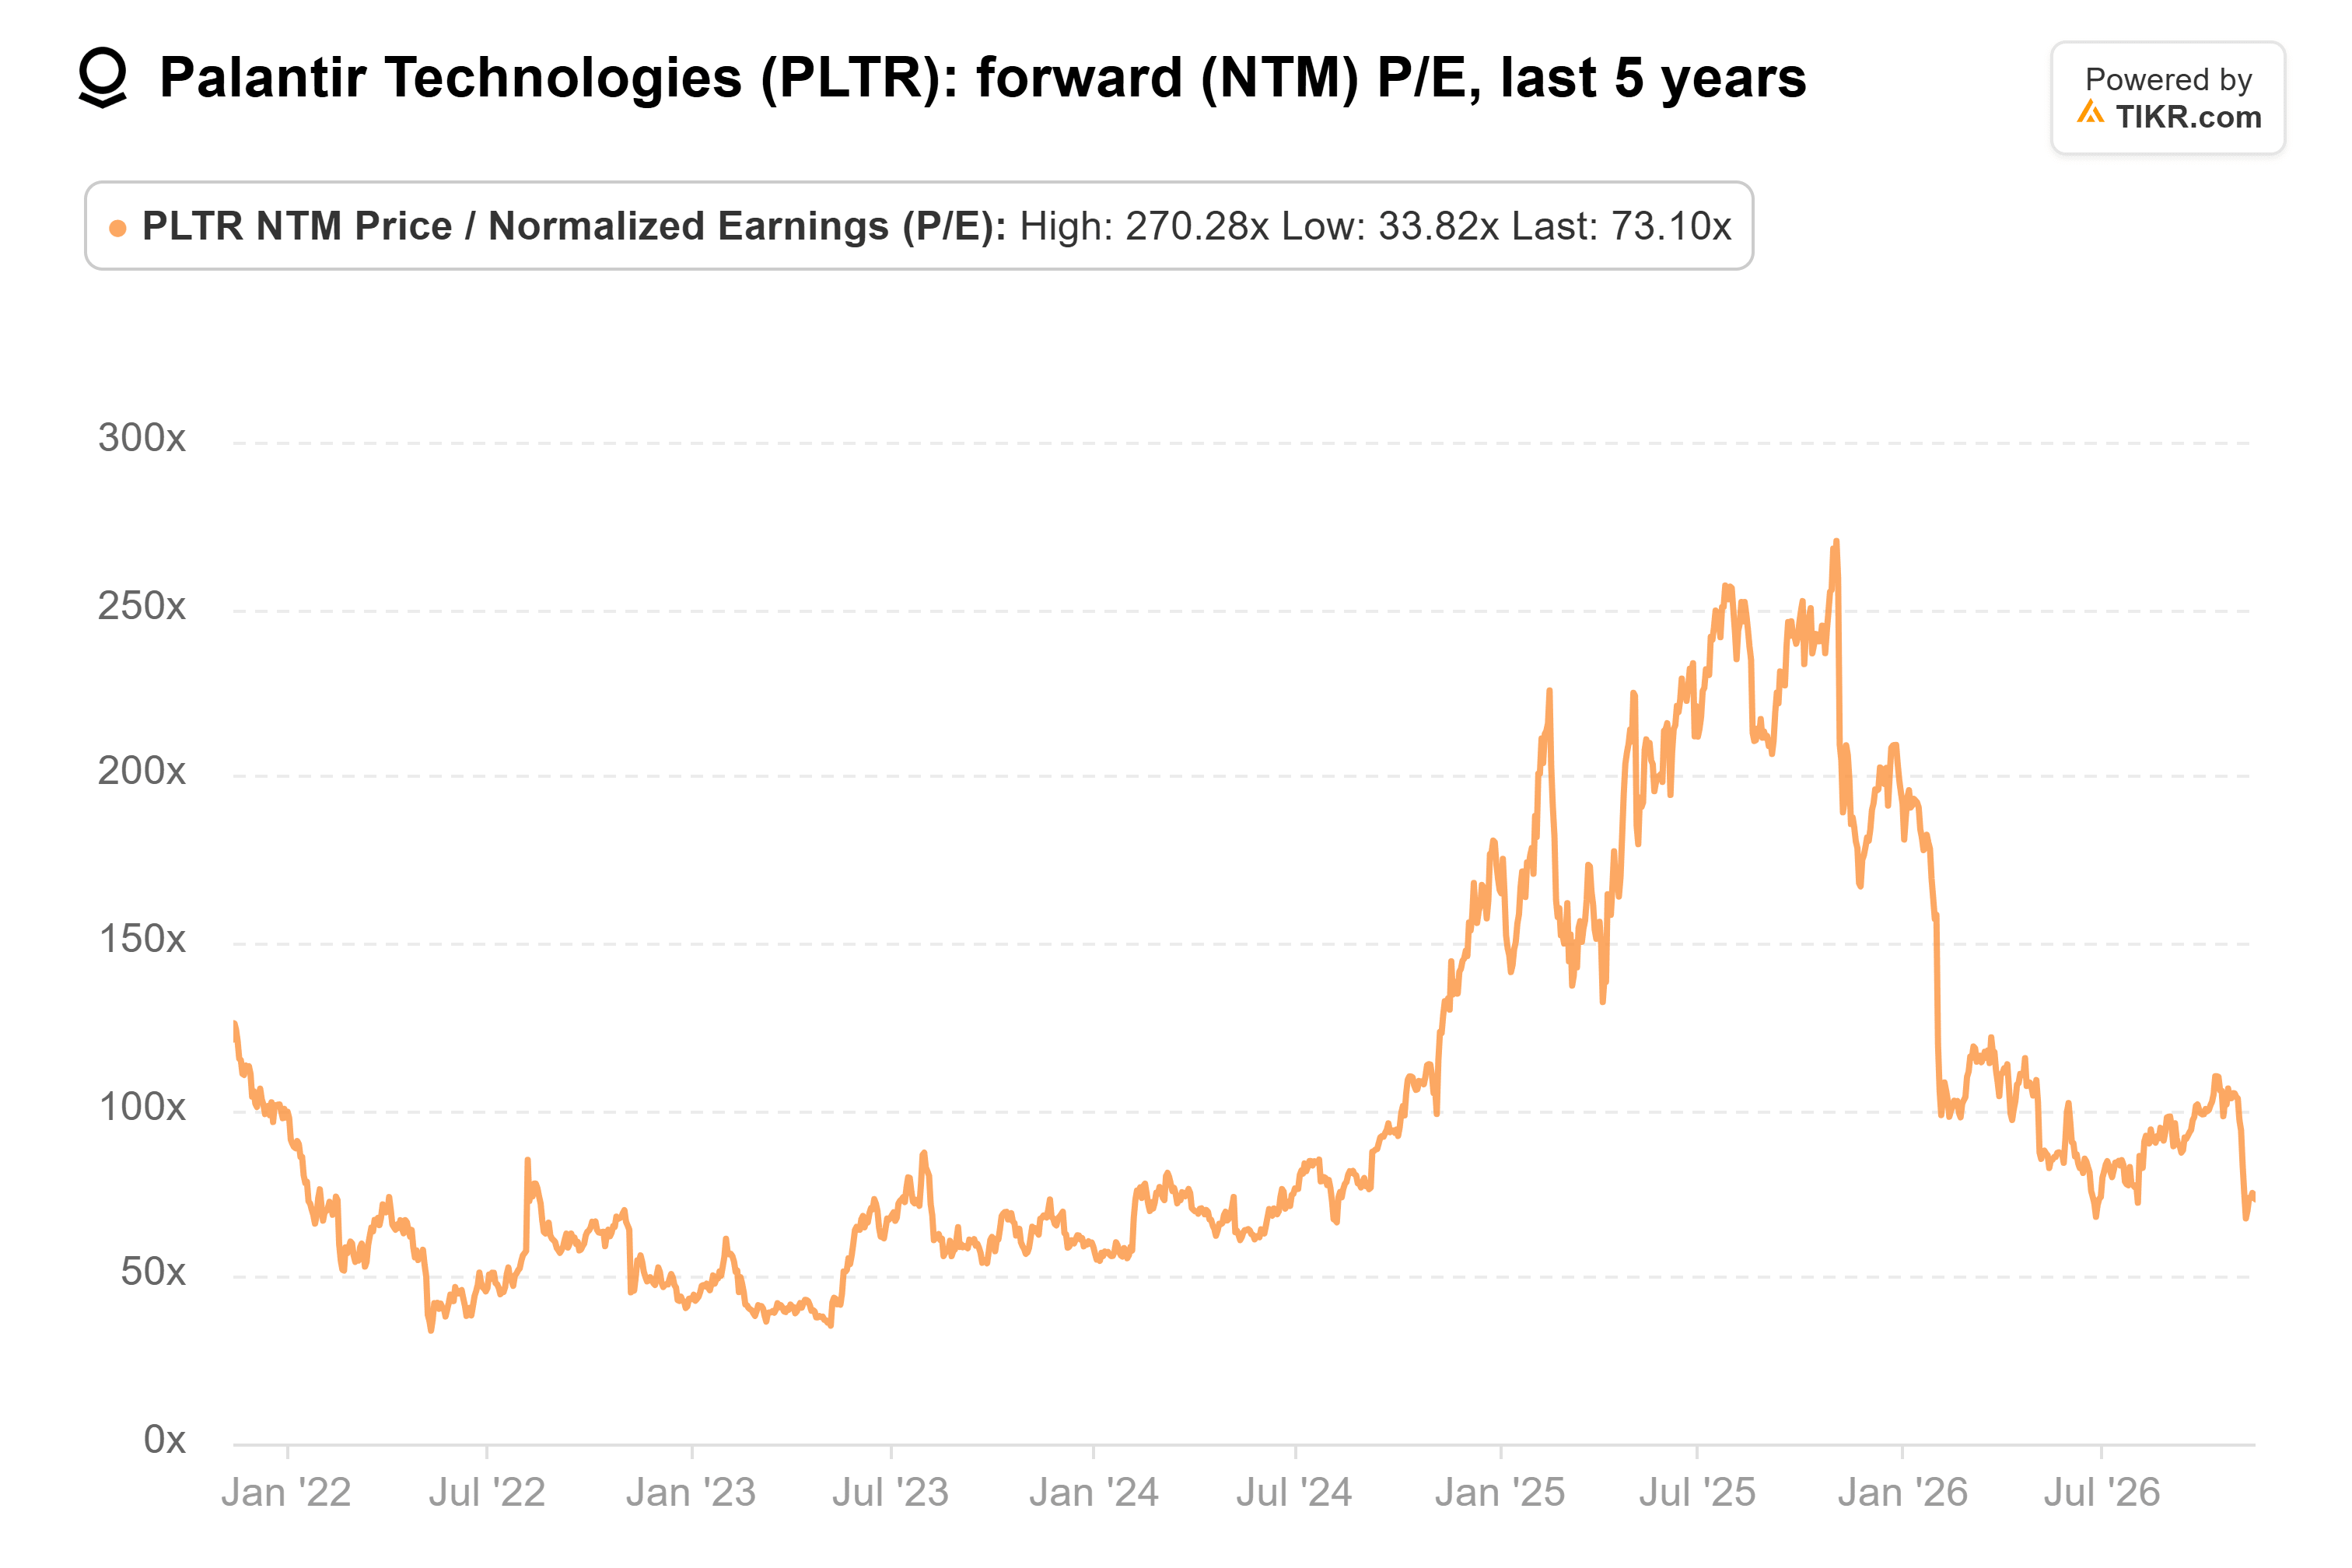
(It’s even lower after the latest drop.)
Analysts’ price targets have gone up. The consensus target rose from $184 a year ago to $222, 39% above the latest close:
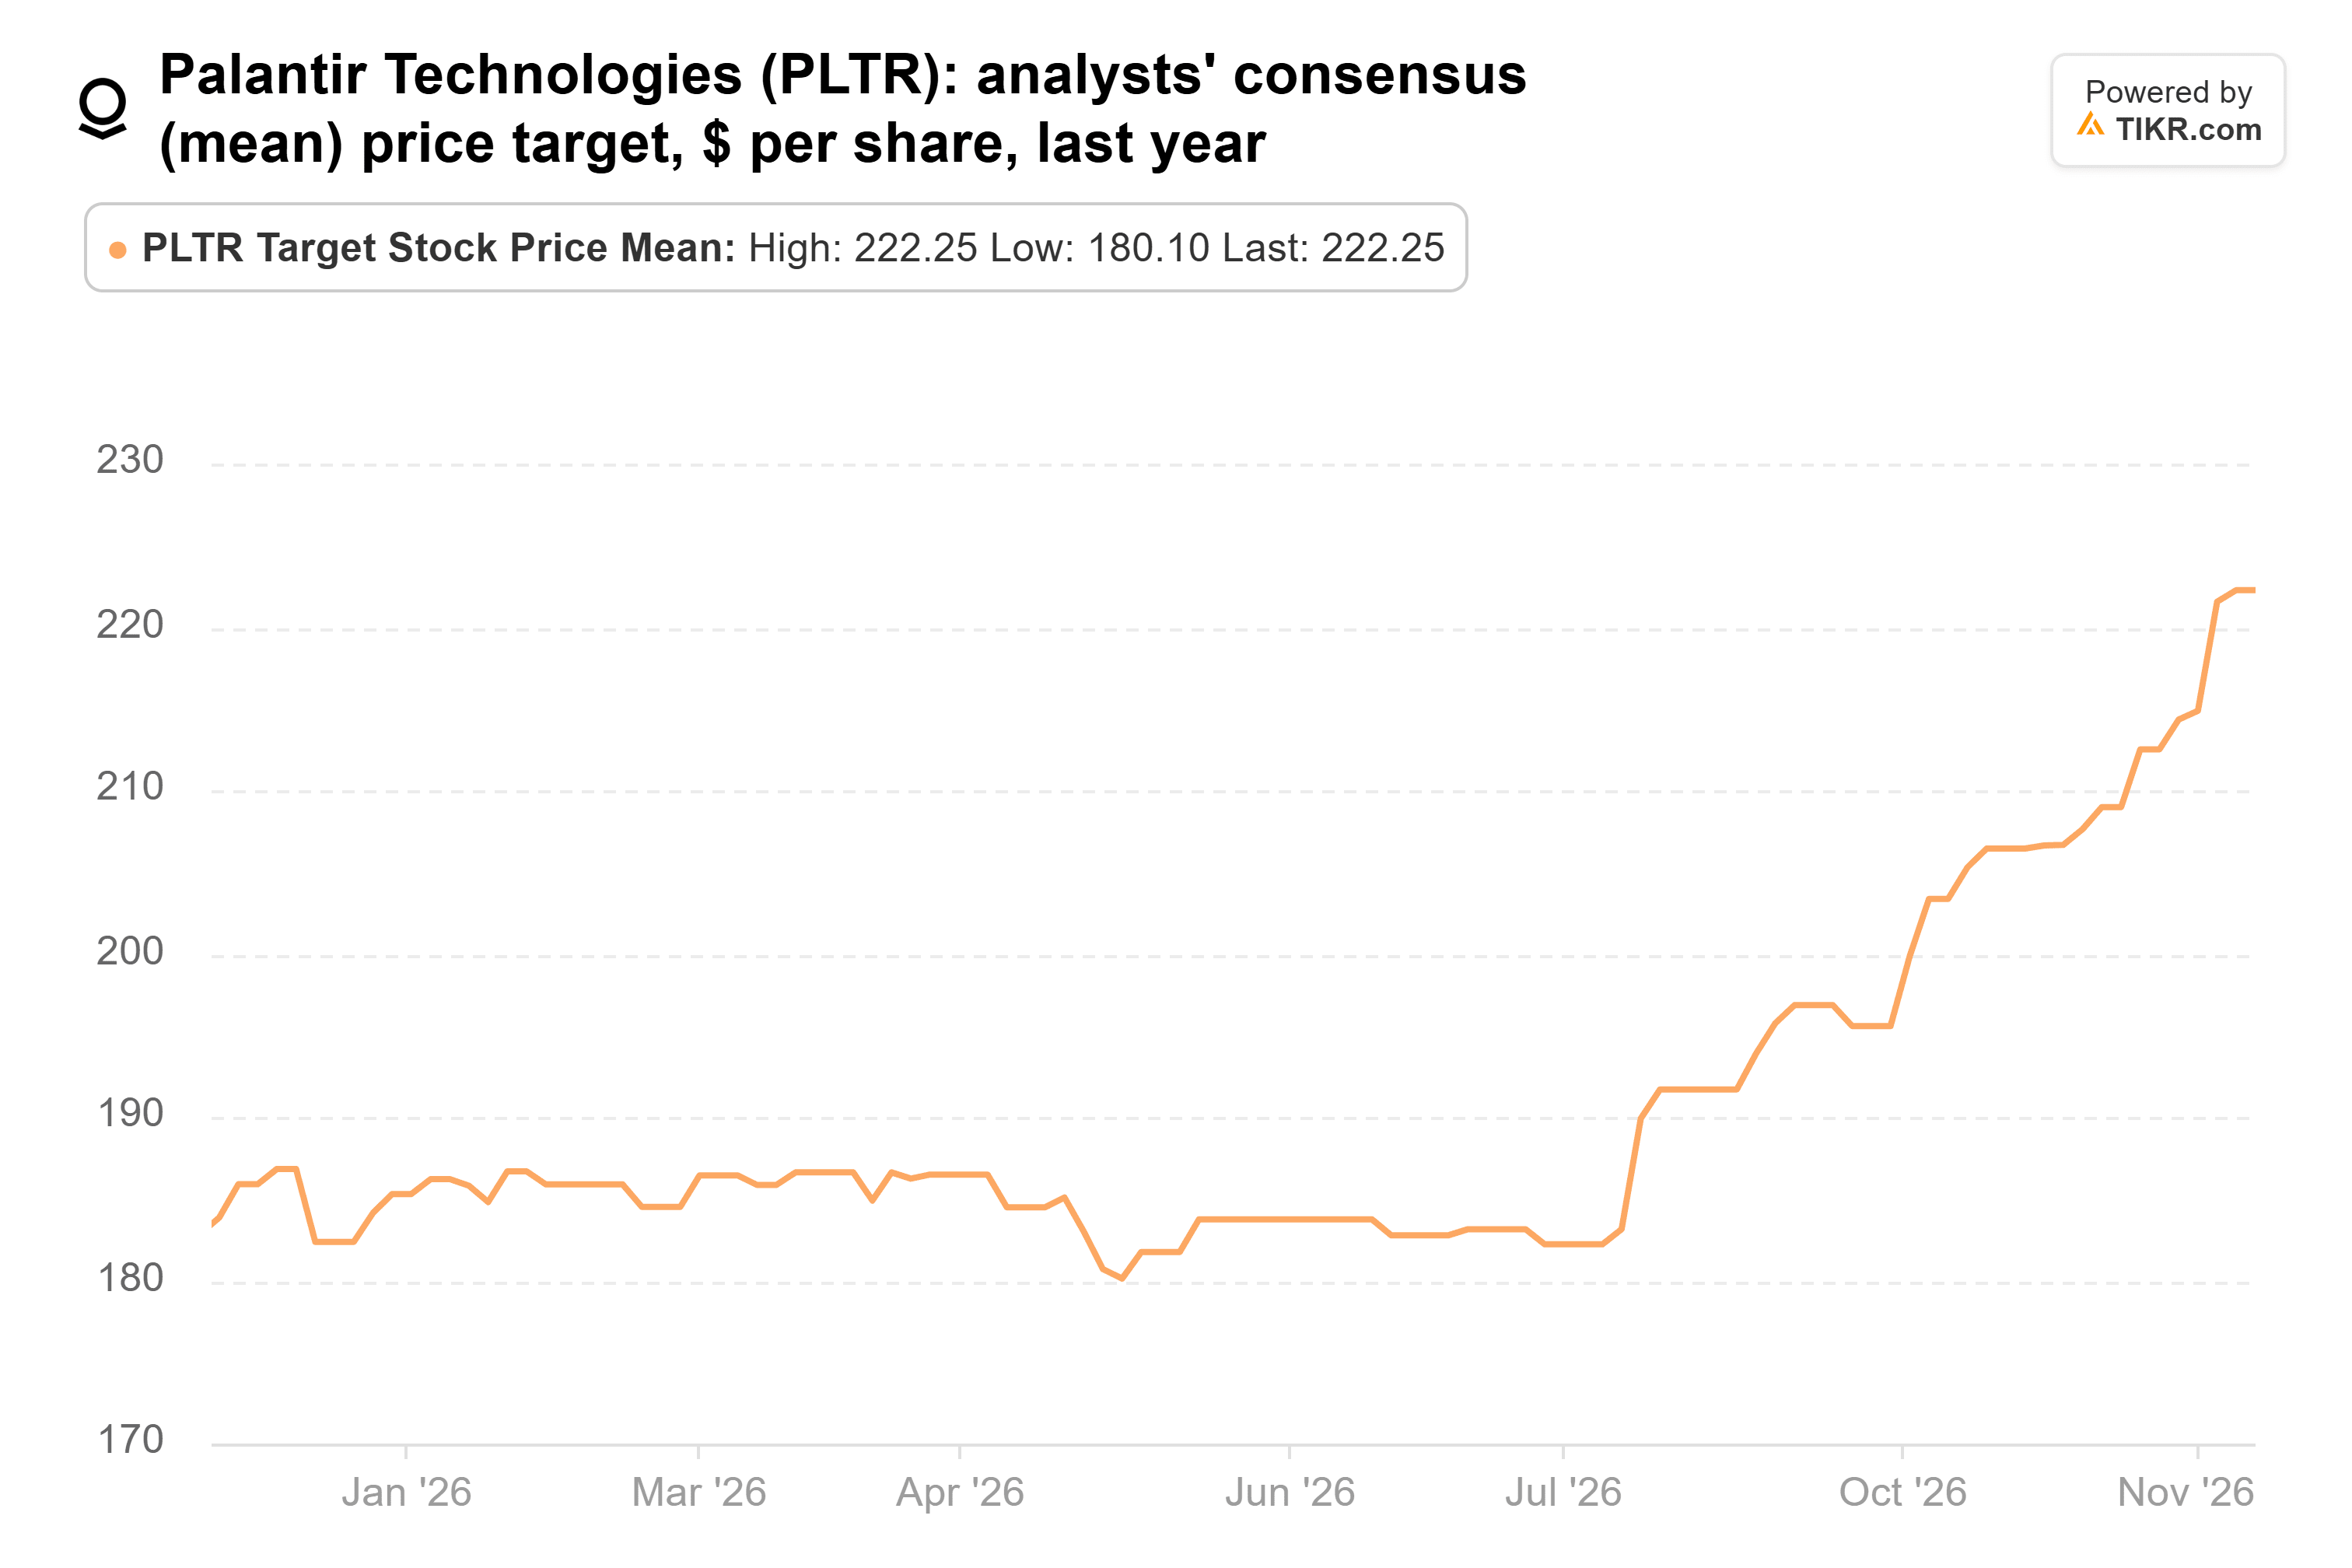
On Nov. 16, Phillip Securities raised its target to $248 from $215 and kept its Buy rating. That target is 55% above the same close.
Of course, 73x is still a rich price, and analysts expect Palantir’s growth to slow sharply next year.
Frankly, at this price I’d be loading up. If Palantir earns anywhere close to what analysts expect, the stock can climb with its earnings, even if the multiple never gets back to its average.
The next test comes in early February. The fourth-quarter report will bring Palantir’s first 2027 guidance, which investors will compare with the $13.1 billion of revenue analysts expect. If the guide comes in below that, or contract signings stay slow for another quarter, 73x won’t look like such a bargain.
So what is Palantir stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palantir could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


