Key Takeaways
- Nvidia shares are down 48% from their high after Jensen Huang’s departure as CEO and a report that the SEC is examining the company’s accounting.
- Nvidia’s biggest customers are building their own chips with Alphabet and Broadcom, and AI labs are moving code onto chips from AMD.
- Nvidia’s best defense is to become a frontier lab itself, and its Nemotron models give it a lead no other chip seller has.
- Huang’s exit puts the plan’s funding in question, but the stock trades far below its usual forward multiple.
The biggest threat to Nvidia (NVDA) may be the companies writing it the biggest checks.
An investor who posts on X as PersianMacroGuy made that case in a post about Nvidia without Jensen Huang: “NVIDIA has to become a frontier lab faster than frontier labs are becoming chip companies.”
Those customers have already started. Alphabet (GOOG) has its own TPU chips, and the post says OpenAI and Meta are building custom chips with Broadcom (AVGO). The Economist reports that Anthropic and OpenAI are using more chips from AMD (AMD) and Google, “helped by the very models these labs are developing, which make it easier to rewrite chunks of code to run on other chips.”
Analysts still see earnings climbing
On Friday, Reuters reported that SEC enforcement staff are examining potential accounting issues at the company, citing two people briefed on the matter. The SEC declined to comment, and the shares fell 13% that day.
An accounting probe puts the E in P/E in question. Even so, analysts expect normalized EPS to roughly double, from $4.77 in the year ended January 2026 to $9.67 this fiscal year, and to reach $25.66 in the year ending January 2030:
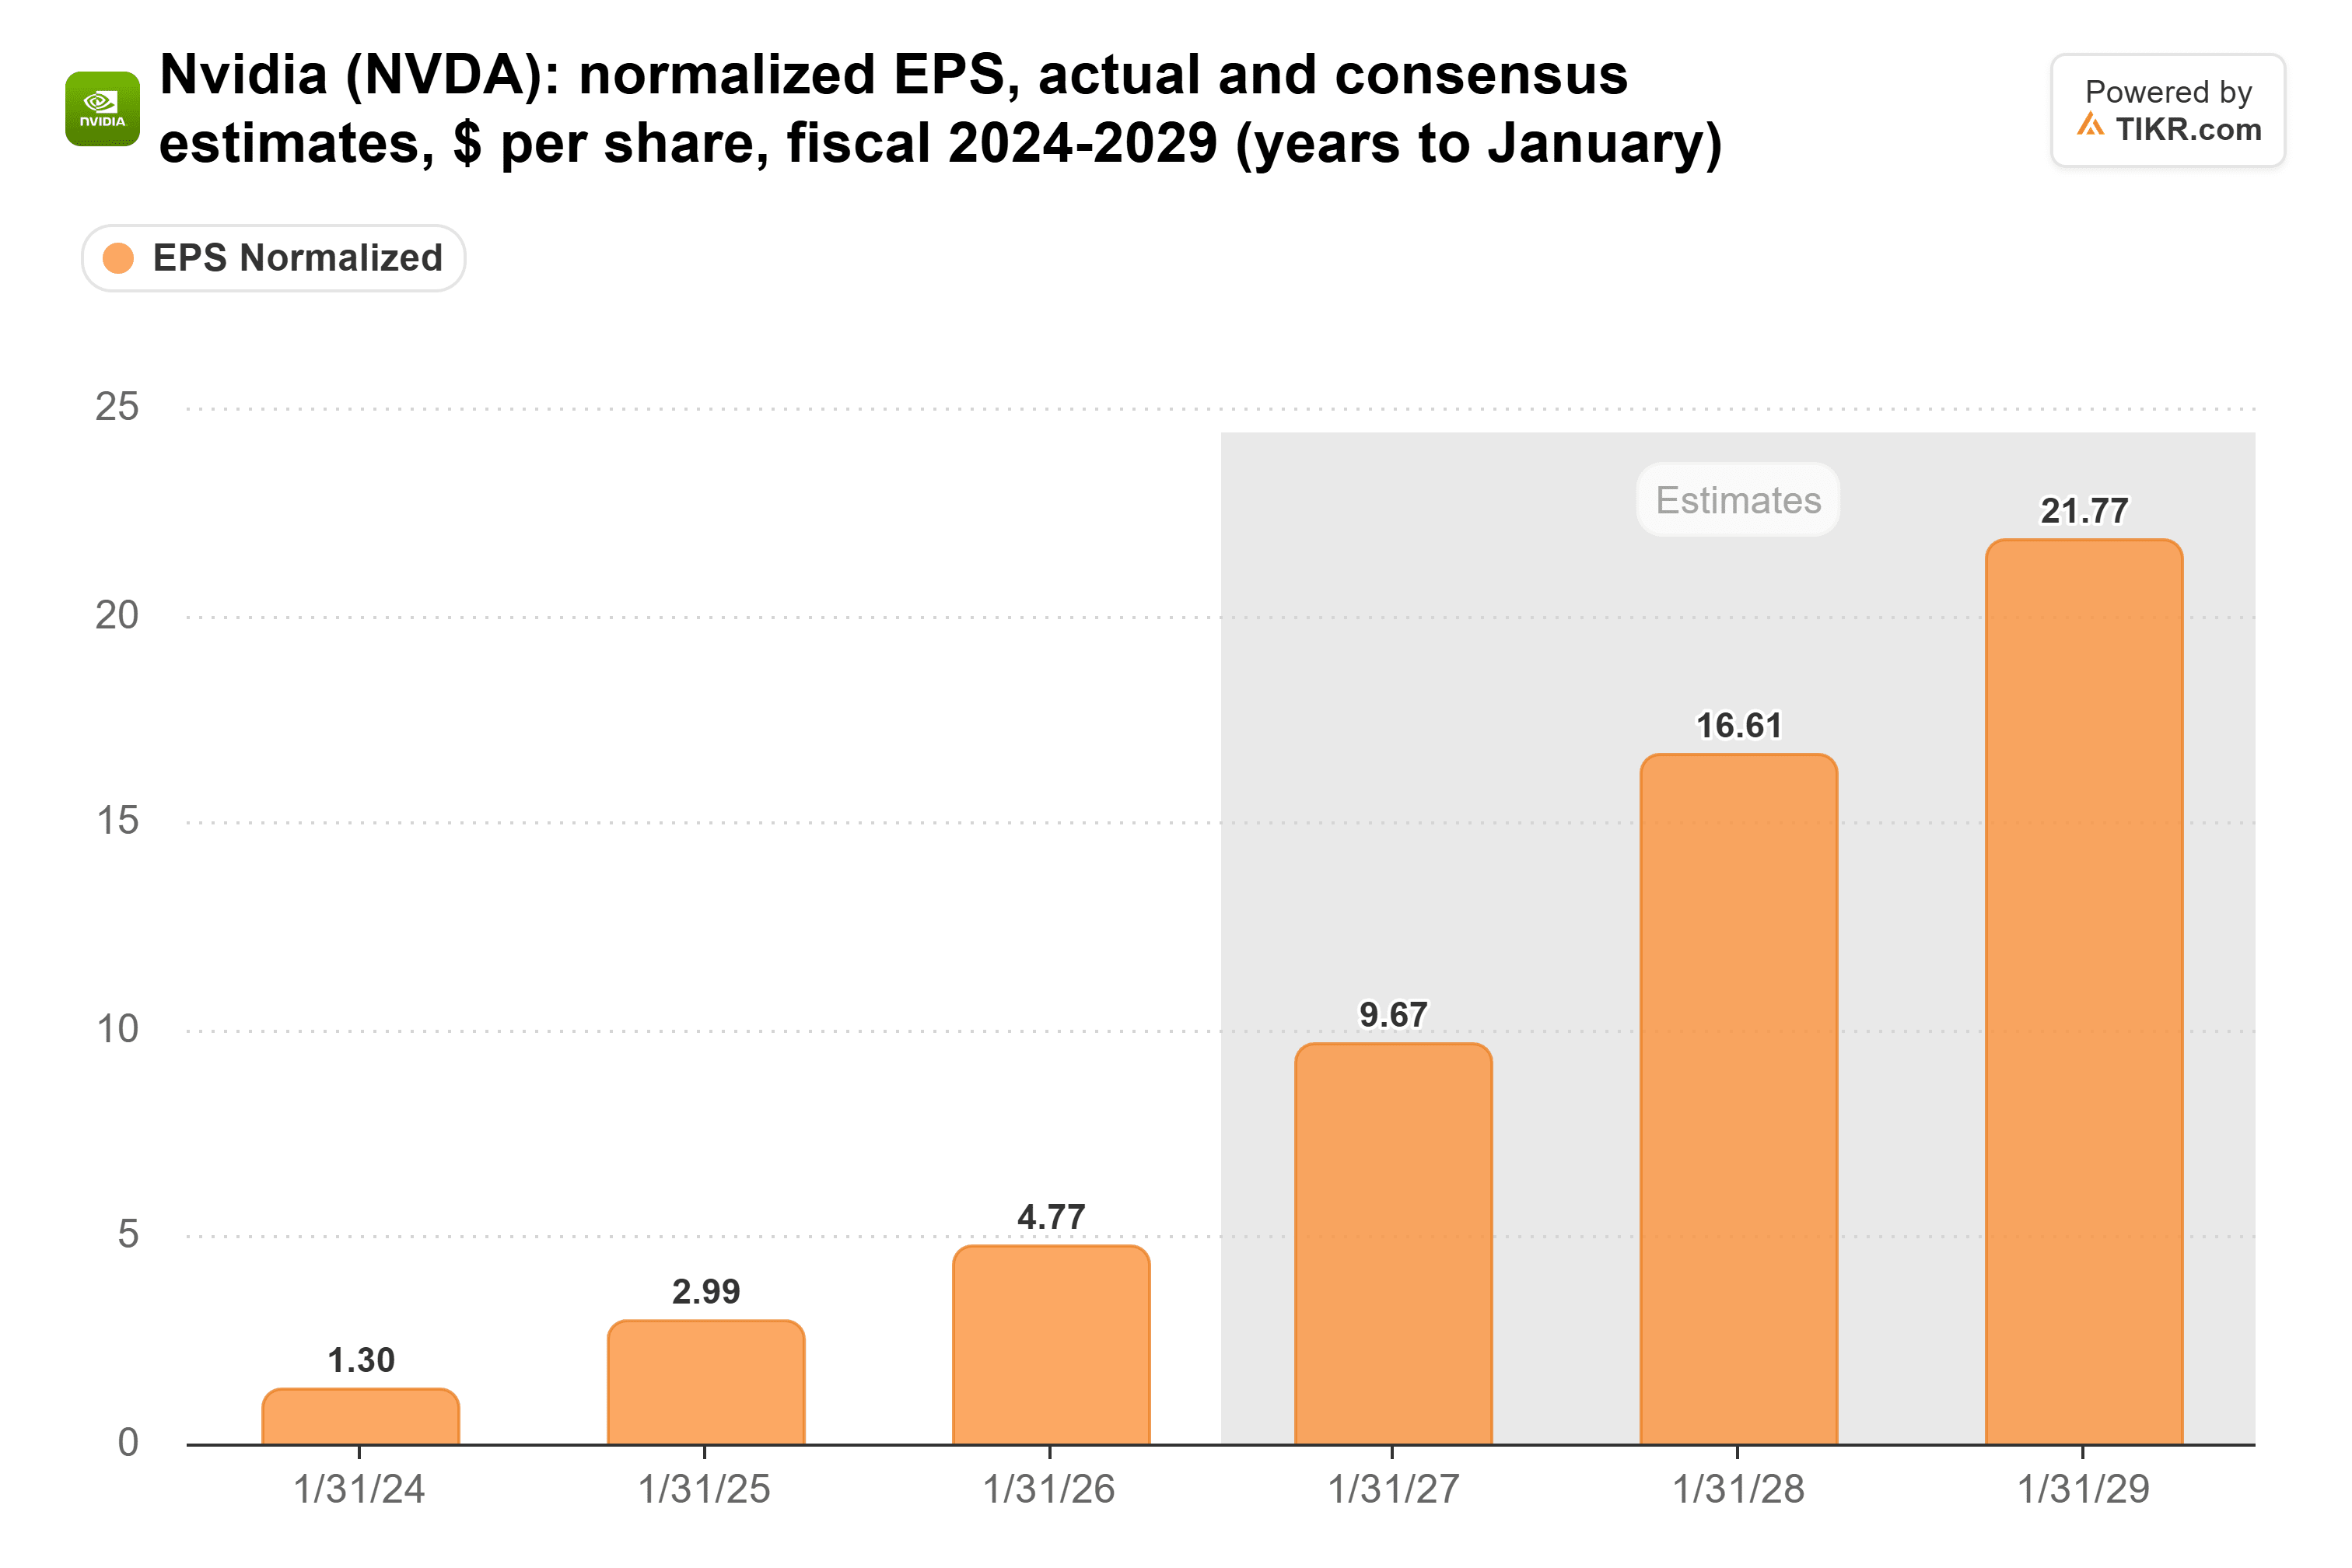
(Those estimates came before anyone outside the SEC knew what it’s examining.)
TIKR tracks 63 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
The labs want their margins back
Nvidia’s margins are exactly what its customers are building chips to get away from. It kept 71.1% of its revenue as gross profit in the year ended January 2026, after 75.0% the year before:

An AI infrastructure CEO made the same point in a clip Harry Stebbings posted on X: “If you are serving frontier models, it is important that you are not squeezed all the way down by very high margins on incumbent chip players.”
And the money is already moving. Broadcom’s AI semiconductor revenue, which counts custom accelerators and networking together, grew 221% to $16.7 billion in its quarter ended Aug. 2. Nvidia’s data center revenue grew 117% to $89.0 billion in its quarter ended July 26. Broadcom is growing faster from a much smaller base, and it guided to $21.7 billion for the quarter ended Nov. 1.
Nvidia’s answer is its own models
On its third-quarter call on Nov. 17, Nvidia said Nemotron, its family of open models, is now the most widely used open model on OpenRouter.
Open models matter here because of where they run. If closed labs win, PersianMacroGuy argues, enterprises “just call their APIs running on the labs’ own custom silicon and NVIDIA gets cut out.” With an open model, the company running it picks the hardware, and Nvidia wants that hardware to be its own.
Nvidia already spends like a lab, too. R&D rose 43% to $18.5 billion in the year ended January 2026, and in September it agreed to buy Hugging Face for about $11.9 billion. Neither Broadcom nor AMD has an open model at the top of OpenRouter.
Losing Huang could cost Nemotron its funding
Nathan Lambert of Interconnects AI argued that Huang’s departure is a setback for US open models, and he expects that funding will very likely dry up. Paying for free models that compete with your own biggest customers is a hard call for a new CEO in the middle of an SEC probe. Nvidia has the money: it generated $96.7 billion of free cash flow in the year ended January 2026. What’s unknown is whether its leadership will keep spending it on models.
The market is pricing Nvidia like a shrinking chip seller
After the slide, Nvidia trades at 8.7x forward earnings. Its average over the last three years is 30x, and it peaked at 47x in June 2024:
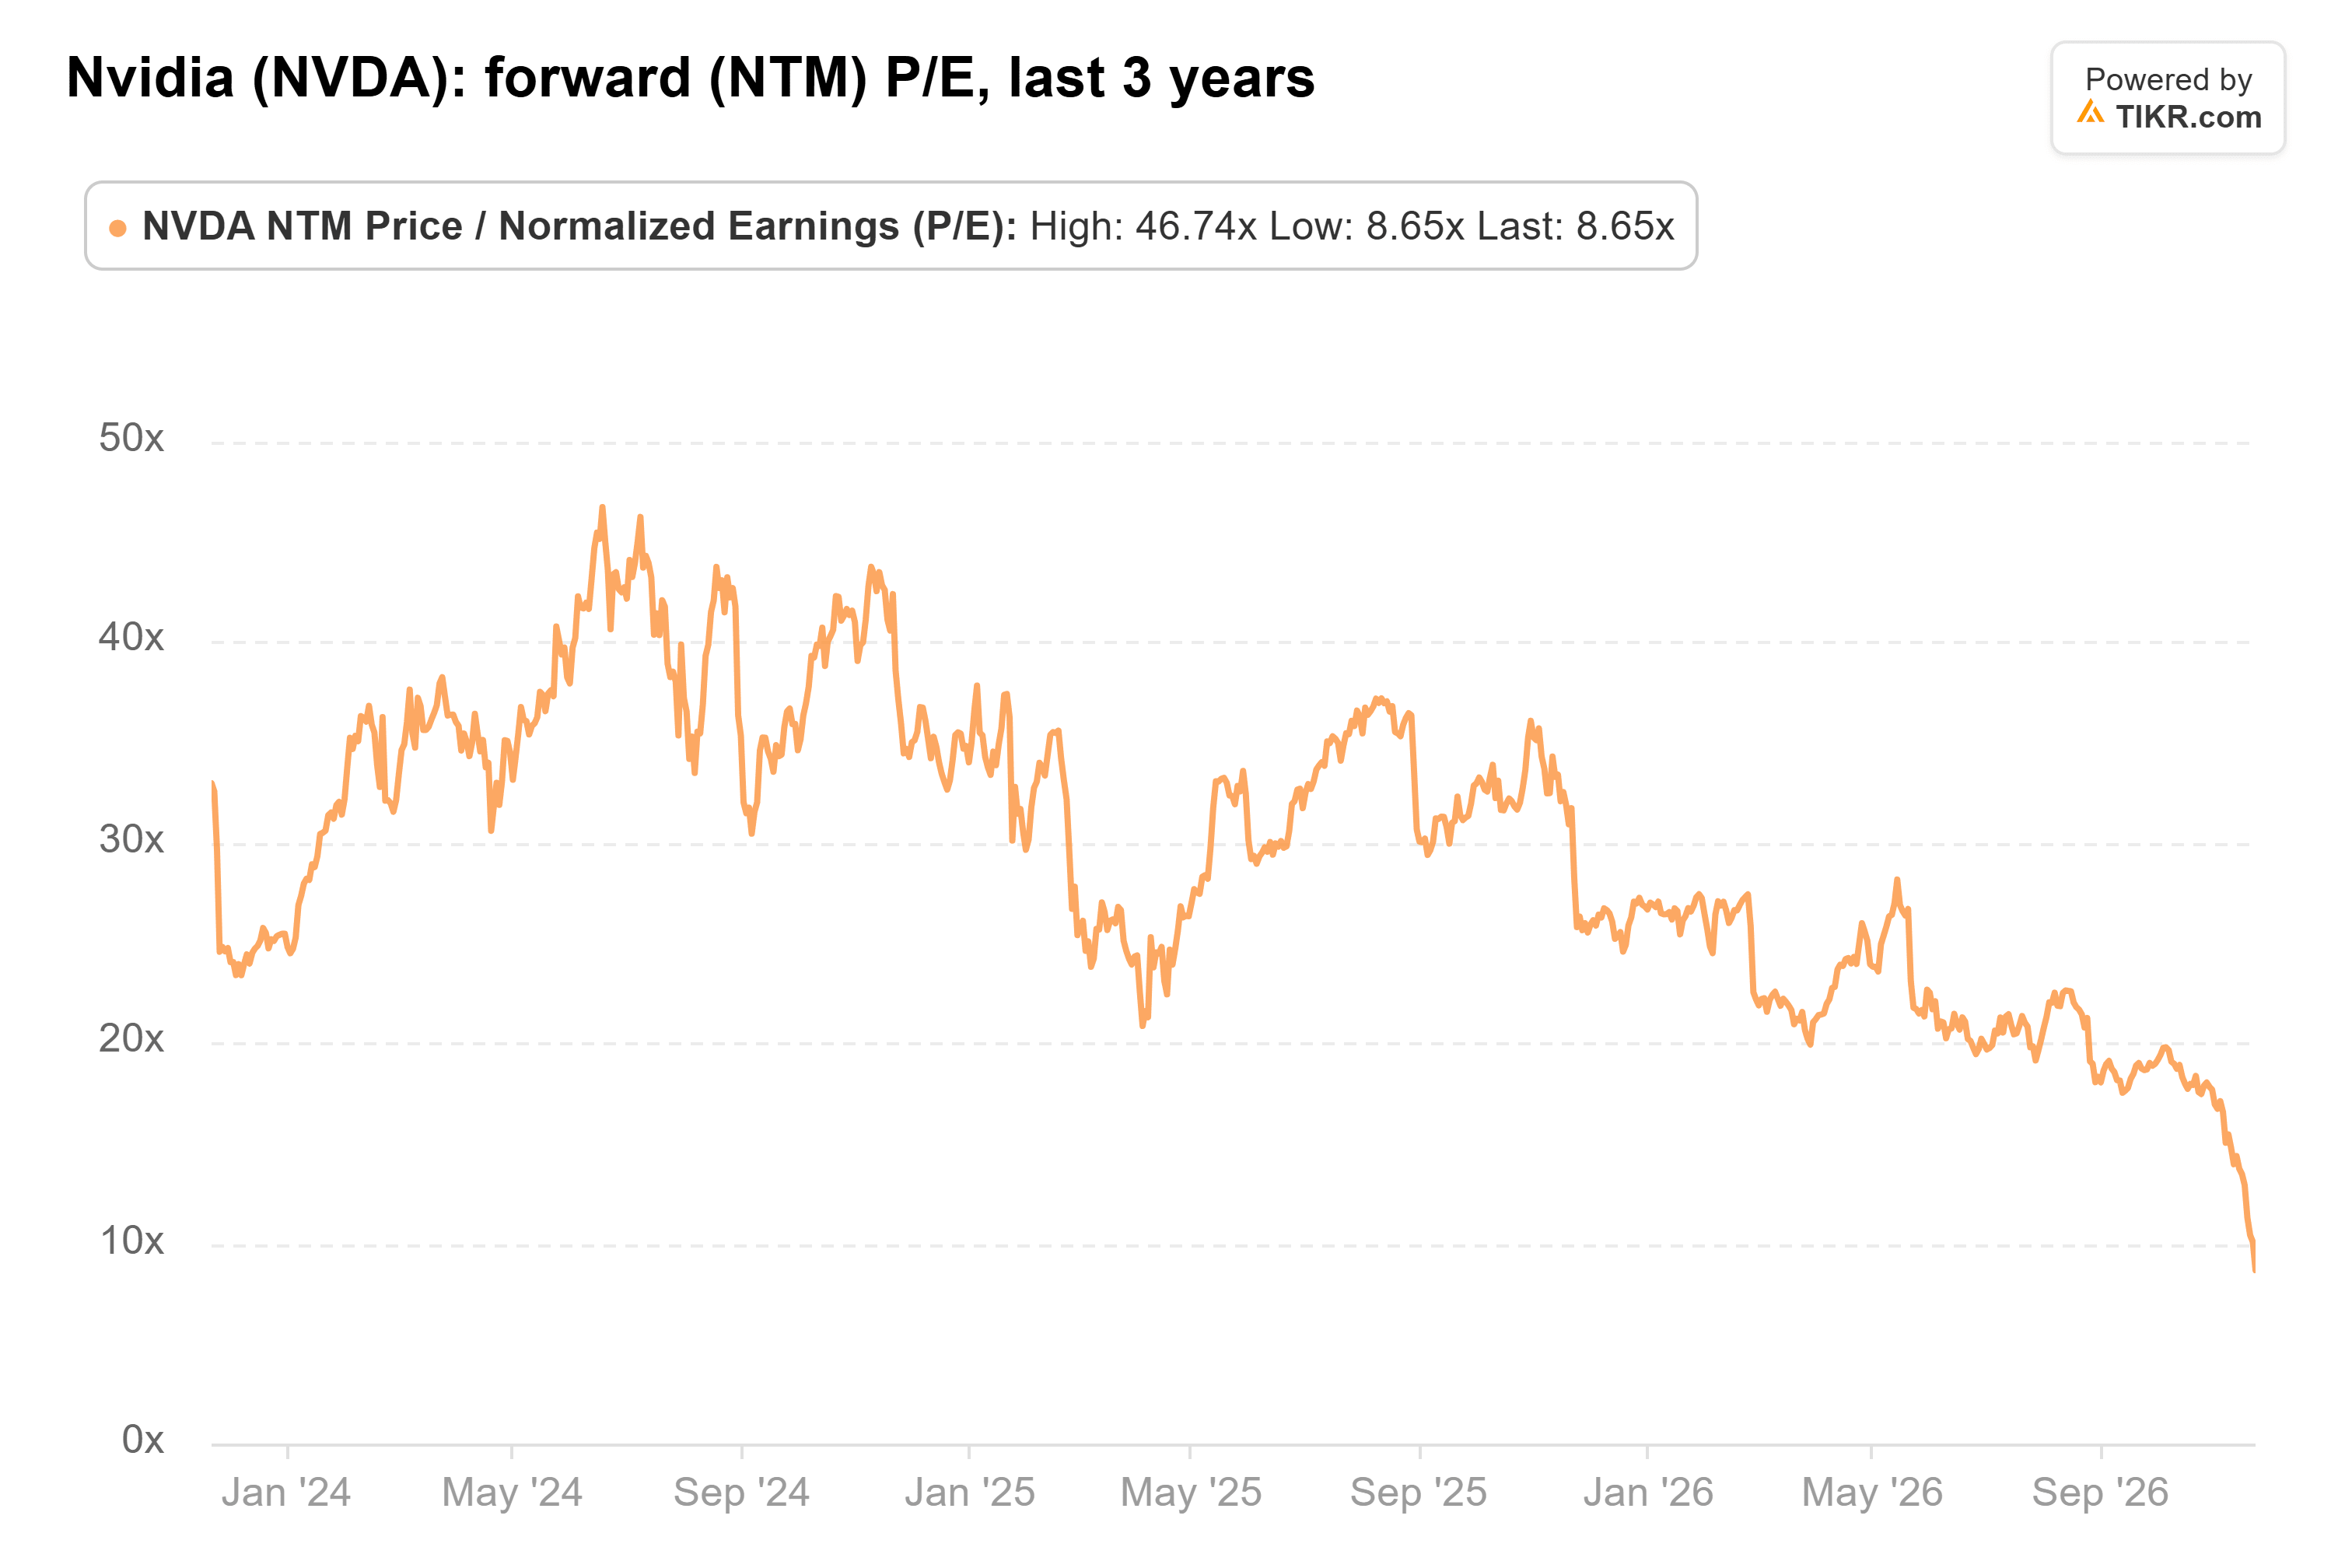
The way I see it, that multiple prices Nvidia as a chip seller watching its best customers leave, and it gives nothing for the model business that could keep them close. Nvidia’s strategy is right, it has the cash to pay for it, and it has the lead.
We’ll get an early read on Dec. 9. If Broadcom’s AI revenue beats its $21.7 billion guide, the labs are building chips faster than Nvidia is building its lab.
So what is Nvidia stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nvidia could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!