Key Takeaways
- Dan Niles says supply, not demand, caps NVIDIA’s 70% growth outlook, leaving a cushion.
- On the Street’s numbers, that cushion is about $120 billion, or 15% of demand, not 30%.
- Niles still expects calendar 2027 estimates to fall, so a cautious outlook could hit the stock anyway.
- NVIDIA trades at 12.9x forward earnings, its lowest in five years and barely a third of its five-year average.
NVIDIA (NVDA) goes into Tuesday’s report with plenty to make investors nervous. The stock has lost about a third of its value in six weeks, closing at $156.14 on Monday. NVIDIA said on Nov. 12 that founder Jensen Huang had resigned as CEO, leaving CFO Colette Kress as interim CEO while the board looks for a permanent replacement. Gene Munster has told investors to be prepared for NVIDIA to pull guidance.
Dan Niles, founder of Niles Investment Management, sees a cushion the market is missing. Replying to a follower on X, he noted that NVIDIA had repeated on Oct. 21 that end demand was running above 100%, while it guides to 70% growth because supply is the limit.
So, as he put it, NVIDIA “could have theoretically lost 30% of demand in the last ~4 weeks and still make that forecast.”
About $120 Billion of Breathing Room
The 70% comes from NVIDIA’s August earnings call. Kress guided revenue for the year ending January 2028 (mostly calendar 2027) up about 70%, called it supply-constrained, and said customers’ forecasts point to growth doubling. Analysts agree, with revenue climbing from $412 billion in the year ending January 2027 to $689 billion the year after, up 67%:
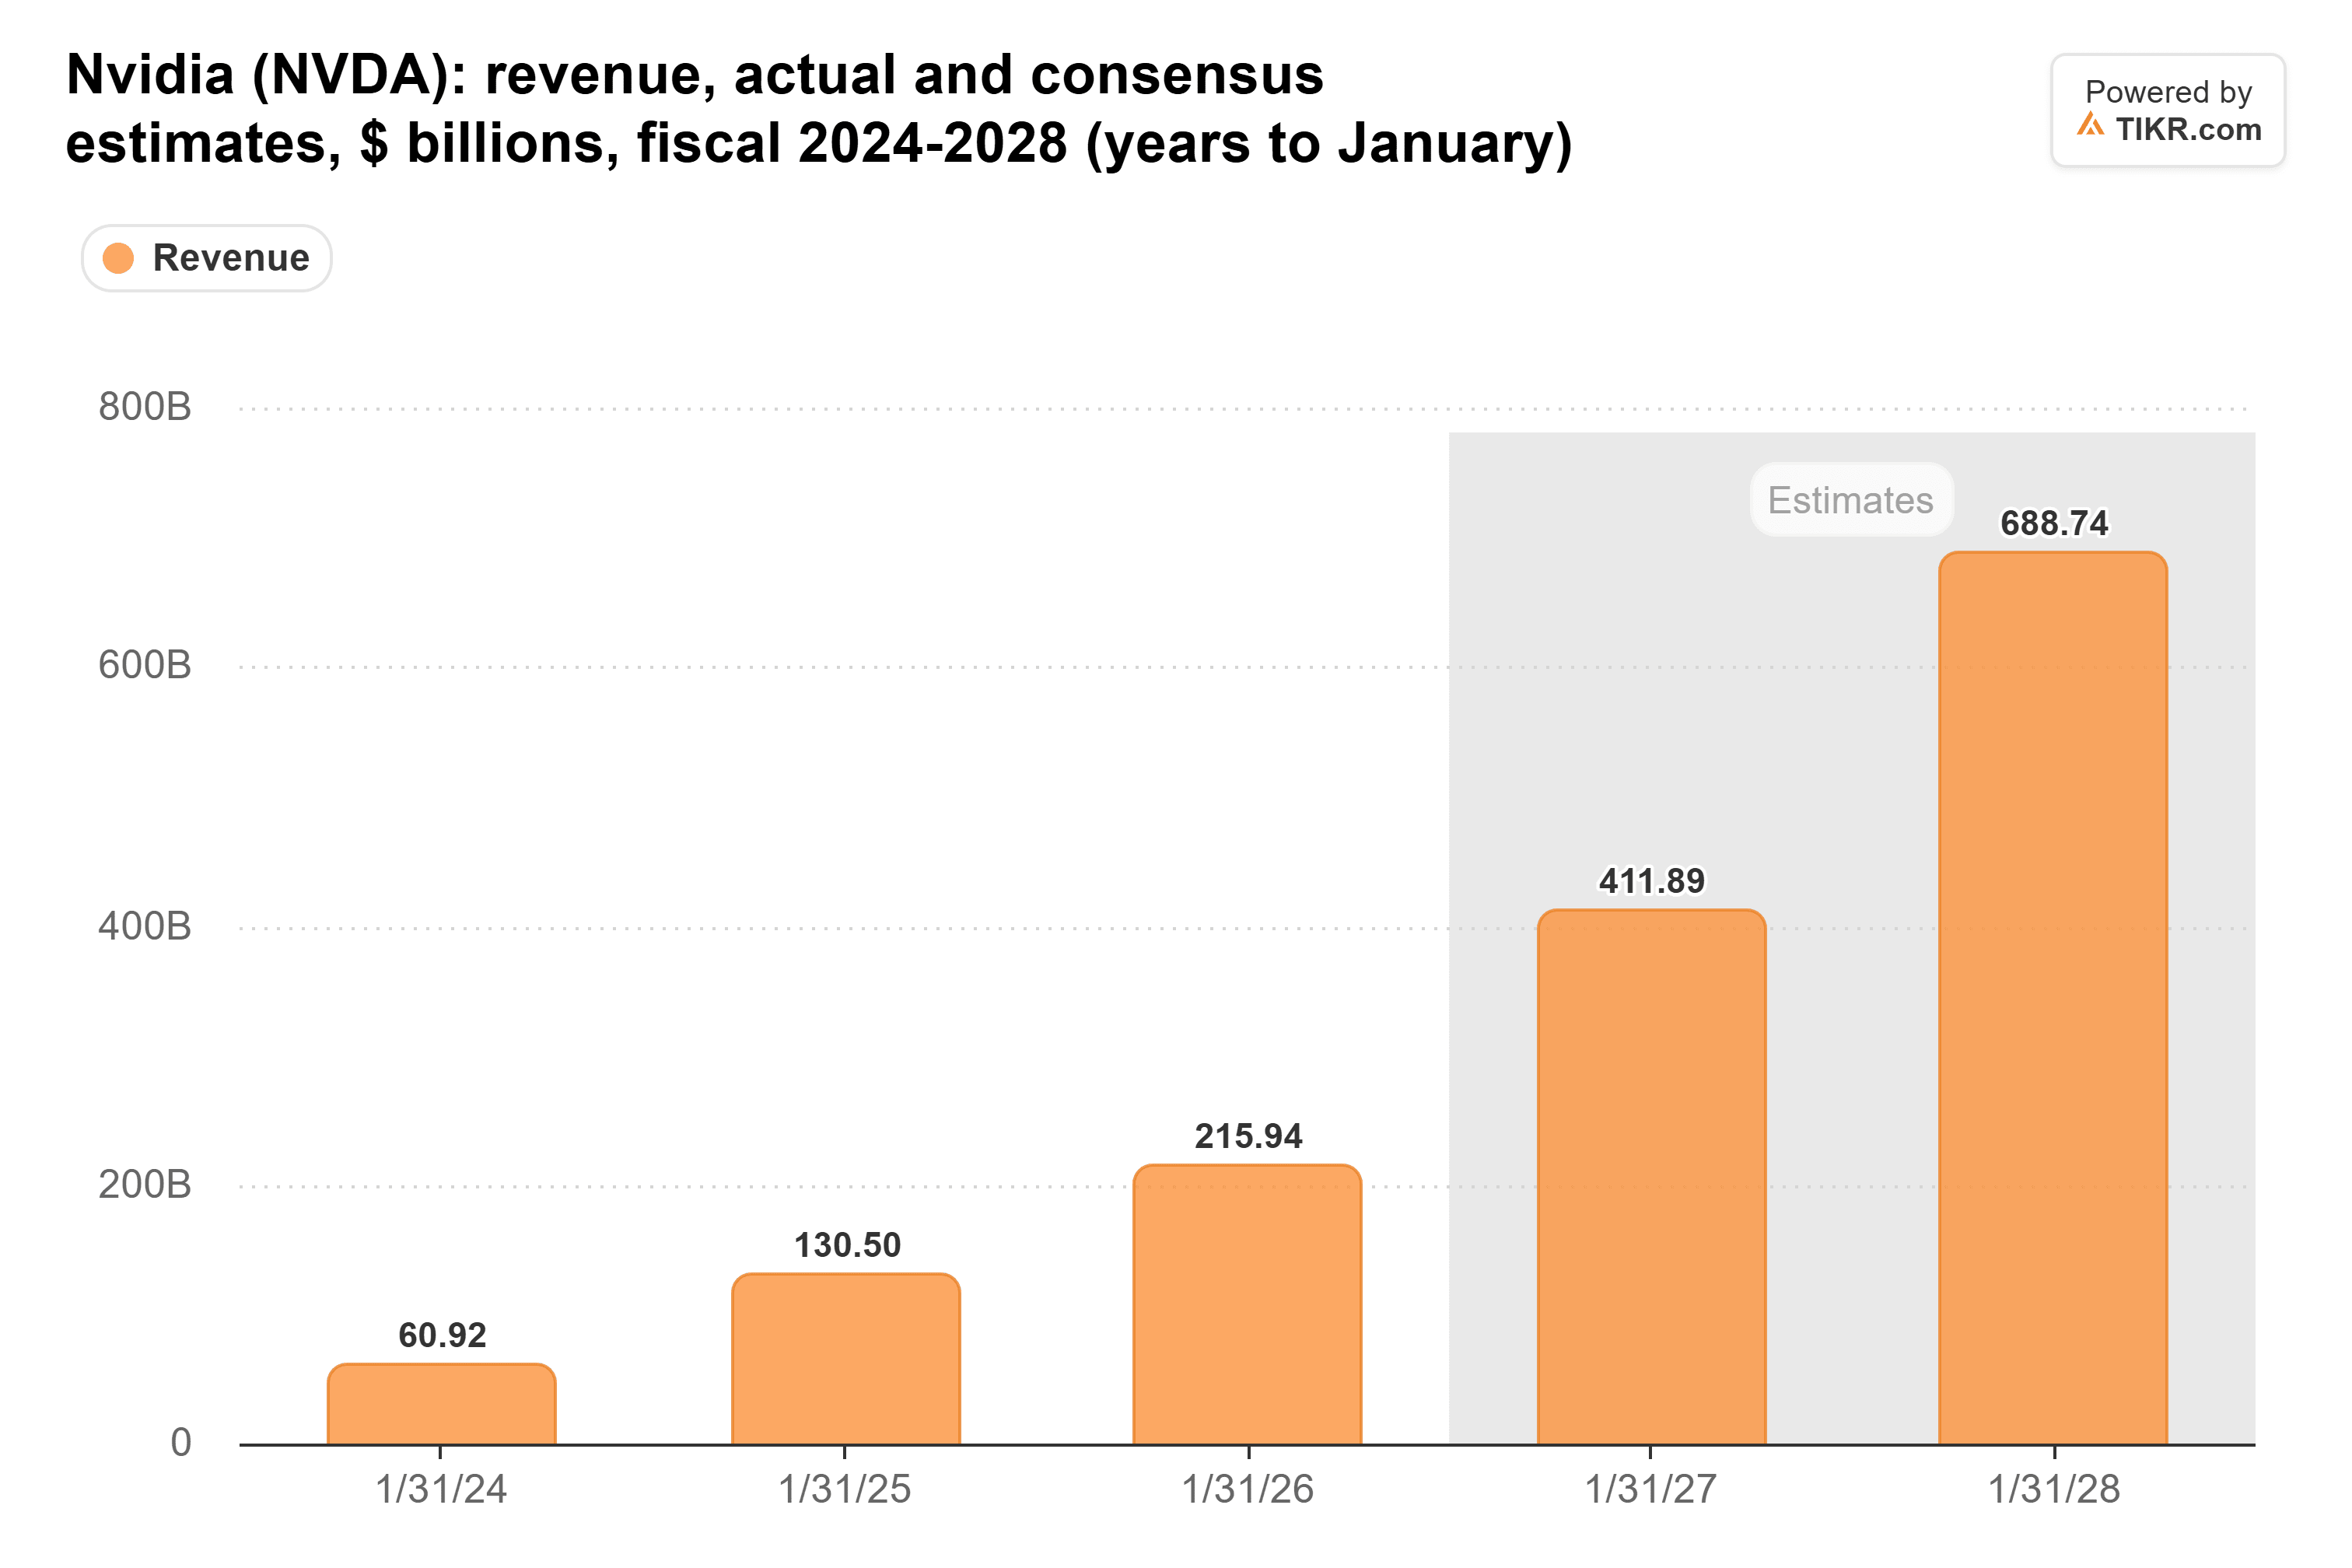
Strictly speaking, Niles’s 30% is 30 points of growth. Doubling $412 billion means about $820 billion of demand, against about $700 billion at 70% growth. The roughly $120 billion gap is about 15% of demand, and more than half of the $216 billion NVIDIA sold in the year ended January 2026.
Gross margin has held between 72% and 75% in every quarter but one for the past two years:
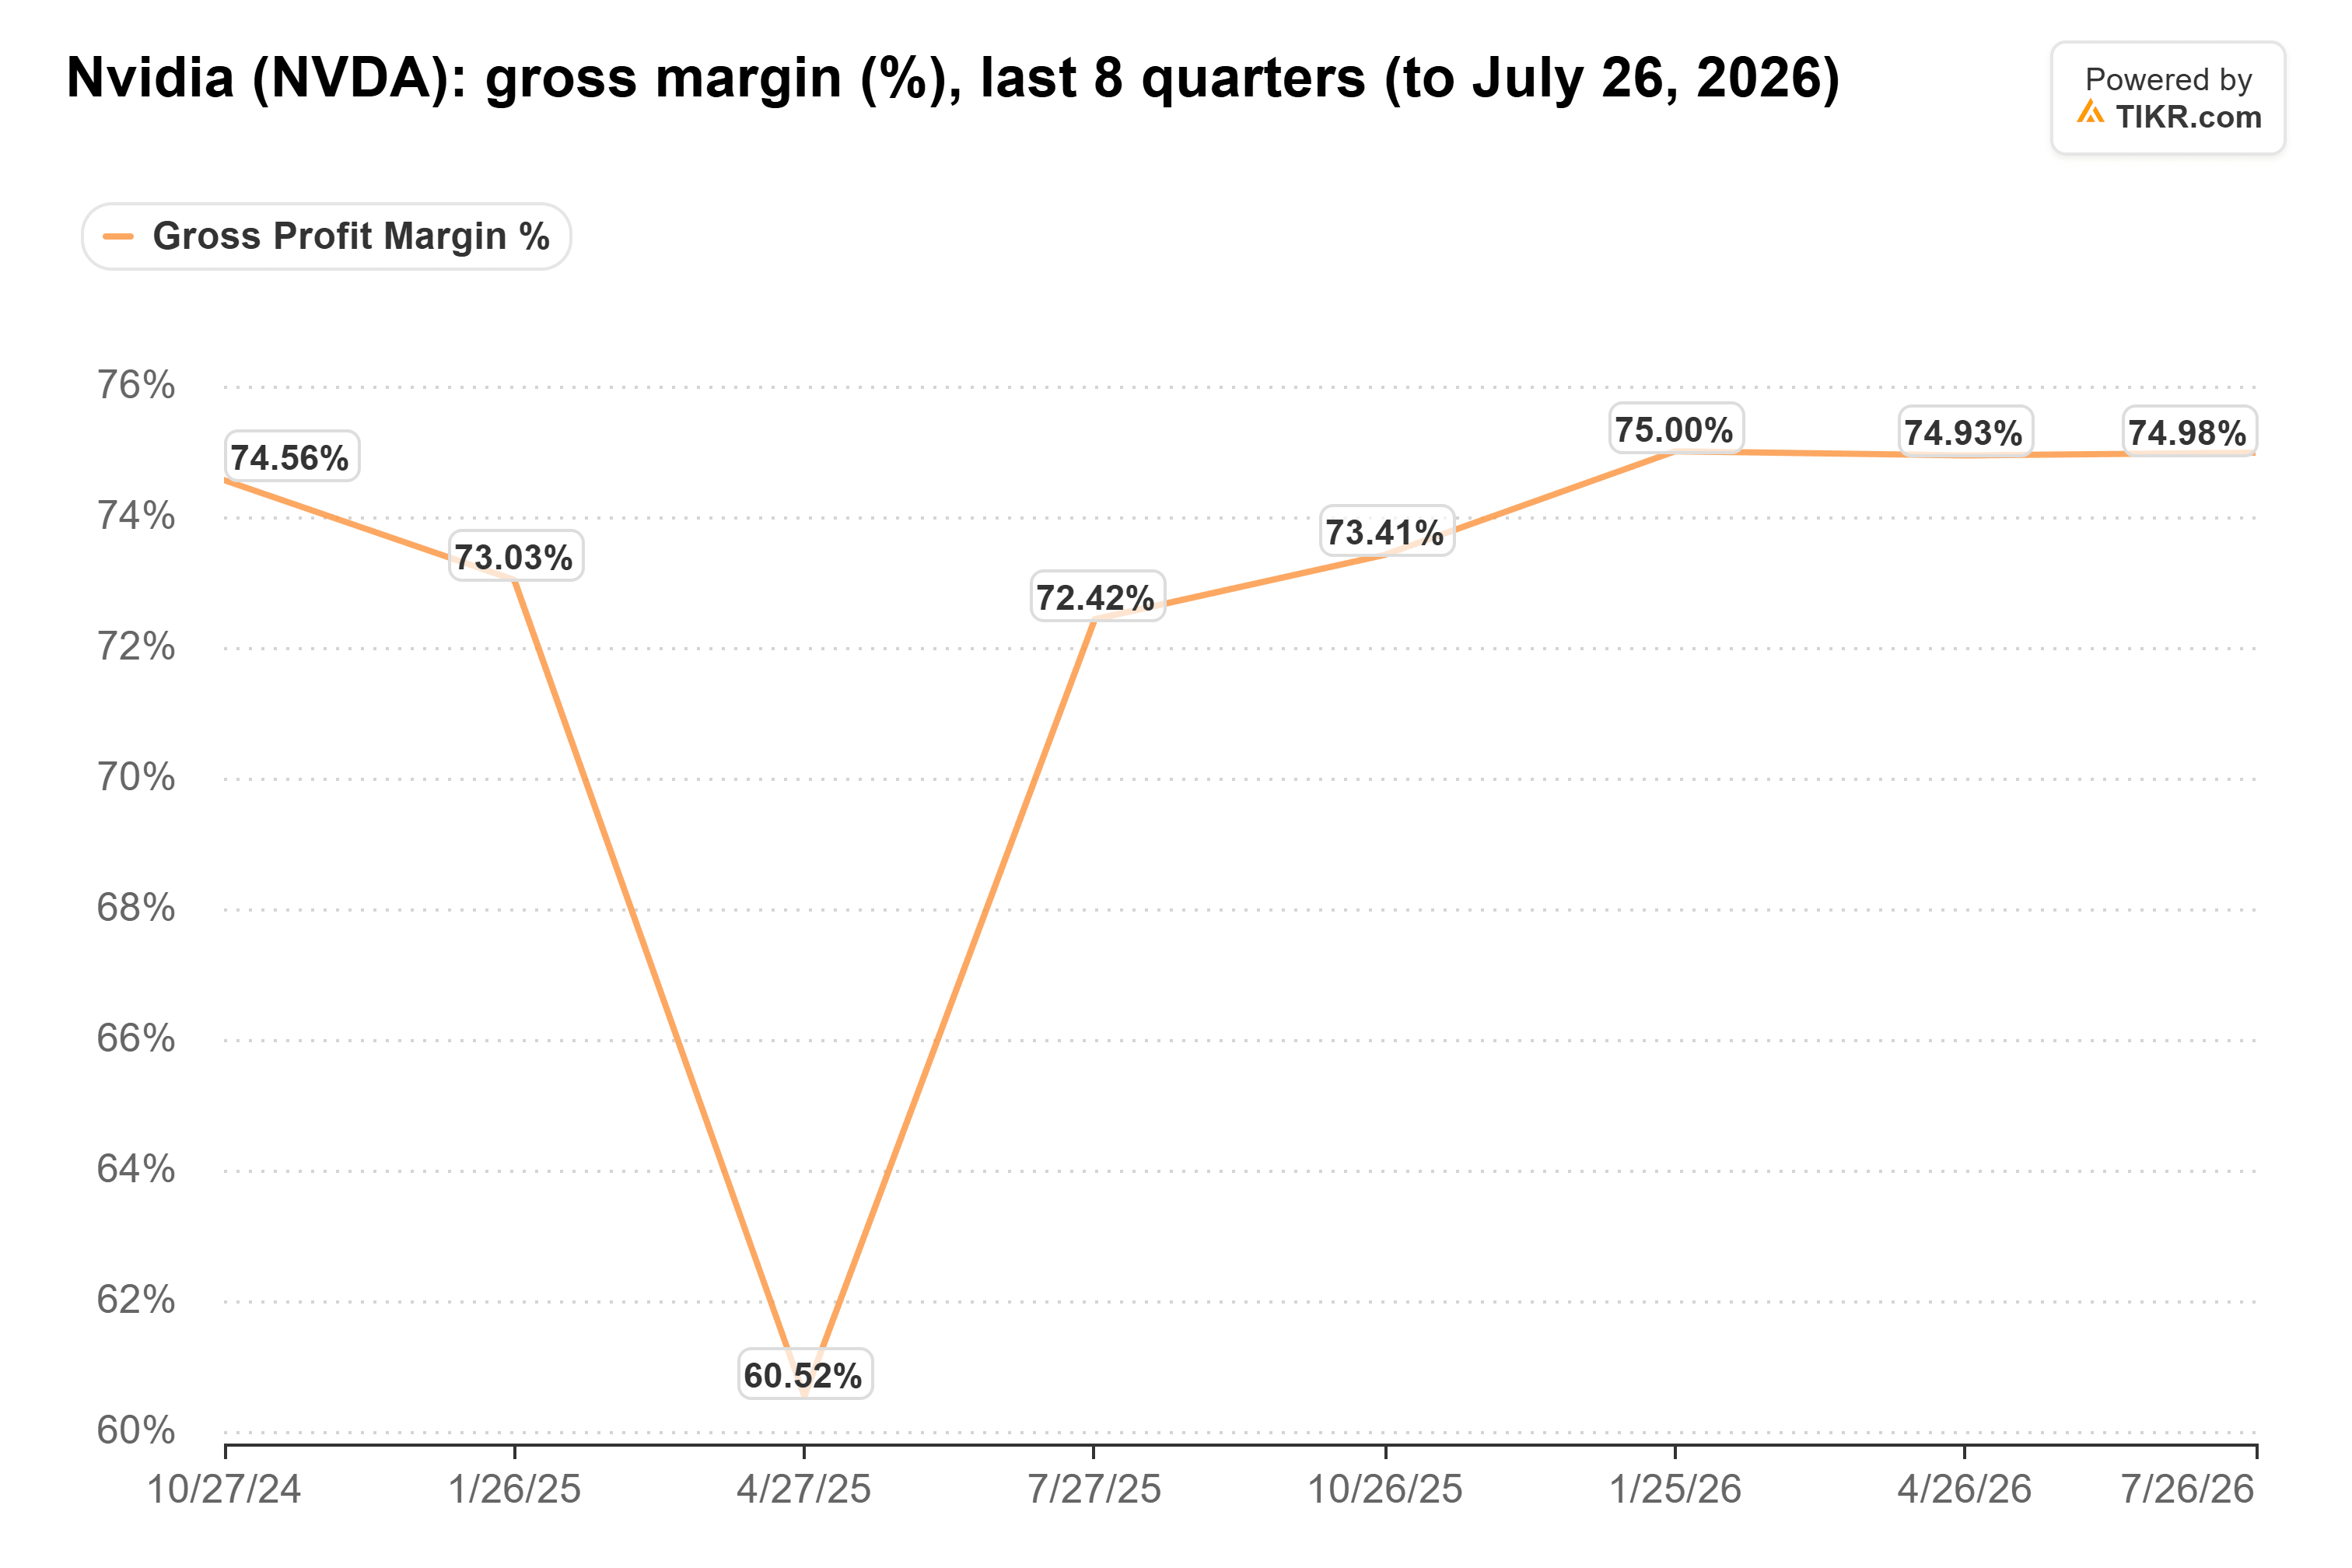
(The exception: the April 2025 quarter’s $4.5 billion H20 charge.)
TIKR Tracks 61 Analysts on Nvidia. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Next Year’s Estimates Are the Real Risk
Niles isn’t calling for clear skies. Asked why he valued NVIDIA on calendar 2026 numbers, he said he prefers actual revenue when uncertainty is high, then added: “Given some of the negative developments recently, especially the mid-term results, CY27 estimates likely have to come down for the AI capex as DC expansion slows.”
That’s the same year his cushion covers. It absorbs some lost demand, but a real building slowdown could push demand below what NVIDIA can ship. Costs are rising too: management expects gross margin to bottom at 71% to 72% in the January quarter as memory prices climb.
And Kress, now CEO and CFO at once, has little reason to stretch on Tuesday. A cautious number would hit the stock however strong demand looks.
At 12.9x, NVIDIA Stock Already Prices In Plenty
The forward P/E is at a five-year low:
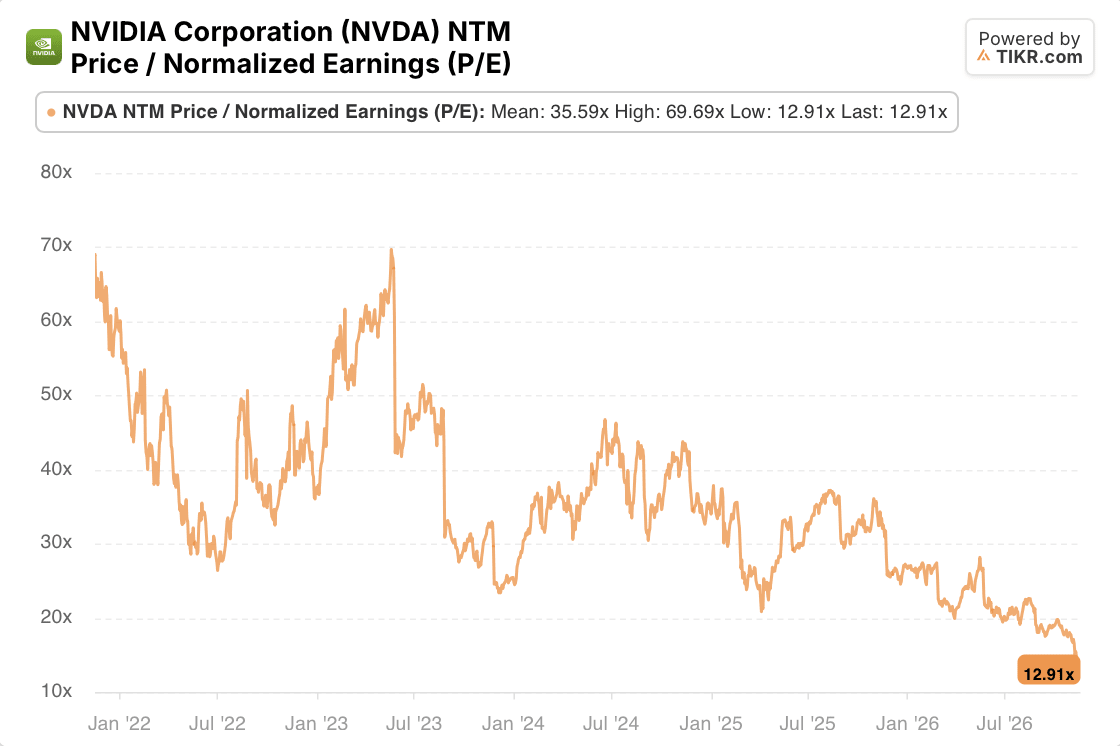
At 12.9x, it’s barely a third of its five-year average of 35.6x and a fraction of its high of nearly 70x in 2023.
Trimmed down, Niles’s math holds. If customers’ forecasts hold, demand could fall about $120 billion and still support the 70% outlook, so a demand-driven miss looks unlikely. A cautious guide would cut estimates, but at today’s price, even a 20% cut to forward earnings only lifts the multiple to about 16x. The line to listen for Tuesday is whether Kress still calls next year supply-constrained.
So What Is NVIDIA Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!