Key Takeaways
- Netflix shares fell 5.3% after Q3 results and closed Friday at $62, near a 52-week low, after the company cut its 2026 ad revenue target to $2.7 billion.
- Q3 EPS of $0.87 beat estimates and operating margin hit 34.6%, but revenue grew 11.8%, its slowest pace in nearly three years.
- Fourth-quarter EPS guidance of $0.67 missed the $0.73 consensus, and YouTube’s roughly $11 billion of quarterly ad revenue dwarfs Netflix’s full-year ad target.
- The January 19 report will show whether new content chief Peter Rice and the 2027 ad tier expansion can lift engagement.
Netflix (NFLX) delivered a clean profit beat in the third quarter. Then it trimmed the one number investors most wanted to see rising.
The streamer cut its 2026 advertising revenue target to about $2.7 billion from roughly $3 billion, and shares fell 5.3% after the report. By Friday’s close they sat at $62, barely above the 52-week low and 47% below the high.
That ad target looks even smaller next to Alphabet (GOOGL). YouTube brings in around $11 billion of ad revenue every quarter, and it fights Netflix for the same TV screens and the same brand budgets.
Co-CEO Greg Peters didn’t dress it up. “We are currently a bit behind our aggressive target for the year,” he told analysts.
The beat came with fine print
Revenue rose 11.8% to $12.87 billion, in line with estimates and the slowest growth in nearly three years. Profit did the heavy lifting:
- EPS of $0.87 beat the $0.82 consensus and rose 49% from a year ago.
- Operating income jumped 37% to $4.46 billion, a 34.6% margin versus 28.2% last year.
- Netflix spent $4.8 billion repurchasing 63.9 million shares, its biggest quarterly buyback ever.
Some of that margin came from the timing of expenses, though, so the quarter flatters the run rate.
The top line tells the slower story…

Growth has slowed from 17% a year ago, and the fourth-quarter guide of $13.44 billion implies roughly 11.5% again.
Ads were supposed to fill the gap
Advertising was meant to be Netflix’s second engine. Ad revenue should still grow more than 80% this year, yet the company now expects to land $300 million short of plan because some ad features rolled out slower than expected.
The bigger problem is attention. Gabelli Funds portfolio manager John Belton told the AP that investors are worried about “soft engagement trends” and slowing growth.
Netflix is responding with a reset. It cut about 1,000 jobs, roughly 6% of staff, and named former Disney and Fox executive Peter Rice content chief after Bela Bajaria and film chief Dan Lin left. Co-CEO Ted Sarandos said Netflix sees “an opportunity to take our slate to the next level.”
The ad tier also expands to 15 more countries in 2027, starting in March. But analysts already expect growth to keep cooling.
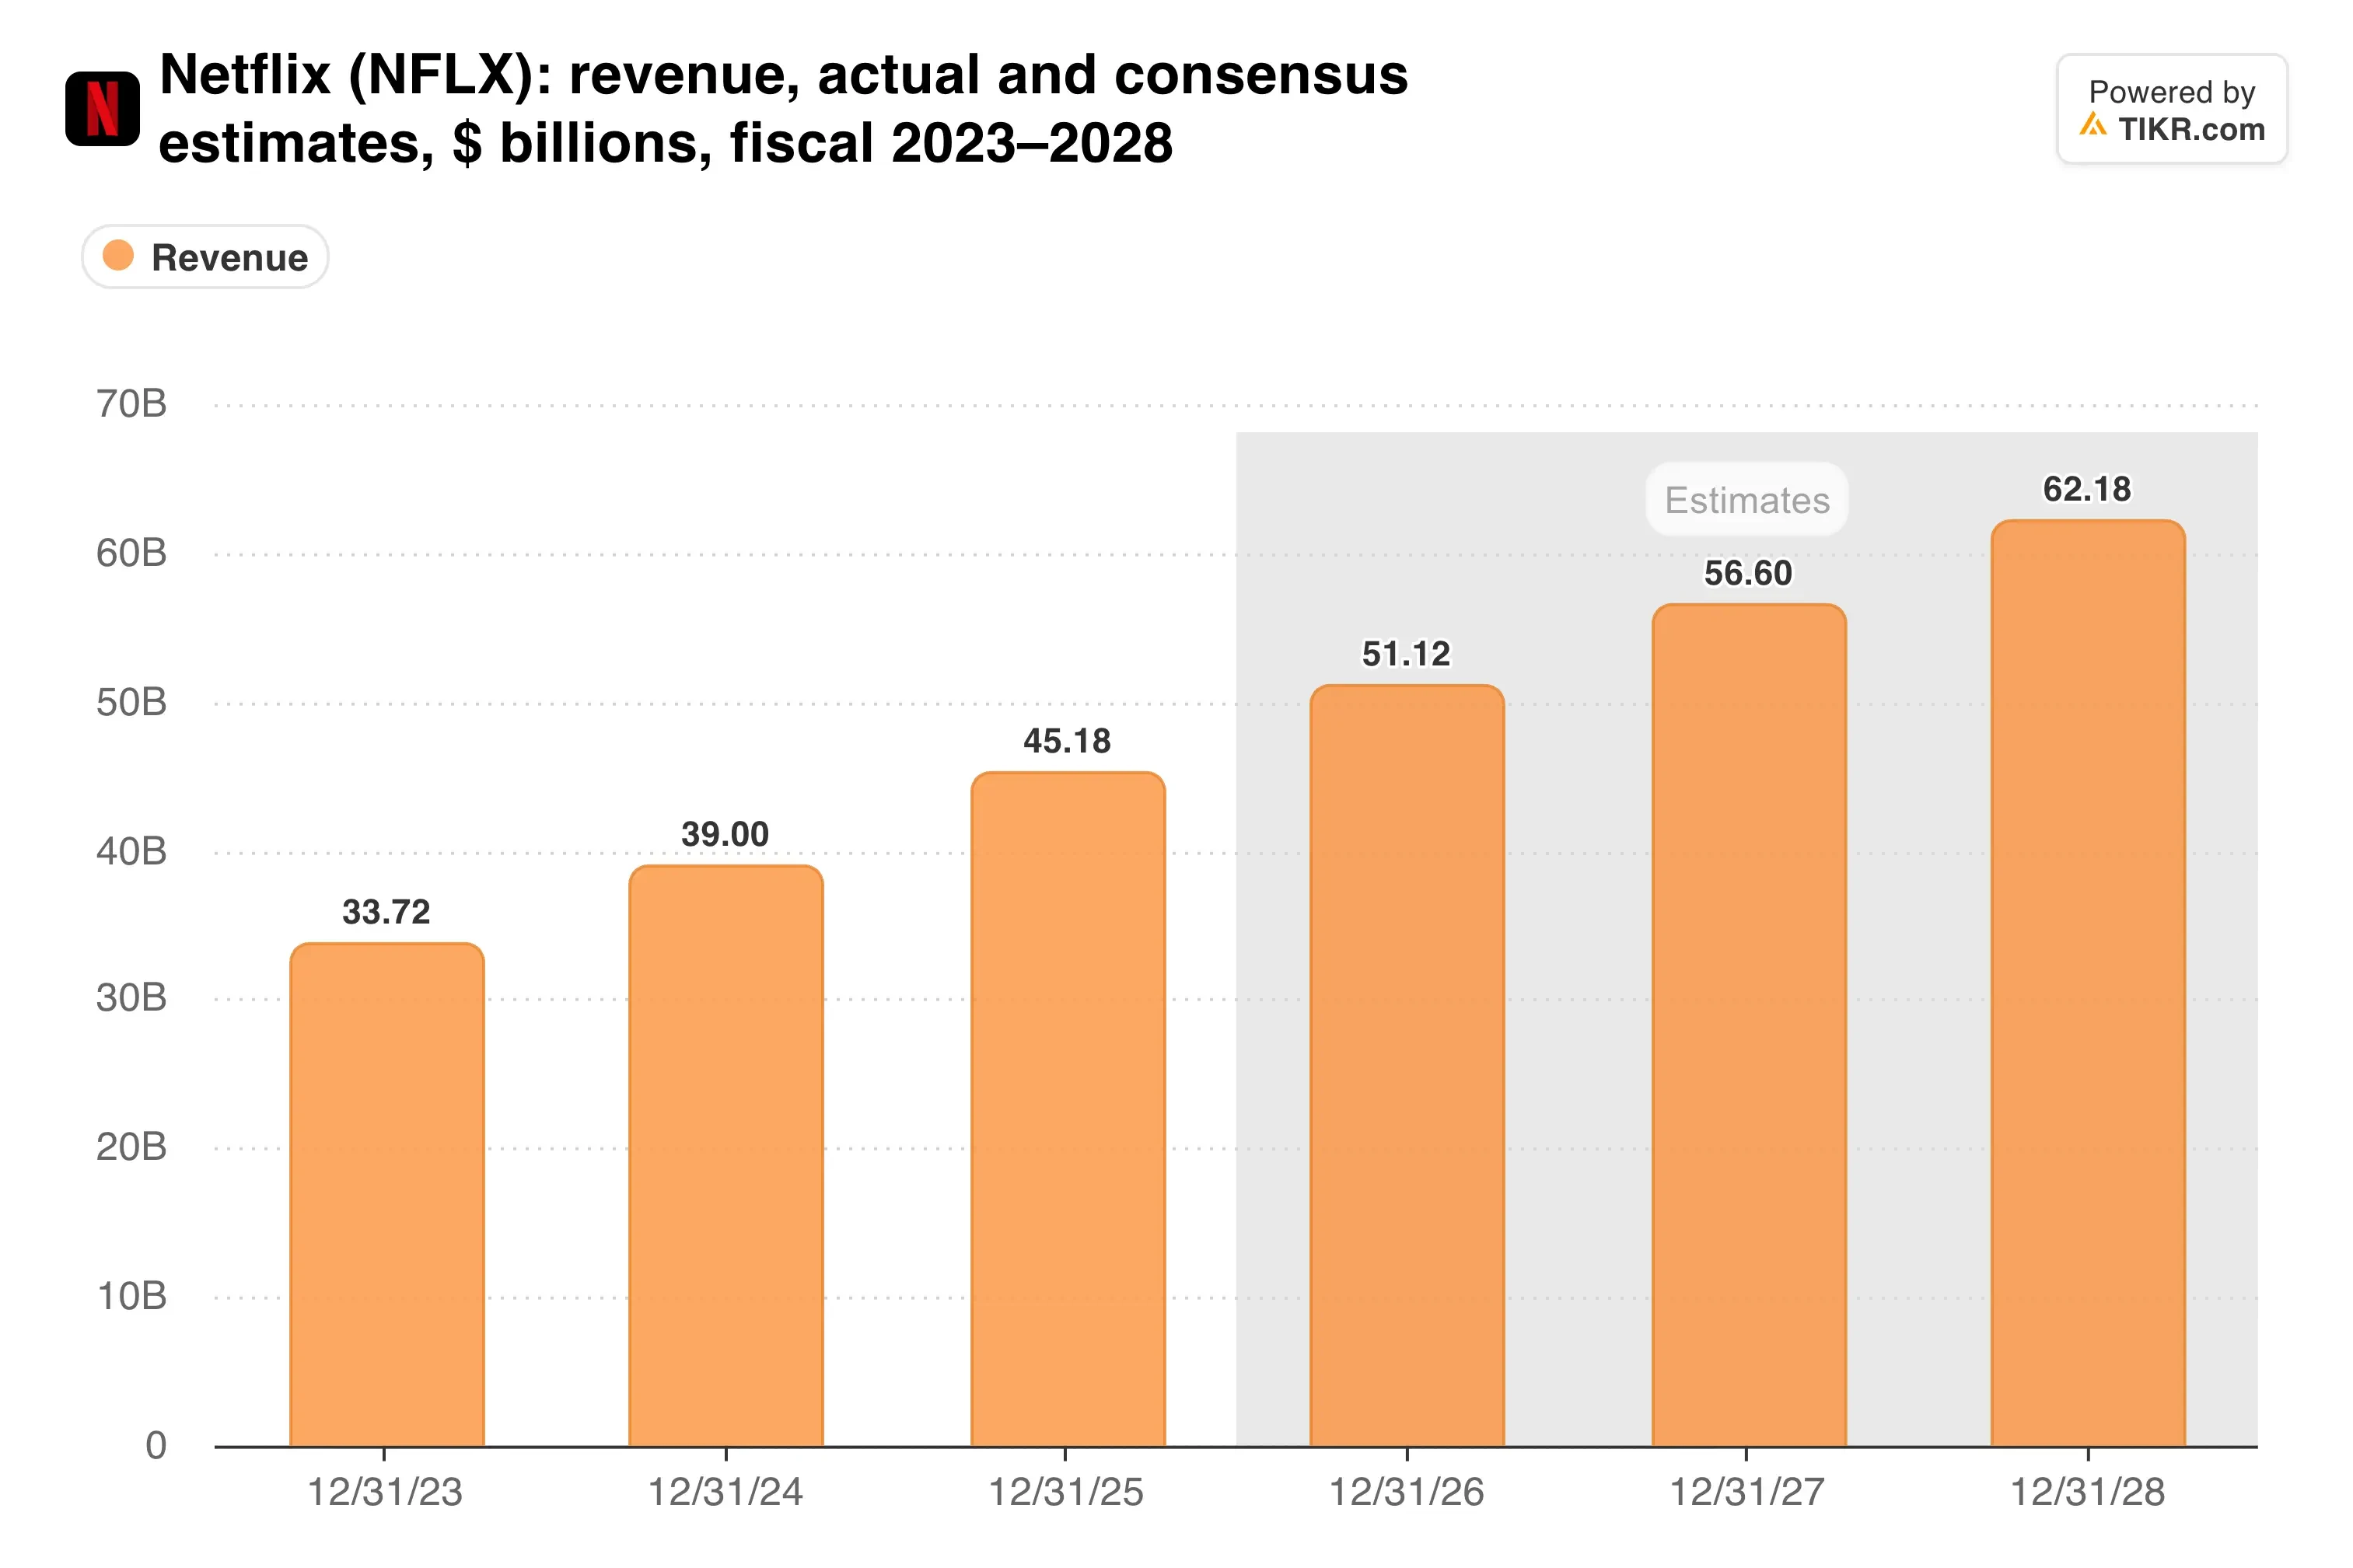
Consensus calls for about 12% annual revenue growth over the next two years, so the ad rebuild has to work just to hold that pace.
TIKR tracks 52 analysts on Netflix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
Priced like a slower Netflix
The fourth-quarter guide disappointed too. Netflix forecast EPS of $0.67 and net income of $2.79 billion, below the $0.73 and $3.07 billion analysts expected. Job cuts will shave about 120 basis points off a 26% operating margin.
Full-year revenue now lands at $51.1 billion, the bottom of the prior range, with a 31.5% operating margin. Free cash flow guidance also dropped to $12 billion from $12.5 billion because of a real estate transaction. That comes after Netflix collected a $2.8 billion breakup fee in February when Paramount won Warner Bros. Discovery.
The stock has already absorbed a lot of this. Here’s how far the multiple has fallen:

At 17.3x forward earnings, Netflix now trades like a mature media company. The Street’s $85 average target implies about 37% upside.
My take: The valuation already assumes growth keeps slowing, and the buyback, with $22.3 billion of authorization left, gives the stock real support. Still, a full year of Netflix ad revenue equals about three weeks of YouTube’s, so ads can’t carry the story yet. I’d want proof that engagement is turning before buying aggressively.
The next checkpoint is the January 19 report. It will show Rice’s first full quarter in charge, the year-end ad number, and 2027 guidance that tells us whether 12% growth is a floor or a ceiling.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!