Key Takeaways
- Moderna stock is up 750% in 2026, mostly on its melanoma vaccine with Merck, which succeeded in Phase 3.
- Third-quarter revenue rose 29% on COVID deals abroad, while Pfizer’s rival shot sold less.
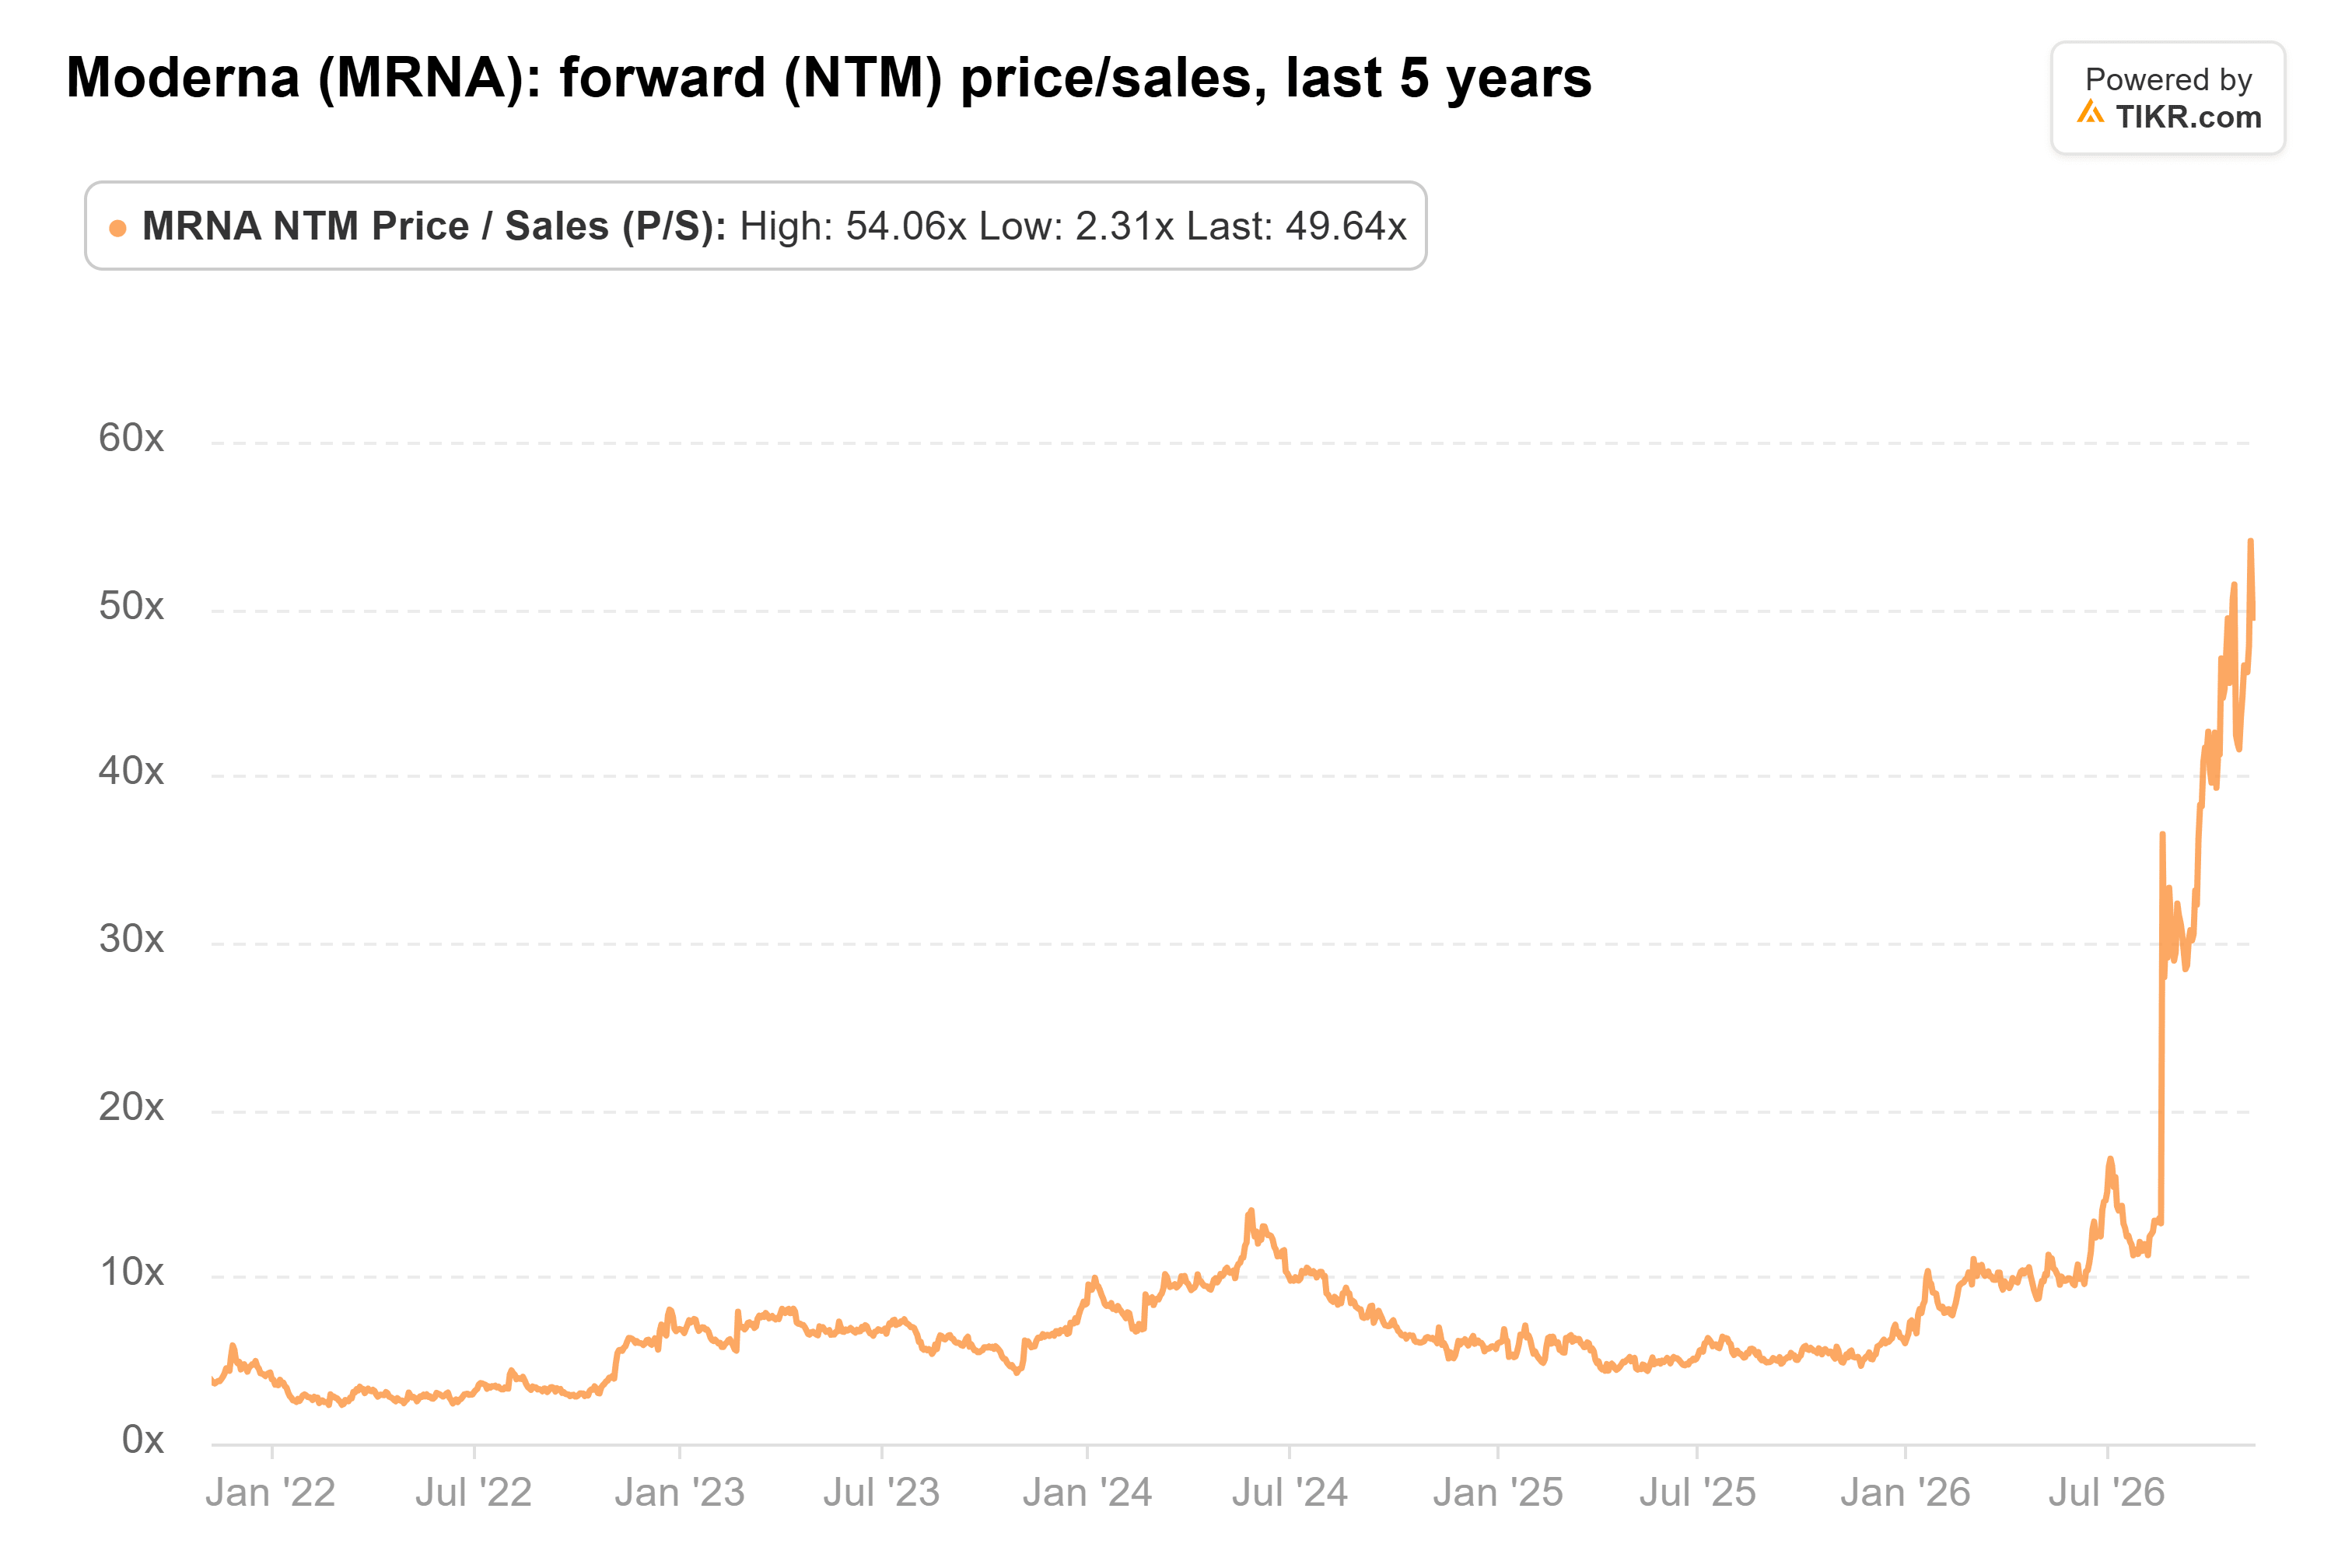
- Moderna trades far above its usual forward sales multiple, so investors are already paying for a launch the FDA hasn’t approved.
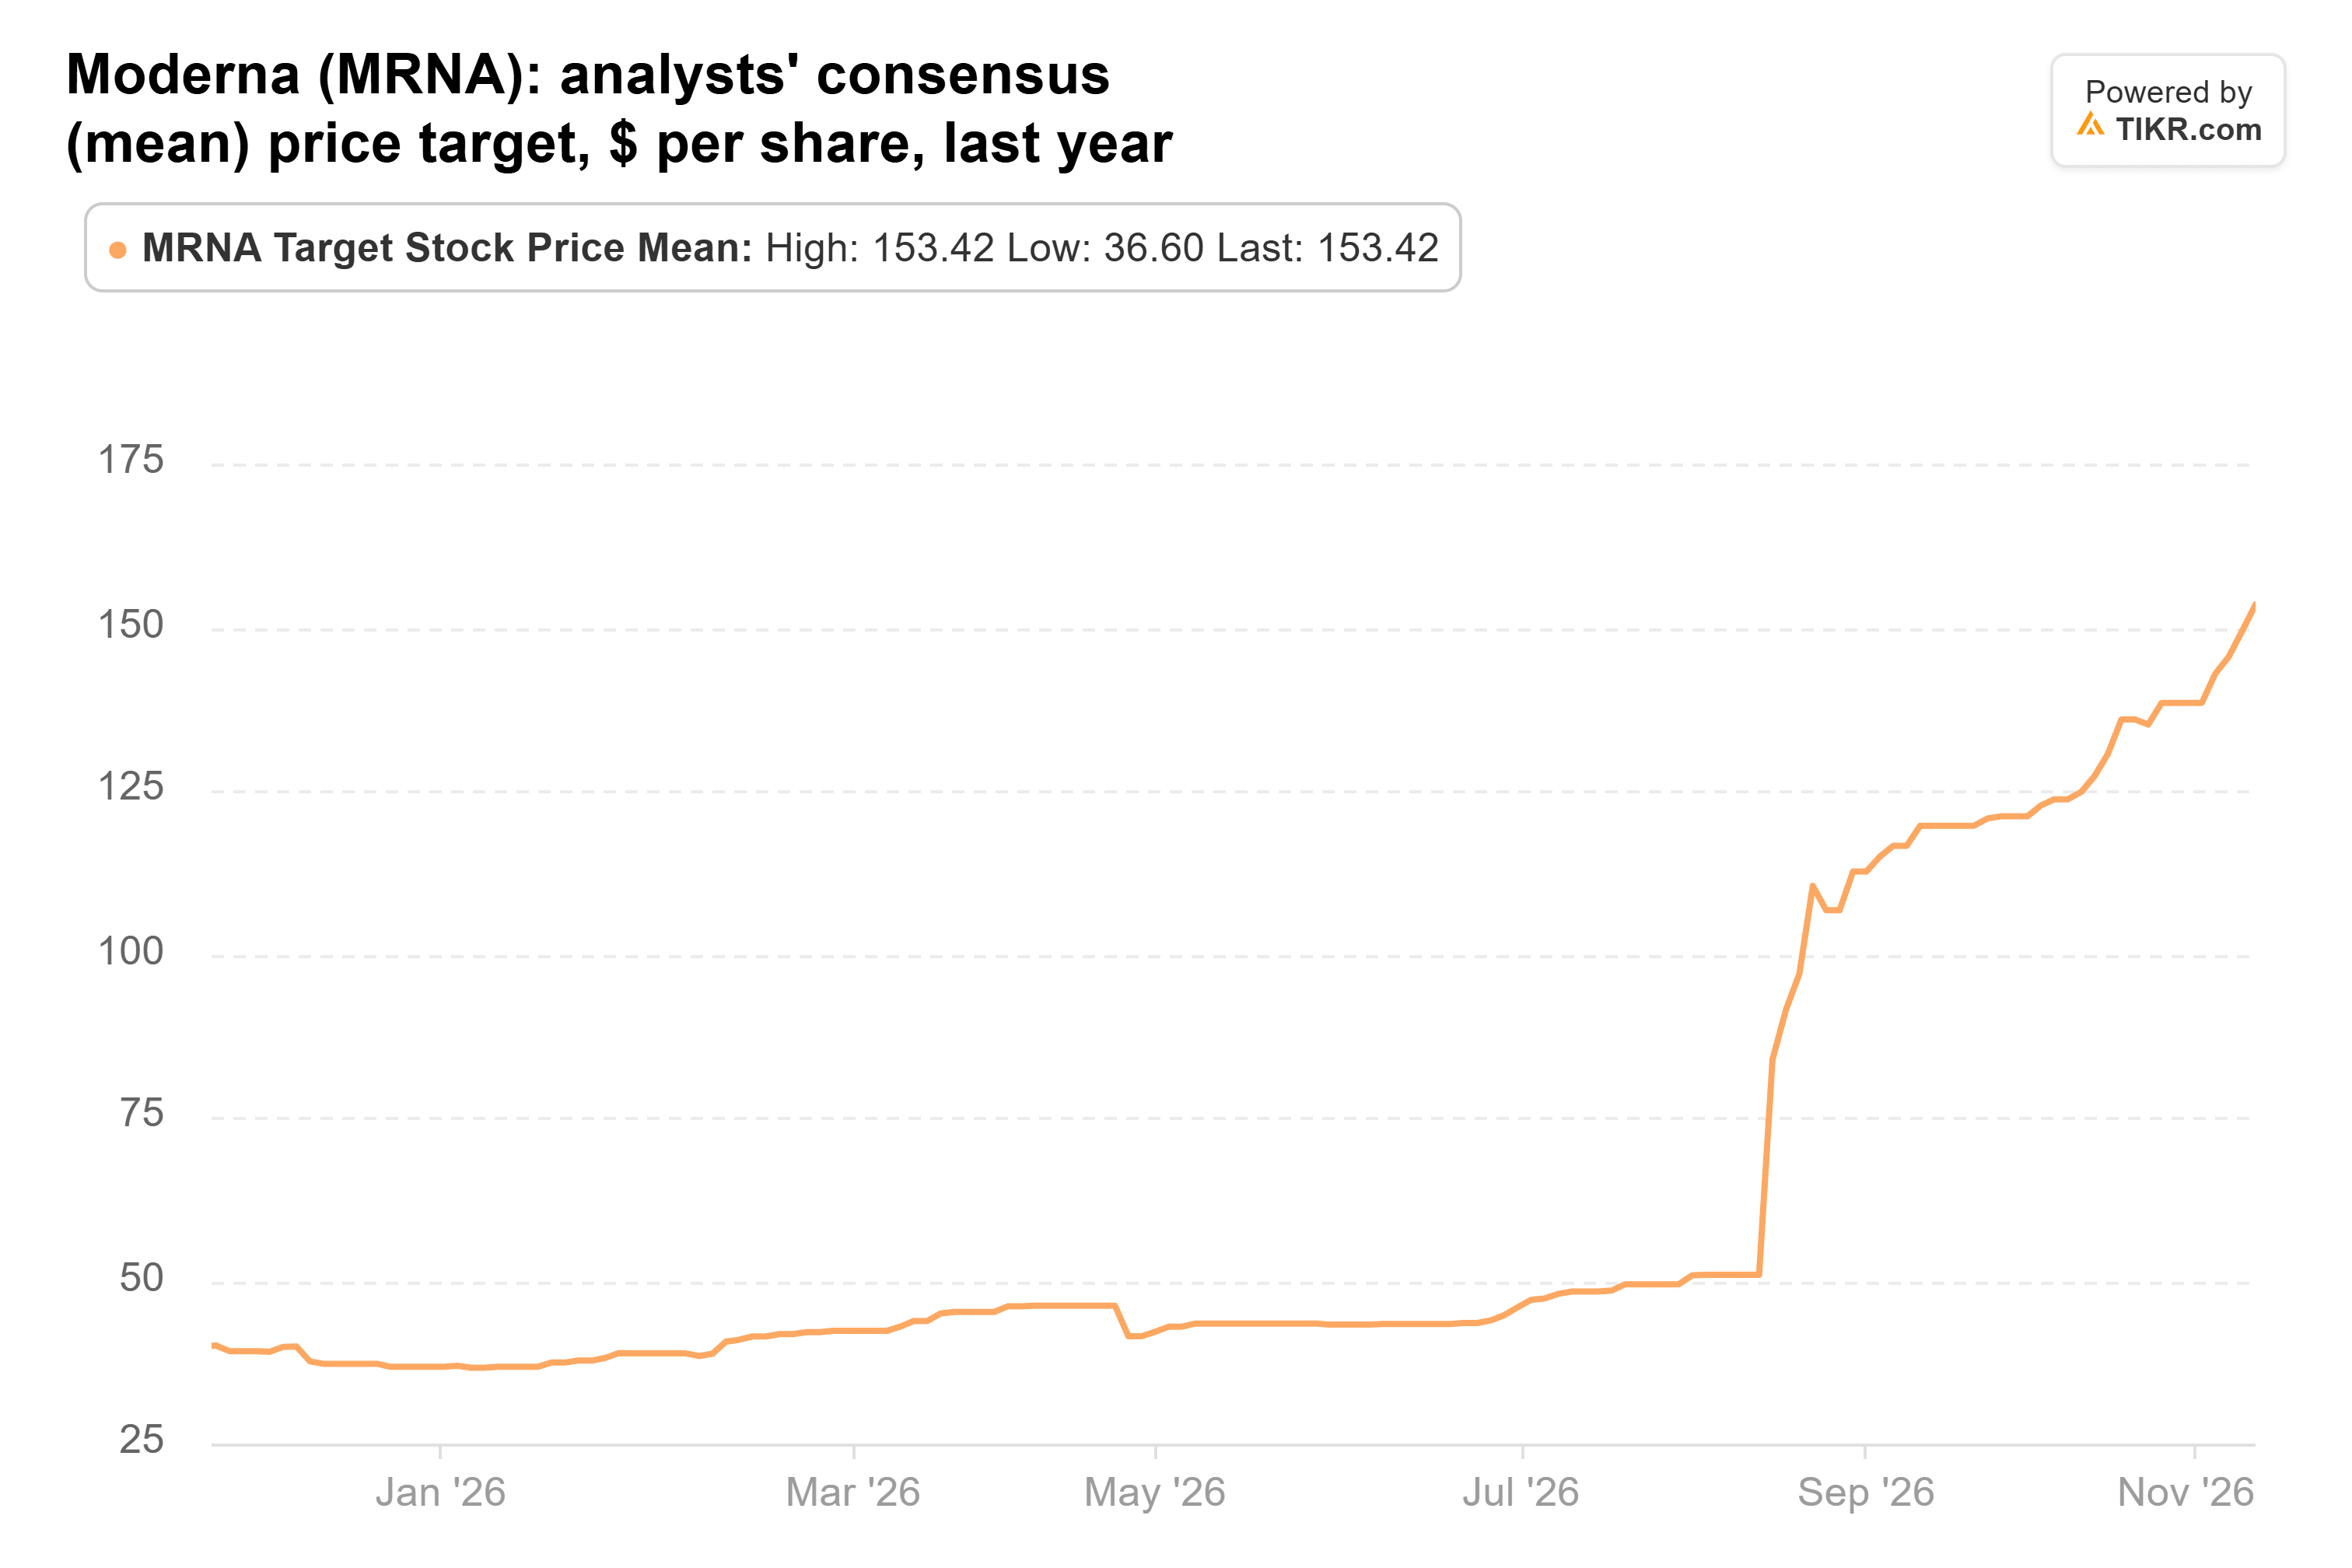
- With the Street’s average target well below the stock, I’d take some profits.
Moderna (MRNA) is up 750% in 2026, mostly on intismeran, its personalized melanoma vaccine with Merck (MRK). And CEO Stéphane Bancel thinks melanoma is just the start: “We believe that it’s going to work in more cancers than melanoma because of a mechanism of action,” he said on Bloomberg Talks on Oct. 26.
Meanwhile, Moderna’s COVID business grew again last quarter, as Pfizer (PFE) sold less of its rival shot.
The Phase 3 win is real
On Aug. 19, the partners said intismeran’s Phase 3 trial with Merck’s Keytruda met its main goals. Moderna stock nearly tripled that day. The full results in October showed a 42% cut in the risk of recurrence or death against Keytruda alone. That came in below the Phase 2b’s 49%. But the benefit came after the six-month vaccine regimen: no difference over those first months, then a 58% cut, in a pre-specified analysis. Overall-survival data is still to come, and a launch could follow in 2027.
Merck, up 41% this year, splits the vaccine’s costs and profits evenly with Moderna. That’s a side bet for Merck, whose Keytruda sold $8.6 billion in the third quarter alone. For Moderna, however, it’s most of what investors are paying for.
TIKR tracks 23 analysts on Moderna. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Moderna, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Moderna’s Analyst Ratings
COVID sales are growing again
Third-quarter revenue rose 29% to $1.31 billion on COVID deals with the UK, Canada and Australia. Moderna also swung to a $162 million profit. Pfizer’s Comirnaty sales fell 29% operationally, and its stock is up just 18% this year. Moderna raised its 2026 growth outlook to 15% to 25%. It also expects $8.1 billion to $8.3 billion of cash and investments at year-end, including a $2.6 billion convertible note sale.
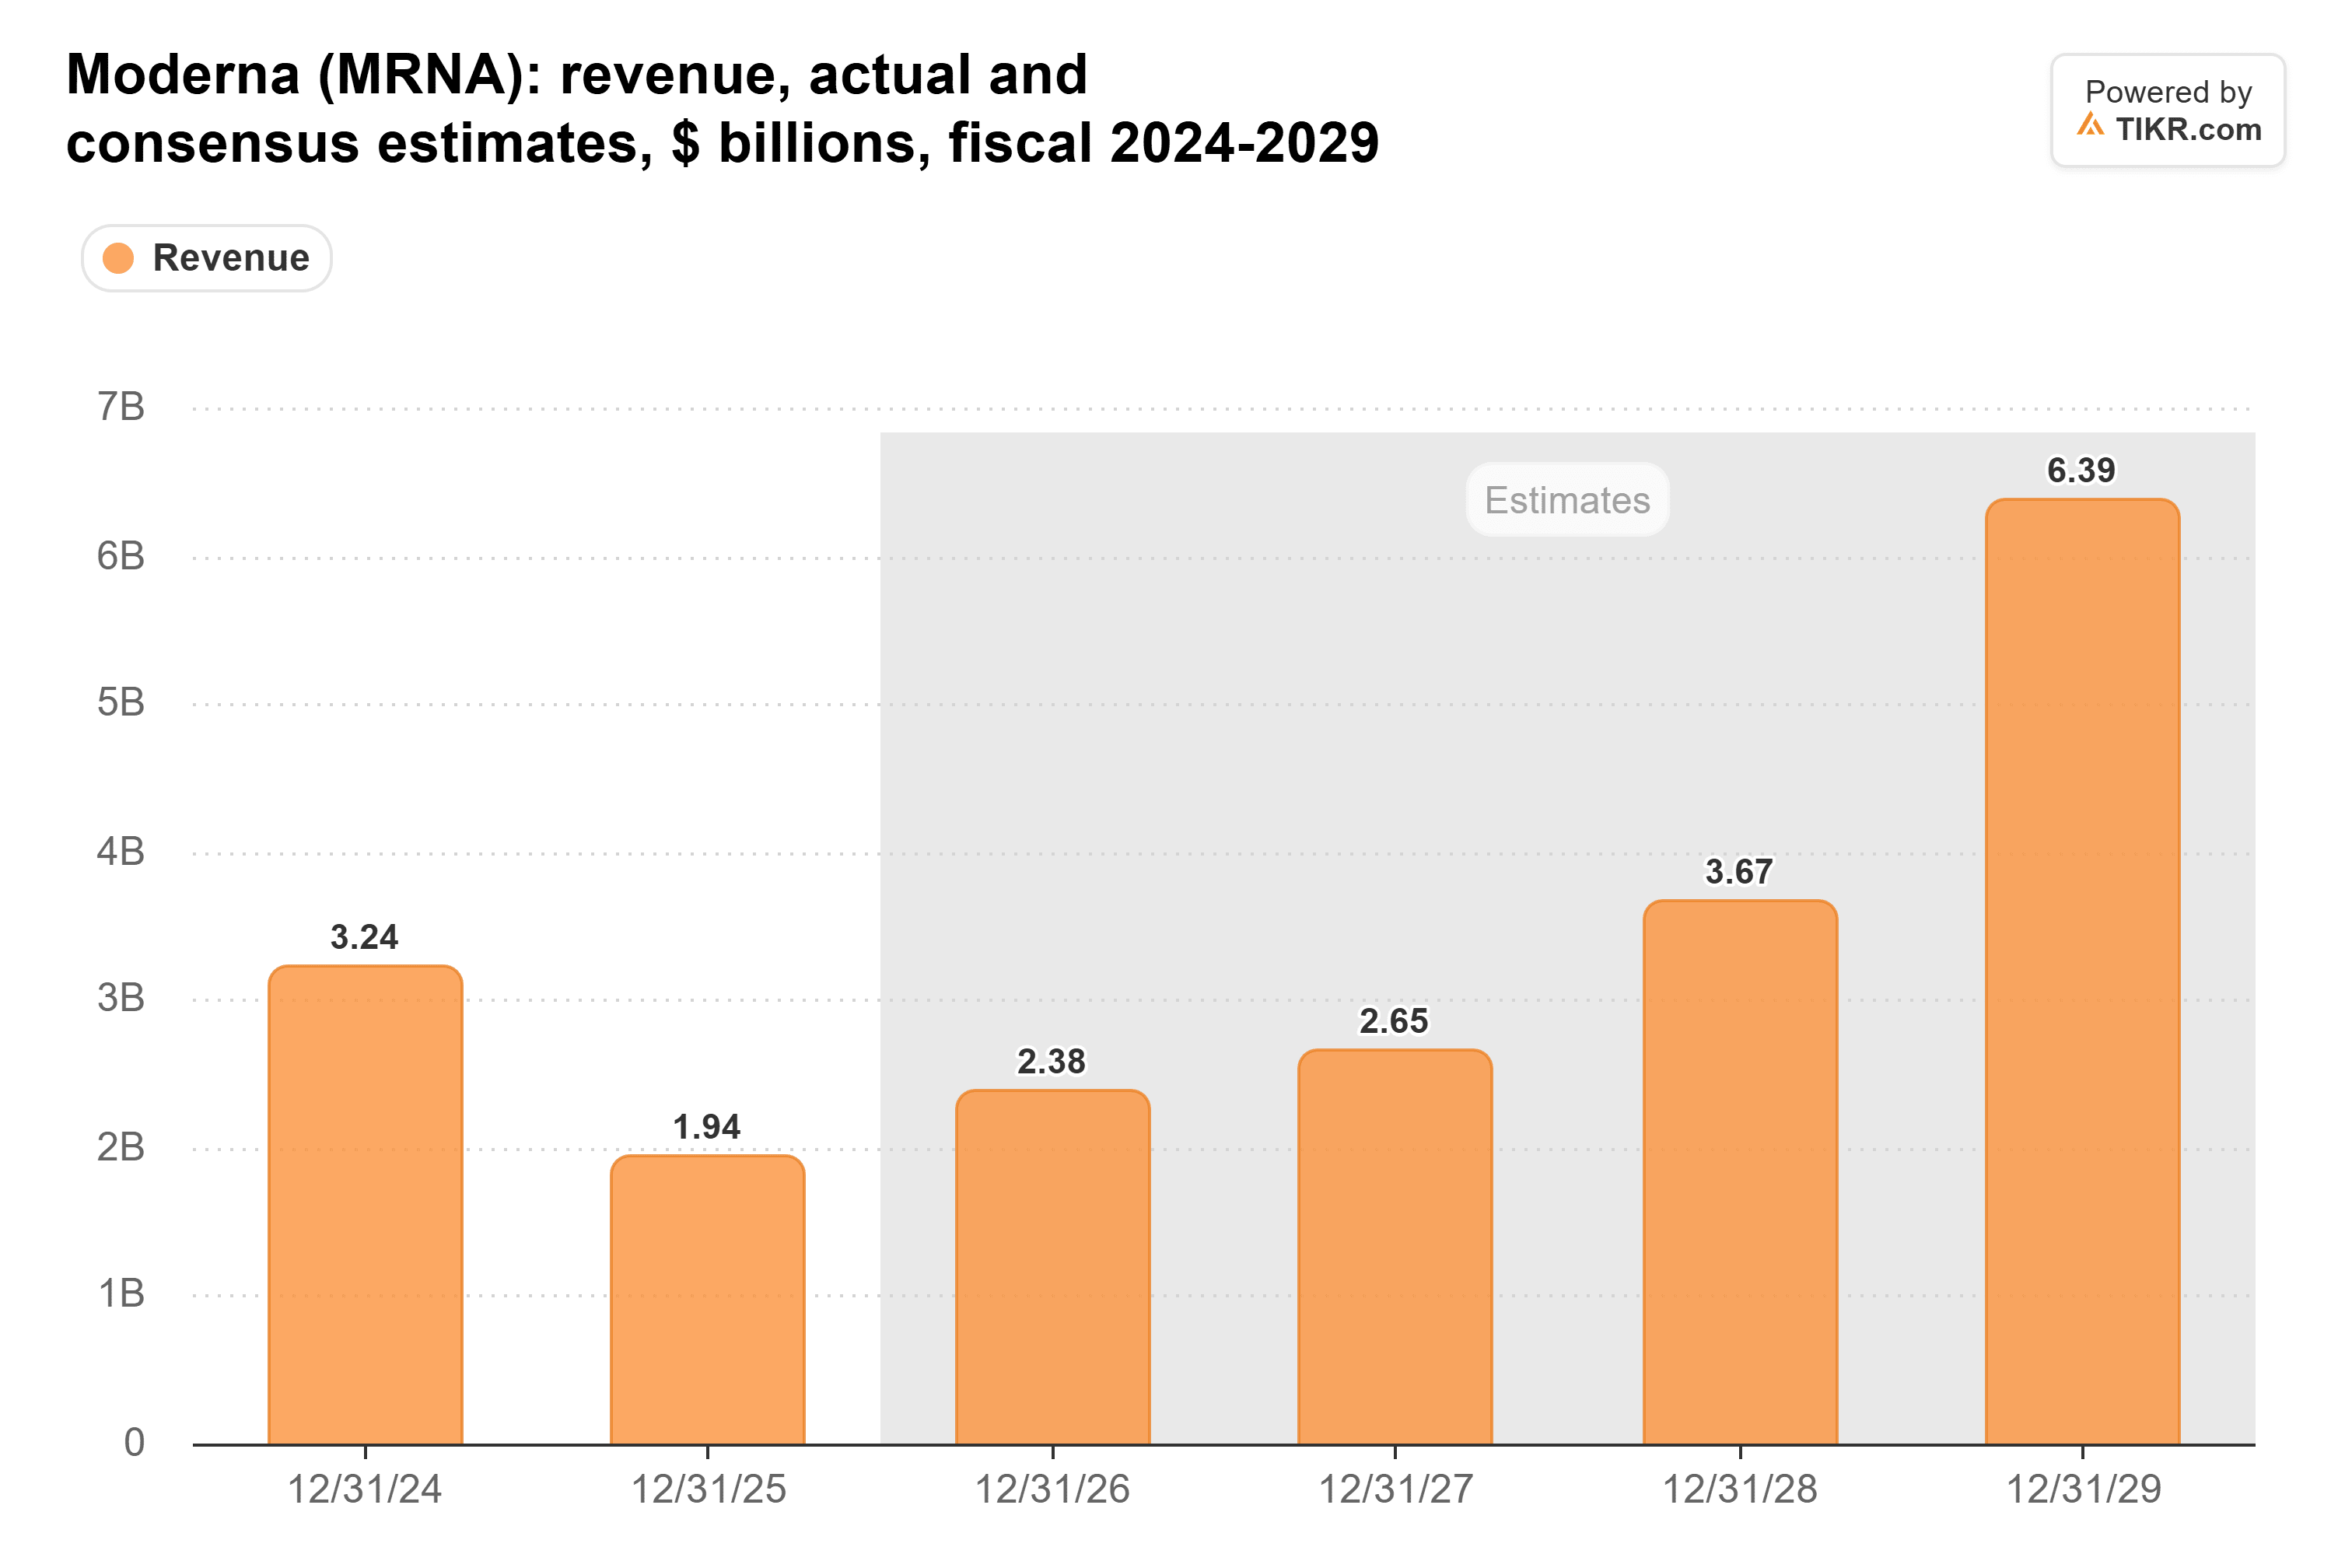
Still, analysts see revenue reaching only $3.67 billion by 2028, about half of 2023’s $6.85 billion:
Priced for a blockbuster already
Moderna trades at more than 45x forward sales, against an 8.1x five-year average:
And analysts’ average target, at $153, sits well below the stock:
The bull case is that intismeran works in other cancers too, with kidney, bladder and lung cancer trials underway. Moderna’s myeloma therapy mRNA-2808 also gets an oral slot at ASH in December. But at more than 45x sales for a drug the FDA hasn’t approved, I’d take some profits here. Of course, strong kidney cancer or overall-survival data would change that math. Early next year’s COVID contracts will also show whether this quarter’s growth can repeat.
So what is Moderna stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Moderna could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!