


Key Takeaways
- Moderna fell 12% in the week to Nov. 13 after guiding to about $4 billion or more of cash costs a year through 2030, mostly for cancer drugs.
- Most of the money goes to oncology, led by intismeran, its melanoma vaccine with Merck, while rival BioNTech’s revenue is shrinking.
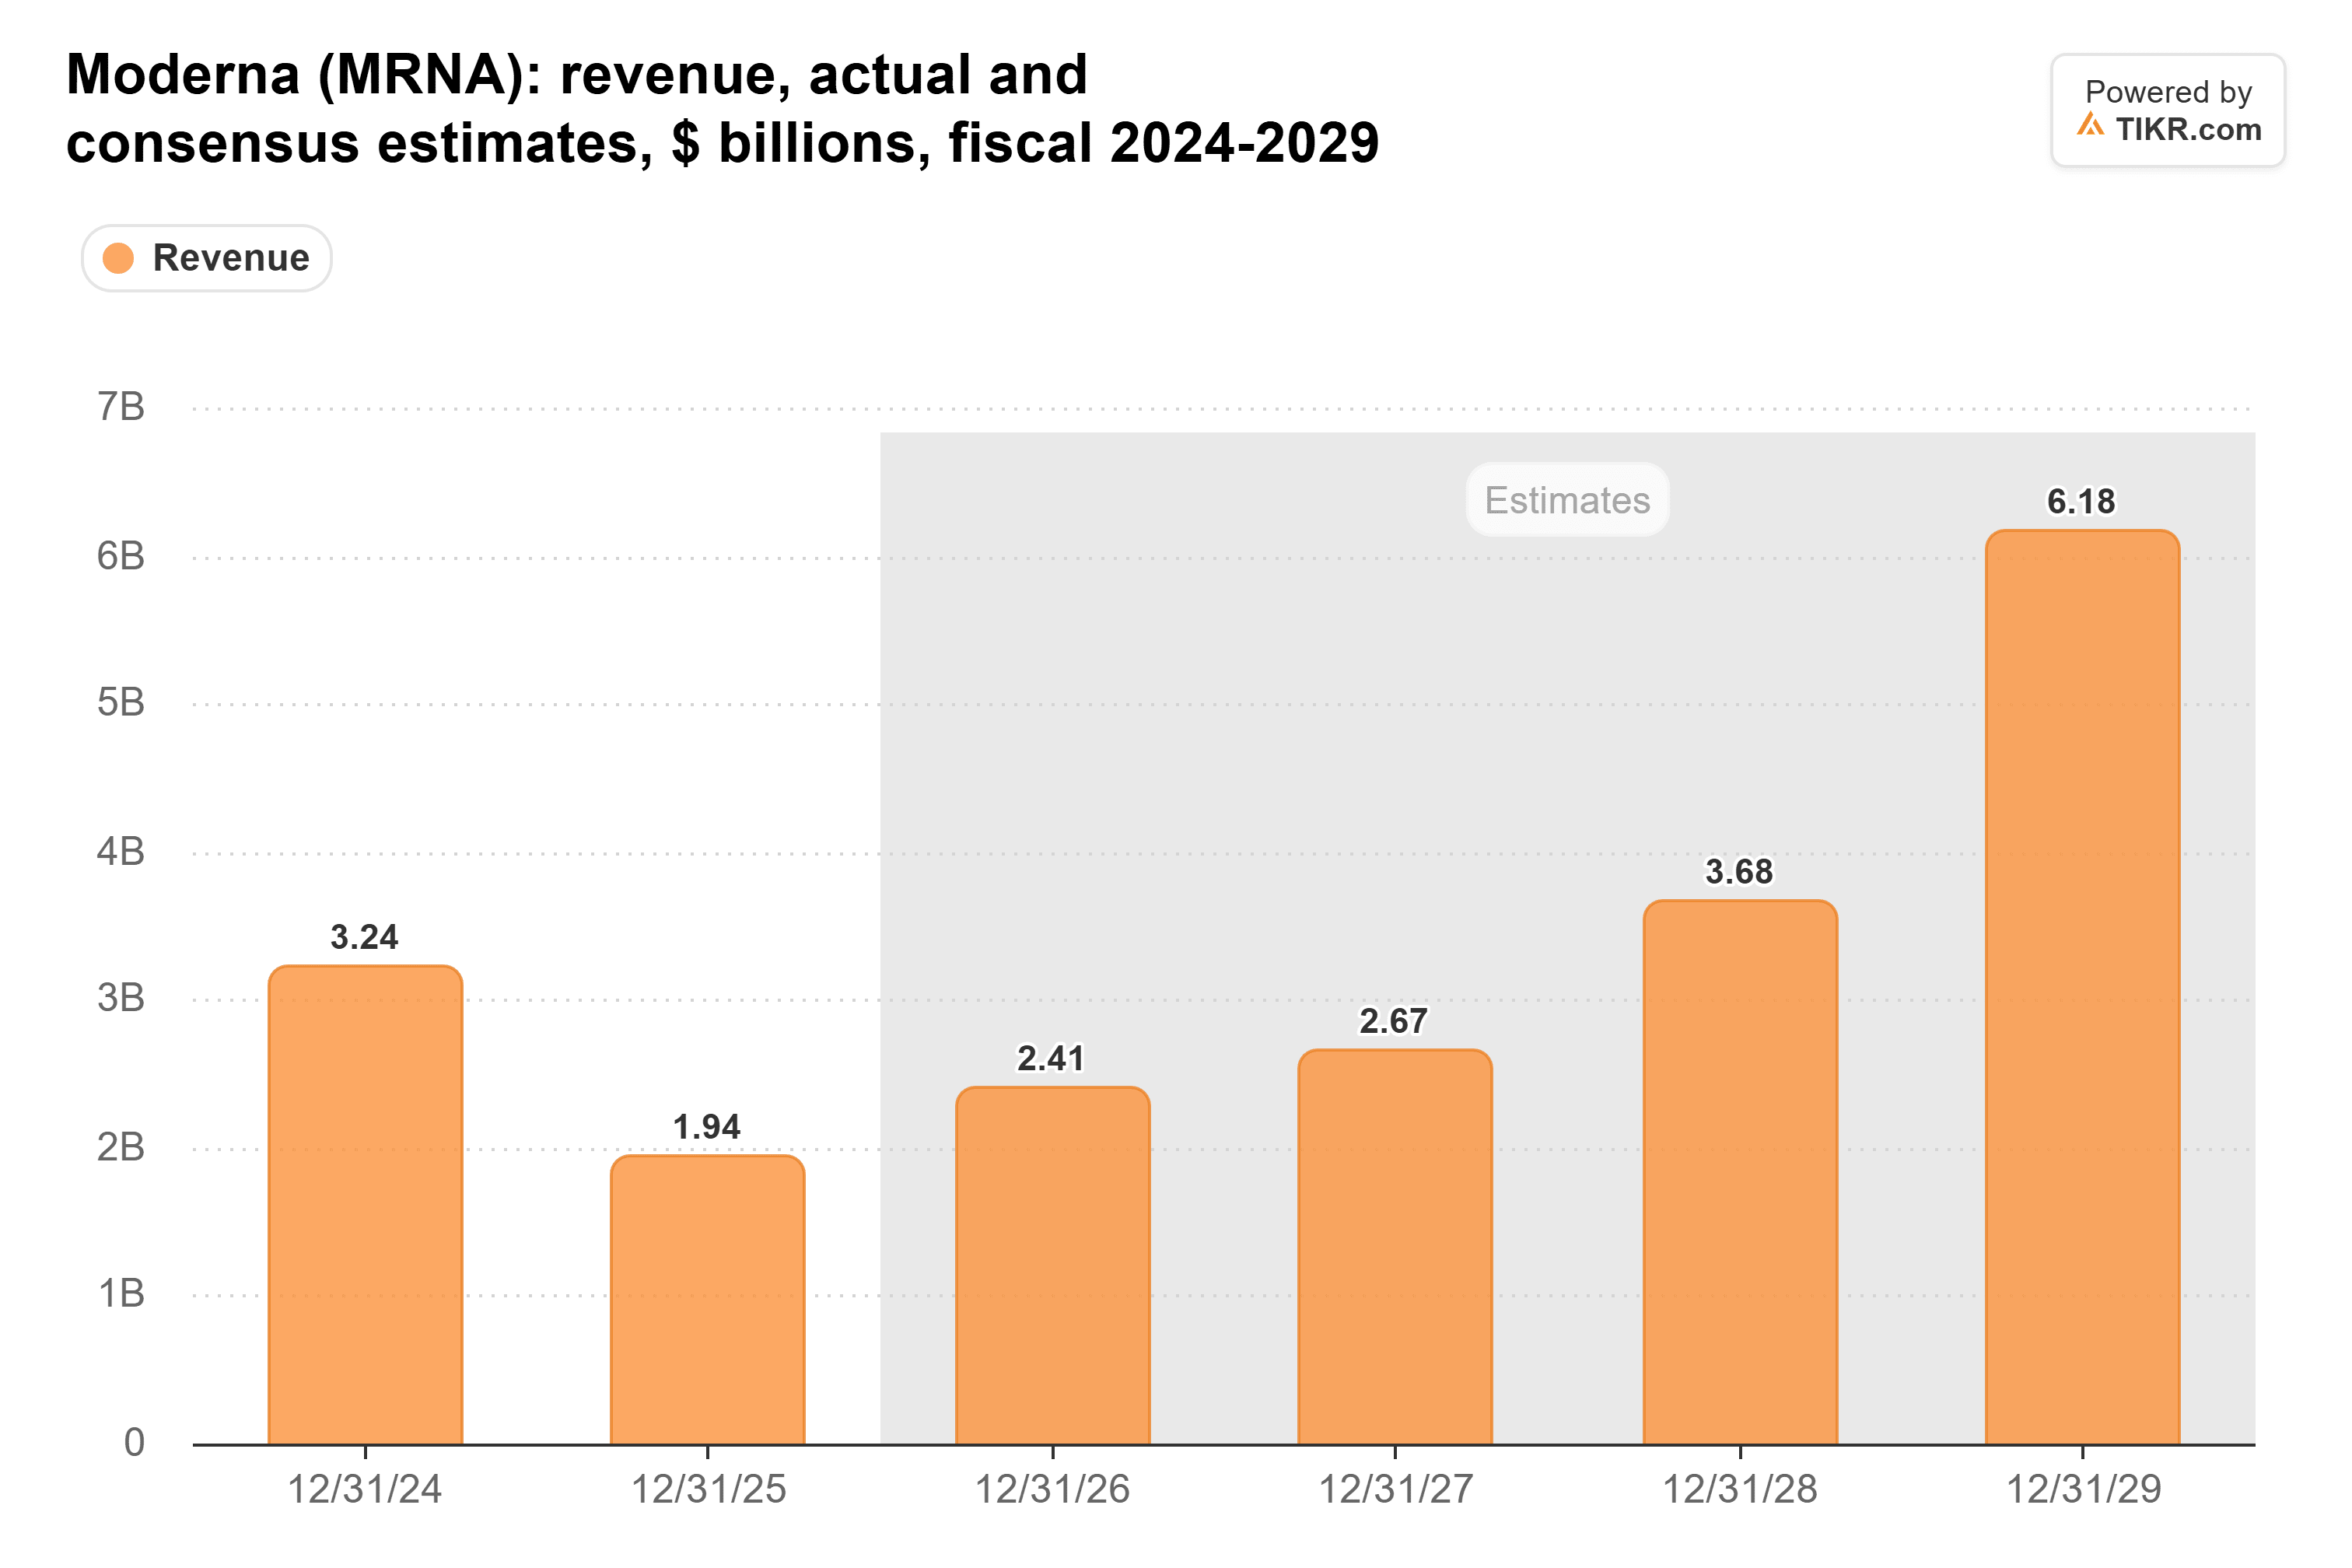
- Analysts’ 2028 revenue estimate is below a single year’s costs, and the stock trades far above its usual sales multiple.
- The stock looks too pricey to buy before the intismeran filing and 2027 guidance.
Moderna (MRNA) fell 12% in the week to Nov. 13, while the S&P 500 rose 2.5%. At its Nov. 12 Analyst Day, it put a bigger price tag on its cancer push, led by intismeran, the melanoma vaccine it shares with Merck (MRK).
And on Mad Money that night, CEO Stéphane Bancel said of intismeran: “we are working very, very deliberately to try to get the filing to the FDA before the end of the year.” That leaves rival BioNTech (BNTX), which has mRNA cancer drugs in its own late-stage pipeline, facing a better-funded push.
Costs are going back up
Moderna can fund the gap for now: it expects roughly $9 billion of liquidity at the end of 2026, counting cash, investments and undrawn borrowing. BioNTech holds more cash, at €16.2 billion, but its business is shrinking: analysts expect its revenue to fall 35.4% this year, with a loss of $5.68 a share.
Moderna can fund the gap for now: it expects roughly $9 billion of liquidity at the end of 2026, counting cash, investments and undrawn borrowing. BioNTech holds more cash, at €16.2 billion, but its business is shrinking: analysts expect its revenue to fall 35.4% this year, with a loss of $5.68 a share.
TIKR tracks 23 analysts on Moderna. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Moderna, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Moderna’s Analyst Ratings
Investors have already paid for a launch
Intismeran’s results are strong: in Phase 3, adding it to Merck’s Keytruda lowered the risk of melanoma recurrence or death by 42%, and by 58% after the six-month regimen ended. Merck splits its costs and profits evenly, but it’s a side bet next to Keytruda. For Moderna, it’s most of what investors are buying. Even after the drop, Moderna trades at about 40x forward sales, against a five-year average of 8.2x:

And the consensus target has climbed only to $158, well below the $223.37 close on Nov. 13:

A filing, ASH and 2027 guidance come next
A filing on schedule could bring an FDA decision in 2027, the timing Bancel gave TIME. Moderna also presents updated myeloma data at ASH on Dec. 12. It hasn’t given 2027 revenue guidance yet, and its fourth-quarter report, expected in February, is the next scheduled update. Waiting for the filing and that guidance makes sense, since analysts don’t expect revenue to catch up with costs until 2029. Of course, a 2027 revenue outlook well above the Street’s $2.67 billion would make those costs far easier to carry.
So what is Moderna stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Moderna could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


