Key Takeaways
- Oklo (OKLO) signed definitive agreements with Centrus Energy (LEU) on November 12 to secure enough nuclear fuel for up to five Aurora powerhouses, with deliveries starting in 2029.
- Meta Platforms (META) is helping finance fuel purchases for Oklo’s planned 1.2-gigawatt Ohio nuclear campus, while Centrus benefits from funding for its domestic uranium enrichment expansion.
- Oklo shares gained 1.6% over five trading sessions through November 13, closing at $23.92, while TIKR consensus estimates project negative $1.03 billion in free cash flow by 2028.
- Piper Sandler’s $49 price target implies approximately 105% upside, although construction costs, shareholder dilution, and commercial execution remain significant risks.
What Happened?
Oklo (OKLO) shares gained 1.6% over five trading sessions through November 13, closing at $23.92, despite falling 2.2% in the final session after announcing nuclear fuel agreements with Centrus Energy (LEU) backed by prepayments from Meta Platforms (META).
The November 12 agreements secure enough high-assay low-enriched uranium (HALEU) to support up to five Aurora powerhouses for multiple years. Deliveries from Centrus’ American Centrifuge Plant in Ohio are scheduled to begin in 2029.
According to Oklo’s official announcement, the fuel will support initial deployments at its planned 1.2-gigawatt Ohio campus, future Aurora projects, and later refueling at its first Idaho reactor.
The agreements formalize a June 2026 letter of intent, giving Oklo greater certainty over a critical part of its nuclear fuel supply chain.
More importantly, Meta is already helping fund these purchases through prepayments for future electricity rather than simply expressing interest in nuclear power.
Oklo’s third-quarter filing confirms that Meta’s initial funding installment was released from escrow on November 2 and paid directly to Centrus as a credit toward fuel orders.
The companies described the prepayments as meaningful but did not disclose their dollar value.
Oklo CEO Jacob DeWitte highlighted the importance of the agreements, saying, “These agreements support our initial Ohio deployments and provide fuel for future Aurora powerhouses.”
Centrus also benefits from the arrangement. The prepayments support its domestic enrichment expansion, while the company has secured $5.4 billion in customer contracts and commitments for low-enriched uranium and HALEU from its planned new capacity.
For Oklo, the agreement reduces uncertainty over specialized fuel supply. However, securing fuel doesn’t eliminate the significant capital required to build and operate commercial reactors.
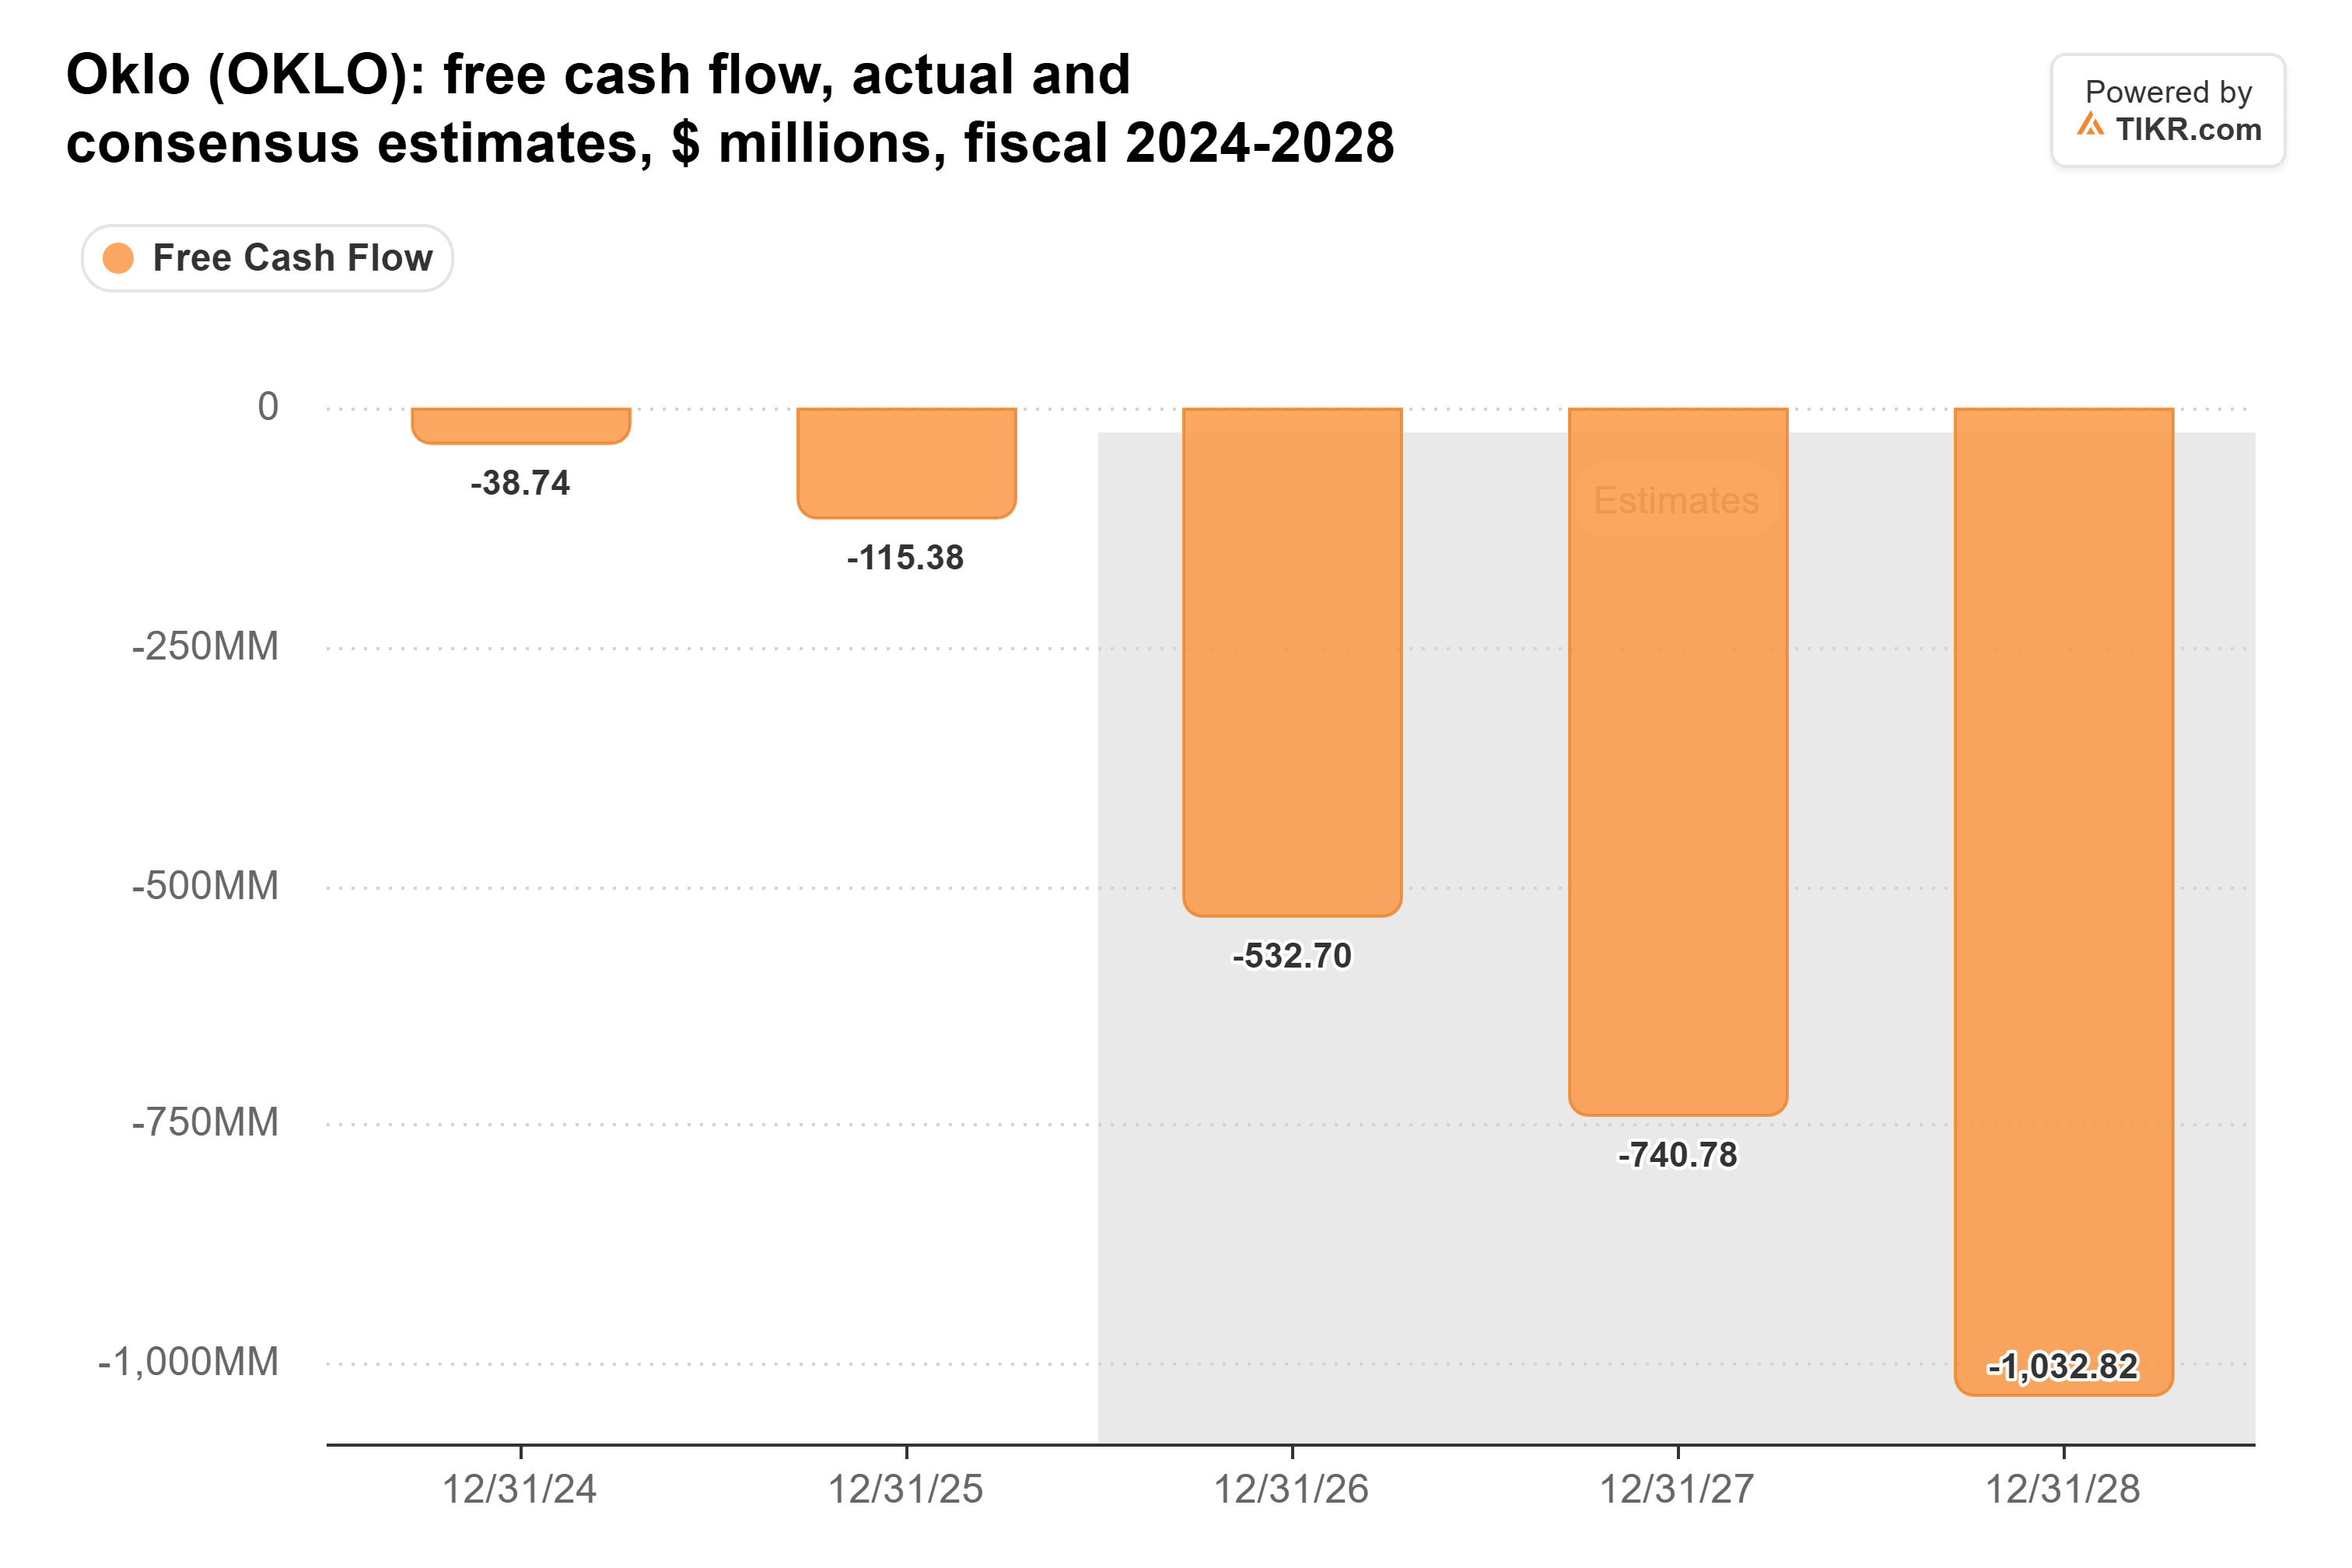
Oklo recorded negative $115 million in free cash flow in 2025. TIKR consensus estimates project negative $533 million in 2026, negative $741 million in 2027, and negative $1.03 billion in 2028.
Those figures illustrate why customer-funded fuel purchases matter. Oklo is still developing its commercial power business and needs substantial capital before its reactors can generate meaningful electricity revenue.
The company raised approximately $2.3 billion through stock sales during the first nine months of 2026 and announced another $1 billion at-the-market offering program in September.
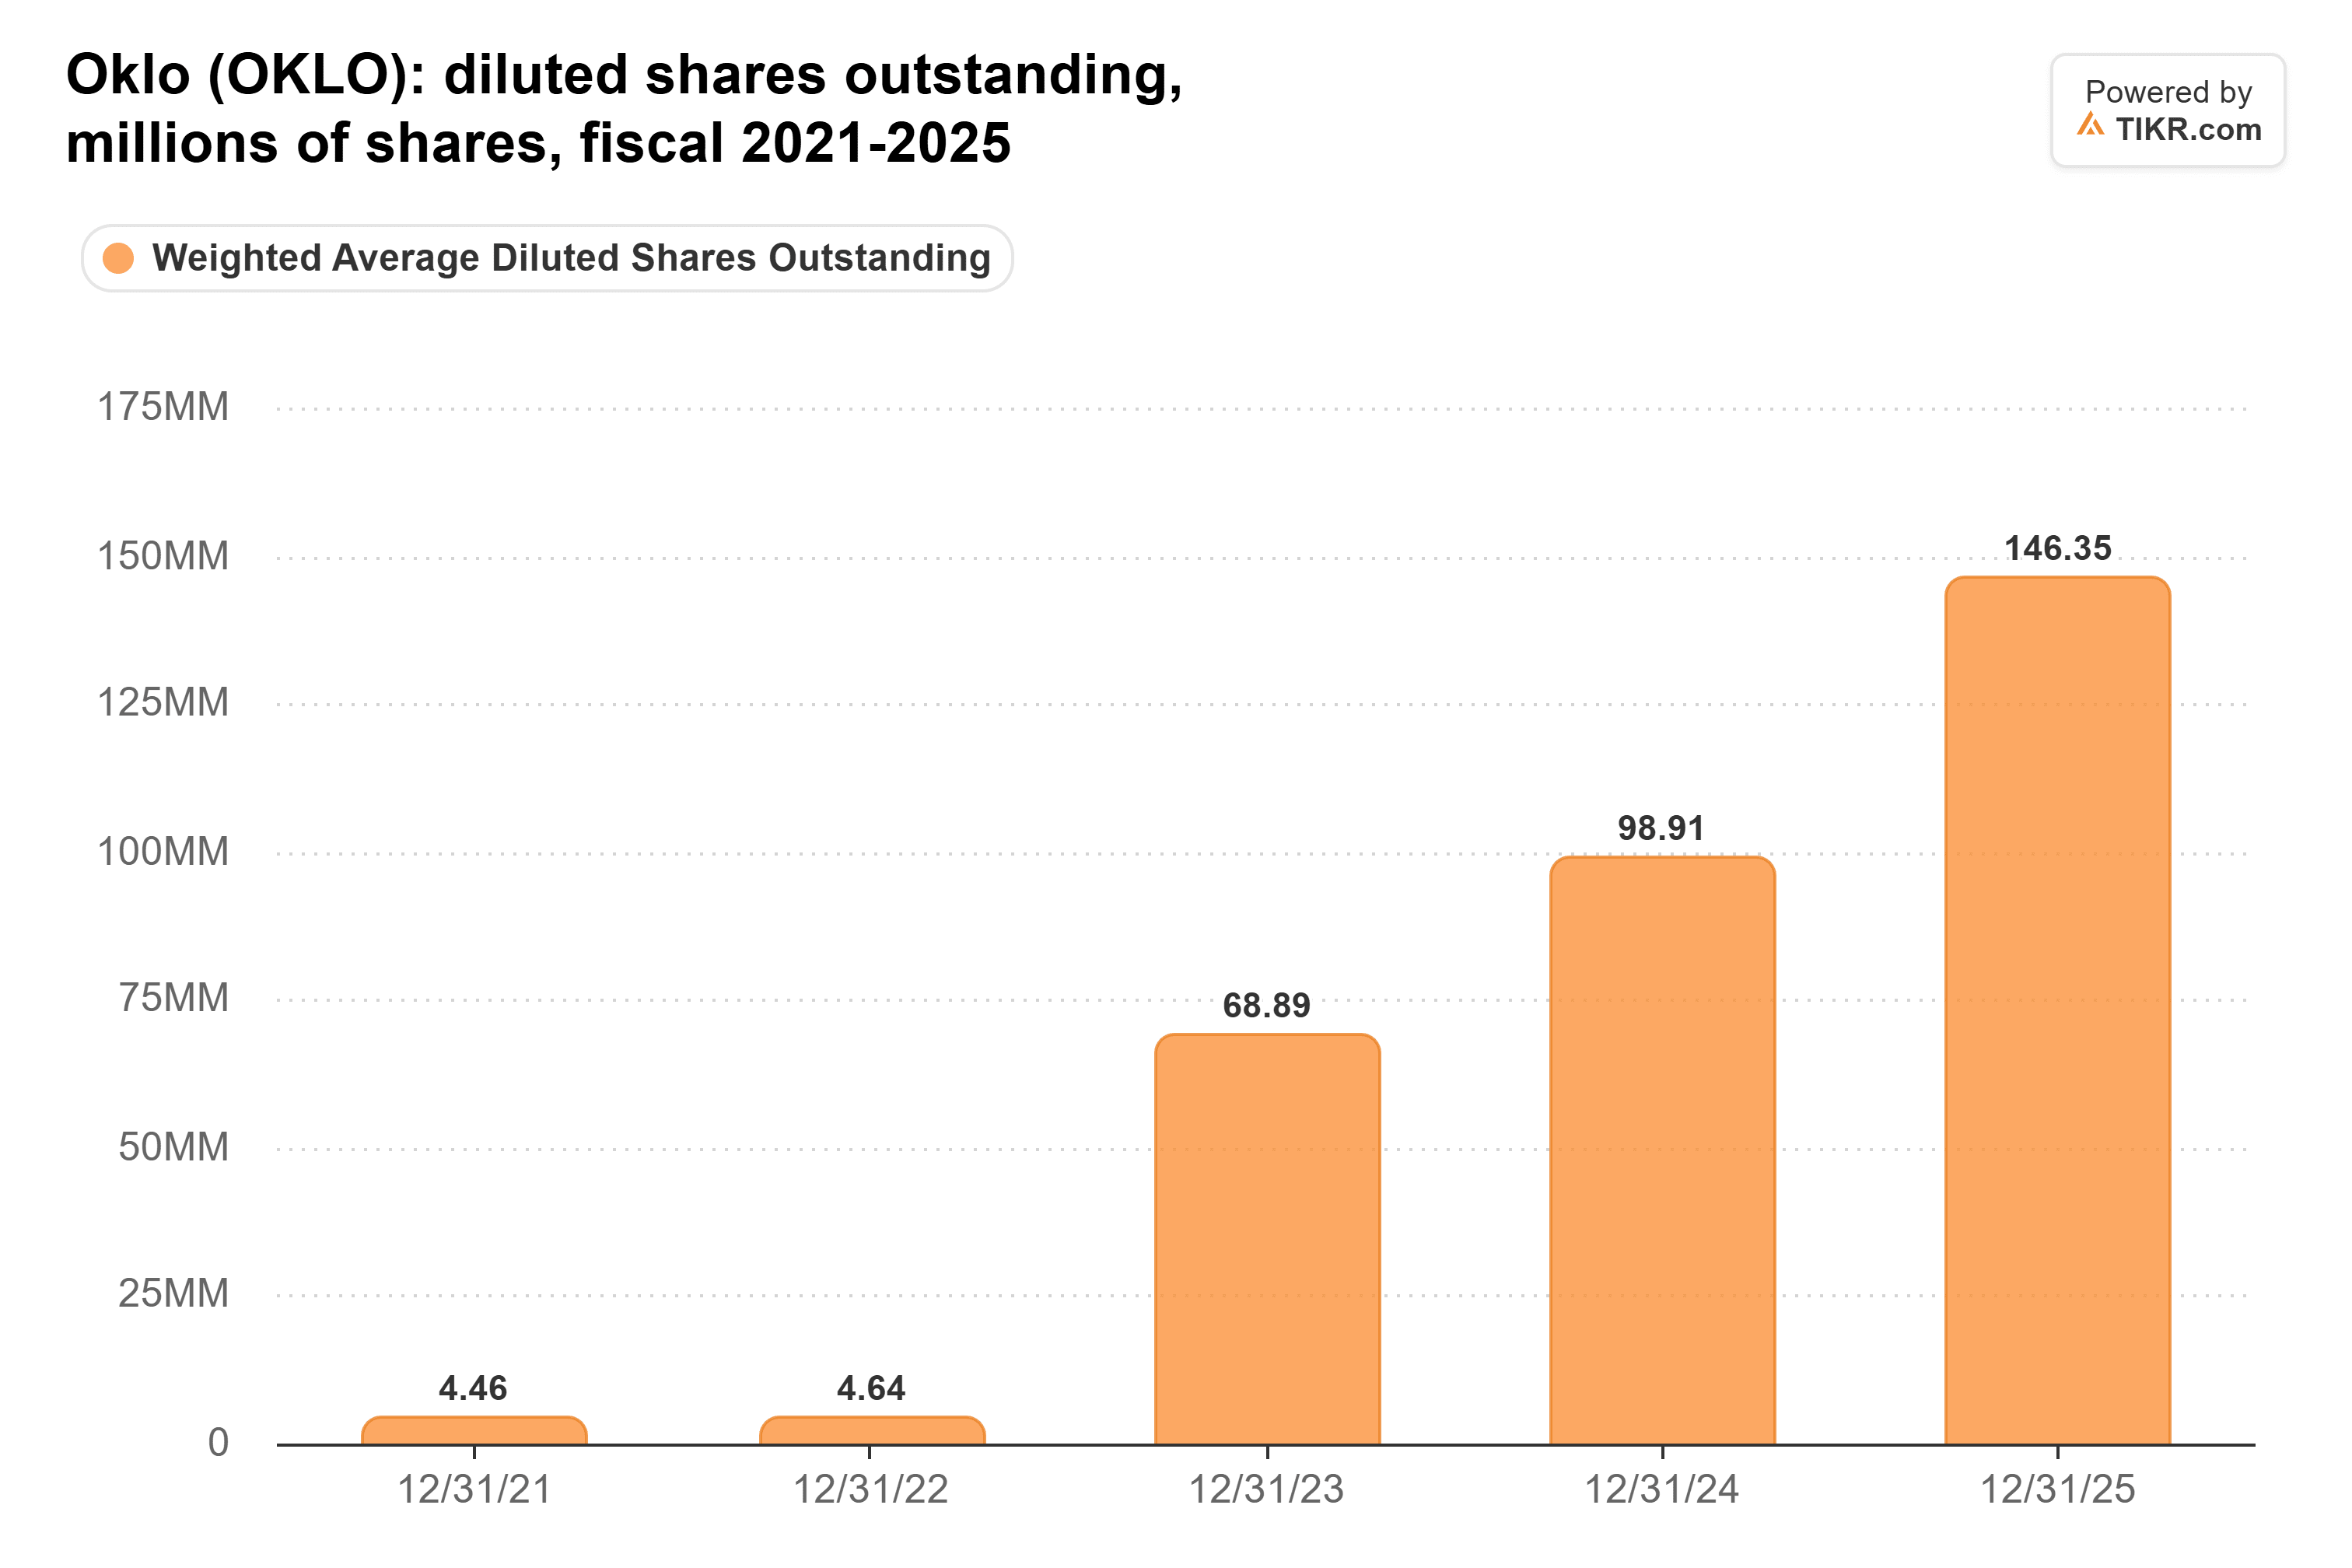
Oklo’s weighted-average diluted share count increased from approximately 98.9 million in 2024 to 146 million in 2025, highlighting how equity financing has expanded its share base.
Meta’s prepayment helps reduce the amount Oklo must independently finance for fuel purchases, although the undisclosed payment amount makes the overall impact difficult to quantify.
Meta also has its own financial considerations. The company signed its prepayment agreement with Oklo in January to support future power generation for its data centers, but its capital spending requirements are substantial.
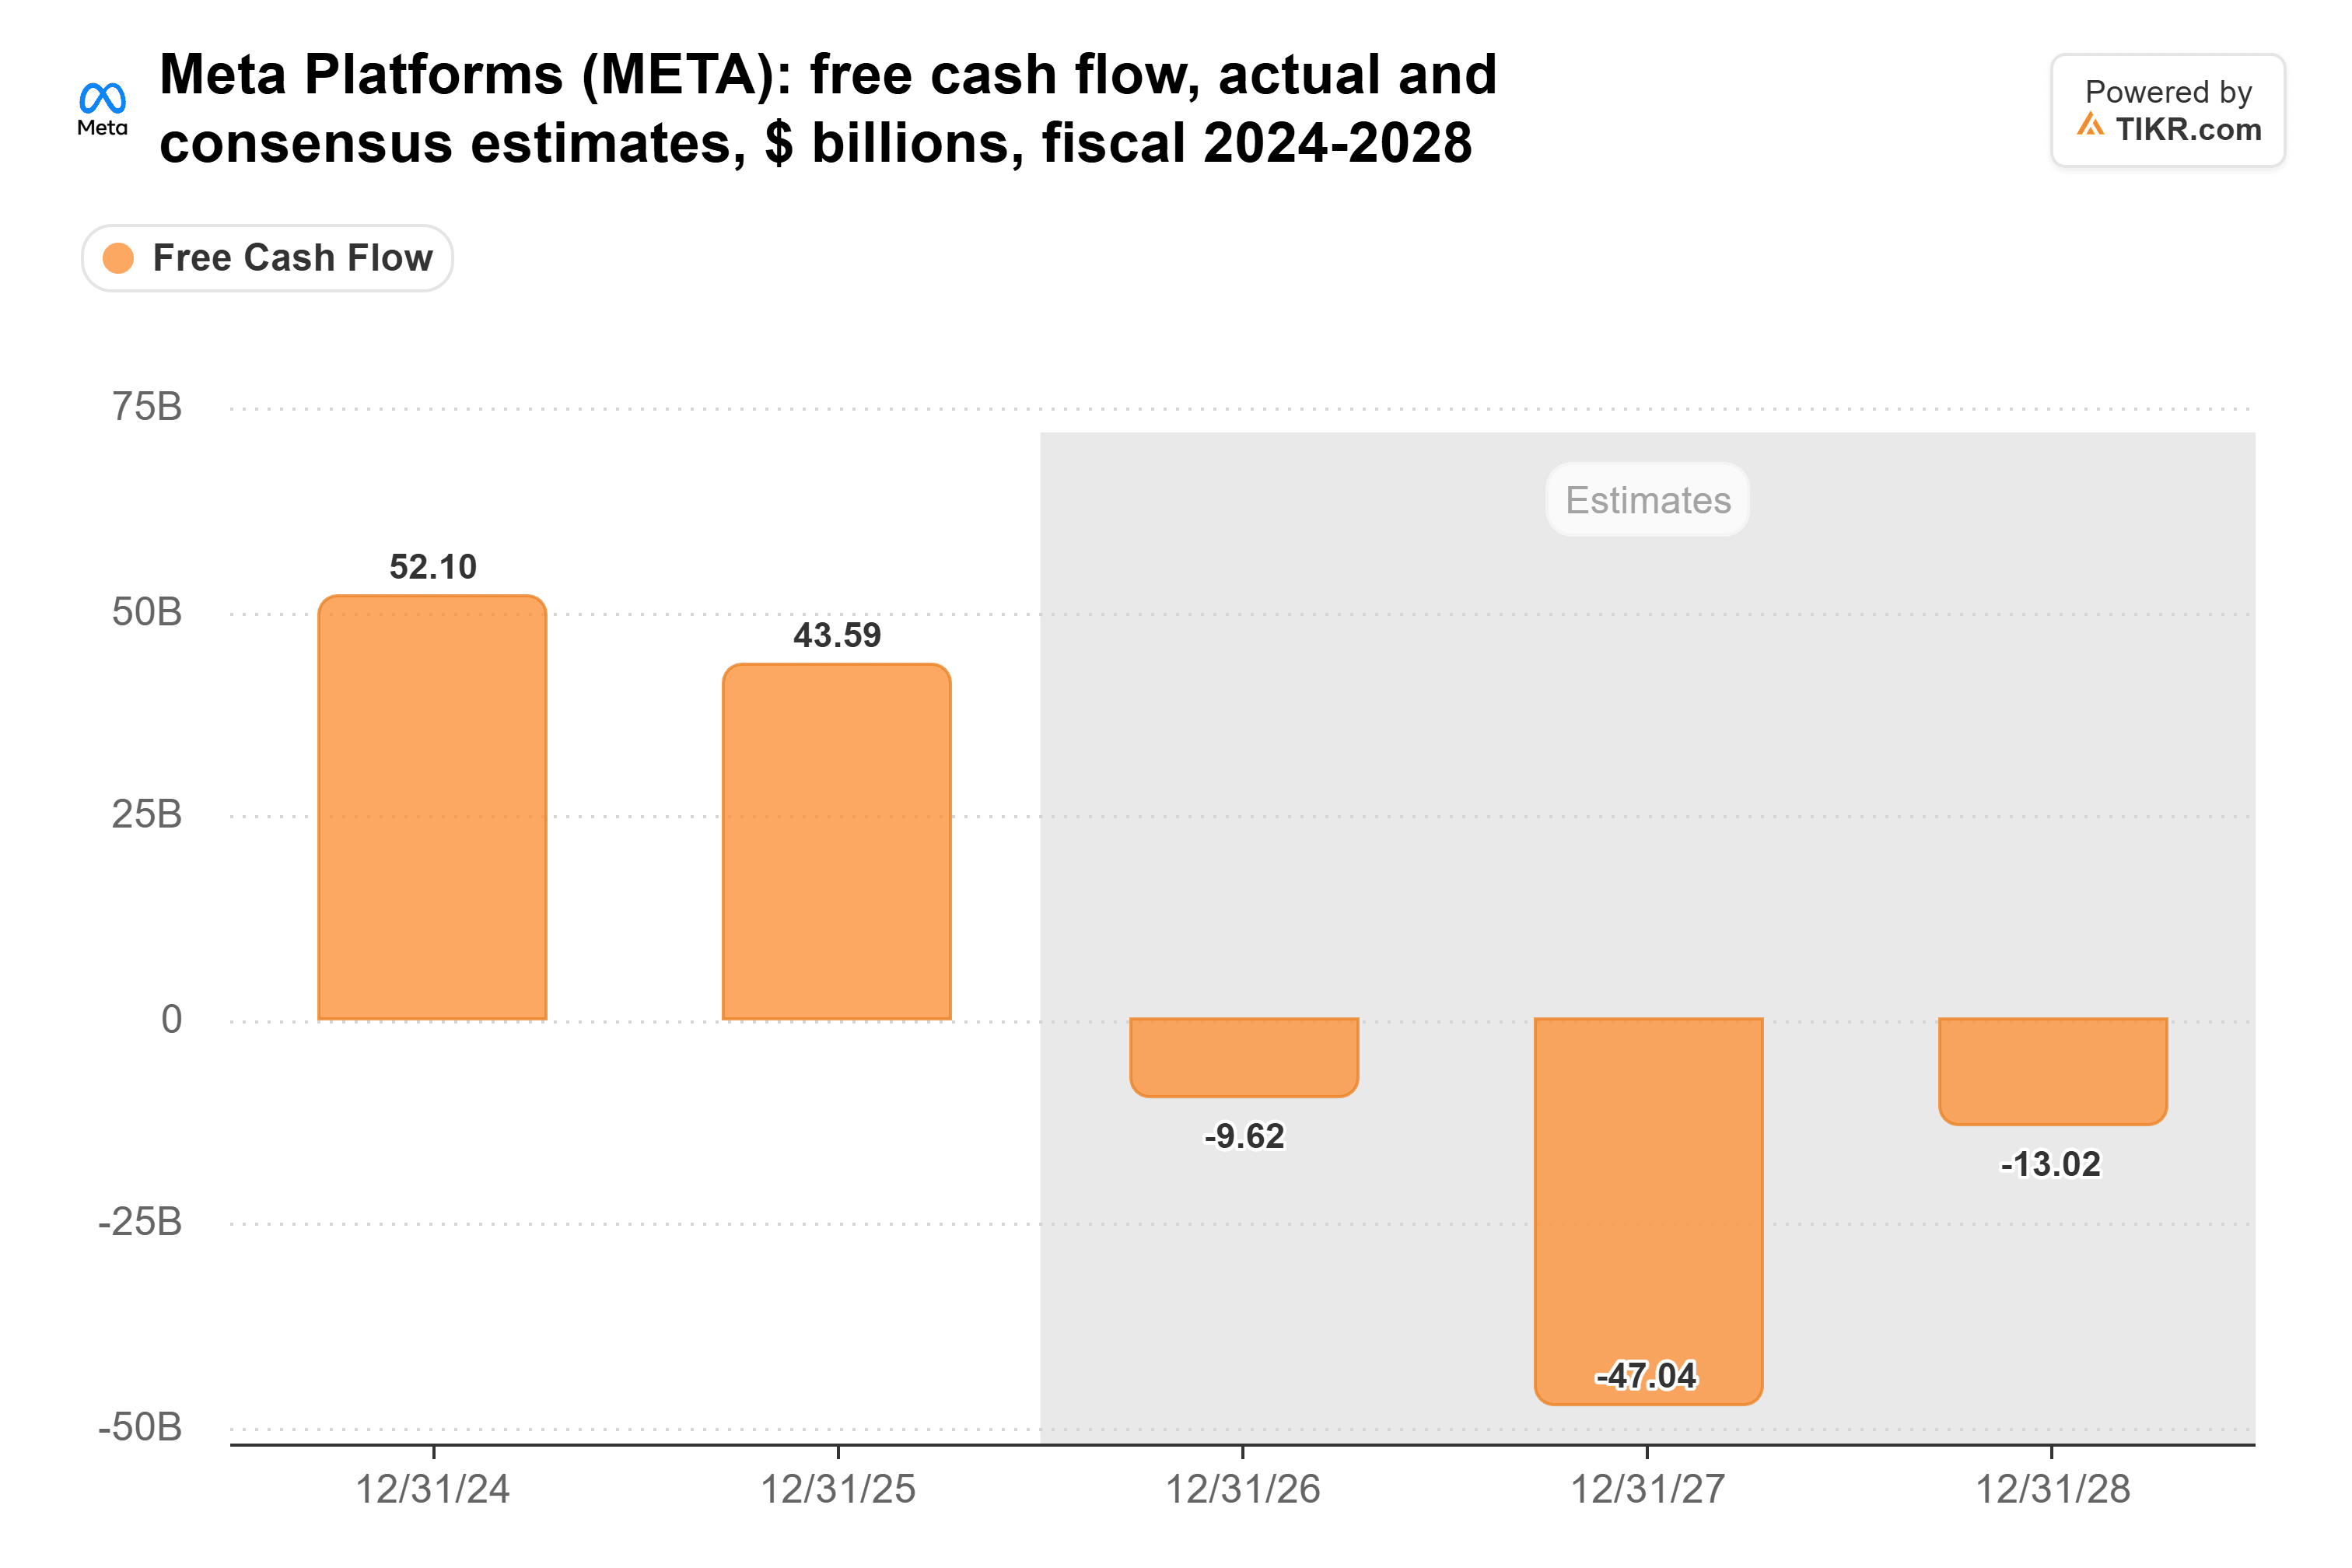
Meta generated approximately $43.6 billion in free cash flow in 2025. Based on TIKR consensus estimates as of November 4, 2026, free cash flow is projected to turn negative at approximately $9.6 billion in 2026, $47 billion in 2027, and $13 billion in 2028, reflecting expectations for substantial investment spending.
These projections suggest that Meta’s infrastructure investment plans could consume substantial cash even as it commits funding to future nuclear power supplies.
The prepayment may help Meta secure access to electricity for its expanding data centers, but the undisclosed amount means investors cannot determine how significant the obligation is relative to its broader capital spending.
Is Oklo Stock Undervalued or Overvalued?
At approximately $23.92 per share, Oklo remains a speculative investment rather than a clearly undervalued nuclear energy stock, despite progress in securing fuel supply.
Piper Sandler maintained its Overweight rating in October while lowering its price target to $49 from $55, implying approximately 105% upside from the November 13 closing price.
That potential upside reflects expectations for a future commercial reactor business, but Oklo still faces substantial construction, regulatory, and financing challenges before generating meaningful electricity revenue.
As discussed in TIKR’s previous Oklo analysis, Piper Sandler raised its estimated construction cost for new Oklo plants to $7,000 per kilowatt from $4,000, highlighting the financial pressure associated with commercial deployment.
Meta’s prepayment helps Oklo address an important fuel supply challenge, but investors still need evidence that the company can build reactors at costs that make electricity generation commercially viable.
The Meta agreement also remains a prepayment framework, with definitive electricity pricing and purchase terms still important to the long-term economics of the Ohio project.
Over the next 12 months, progress on reactor licensing, construction costs, project financing, and binding power purchase agreements could matter more to Oklo’s valuation than additional fuel procurement announcements.
The Centrus agreement strengthens Oklo’s expansion plans by securing a critical input and demonstrating tangible customer support from Meta.
However, with free cash flow projected to remain deeply negative, potential shareholder dilution, and uncertain reactor economics, Oklo stock is difficult to classify as undervalued based on this agreement alone. Clearer construction costs and stronger commercial commitments would make the long-term investment case more convincing.
So what is Oklo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Oklo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!