Key Takeaways
- Marvell Technology fell 14% in the past week on reported Lumentum talks, then in a chip selloff after Intel’s weak outlook.
- Lumentum’s lasers would make Marvell a bigger Broadcom rival and give Coherent a competitor backed by Marvell’s chips.
- A deal would reportedly be paid in Marvell shares, so I’d wait for the share count.
Marvell Technology (MRVL) stock is down 14% in the past week.
Bloomberg reported after Wednesday’s close that Marvell is in advanced talks to buy Lumentum (LITE), which would push it deeper into the AI networking Broadcom (AVGO) sells and leave Coherent (COHR) as the big laser maker not controlled by a chip designer. Then Intel (INTC) gave a weak outlook after Thursday’s close, sinking AI chip stocks again.
The Price Is in Shares
Lumentum was worth about $83 billion at the report, more than a third of Marvell’s own value, while Marvell held just $3.93 billion in cash as of Aug. 1. So a deal would mean a lot of new shares, and investors balked. Analysts expect Marvell’s normalized EPS to more than double, from $2.84 in the year ended January 2026 to $7.33 in the year ending January 2028:
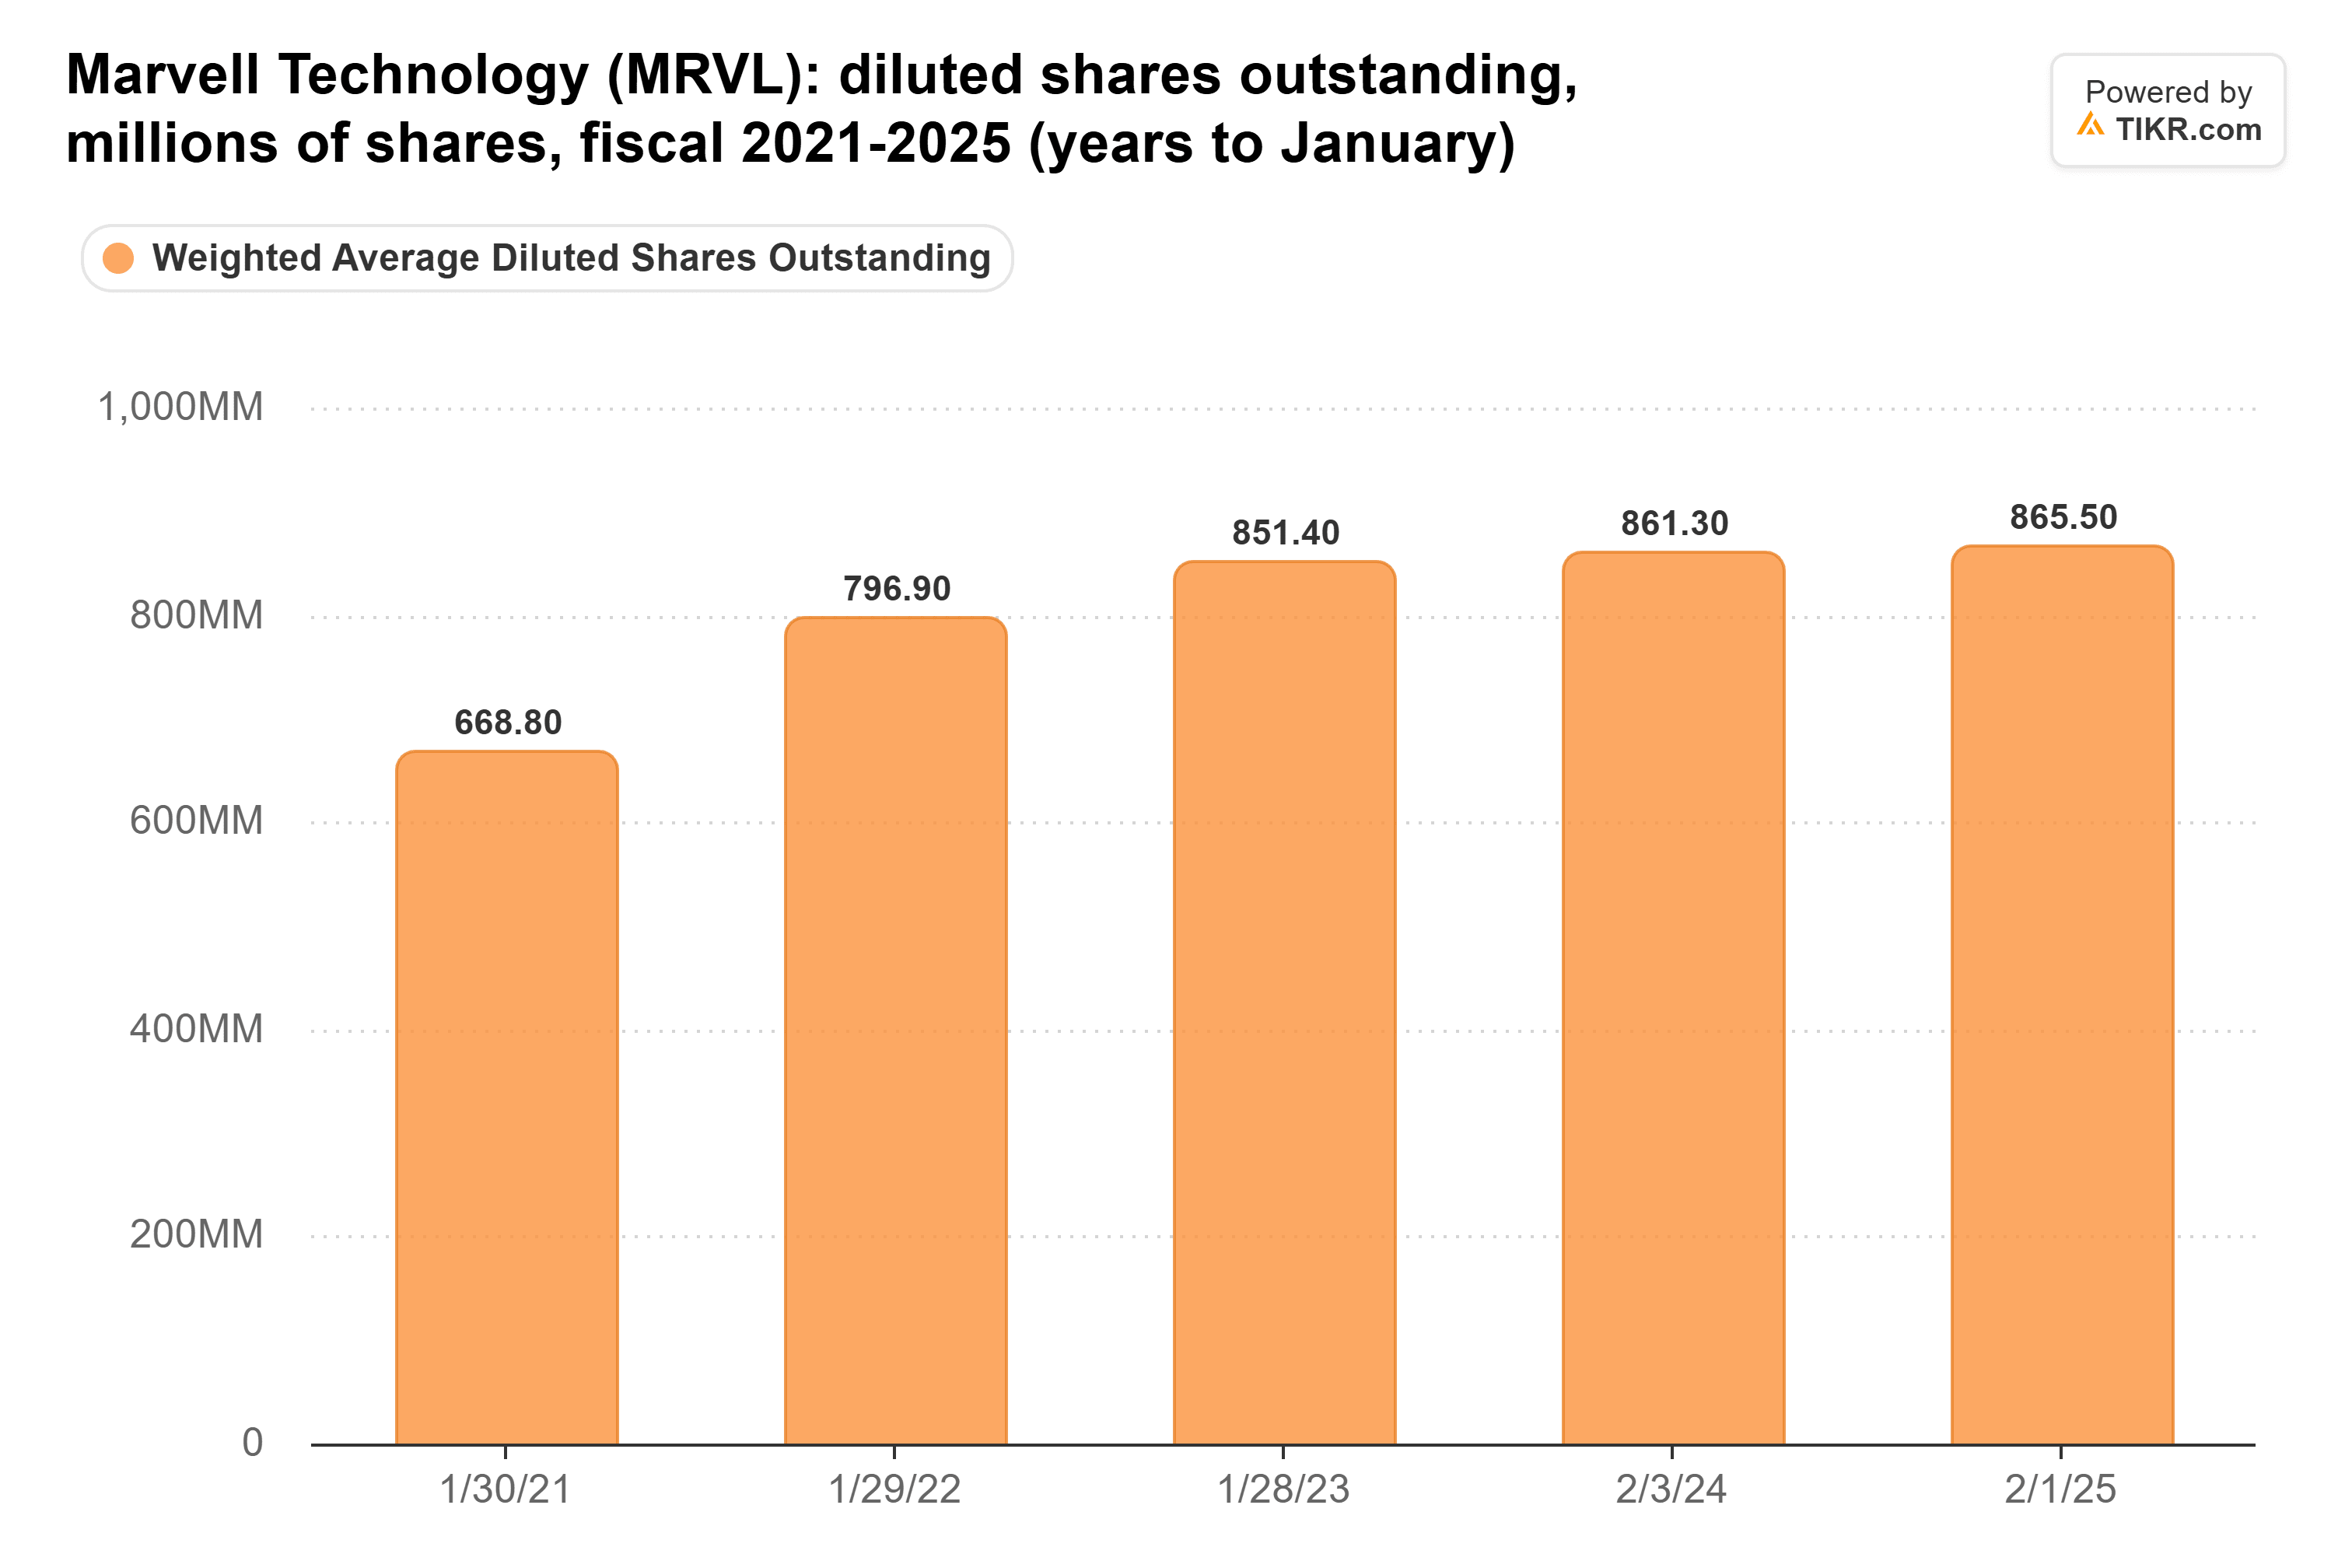
The report shouldn’t move those estimates yet. Paying in stock would add shares, but whether that lowers or raises EPS would depend on Lumentum’s profits and the price Marvell pays. Marvell has paid in shares before: its share count jumped 19%, from 669 million in fiscal 2021 to 797 million in fiscal 2022, after it bought Inphi largely with stock:

Broadcom and Coherent Would Feel It
On a Bloomberg Intelligence podcast Thursday, analyst Mandeep Singh said small chipmakers like Marvell “don’t have a choice but to go the acquisition route.” Broadcom booked $16.7 billion of AI chip revenue in the quarter ended Aug. 2, and lasers would help Marvell chase it.
Coherent grew revenue 34% to $2.05 billion in the quarter ended June 30. Its early-November report should show whether customers wanting an independent laser supplier send it more orders.
Intel’s Outlook Hit the Group
Intel guided fourth-quarter revenue to $15.0 billion to $16.0 billion, below expectations, and chip stocks fell with it on Friday, Marvell by another 10%. Amazon, one of Marvell’s biggest custom-chip customers, reported the same evening, and its spending cuts the other way: its free cash flow was negative $42.4 billion over the trailing 12 months as it builds out AI.
TIKR Tracks 47 Analysts on Marvell. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
Wait for Marvell’s Share Count
Marvell’s forward P/E fell to 39x on Thursday, from nearly 70x in June:

Friday’s drop took it closer to its 33x five-year average, and the $341 consensus target is about 74% above Friday’s close.
Still, I’d wait to see how many shares Marvell issues before calling it cheap. A deal could come as soon as next week, Lumentum reports on Nov. 5, and the talks could still collapse. Marvell’s own fiscal third-quarter report comes in early December, guided at $3.15 billion of revenue.
So what is Marvell stock actually worth if the deal doesn’t go through?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!