Key Takeaways
- Marvell agreed on November 2 to buy Lumentum in an all-stock deal valuing it at $115 billion, leaving Lumentum holders with about a third of the combined company.
- Marvell’s CEO admitted on Fox Business that the deal carries more risk, saying being unorthodox is how you get “the outsized return.”
- Marvell held its $3.15 billion third-quarter revenue midpoint, which implies about 52% growth, and narrowed the range to plus or minus 2%.
- The December 1 report must show the standalone business can carry the stock until closing, which is expected in the first half of 2028.
Marvell Technology (MRVL) has spent two weeks defending the biggest deal in its history. On November 2, it agreed to buy Lumentum (LITE), the maker of lasers and optical transceivers, for an implied $115 billion in stock. Investors sold both shares anyway.
NVIDIA (NVDA) has a stake in how this plays out, since it has invested in both companies. Lumentum CEO Michael Hurlston told Fox Business that Nvidia’s reaction to the deal had been very positive.
Now attention shifts to December 1, when Marvell reports its fiscal third quarter. That report is the first real test of whether the core business can carry the stock while the deal waits on approvals.
A $115 billion bet on optics
Here is what Marvell signed up for:
- Lumentum holders get 4.5 Marvell shares each, worth about $1,132 at signing and a 23.9% premium to the October 28 close.
- Current Marvell holders will own about 67% of the combined company on a fully diluted basis.
- Management targets over $1 billion in annual cost synergies and expects the deal to lift non-GAAP EPS in its first year after closing.
Closing is expected in the first half of calendar 2028, pending shareholder and regulatory approvals. So the payoff sits more than a year out, while the exchange ratio is locked today.
Marvell’s share count was already creeping higher before this…
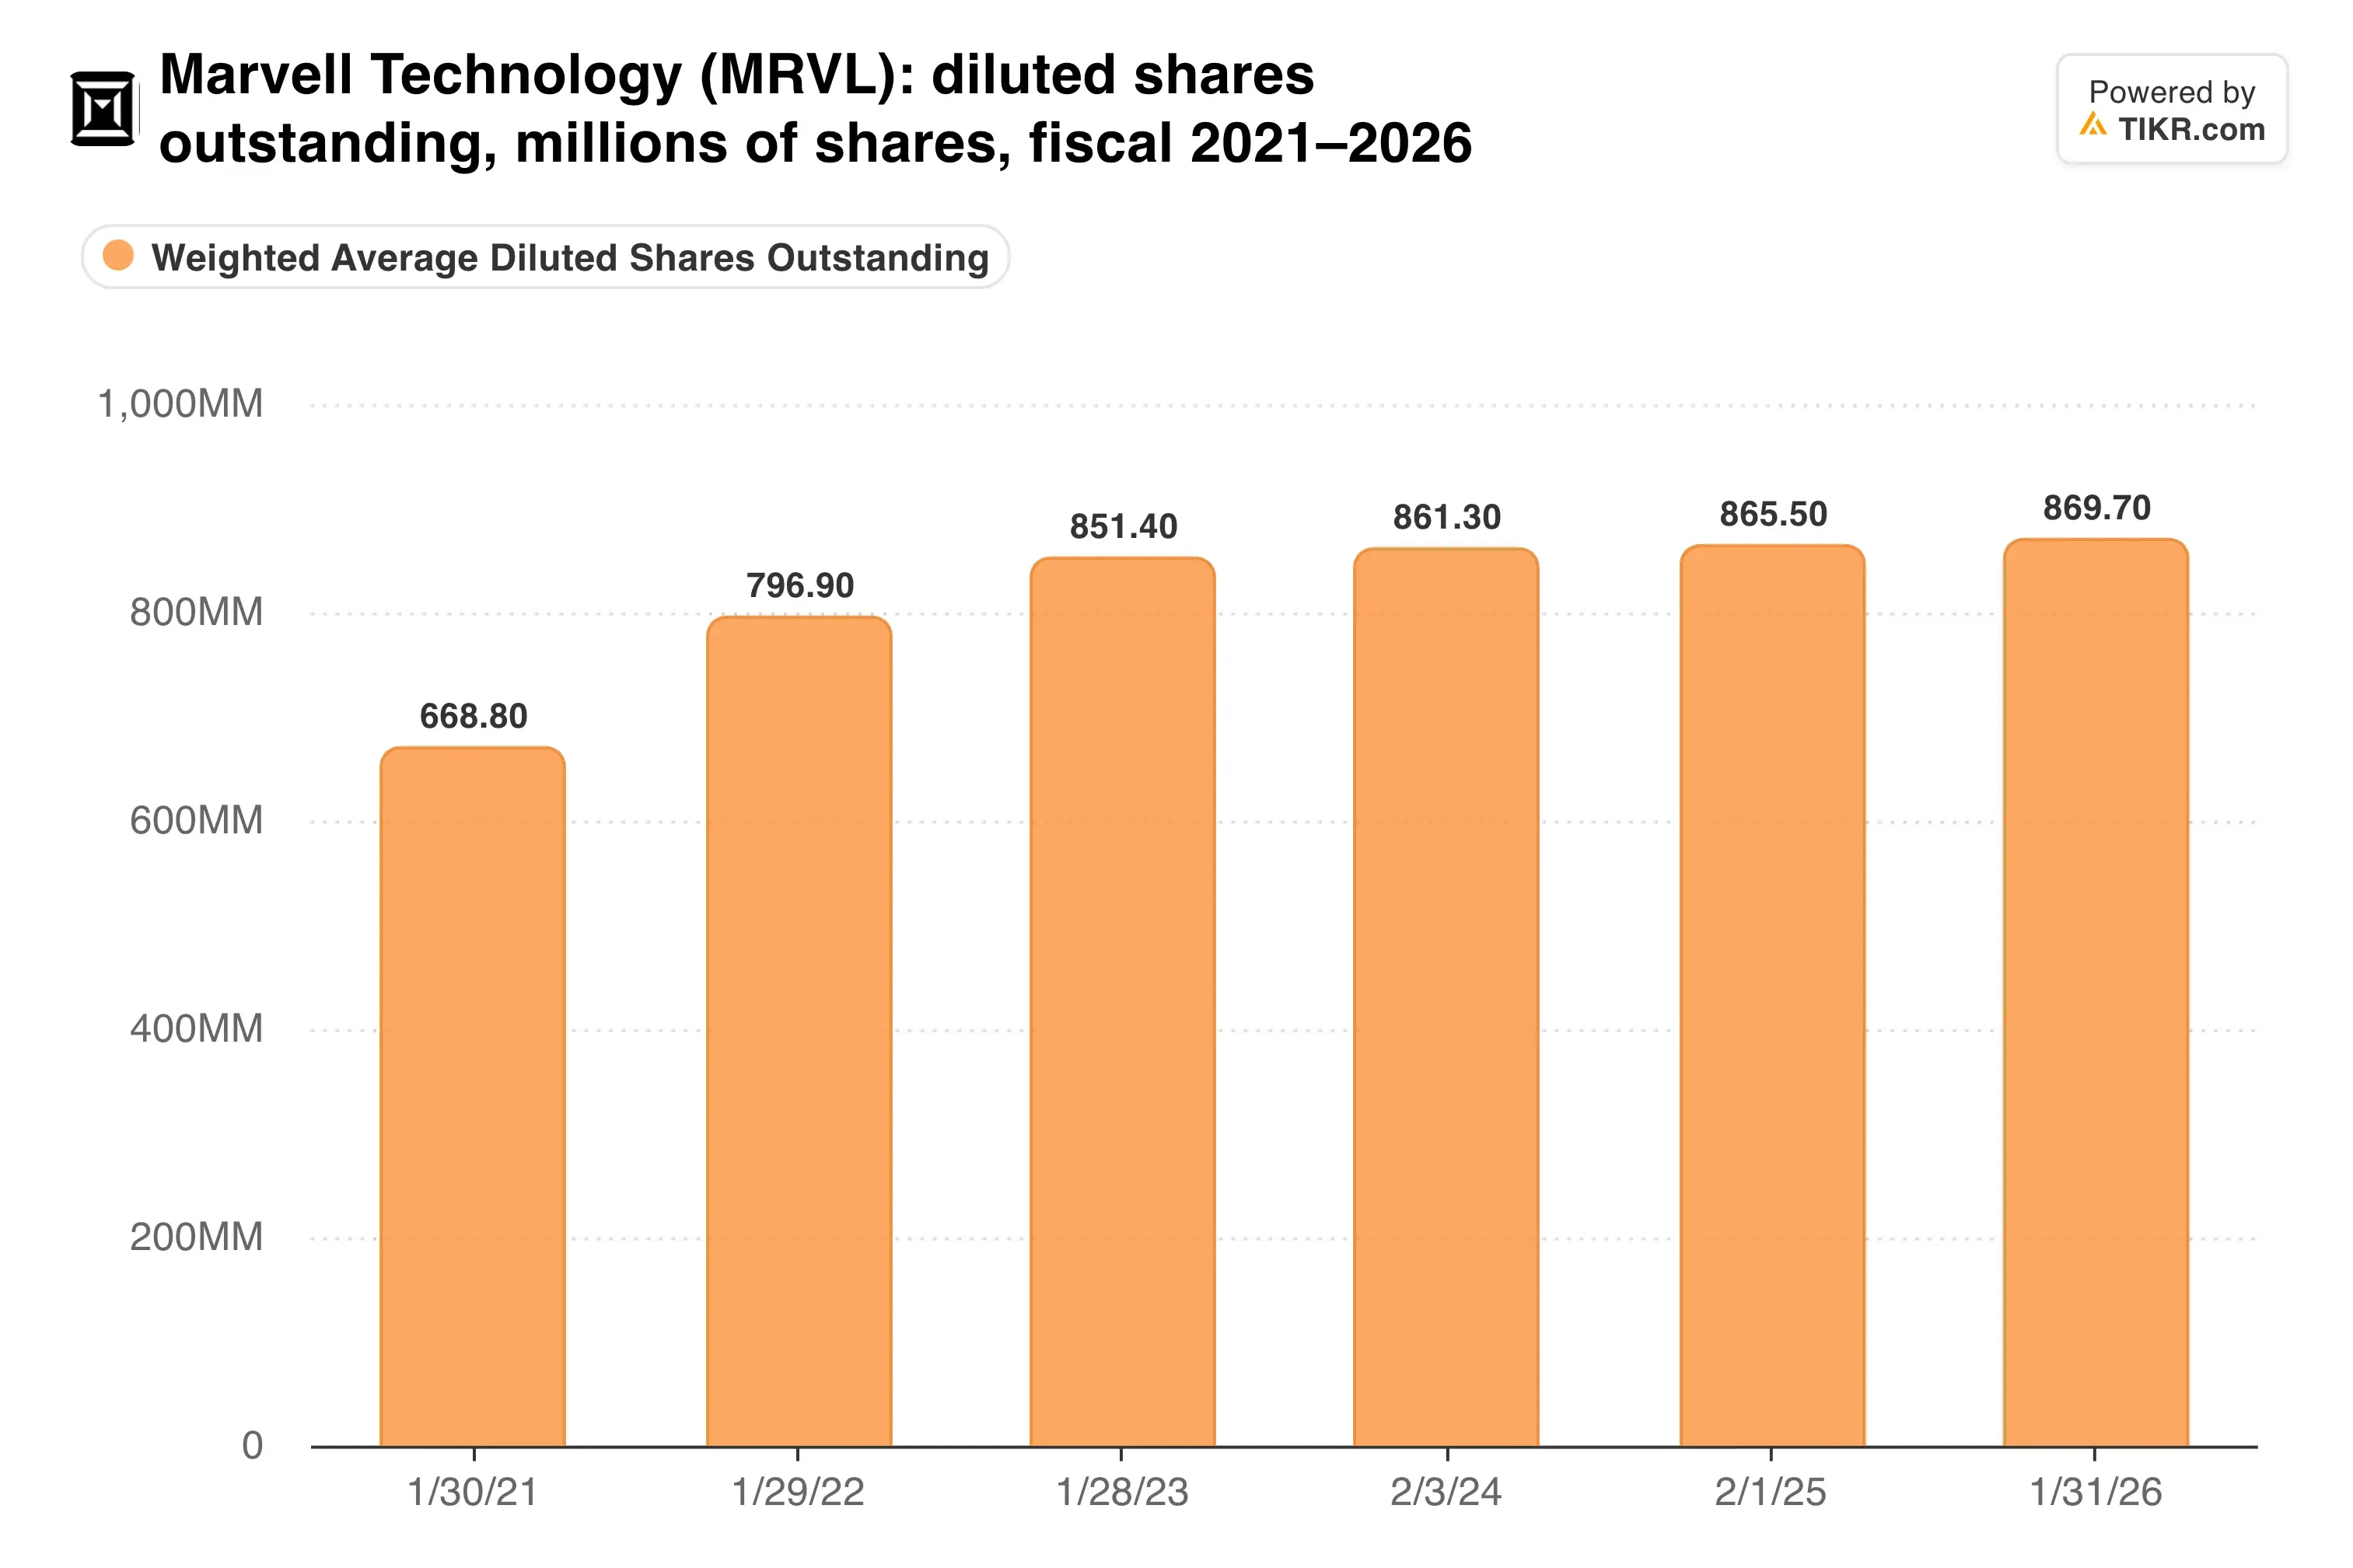
The company guided to 921 million diluted shares for the October quarter. Lumentum’s holders would add roughly half that number again.
The core business is speeding up
Ironically, Marvell didn’t need this deal to tell a growth story. Second-quarter revenue rose 37% to a record $2.739 billion, and data center sales climbed 46% to $2.17 billion. Non-GAAP EPS came in at $0.94.
Alongside the deal, Marvell also held its third-quarter revenue midpoint at $3.15 billion and tightened the range to plus or minus 2%. Against $2.075 billion a year earlier, that midpoint implies about 52% growth.
How sharp is the acceleration?
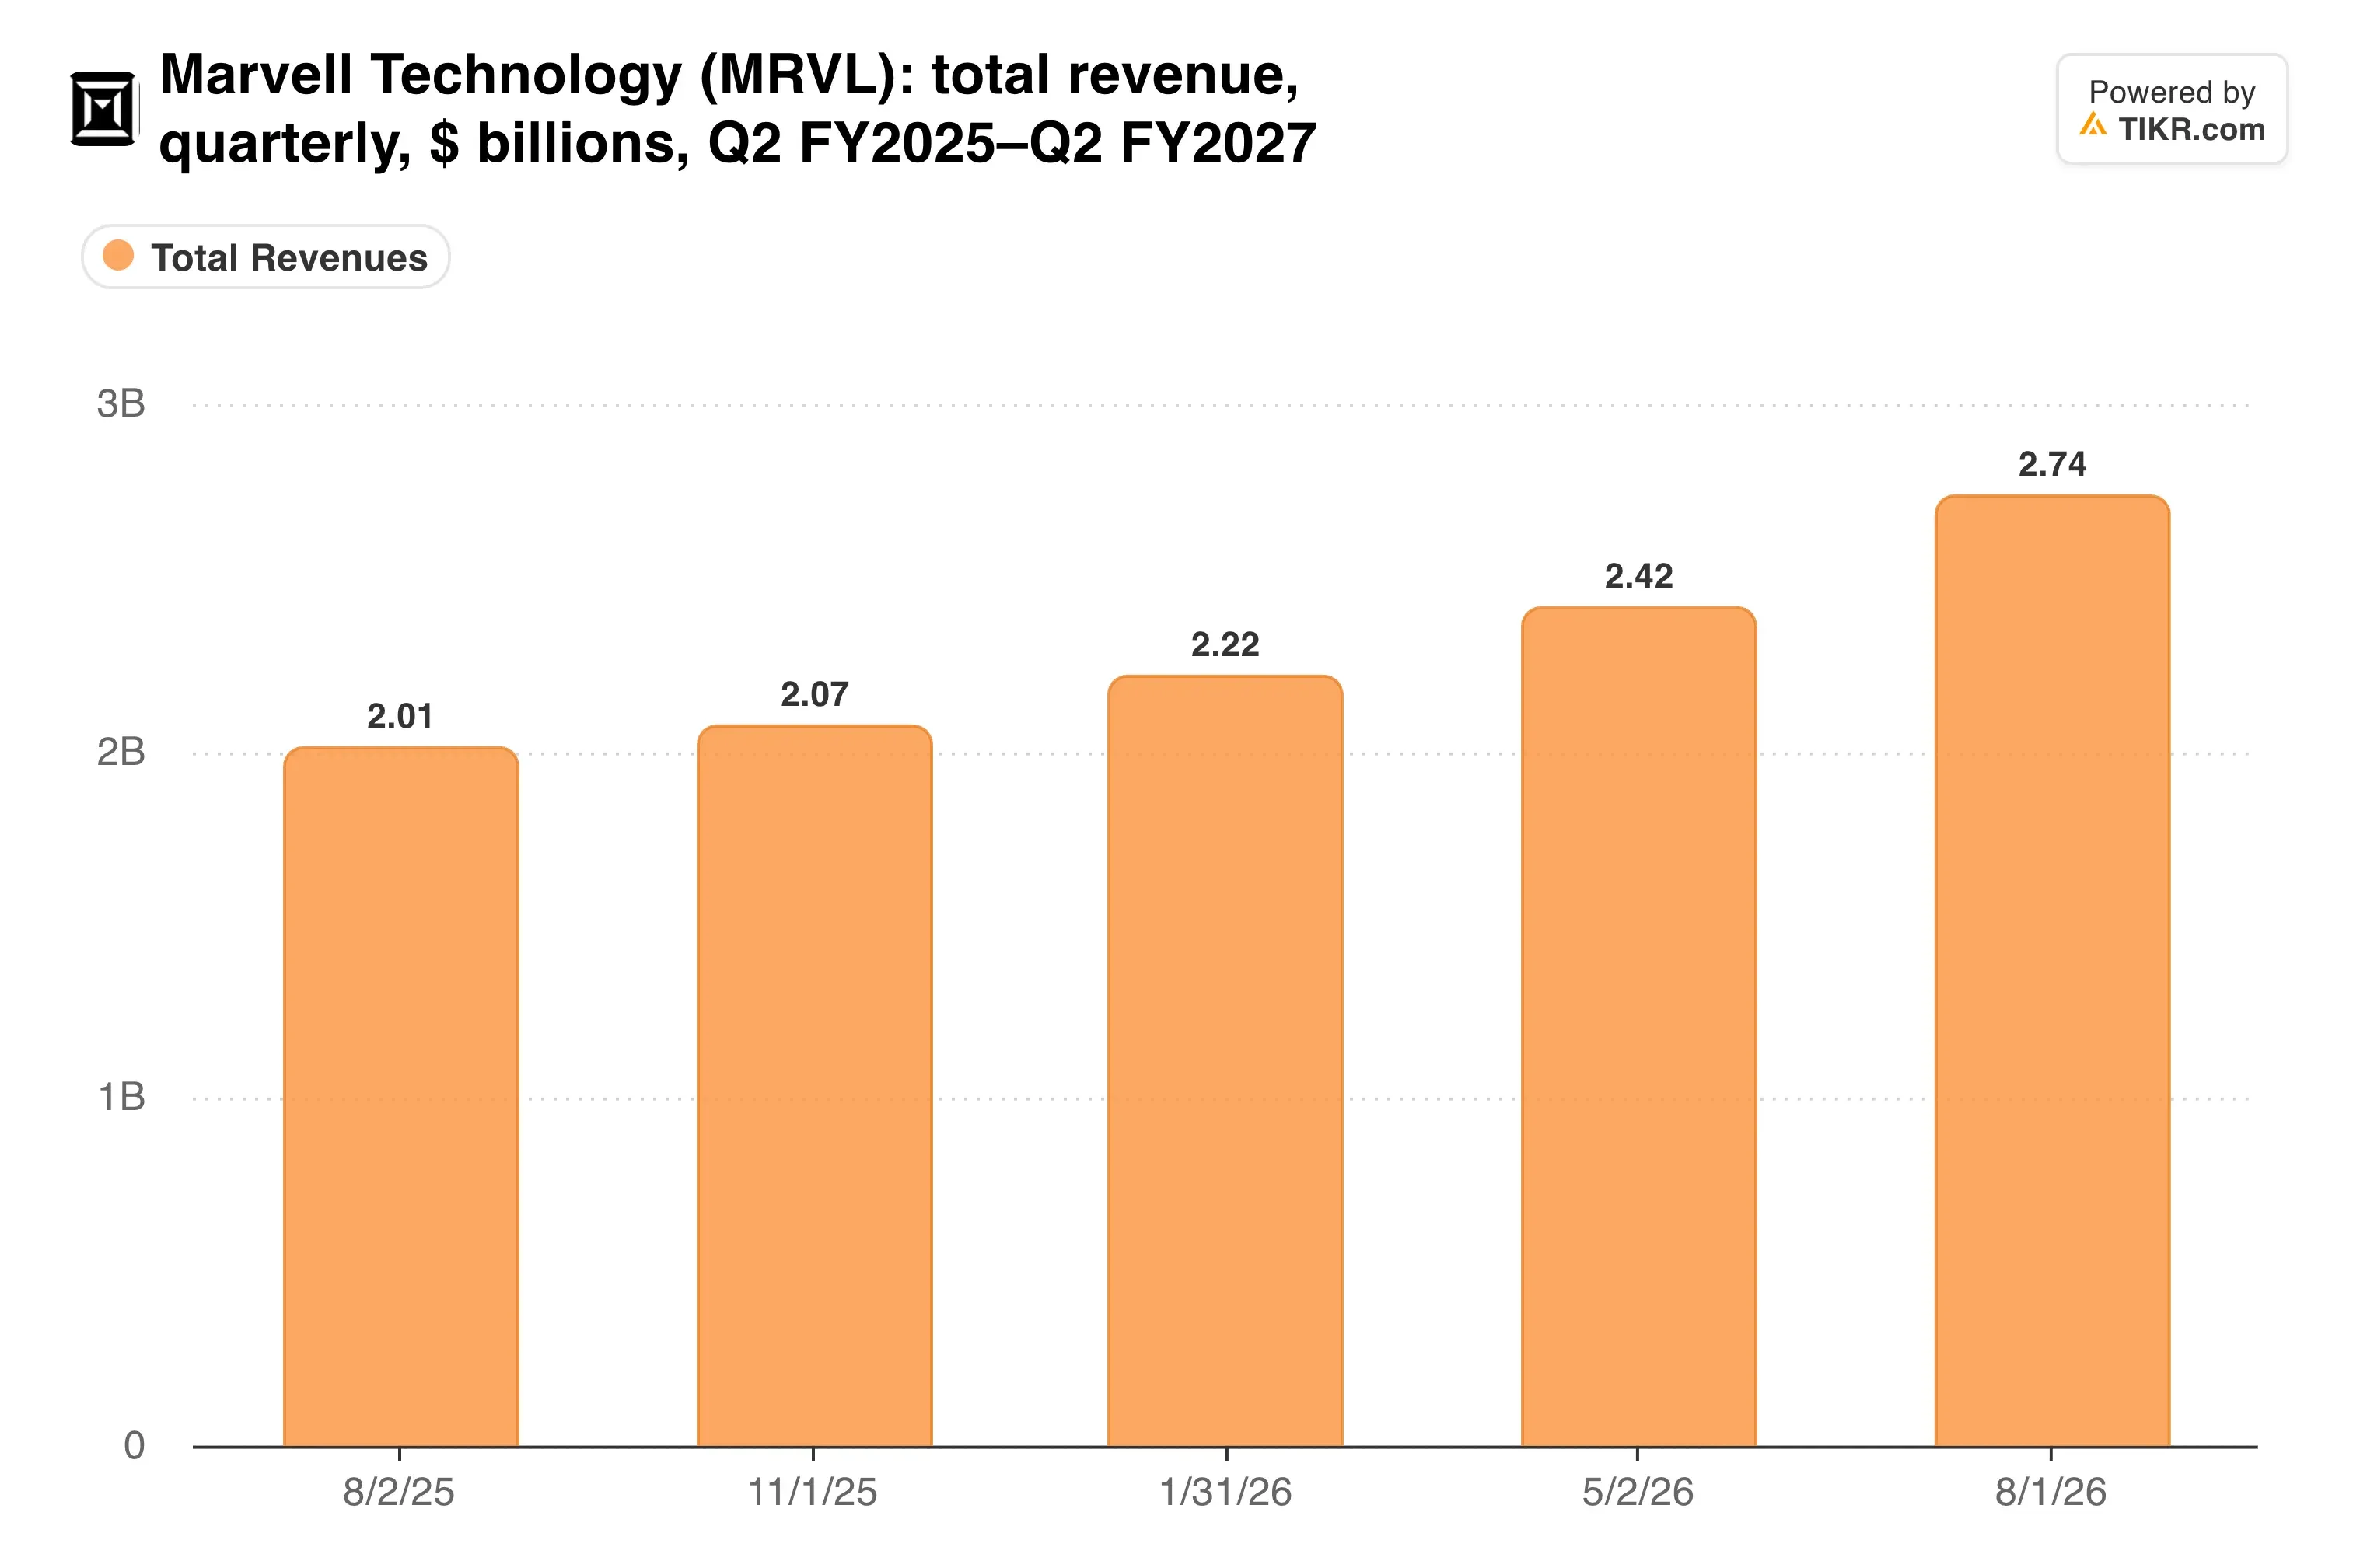
Growth has quickened every quarter this year. Management also raised its fiscal 2028 revenue outlook to about $18 billion, up from $16.5 billion a quarter earlier. On Fox Business, Murphy pegged the two companies at a combined $21 billion annualized run rate, with operating margins above 40%.
TIKR tracks 46 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
December 1 sets the tone
Murphy has blamed the selloff on a risk-off market. Yet he also conceded the bet’s cost in that interview: “you take more risk when you do it, and sometimes being unorthodox is what you have to do in order to get the outsized return.”
Margins are the next pressure point. Marvell guided to a non-GAAP gross margin of 57.5% to 58.5% for the October quarter. Lumentum, by contrast, guided its December quarter to about 53% on revenue of $1.6 billion, Hurlston said.
Here’s where the two companies’ margins stand side by side:
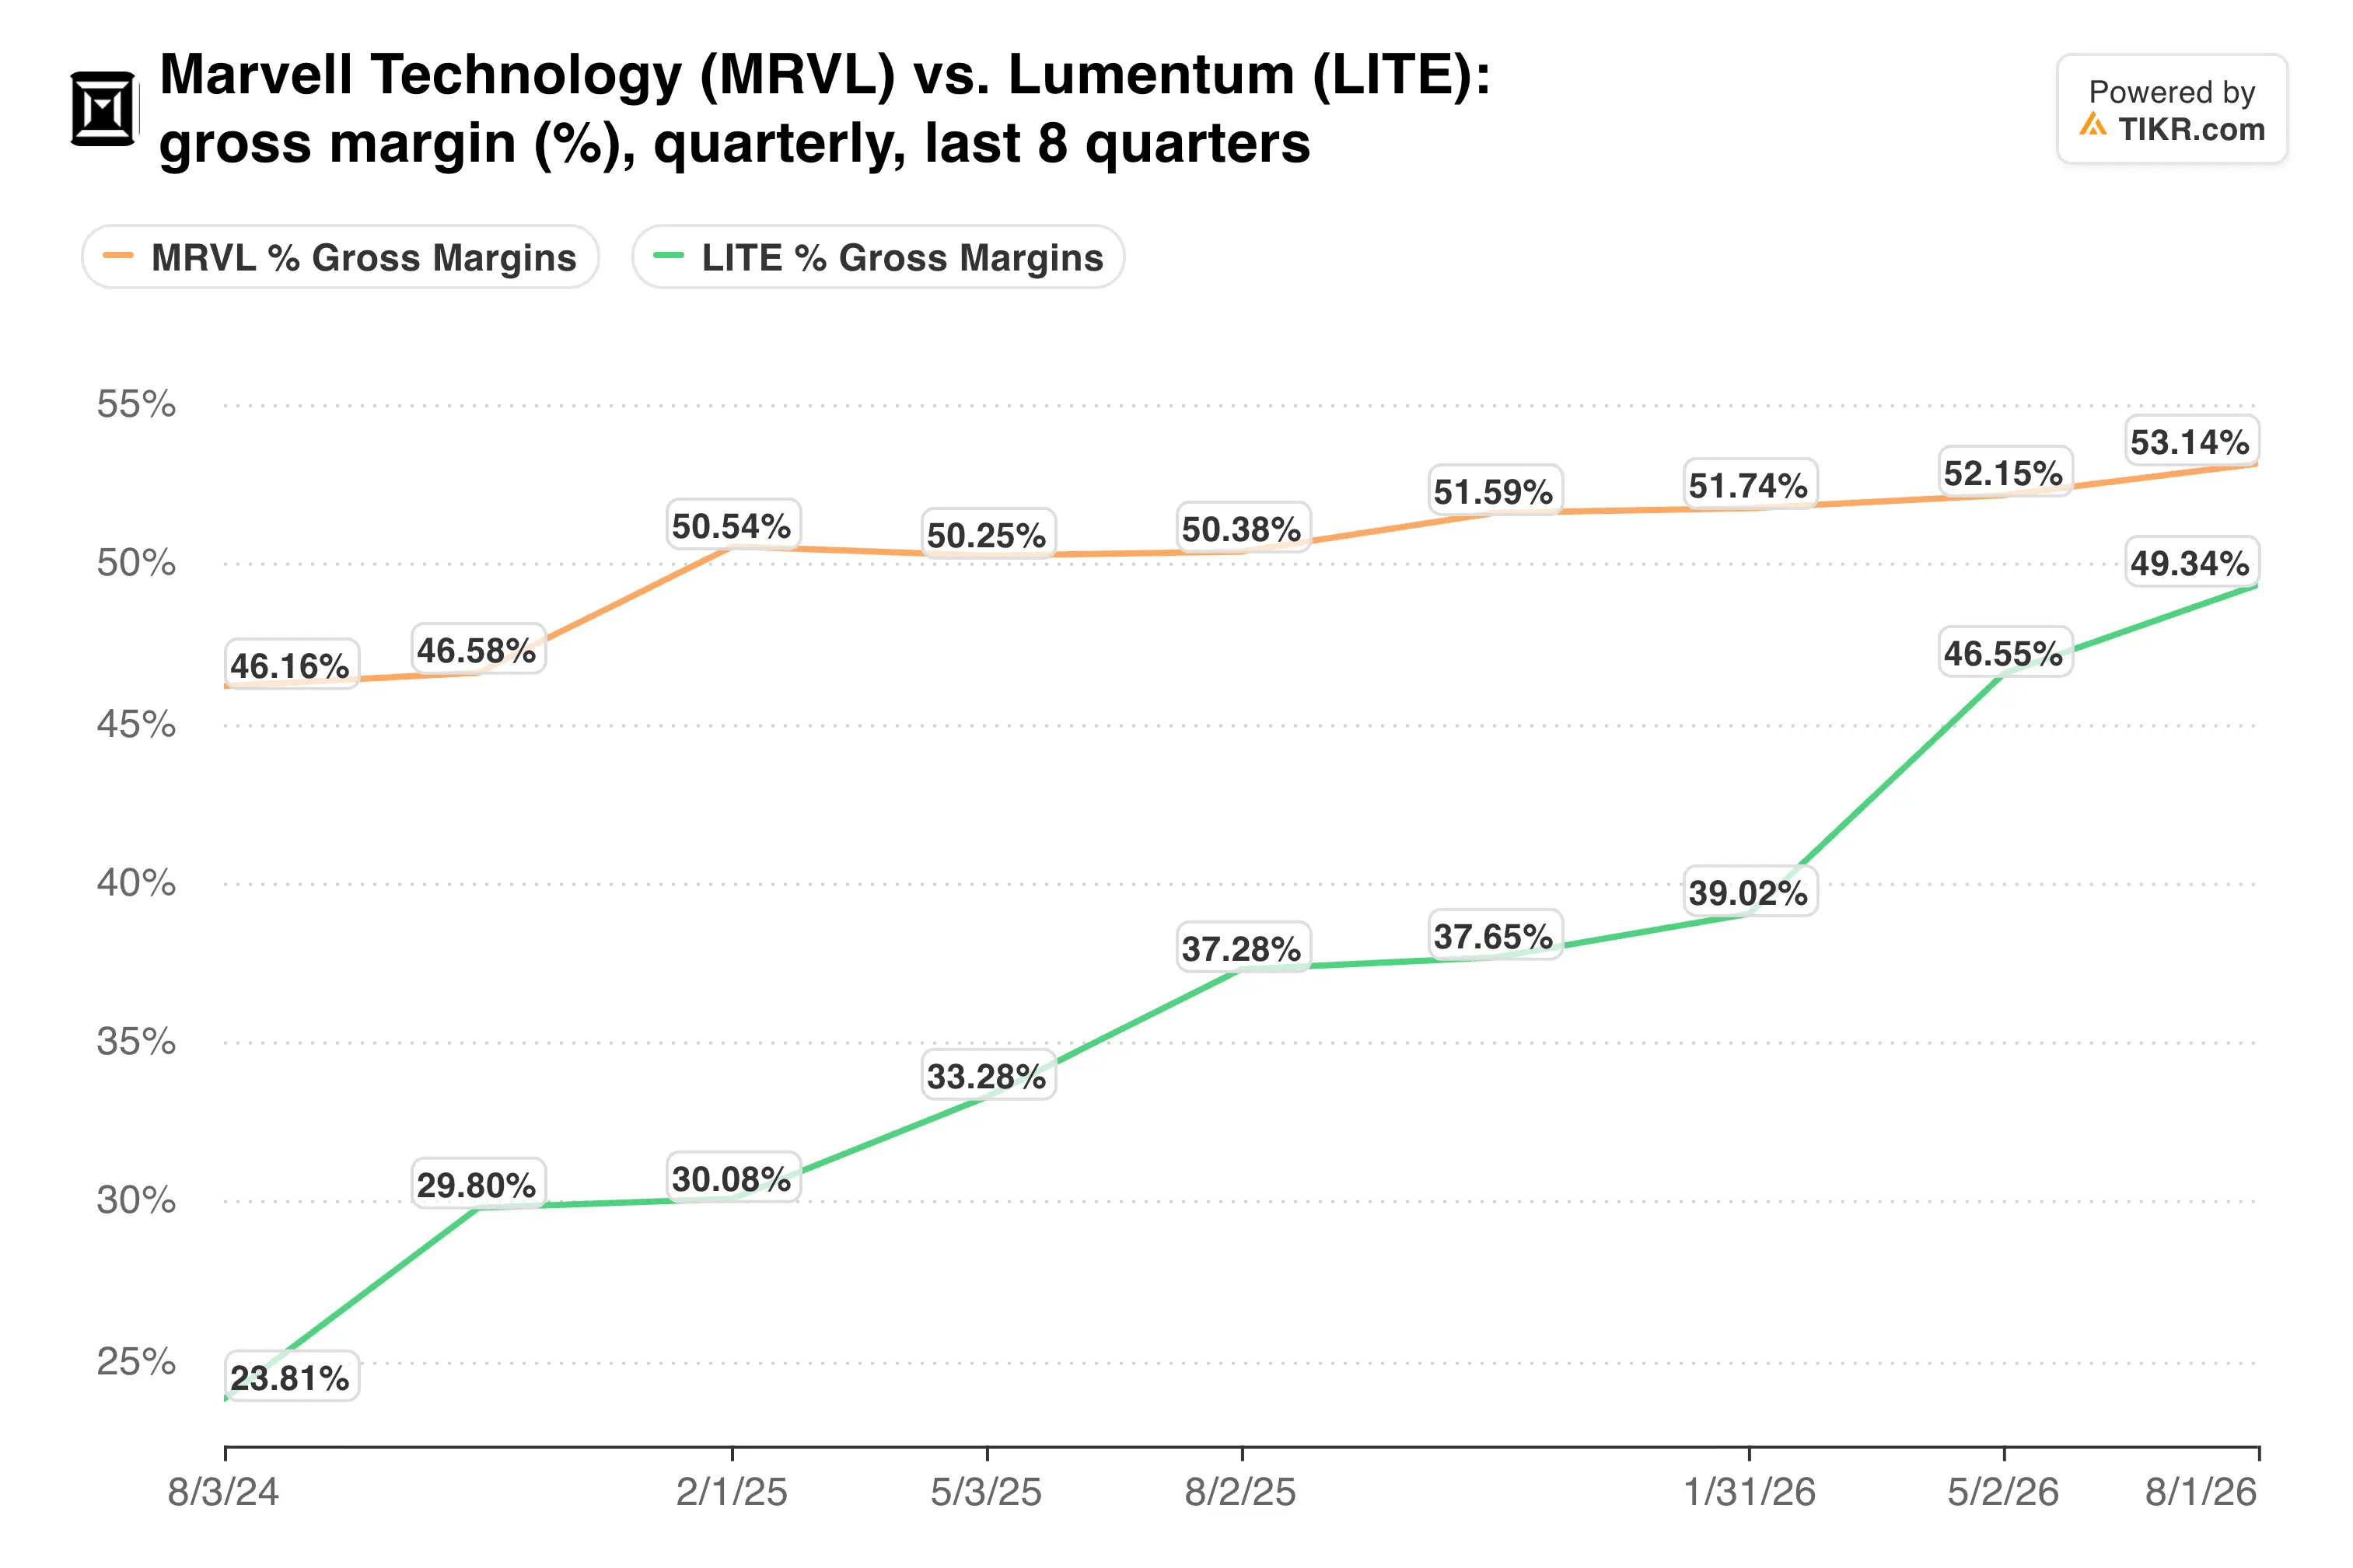
Lumentum’s margins have improved quickly, but they still trail Marvell’s. That gap is where the $1 billion synergy target has to earn its keep.
My take: The strategy is sound, because AI connectivity is moving toward optics and owning the lasers makes sense. Still, Marvell holders are handing over a third of a fast-growing company for gains that mostly land after 2028. I’d want a clean quarter before adding.
On December 1, watch the fourth-quarter revenue guide and any change to the $18 billion fiscal 2028 target. A raise would argue the standalone business can carry the long wait for closing.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!