Key Takeaways
- Josh Brown says Netflix can easily beat Wall Street’s 2027 revenue growth estimate, which sits below the 13% growth Netflix guides for 2026.
- At about 17x forward earnings, Netflix trades at roughly half its five-year average multiple, about Disney’s.
- Netflix’s revenue growth has slowed every quarter this year, and its 2026 earnings include a one-time $2.8 billion break-up fee from Warner Bros. Discovery.
- The growth bar looks easy to clear. The bigger risk is a rumored Netflix bid for Comcast’s NBCUniversal, and January’s 2027 guidance is the next test.
Netflix (NFLX) is nearly 50% below its high from a year ago. Josh Brown, CEO of Ritholtz Wealth Management, just bought more shares, and he told CNBC’s Halftime Report on Wednesday that Wall Street isn’t asking much of Netflix next year:
“Consensus is 10.6% revenue growth, which I think they can do standing on their head.”
Nor is the stock priced for much. On forward earnings, Netflix trades close to Walt Disney (DIS), at 16x, and well above Comcast (CMCSA), which owns Universal along with its cable business, at 7.4x.
Netflix is already growing faster than that
Netflix guides 2026 revenue to a record $51.1 billion, up 13%. Analysts expect $56.6 billion in 2027, which is growth of 10.8% on TIKR’s consensus, close to Brown’s figure. Growth slows again in 2028 on these estimates:
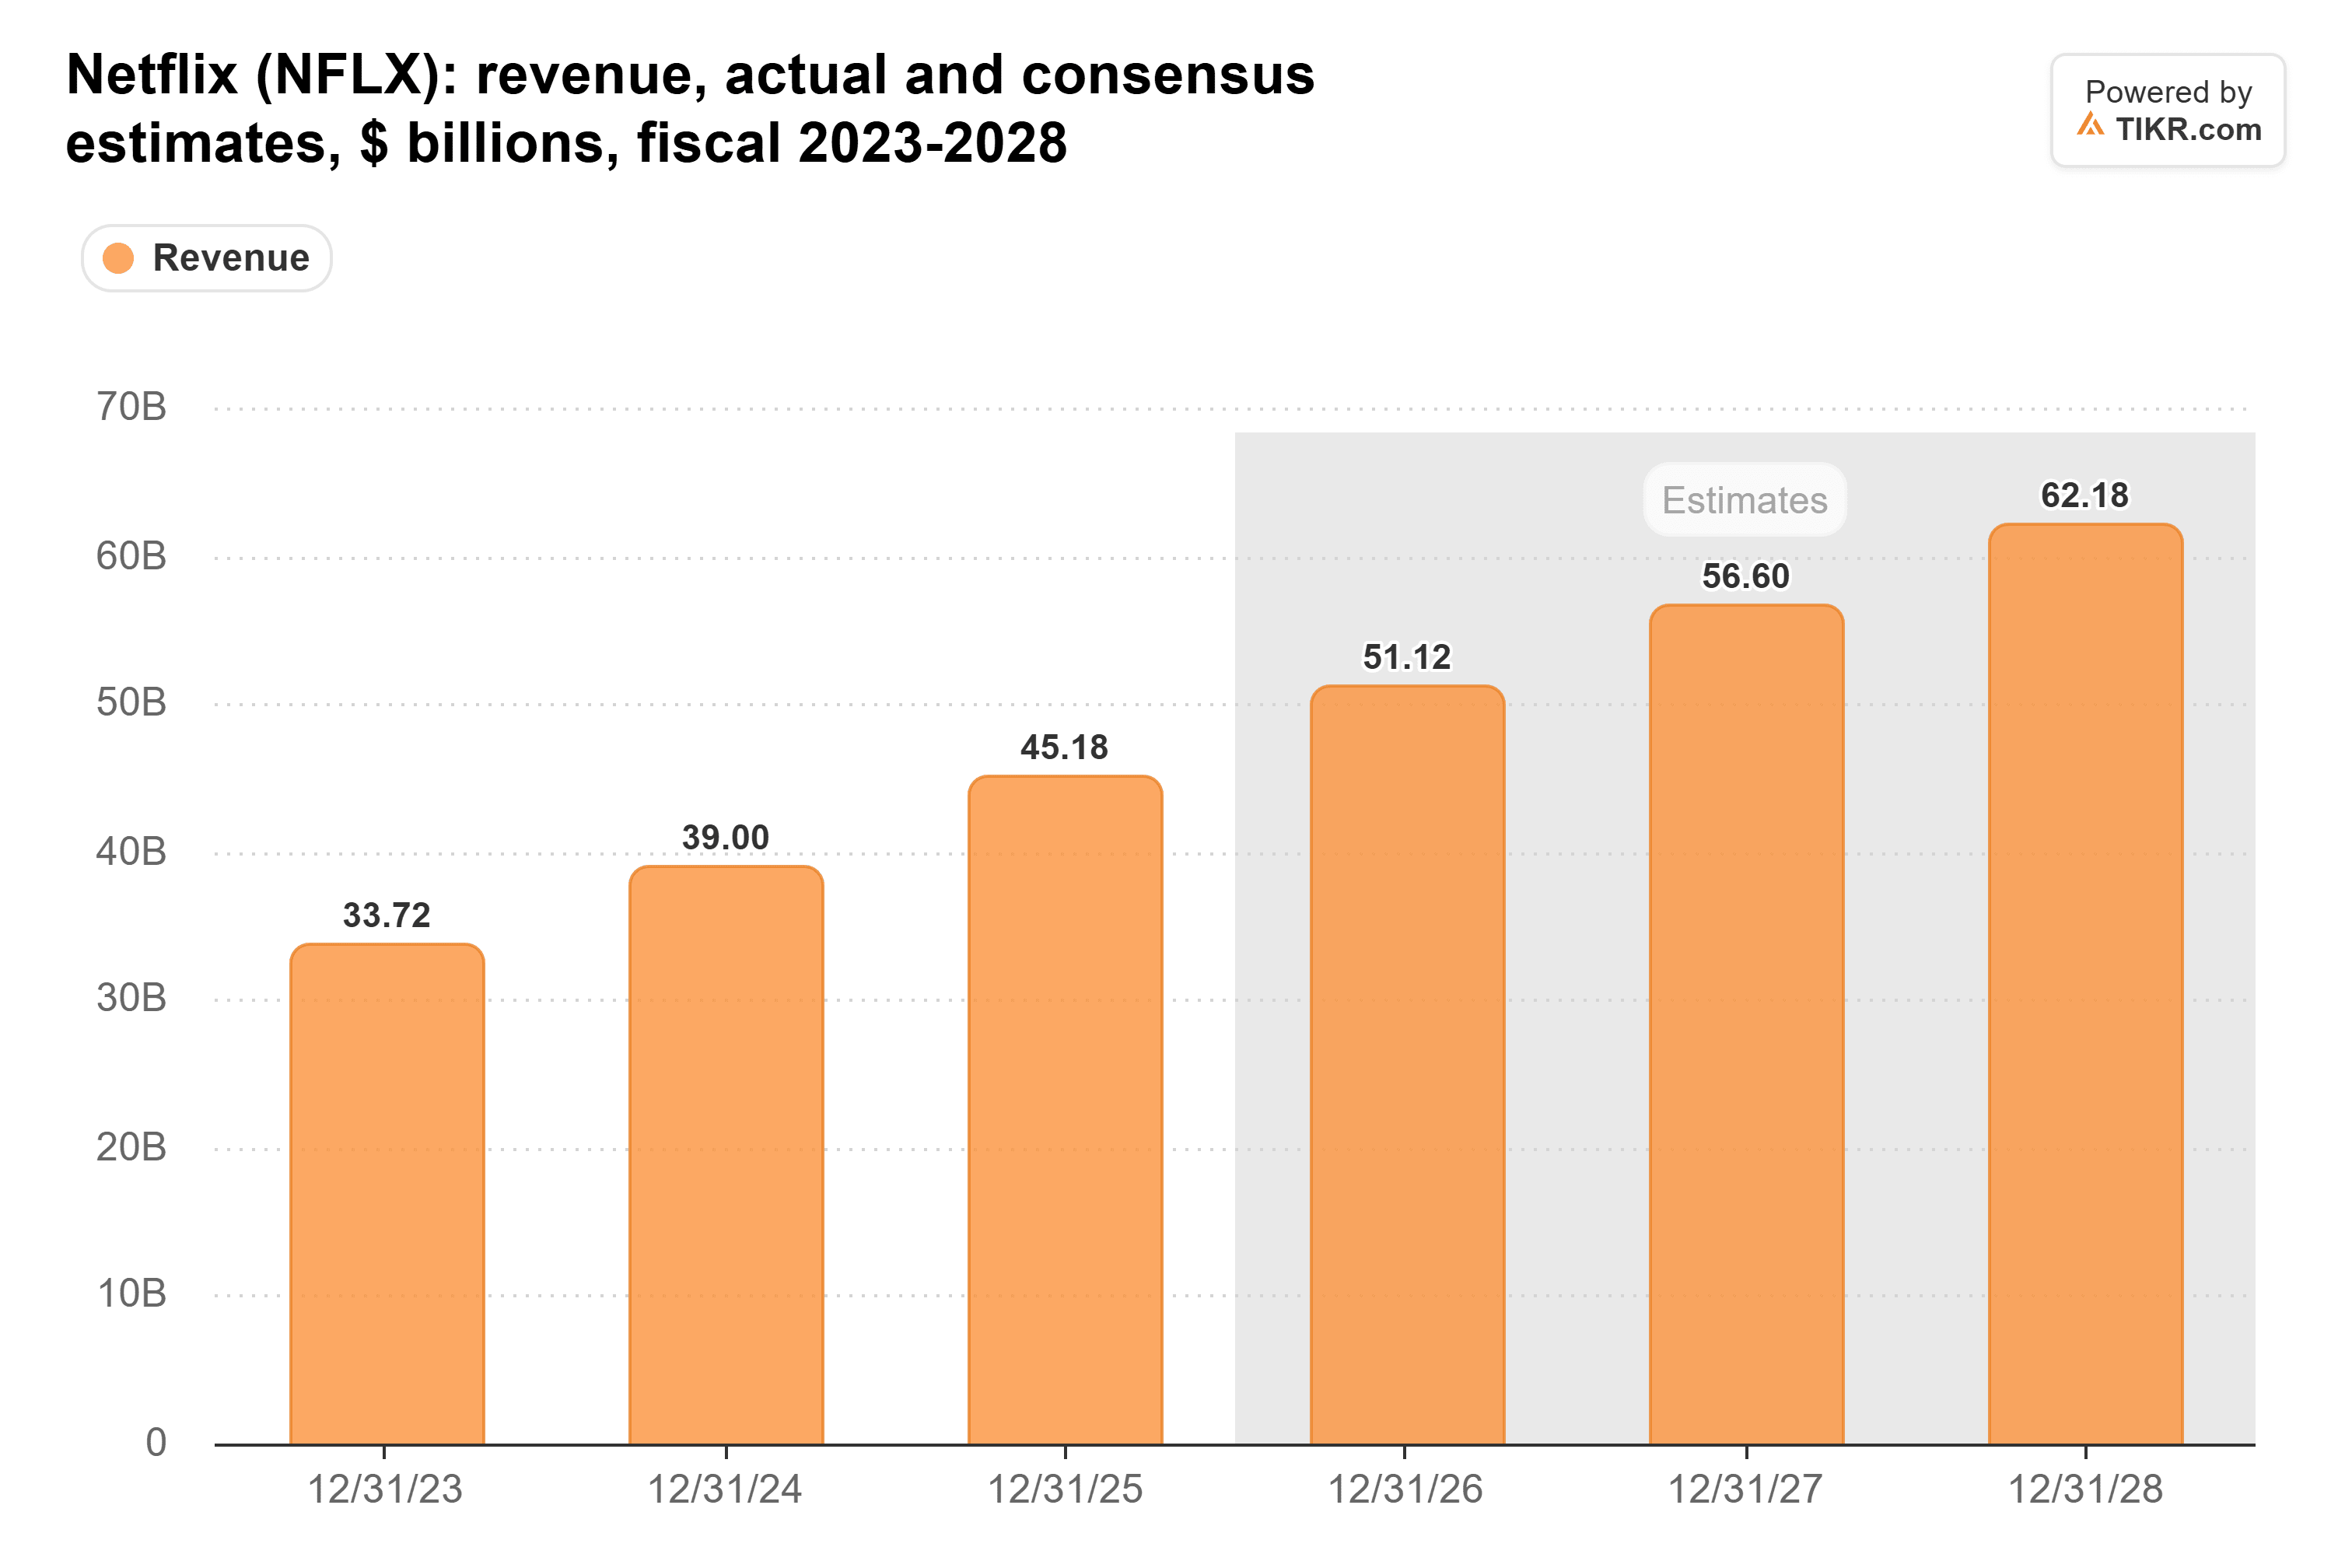
Netflix’s slowest quarter this year already clears that bar: it guides fourth-quarter revenue up 11.5%. Brown also pointed to live events, from NFL games to the Women’s World Cup next summer, calling them “the most reliable ad inventory.” Netflix’s ad plan also launches in 12 more countries in March.
The earnings bar looks even lower. TIKR’s consensus has 2027 EPS up just 5.7%, to $3.77. But that’s because 2026’s $3.57 includes the $2.8 billion break-up fee Netflix collected from Warner Bros. Discovery. Operating income doesn’t count the fee, and analysts expect it to rise 17% in 2027, to $18.9 billion.
TIKR tracks 51 analysts on Netflix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
A Disney price for a better streaming business
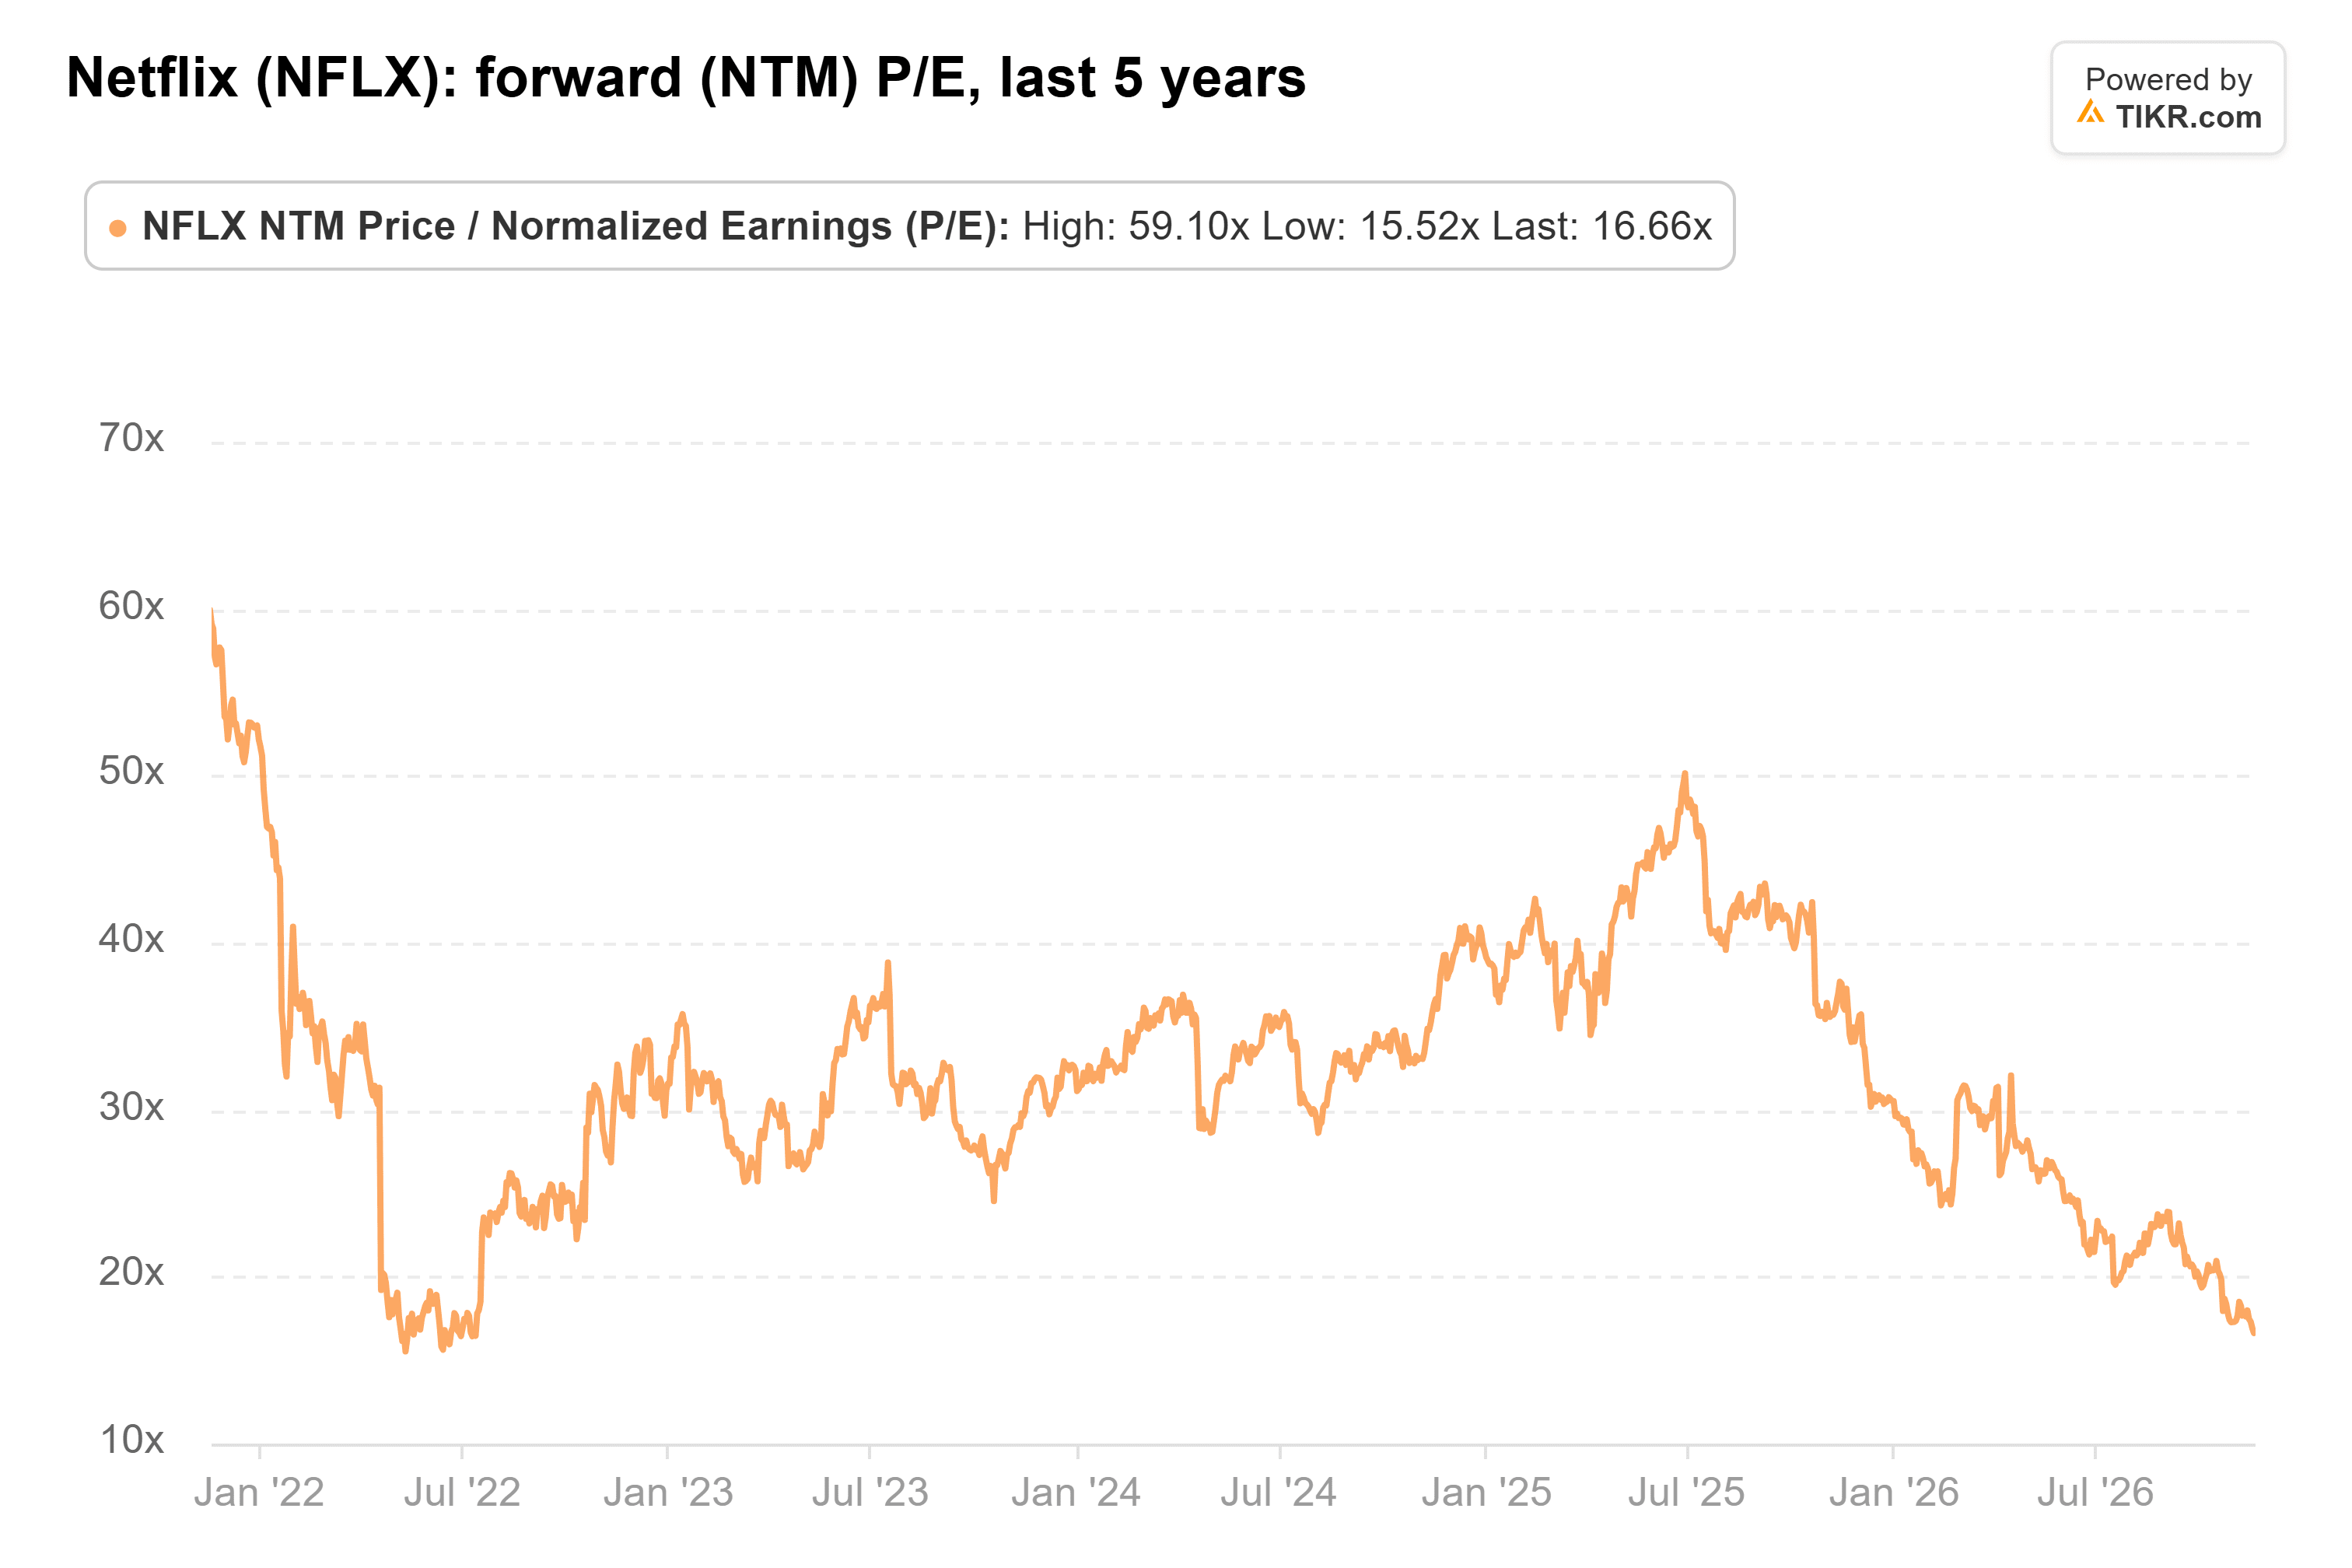
The stock price gives Netflix almost no credit for that. Netflix trades at 17x forward earnings, about half its five-year average of 32x and barely above its May 2022 low of 16x:
The cash is real. Free cash flow reached $9.5 billion in 2025, and Netflix guides to about $12 billion this year:
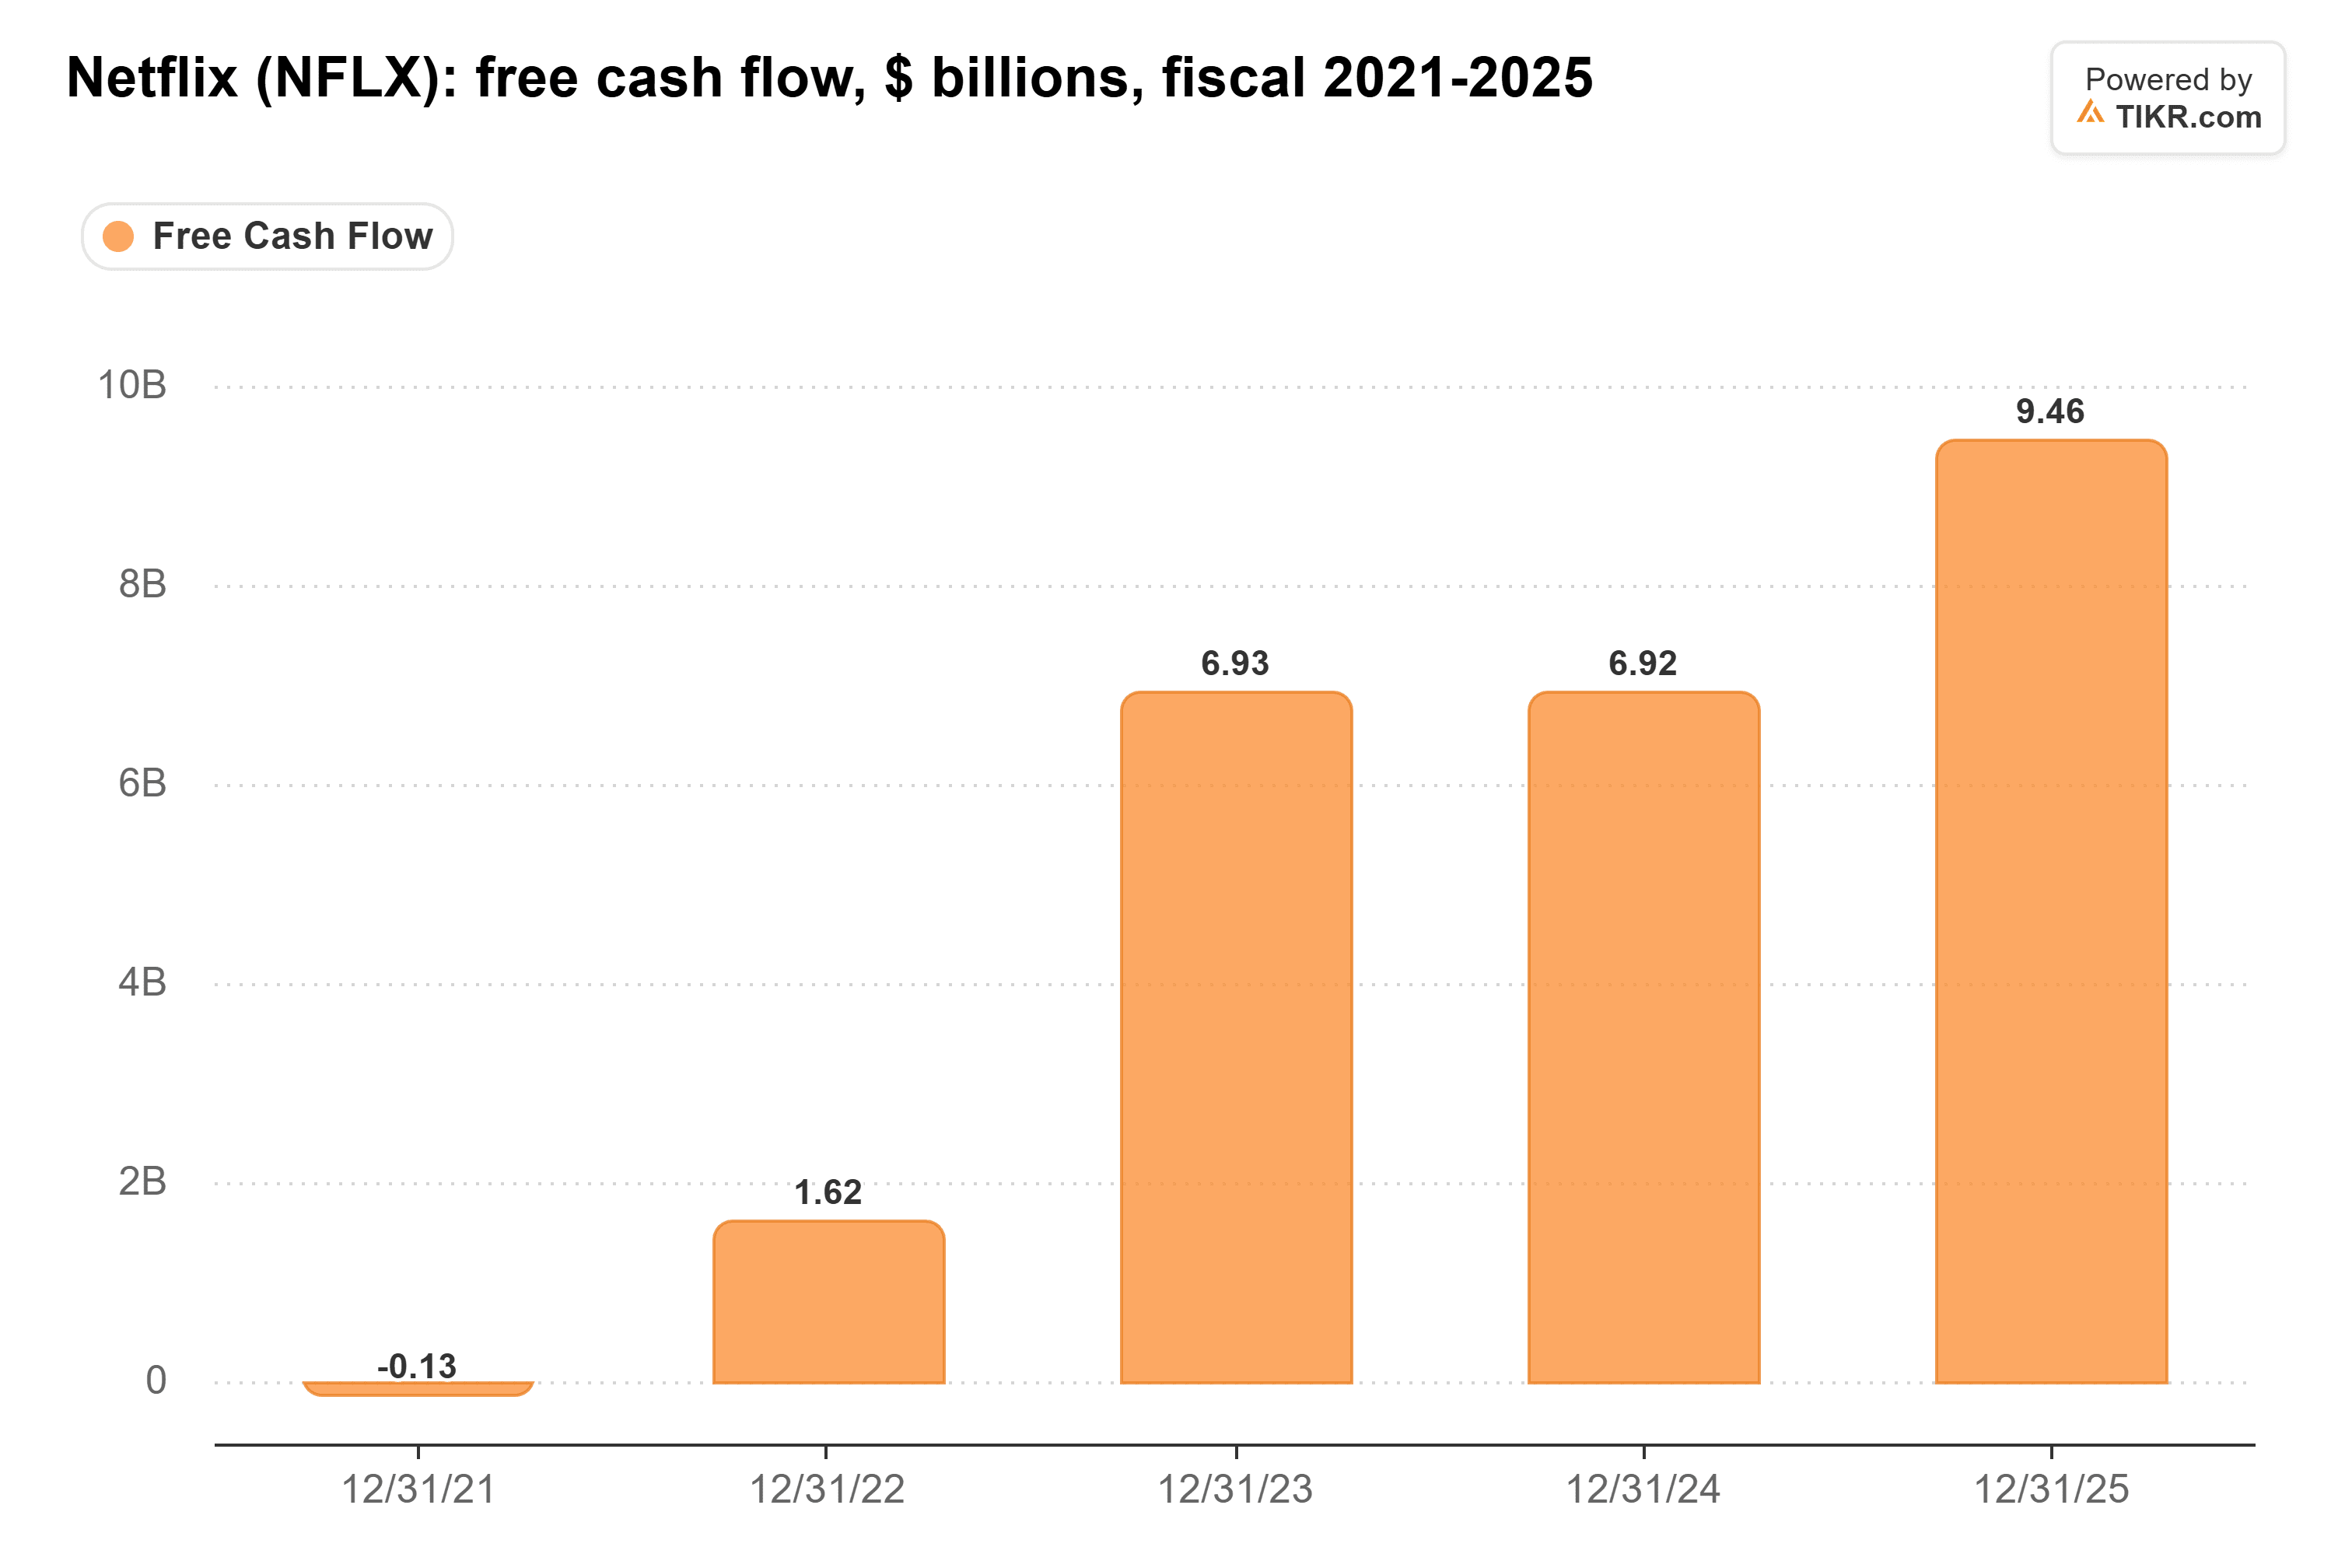
Disney’s revenue grew 8% in fiscal 2026, helped by an extra week in the year, and its Disney+ and Hulu subscription business earned an 11.5% operating margin. Netflix guides to a 31.5% operating margin for 2026, nearly 3x Disney’s streaming margin, on faster growth.
Slowing growth, and a wildcard
Netflix’s revenue growth has slowed every quarter, from 17.6% in the fourth quarter of 2025 to 11.8% in the third quarter of 2026. In October, management also cut its 2026 ad forecast to about $2.7 billion from about $3 billion. The fourth-quarter guide suggests it’s leveling off, but it hasn’t stopped yet.
Brown named the bigger wildcard himself: Hollywood rumors of a Netflix bid for NBC and Universal Studios, the heart of Comcast’s NBCUniversal. Comcast says it’s on track to split NBCUniversal and Sky off into a separate company, which would put those assets in play. Netflix’s last big studio deal, for Warner Bros. Discovery, fell apart in February. On a second try, Brown admitted: “I don’t know what that will do to the stock.”
The bar is the easy part
Brown has this right: Netflix shouldn’t struggle to clear 10.8% next year. At 17x, the market is paying Disney’s price for a faster, more profitable streamer. The bigger risk is what Netflix does with its cash.
Netflix should report fourth-quarter results in mid-January. A 2027 revenue guide of at least $56.6 billion would clear Brown’s bar. A guide under 10% growth, or a formal bid for NBCUniversal, would change the story.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!