Key Takeaways
- Starbucks’ adjusted EPS jumped 54% to $0.80 in its fiscal fourth quarter, and Jim Cramer said on Mad Money that he thinks the stock “goes to 125,” 19% above Friday’s close.
- Earnings have recovered only about half of their fiscal 2025 drop, and analysts don’t expect them to pass fiscal 2024’s level until fiscal 2028.
- At the stock’s five-year average forward P/E of 29x, $125 would take EPS of about $4.30, above management’s fiscal 2028 range.
- $125 is about 33.5x fiscal 2028 estimates, against 28x at today’s price, so it needs a higher multiple or earnings above management’s range.
Starbucks (SBUX) just reported a 54% jump in adjusted earnings per share, and Jim Cramer thinks the stock has plenty of room left to run.
On Wednesday’s Mad Money, a caller asked whether Brian Niccol had Starbucks headed for an all-time high. Starbucks rose 5% that day as restaurant stocks rallied on McDonald’s earnings beat. Cramer called it “a real good cup of coffee and a great place to go with a turnaround agent at the helm,” then gave his number: “I think the stock goes to 125.”
That’s 19% above Friday’s $105.41 close. Cramer didn’t say when, so the useful question is what Starbucks would need to earn to get there.
Earnings Are Only Halfway Back
The fourth quarter, to Sept. 27, was strong. Adjusted EPS of $0.80 beat the $0.73 expected, U.S. comparable sales rose 7.7%, and the adjusted operating margin climbed 4.6 points to 14.0%. For fiscal 2026, adjusted EPS rose 28% to $2.72.
But that comes off a bad year. Normalized EPS fell from $3.31 in fiscal 2024 to $2.13 in fiscal 2025, so fiscal 2026 made up about half the drop. Analysts expect $3.22 in fiscal 2027 and $3.73 in fiscal 2028, the first year above fiscal 2024:
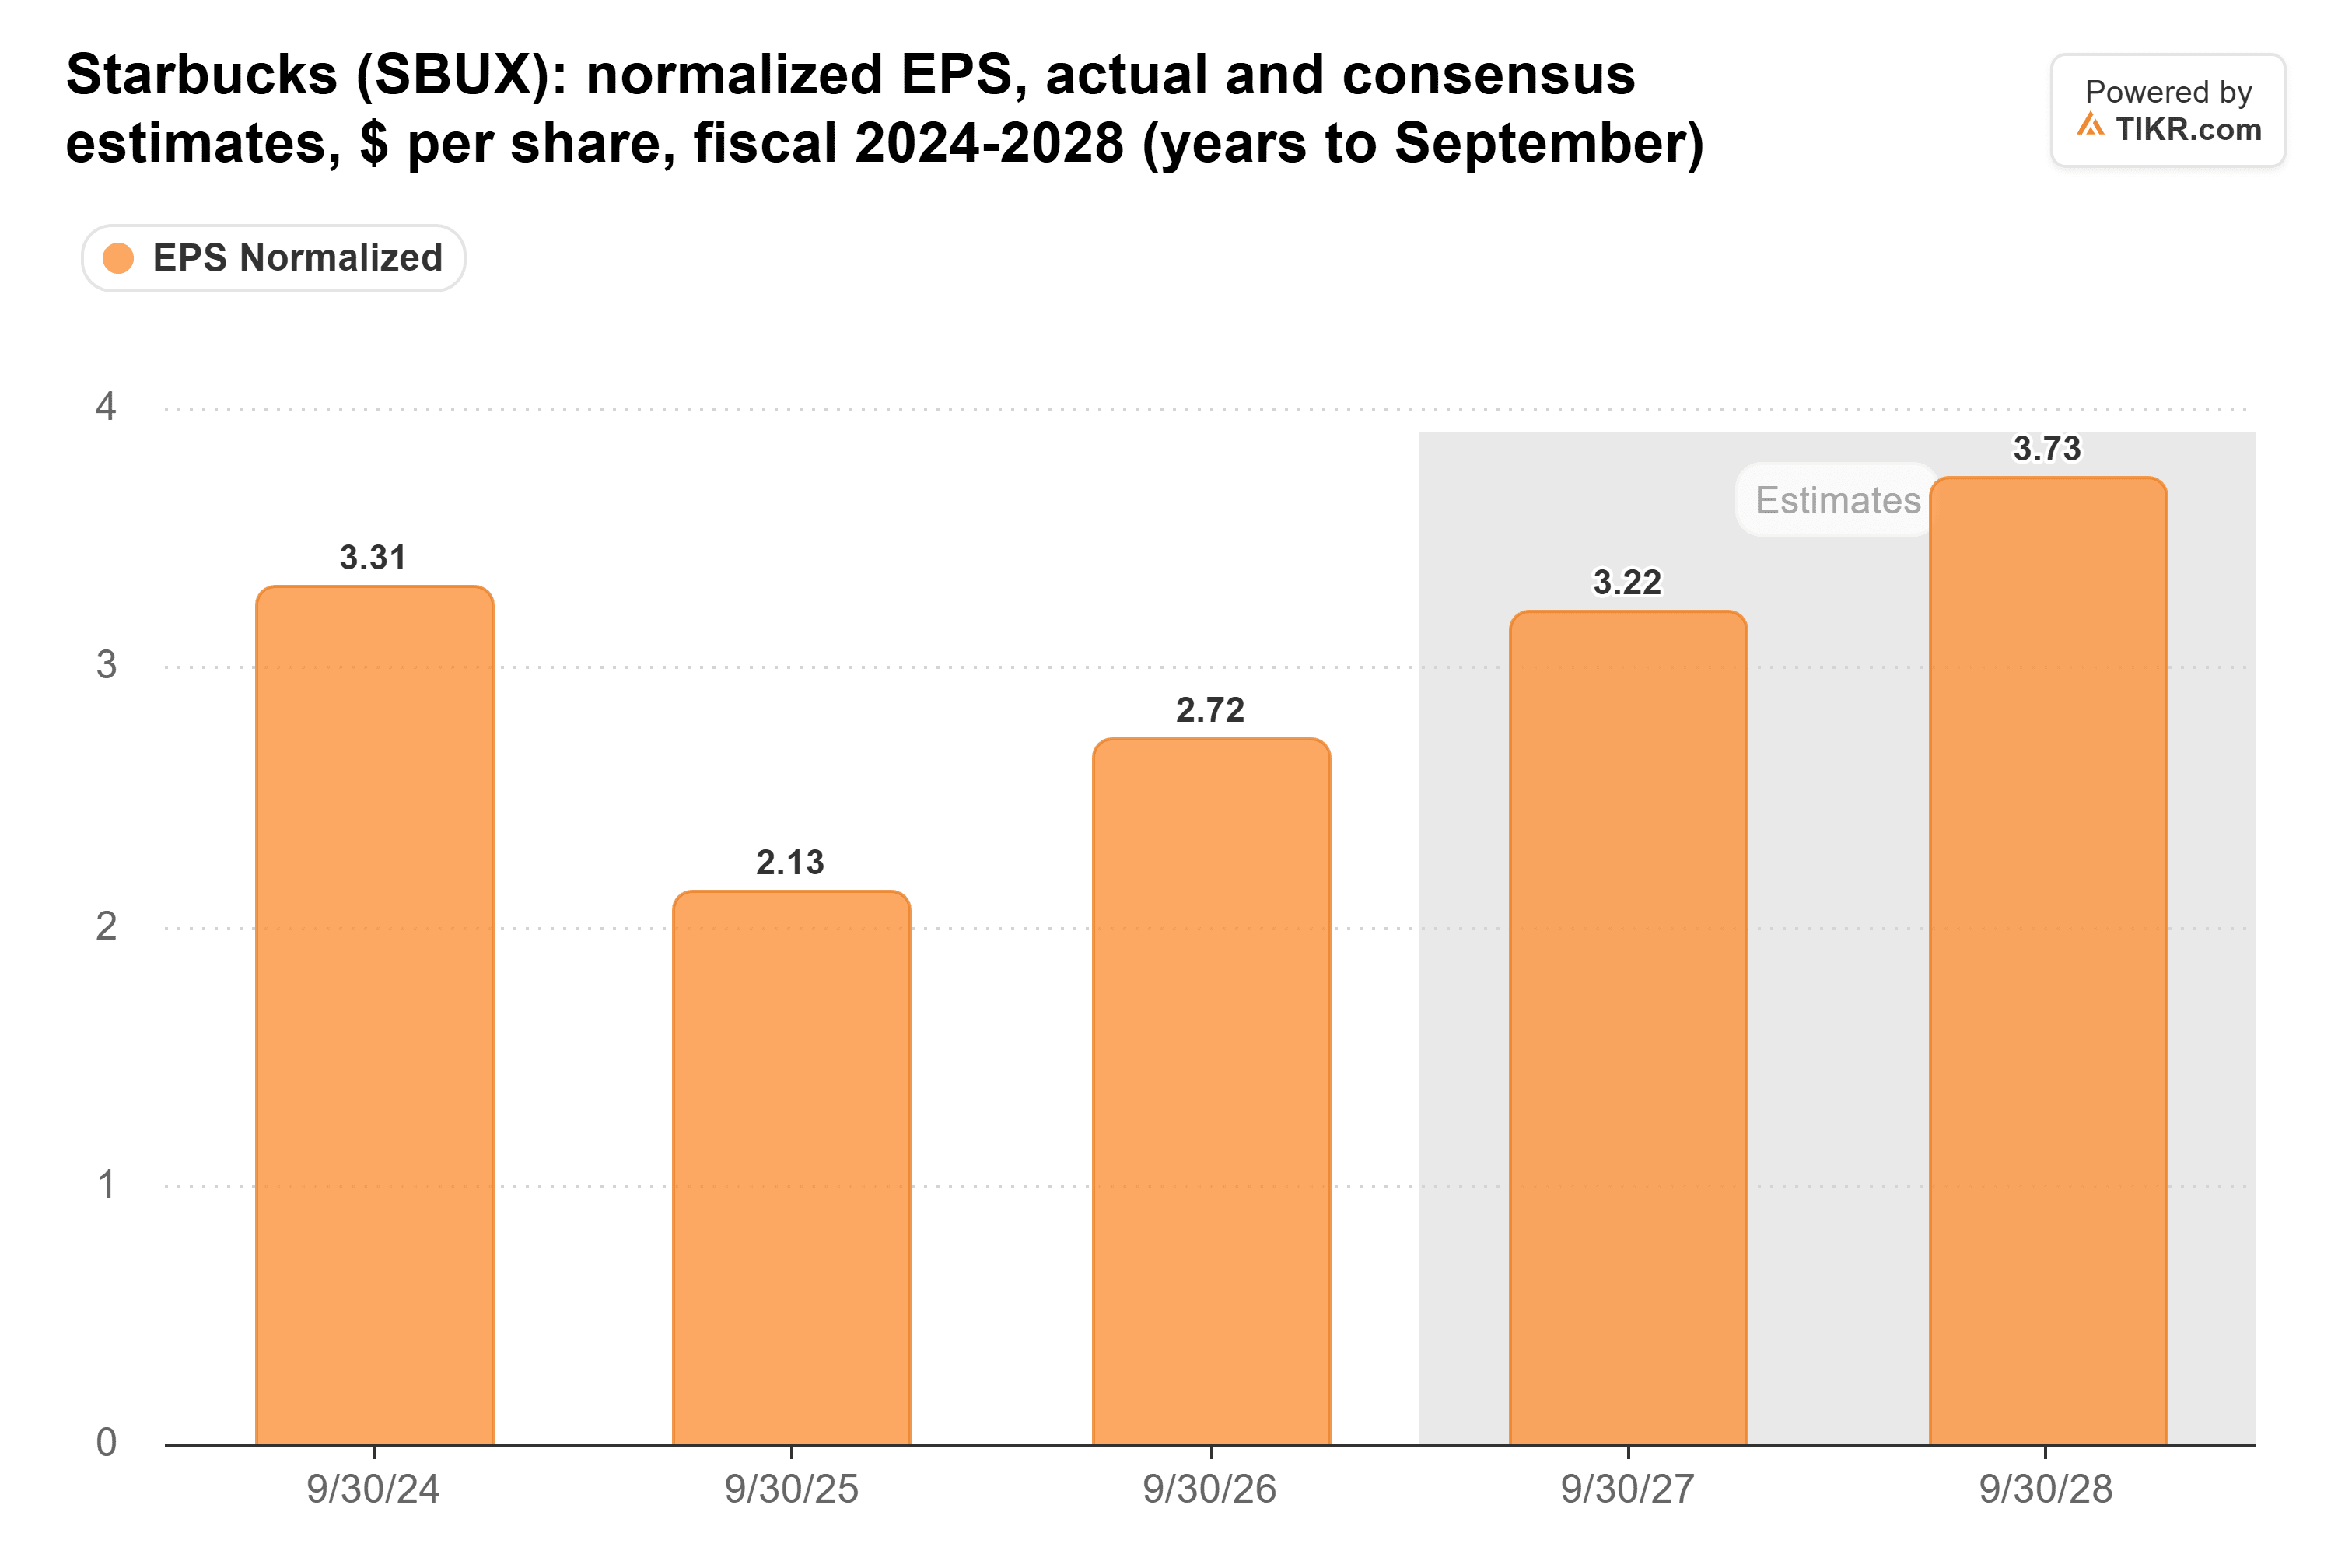
The fiscal 2027 figure is flattered by a 53rd week worth slightly more than $0.10. Without it, growth is closer to 15% than 18%, and the estimate already sits above the midpoint of management’s $3.15-$3.25 guidance.
TIKR Tracks 35 Analysts on Starbucks. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Starbucks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Starbucks’ Analyst Ratings
What $125 Would Take
Starbucks trades at about 33x forward earnings, above its five-year average of 29x, though well below January’s 42x peak:
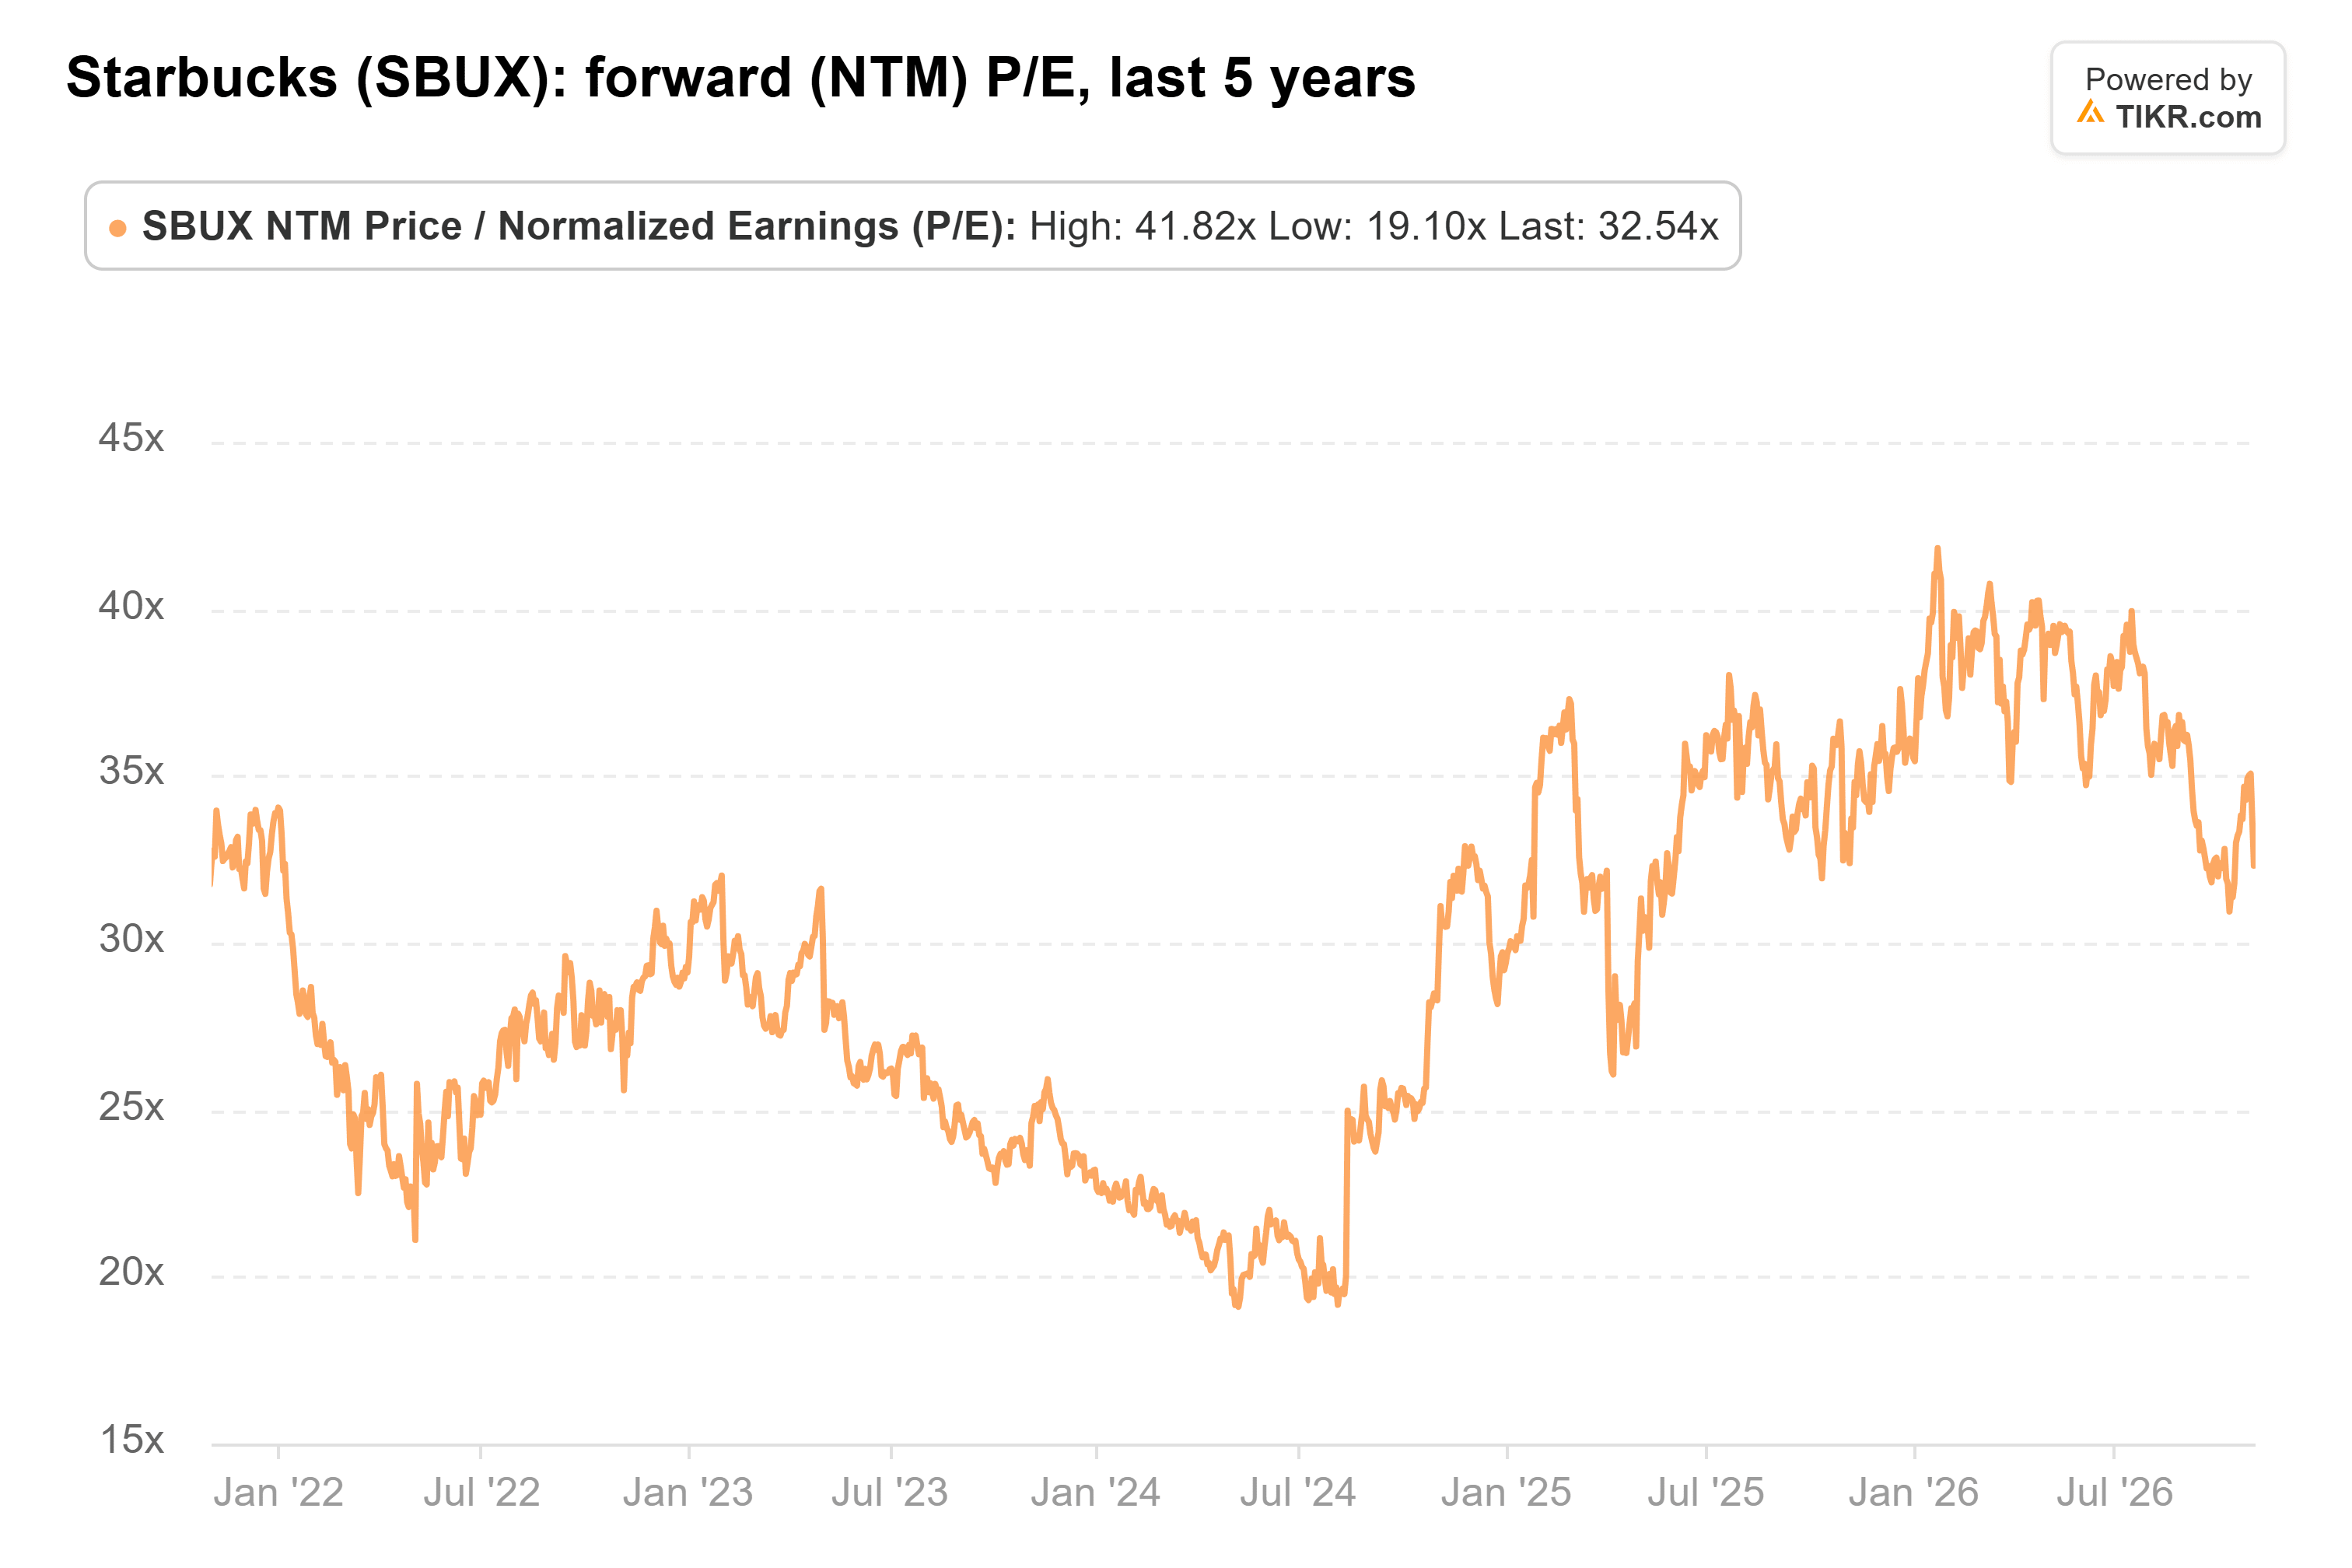
$125 works out to about 33.5x the $3.73 analysts expect for fiscal 2028, against 28x at today’s price. At the 29x average, $3.73 is worth about $108, and reaching $125 takes about $4.30 a share, above the top of the $3.35-$4.00 fiscal 2028 range management set in January. That range also came before the China joint venture, which Starbucks said would trim about $0.15 a share.
It Comes Down to Margins
Sales won’t do it. Starbucks guides fiscal 2027 revenue down about 1%, mostly because of the China change, even with roughly $700 million from the extra week.
Margins are moving the right way. EBIT margin, as TIKR measures it, climbed from 7.5% in the quarter to March 2025 to 12.8% in the quarter to September 2026:
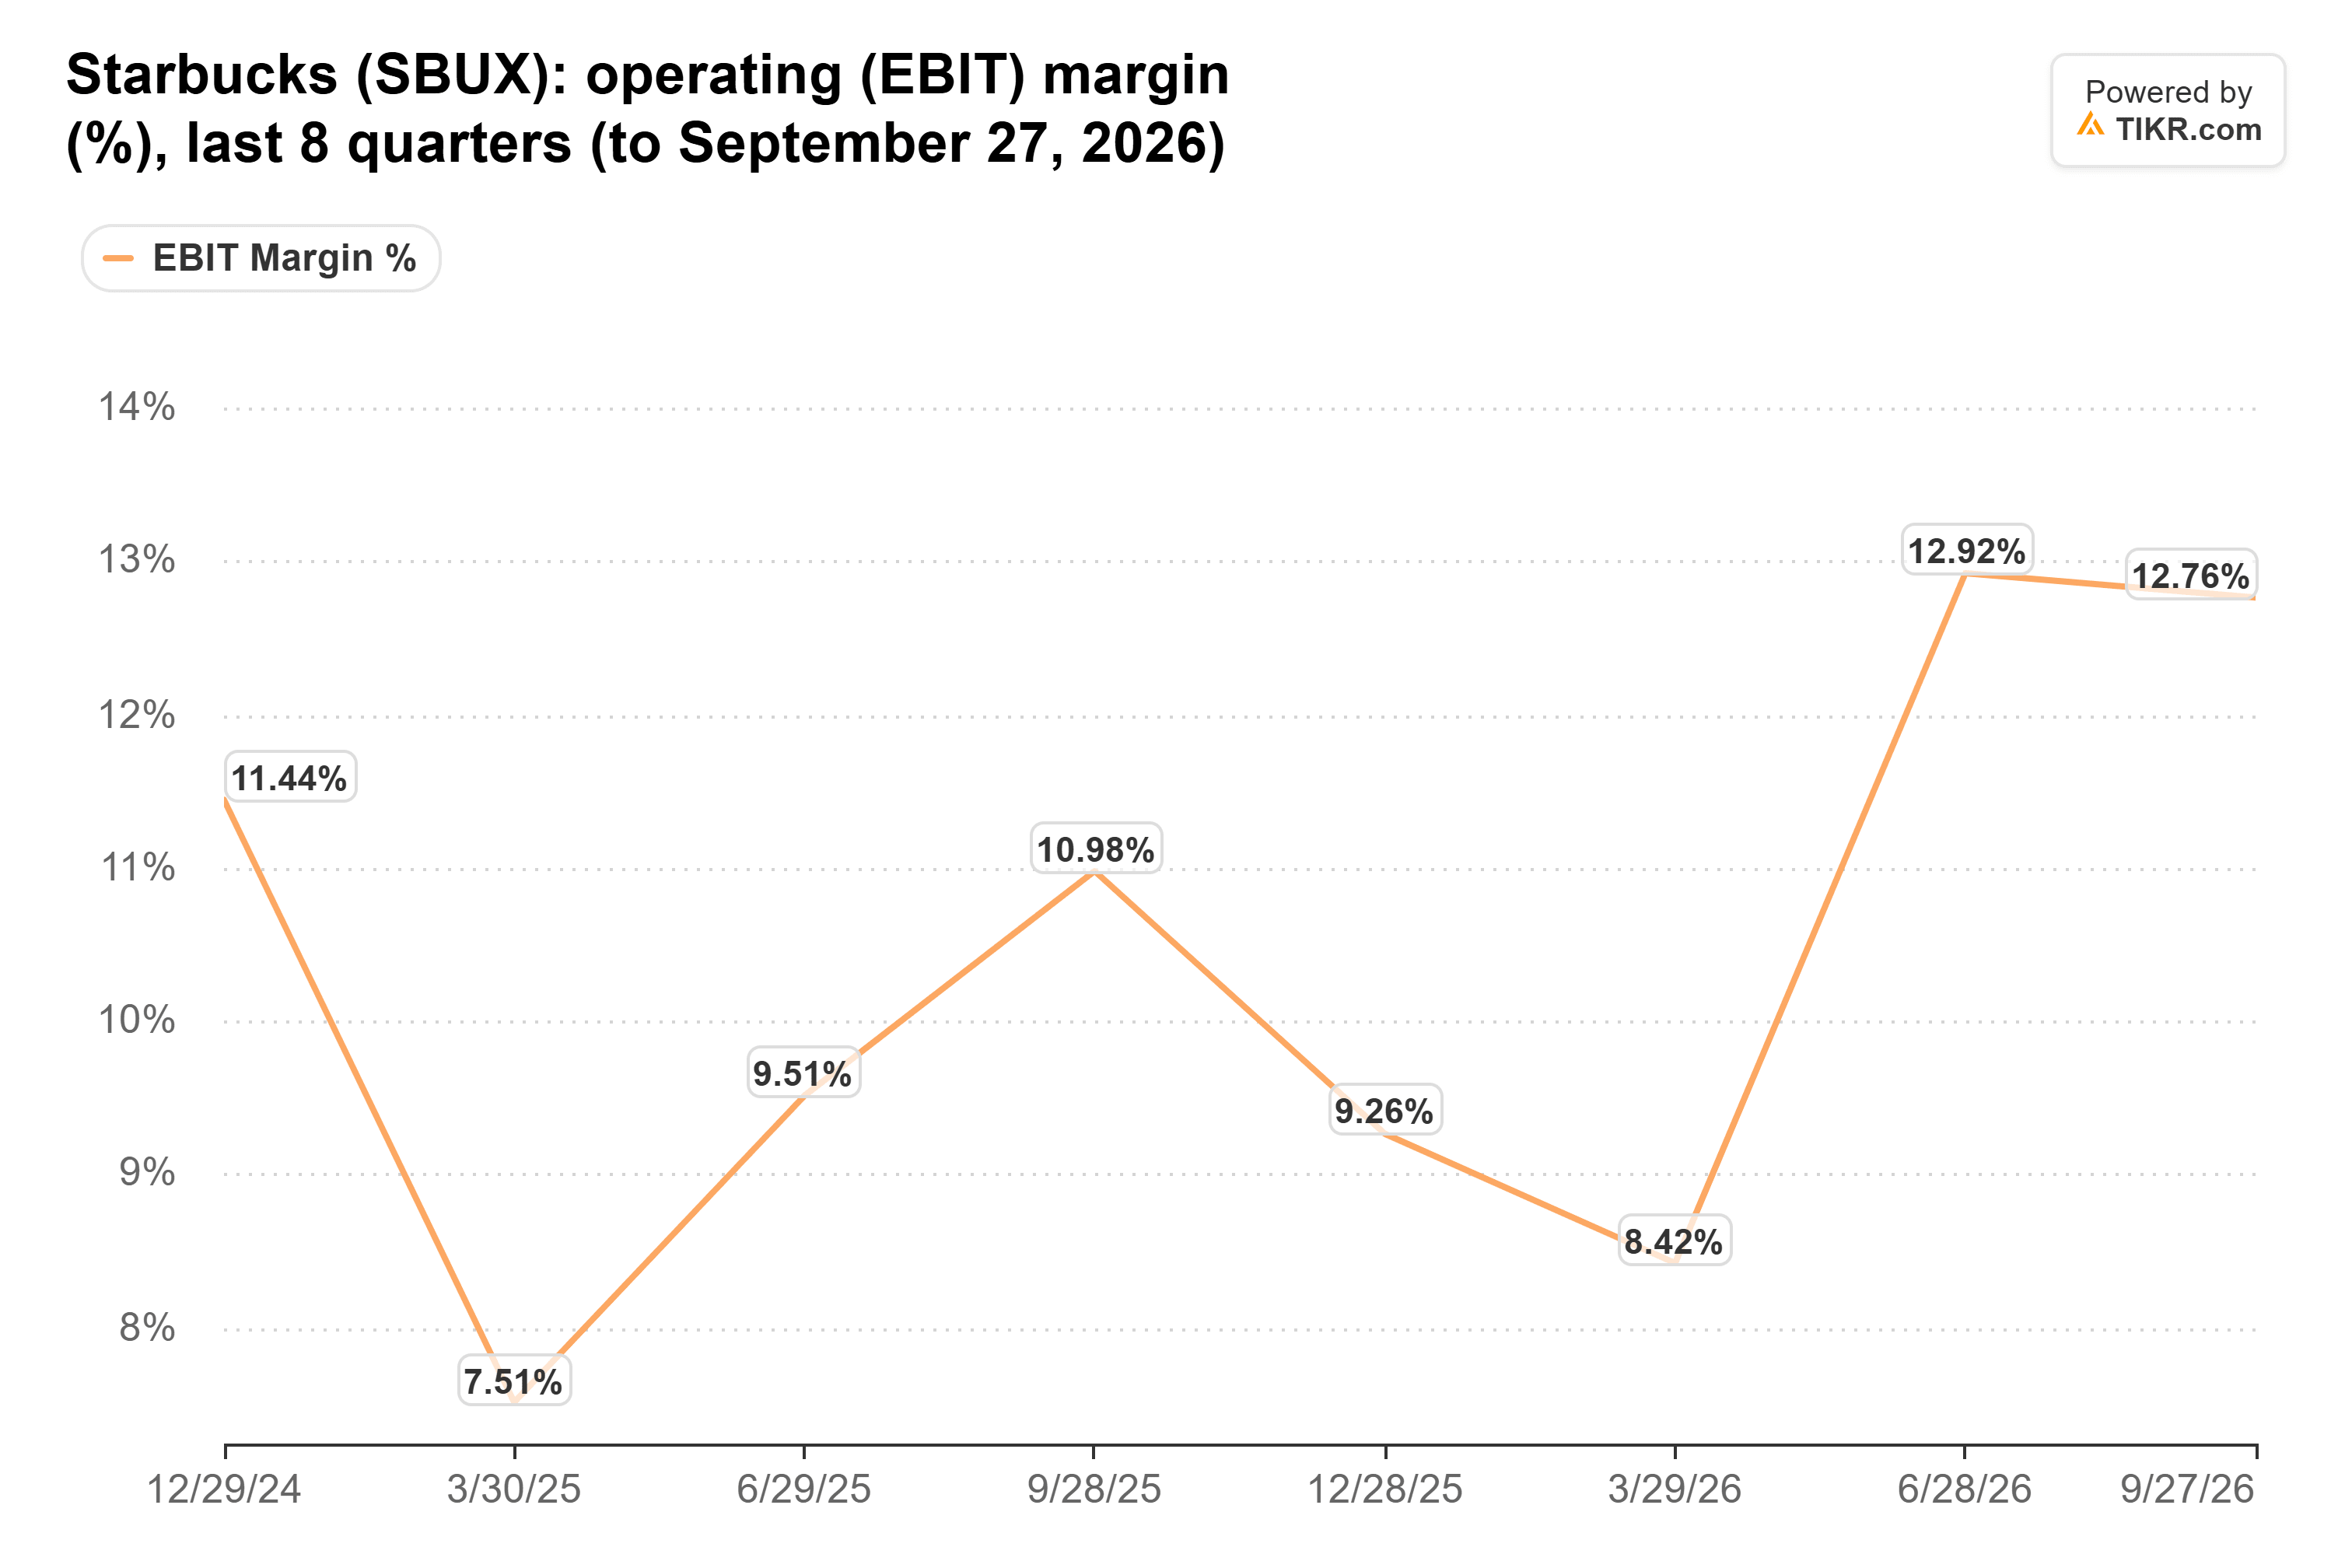
Management targets a 13.5%-15.0% adjusted operating margin in fiscal 2028 and says it can earn 17%-18% again over time. Its fiscal 2027 guide of 13.5%-14.0% already overlaps that range, so the plan is on track. But $125 still needs earnings above that plan, or investors paying a higher multiple than they do today.
Overseas is the soft spot. International comparable sales grew just 0.9% against the roughly 3% expected, an awkward start for Niccol’s goal of doubling stores abroad to 40,000-plus.
Starbucks Has to Prove the Traffic
The turnaround is real, but at 33x, investors are already paying for management’s plan. U.S. transactions rose 2.4% in the fourth quarter, down from 4.2% in the third, while ticket did the heavy lifting at 5.2%. I’d wait for traffic to pick back up before paying for Cramer’s $125.
Starbucks reports its fiscal first quarter in late January, against a 3% rise in U.S. transactions a year earlier. Growth on top of that would make $125 easier to believe.
So What Is Starbucks Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Starbucks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!