Key Takeaways
- Coherent stock is up 21% in the past year, but it’s about 56% below the peak it set in June, a run helped by Nvidia’s $2 billion investment.
- Revenue rose 50% in the September quarter, management now expects fiscal 2027 pro forma revenue growth above 60%, and it signed a PhotonLink deal valued at about $20 billion.
- Fears about AI spending and Marvell’s $115 billion deal for Lumentum have pulled Coherent’s forward P/E below its five-year average.
- Coherent looks like a buy at this multiple, as long as operating cash flow turns positive again by the December-quarter report.
Coherent (COHR) is up 21% in the past year, but it took a round trip to get there. A $2 billion investment from Nvidia (NVDA) helped send the stock to a record in June, and it’s about 56% below that peak now. On Nov. 5, the day after its best guidance yet, it fell 13% as Democrats’ midterm wins sank AI stocks, then regained 13.6% on Nov. 6.
On Nov. 2, Marvell Technology (MRVL) agreed to buy rival Lumentum (LITE) in a $115 billion all-stock deal. That leaves Coherent as the big independent laser maker.
Nvidia lit the fuse
On March 2, Nvidia bought about 7.8 million new Coherent shares at $256.80 apiece and signed a multi-year supply agreement for lasers and optical networking products. (Nvidia paid well above where Coherent trades now, so that stake is underwater.)
Coherent joined the S&P 500 on March 23, and in May it reported March-quarter revenue up 21% (27% pro forma). Then on June 2, Nvidia CEO Jensen Huang appeared at Marvell’s Computex keynote and said copper “has its limits,” leaving more of the work to optics. Coherent jumped 17% to a record close.
TIKR tracks 26 analysts on Coherent. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coherent, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coherent’s Analyst Ratings
Then investors got nervous about AI spending
Investors started doubting AI budgets again after Lam Research reported in late October, and Intel’s and Amazon’s results a week later made it worse.
The Lumentum deal is harder to read. Once it closes, Marvell will sell lasers and transceivers next to its own chips, and Lumentum’s non-GAAP gross margin was 53.2% in the September quarter, against Coherent’s 40.6%. Customers wary of buying optics from a chipmaker could send Coherent more orders. Or a Marvell selling complete modules could keep Coherent’s margin pinned near 40%.
After the report, BofA cut its target to $240 from $400. B. Riley argues that optics stocks’ multiples now follow sentiment about AI funding more closely than quarterly results.
The business never slowed down
In the quarter ended Sept. 30, revenue jumped 50% to $2.37 billion. For the December quarter, Coherent guided to $2.55 billion – $2.75 billion of revenue, ahead of the $2.54 billion consensus, and it now expects fiscal 2027 pro forma growth above 60%. It also signed a PhotonLink agreement with a major AI company worth about $20 billion over five years, with revenue ramping from early 2028.
“As AI datacenters transition from copper to optical connectivity, Coherent’s broad photonics platform and manufacturing scale position us to help customers meet rising needs for bandwidth and energy efficiency,” CEO Jim Anderson said in Coherent’s first-quarter release.
Going into the report, the Street had normalized EPS rising from $5.61 for fiscal 2026 (years end in June) to $9.42 for fiscal 2027 and $13.97 for fiscal 2028:
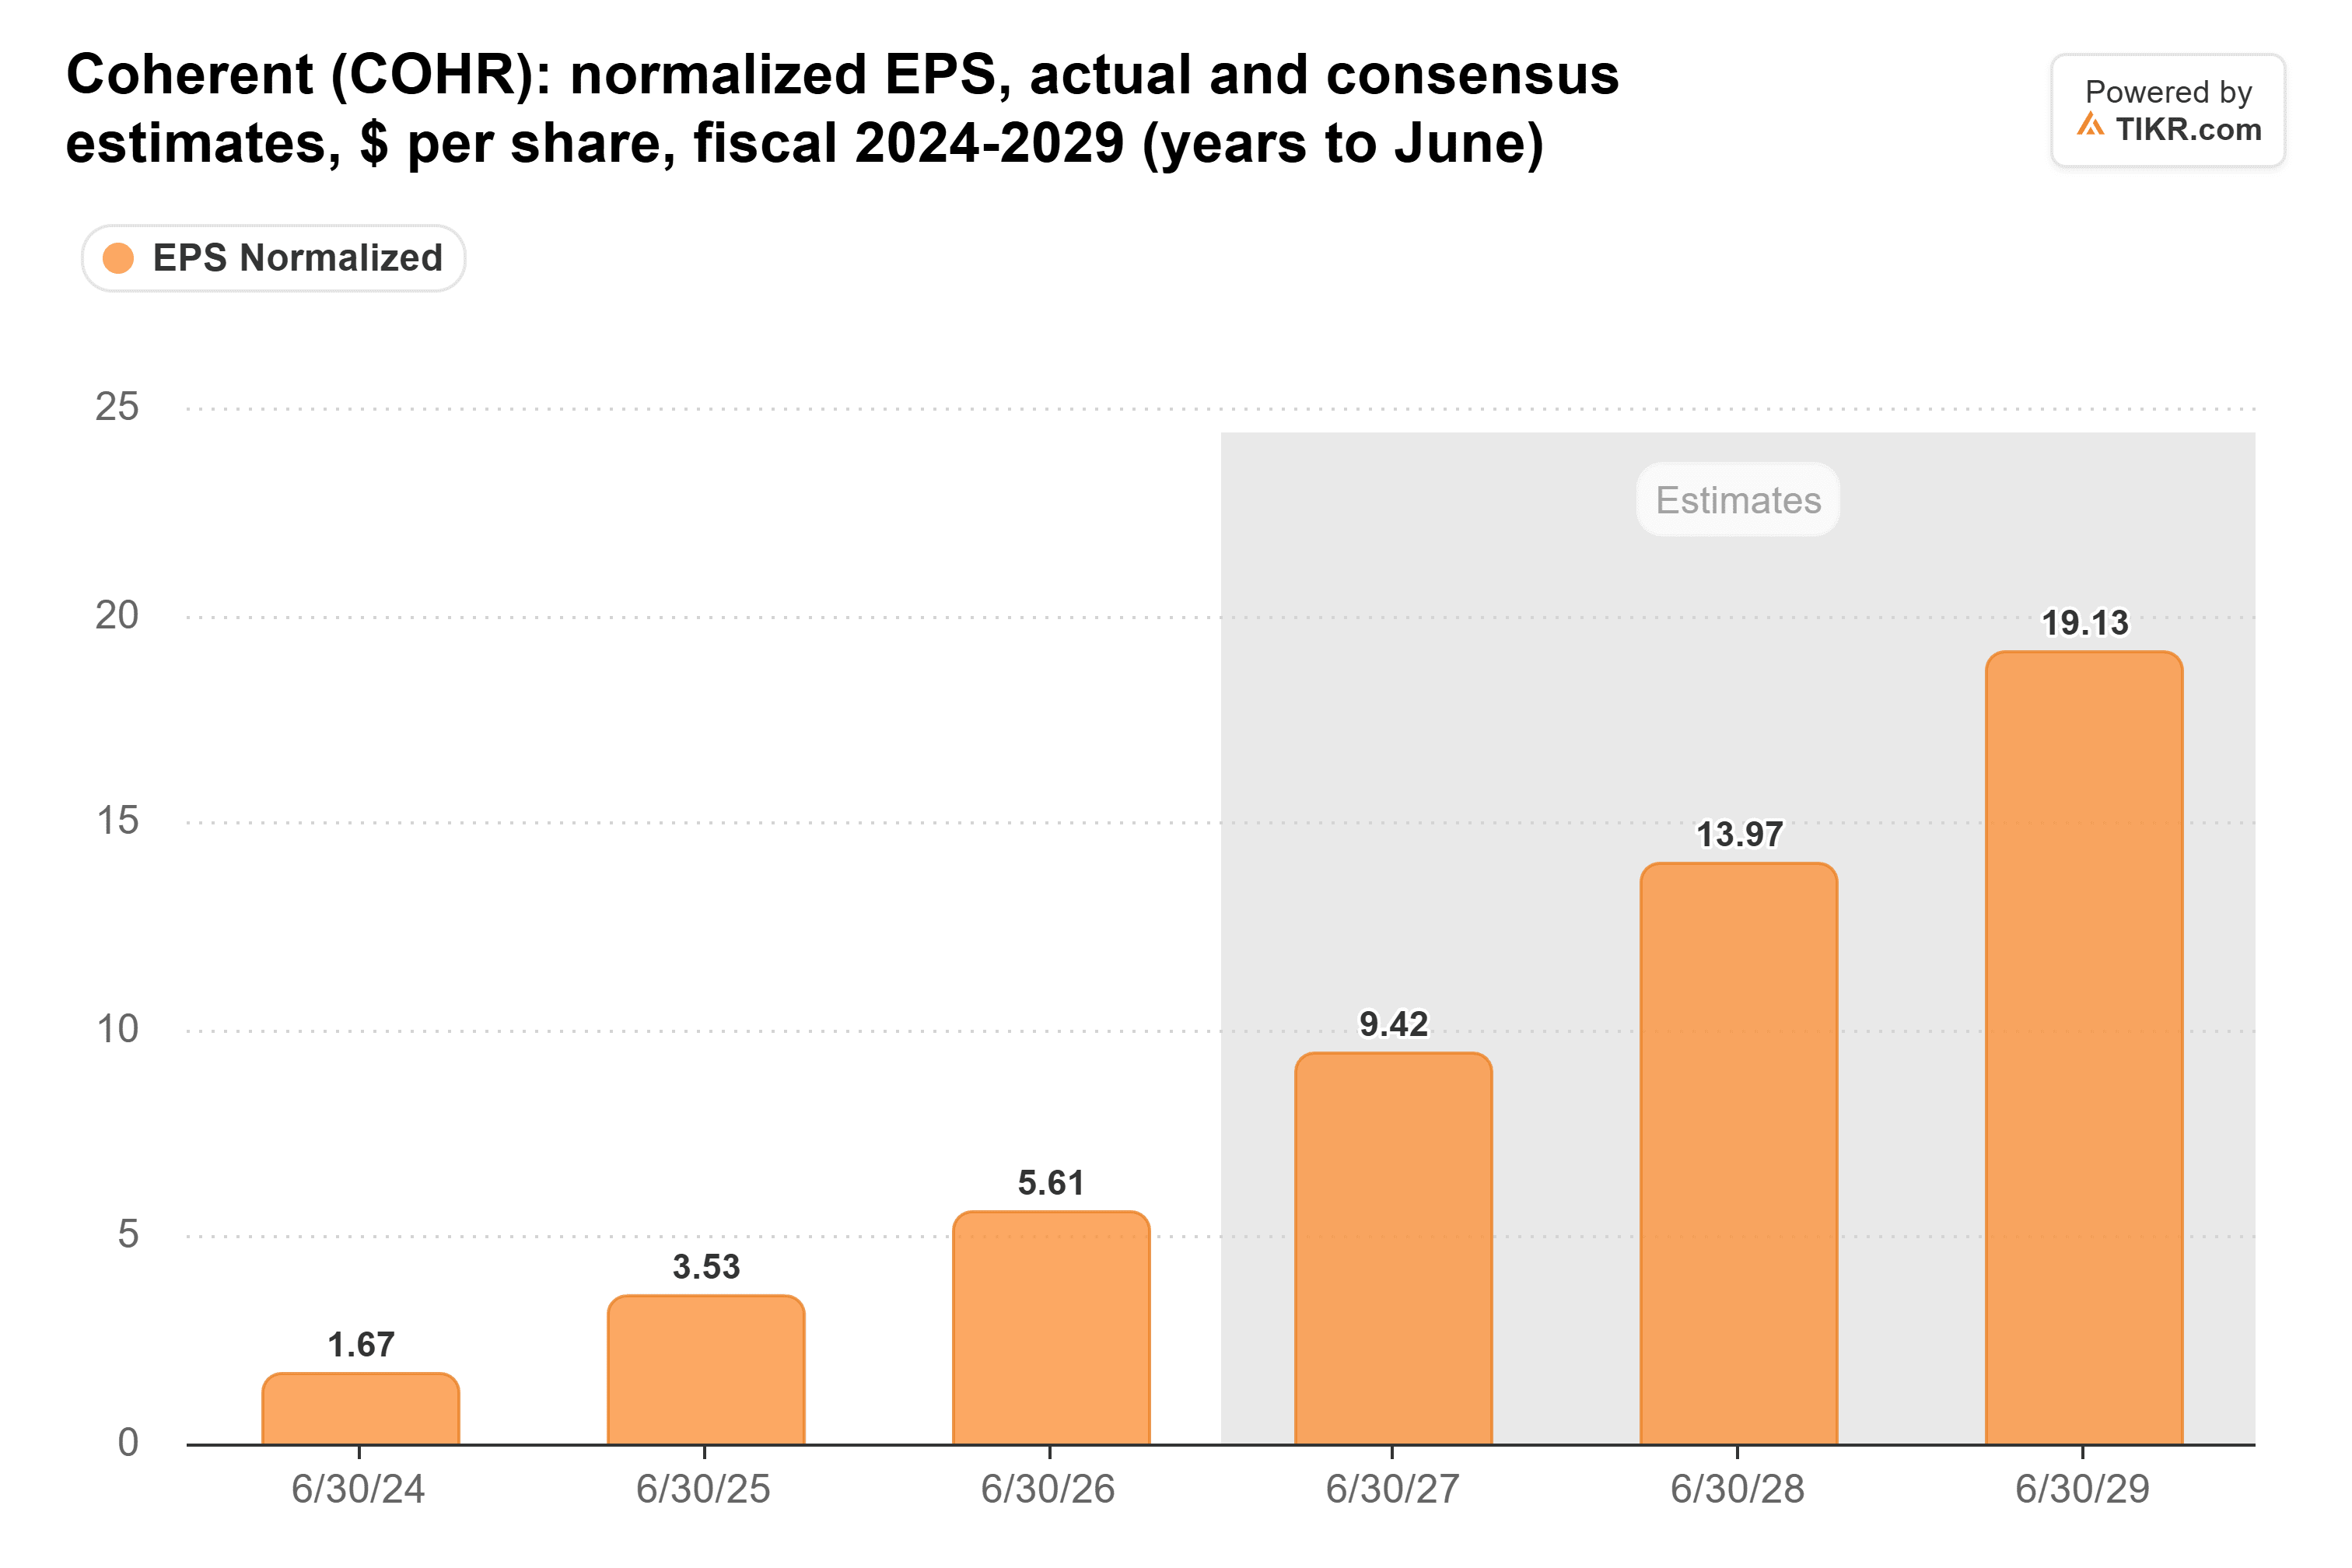
Those estimates assumed about 49% reported growth in fiscal 2027. Pro forma growth ran about six points above reported last quarter, so a 60%-plus guide still points to higher estimates.
Cheaper than its usual multiple
Even so, Coherent’s forward P/E was 21x at the Nov. 2 close, against 57x in early June and a five-year average of 24x:
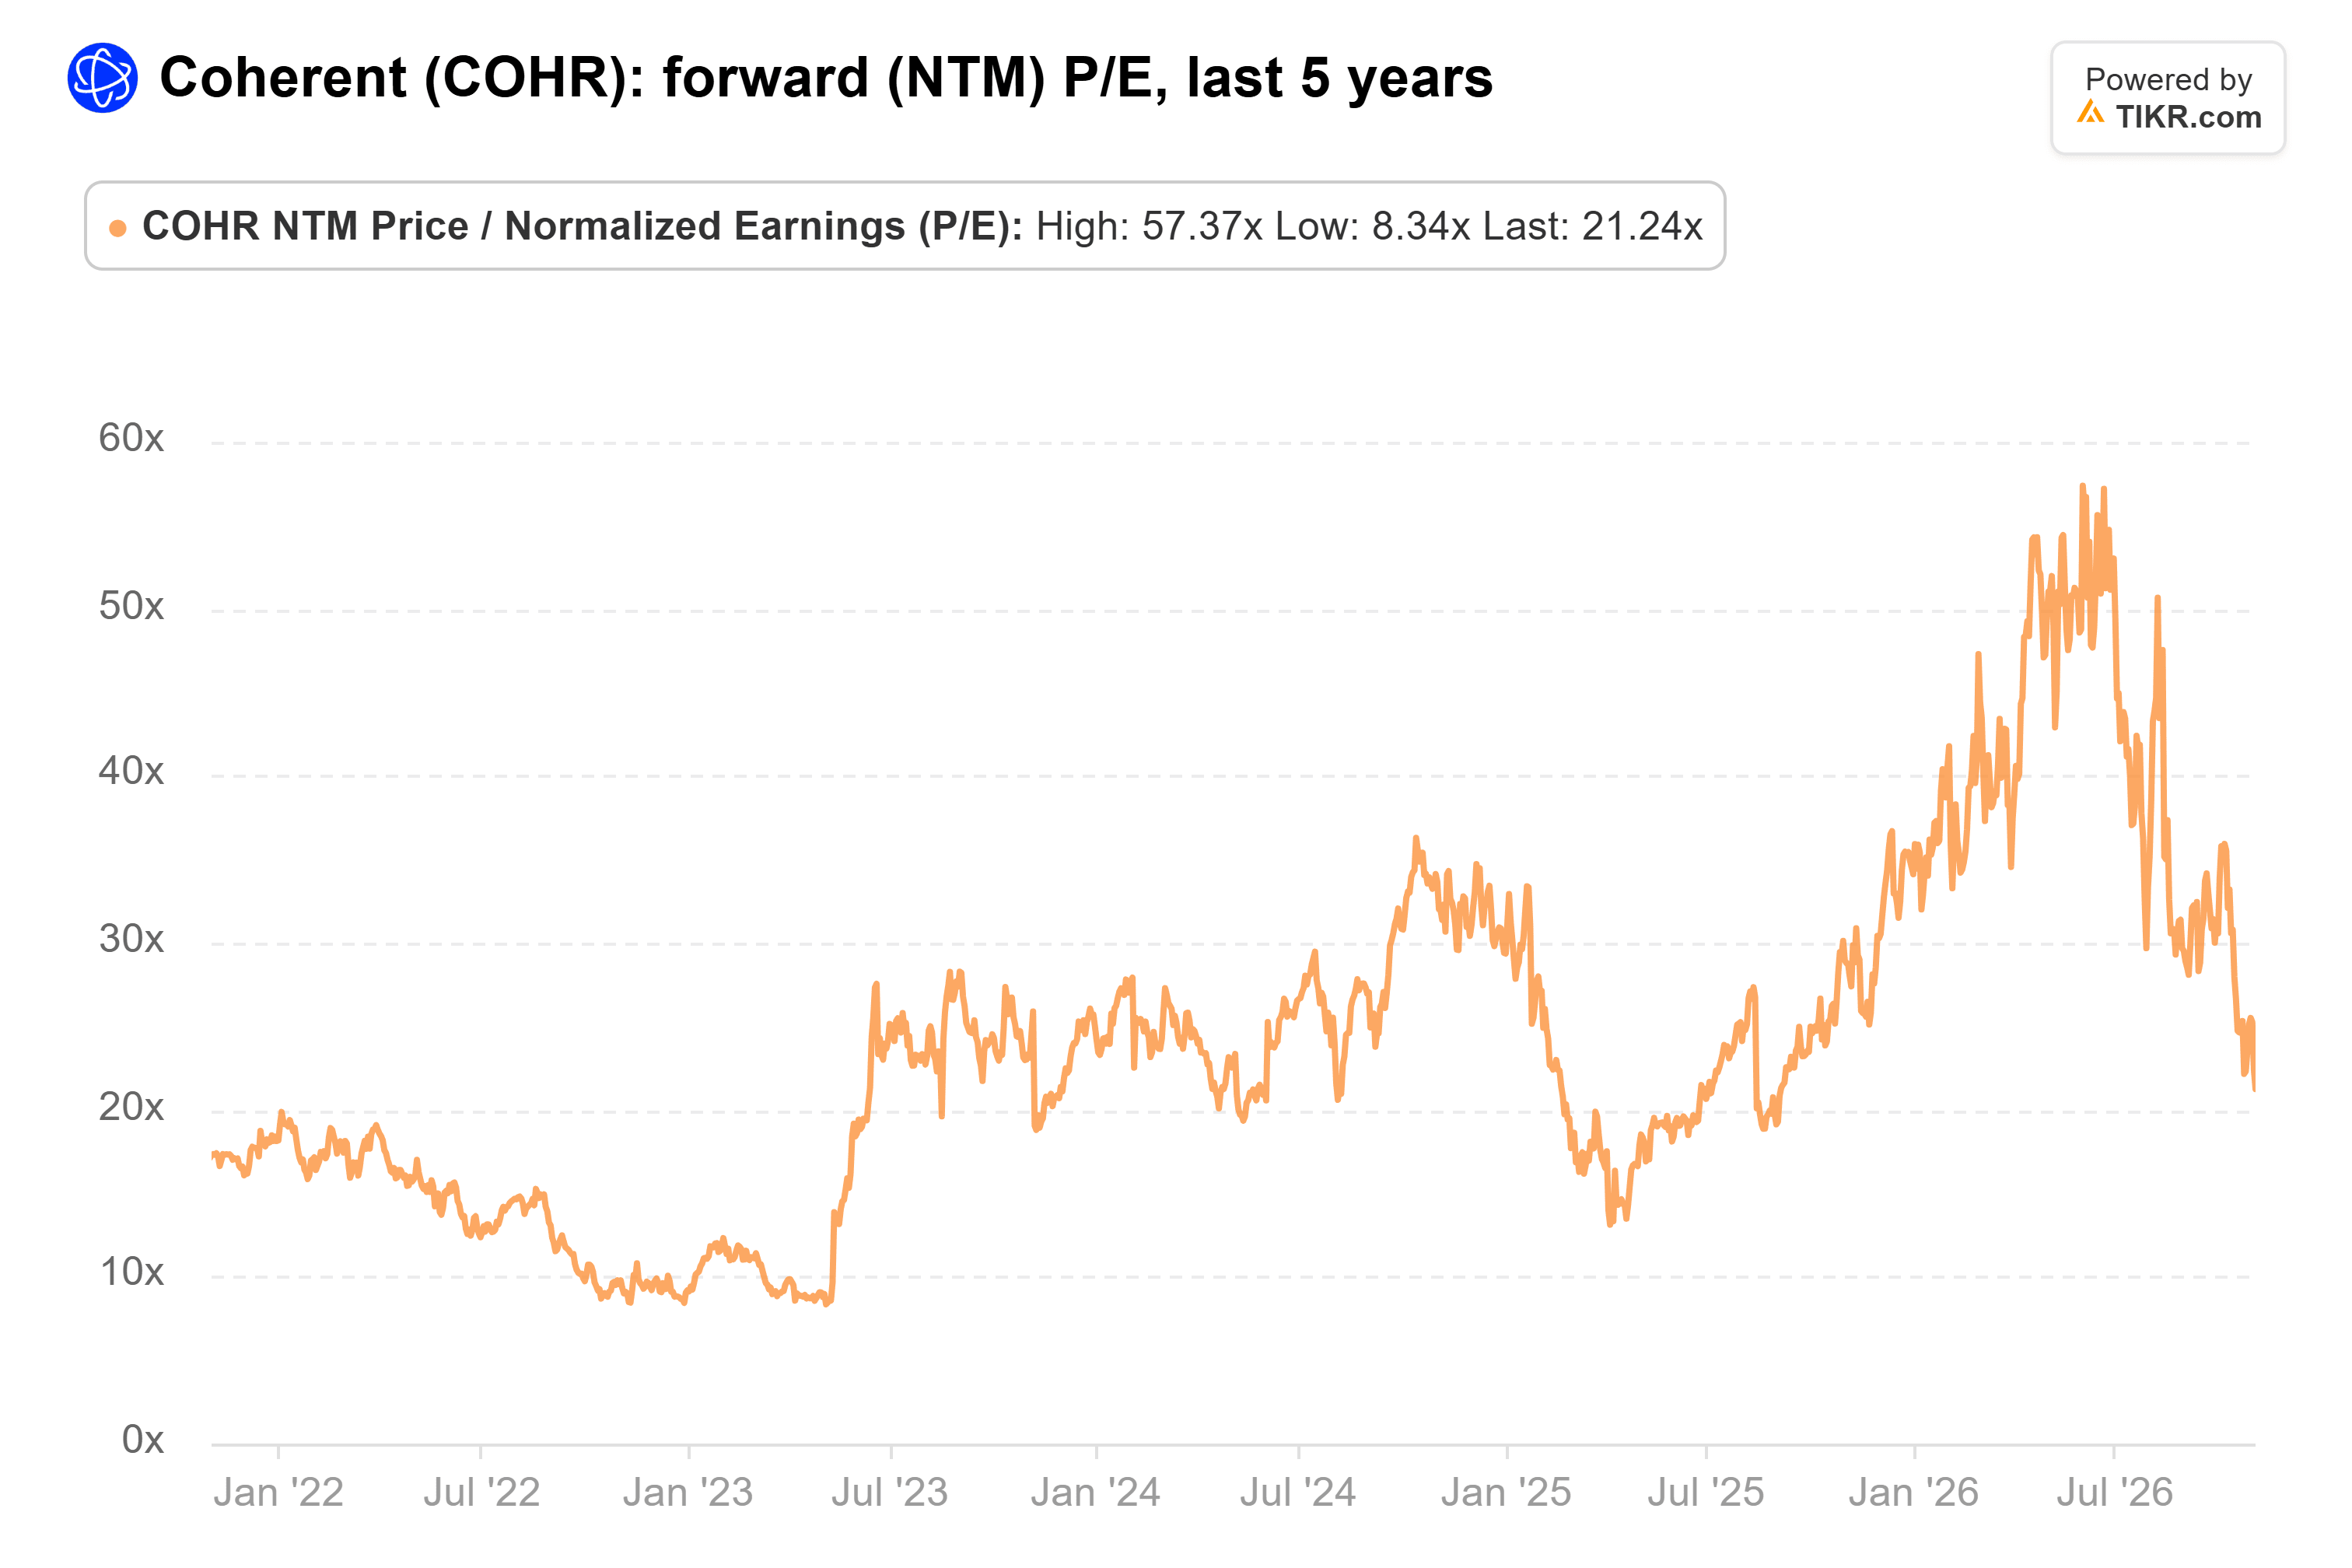
It’s slightly lower at the Nov. 6 close.
Watch the cash
For years, Coherent’s operating cash flow comfortably covered its capex:
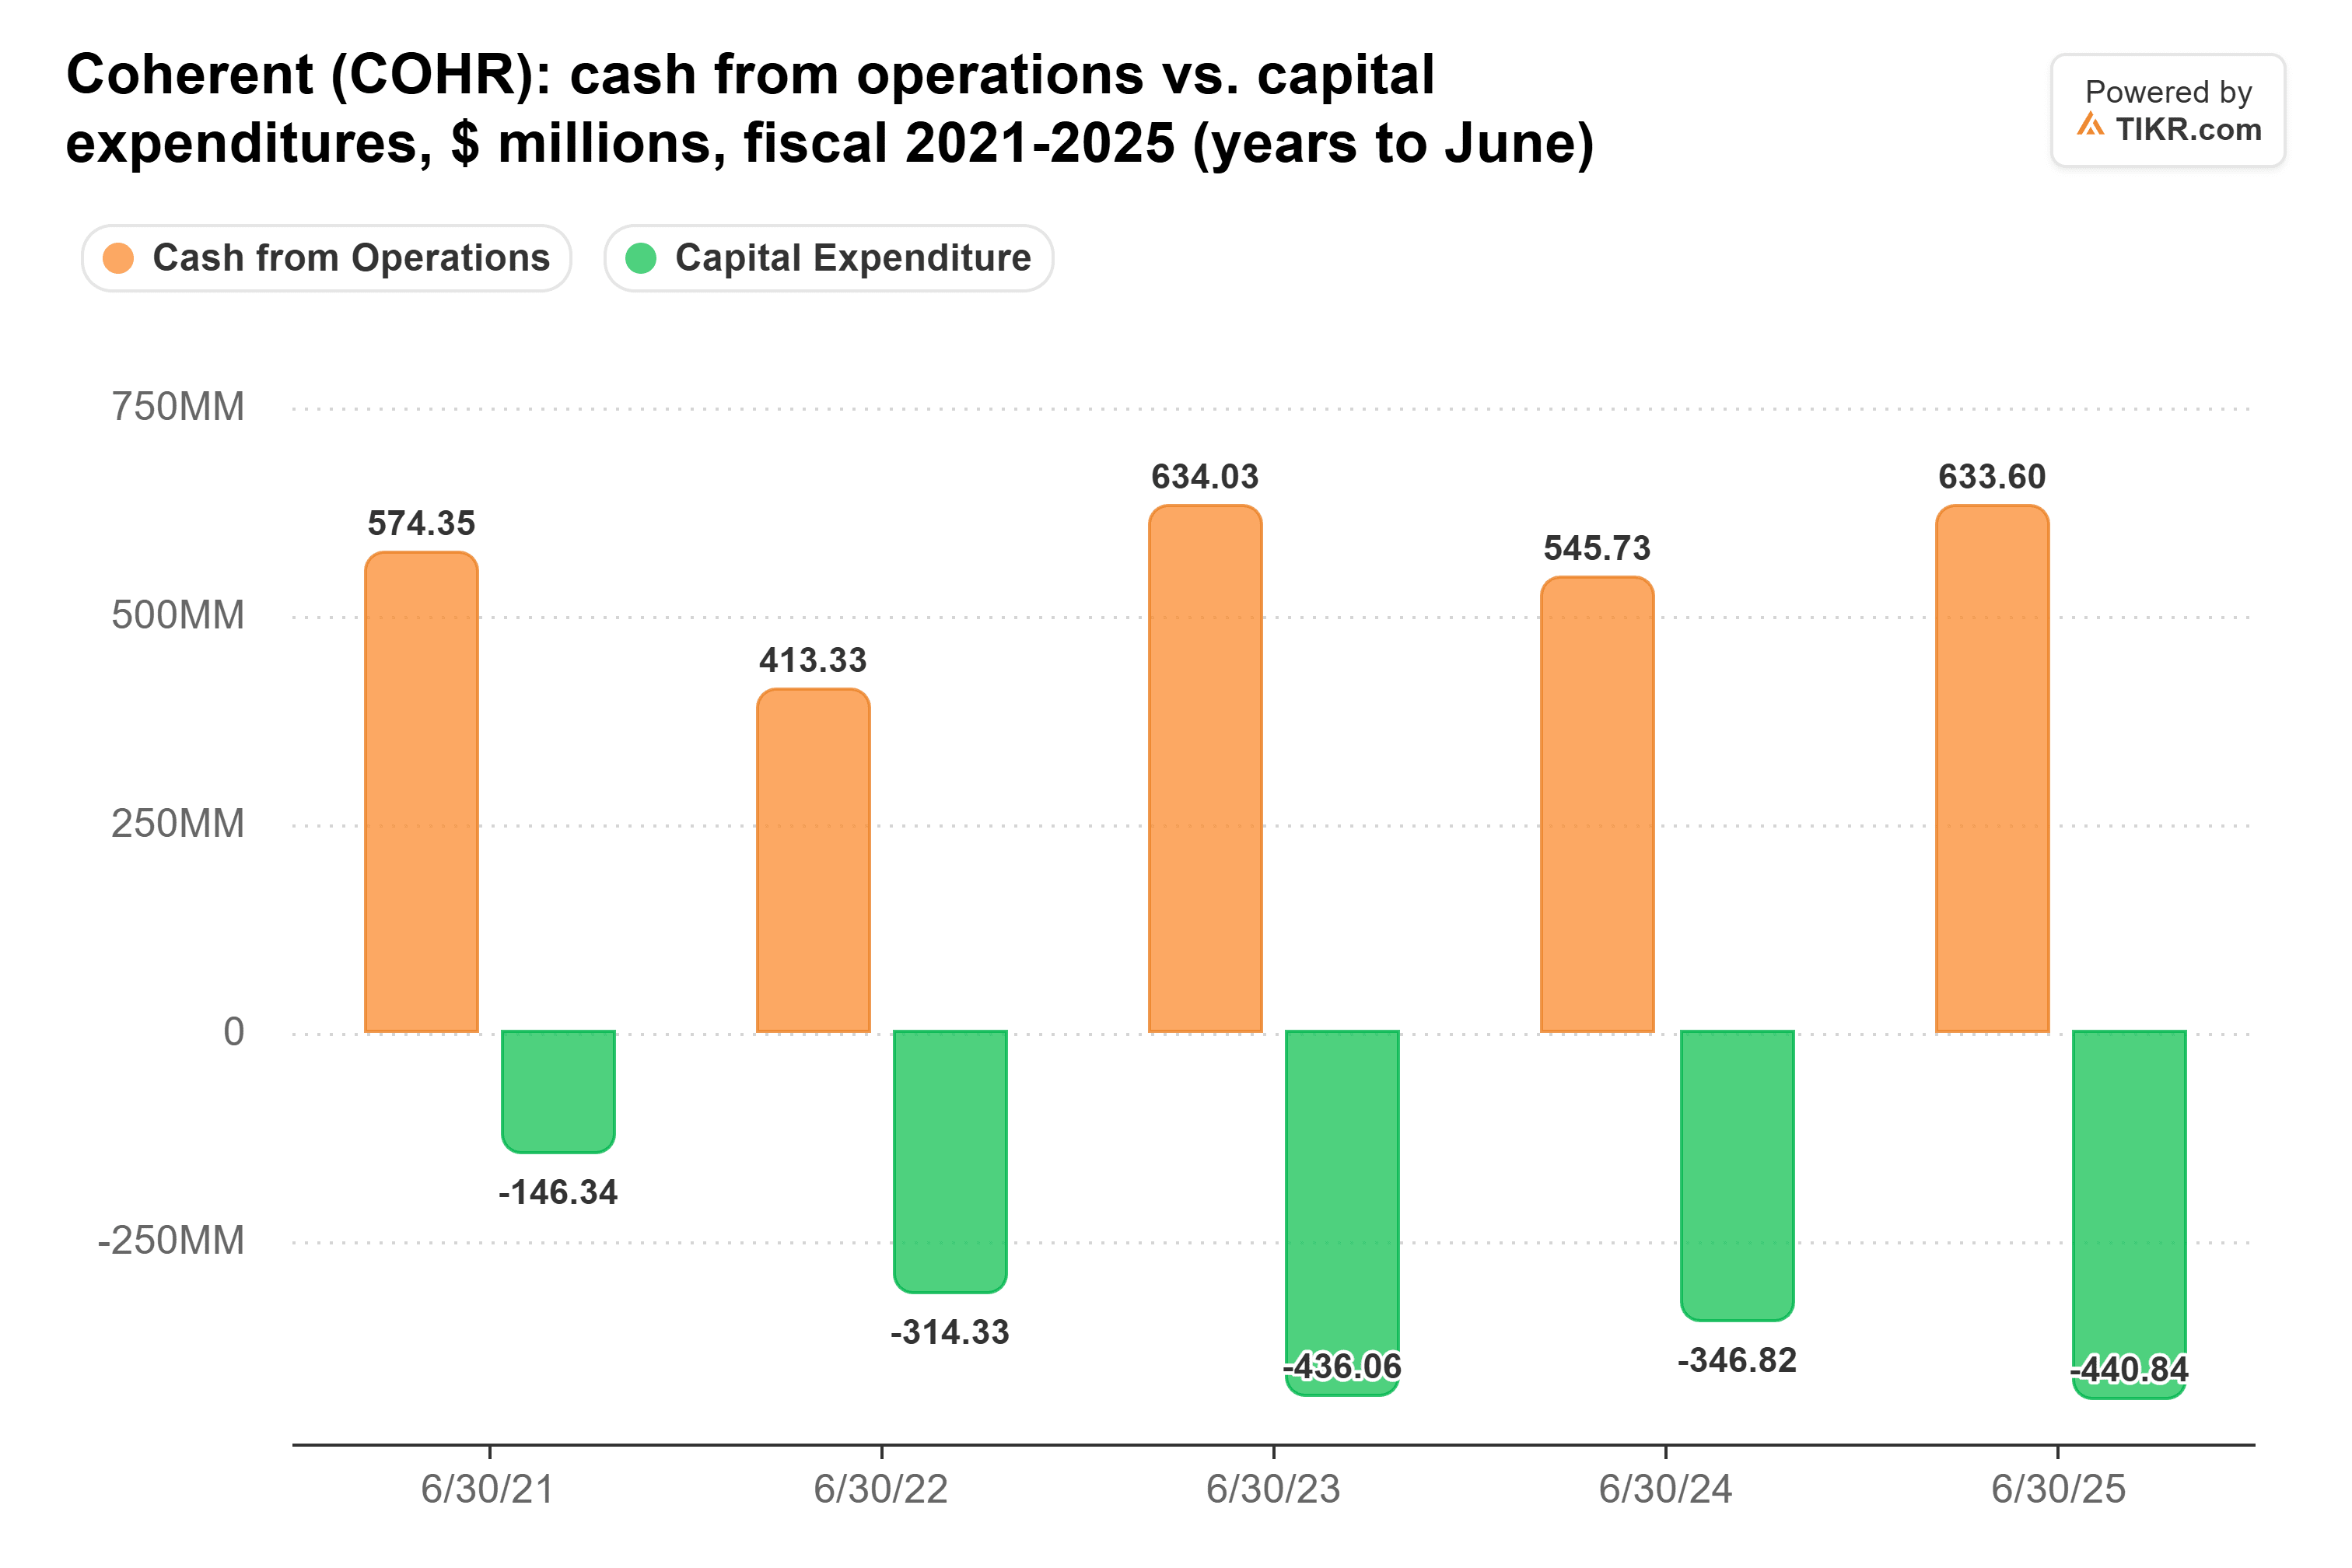
That changed in fiscal 2026, when operating cash flow fell to $80 million against $1.1 billion of capex. In the September quarter it slipped to negative $93 million, with capex at $776 million and inventory up to $3.3 billion.
At this price, Coherent looks like a buy. Management keeps raising its outlook and meeting it, and the stock trades below its usual multiple on estimates that look too low.
Fears about AI funding could squeeze the multiple further, though, and the December-quarter report, expected in early February, needs to show operating cash flow back above zero.
So what is Coherent stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coherent could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!