


Key Takeaways
- Home Depot shares fell about 2% today even though it beat third-quarter estimates and named CFO Richard McPhail its next CEO.
- Jim Cramer called the drop “overdone”: same-store sales rose 2.2%, ahead of the roughly 1.7% analysts expected.
- The catch is margins. Operating income grew about half as fast as revenue, and the margin guides slipped.
- At about 23x forward earnings against a 22x five-year average, the stock looks fairly priced, not cheap.
Home Depot (HD) shares fell about 2% today after the company beat third-quarter estimates and named CFO Richard McPhail its next CEO.
Jim Cramer disagrees. In a post on X, he wrote: “HD decline seems overdone. trades on SS which were better, not guidance which is always conservative”
He has a point. Home Depot’s same-store sales beat, while rival Lowe’s (LOW), which reports Wednesday, has guided to roughly flat same-store sales for the year.
Better comps, and an insider in charge
Home Depot beat estimates across the board:
- Revenue rose 4.9% to $43.4 billion, ahead of the $42.8 billion expected.
- Same-store sales rose 2.2%, against about 1.7% expected. U.S. same-store sales also rose 2.2%, against 1.5%.
- Comparable average ticket rose 3%, while comparable customer transactions fell 0.5%.
- Adjusted EPS rose 3% to $3.86, a hair above estimates.
The U.S. comp is up from 1.3% in the second quarter, and transactions fell half as much as they did then. After three years of same-store sales that fell or barely grew, that’s real progress.
McPhail takes over on Nov. 23, with Ted Decker, back from medical leave, staying on as chairman. McPhail has been CFO since 2019, so the executive who helped put about $24 billion into SRS, GMS and Mingledorff’s now has to make those deals pay off.
TIKR Tracks 36 Analysts on Home Depot. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Home Depot, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Home Depot’s Analyst Ratings
Home Depot’s guide landed where analysts already were
Home Depot now expects fiscal 2026 sales to grow about 4.5%, the top of its earlier 2.5% to 4.5% range, with same-store sales up about 1.4%. Adjusted EPS should grow about 2% from $14.69, or roughly $14.98, in line with what analysts expected:
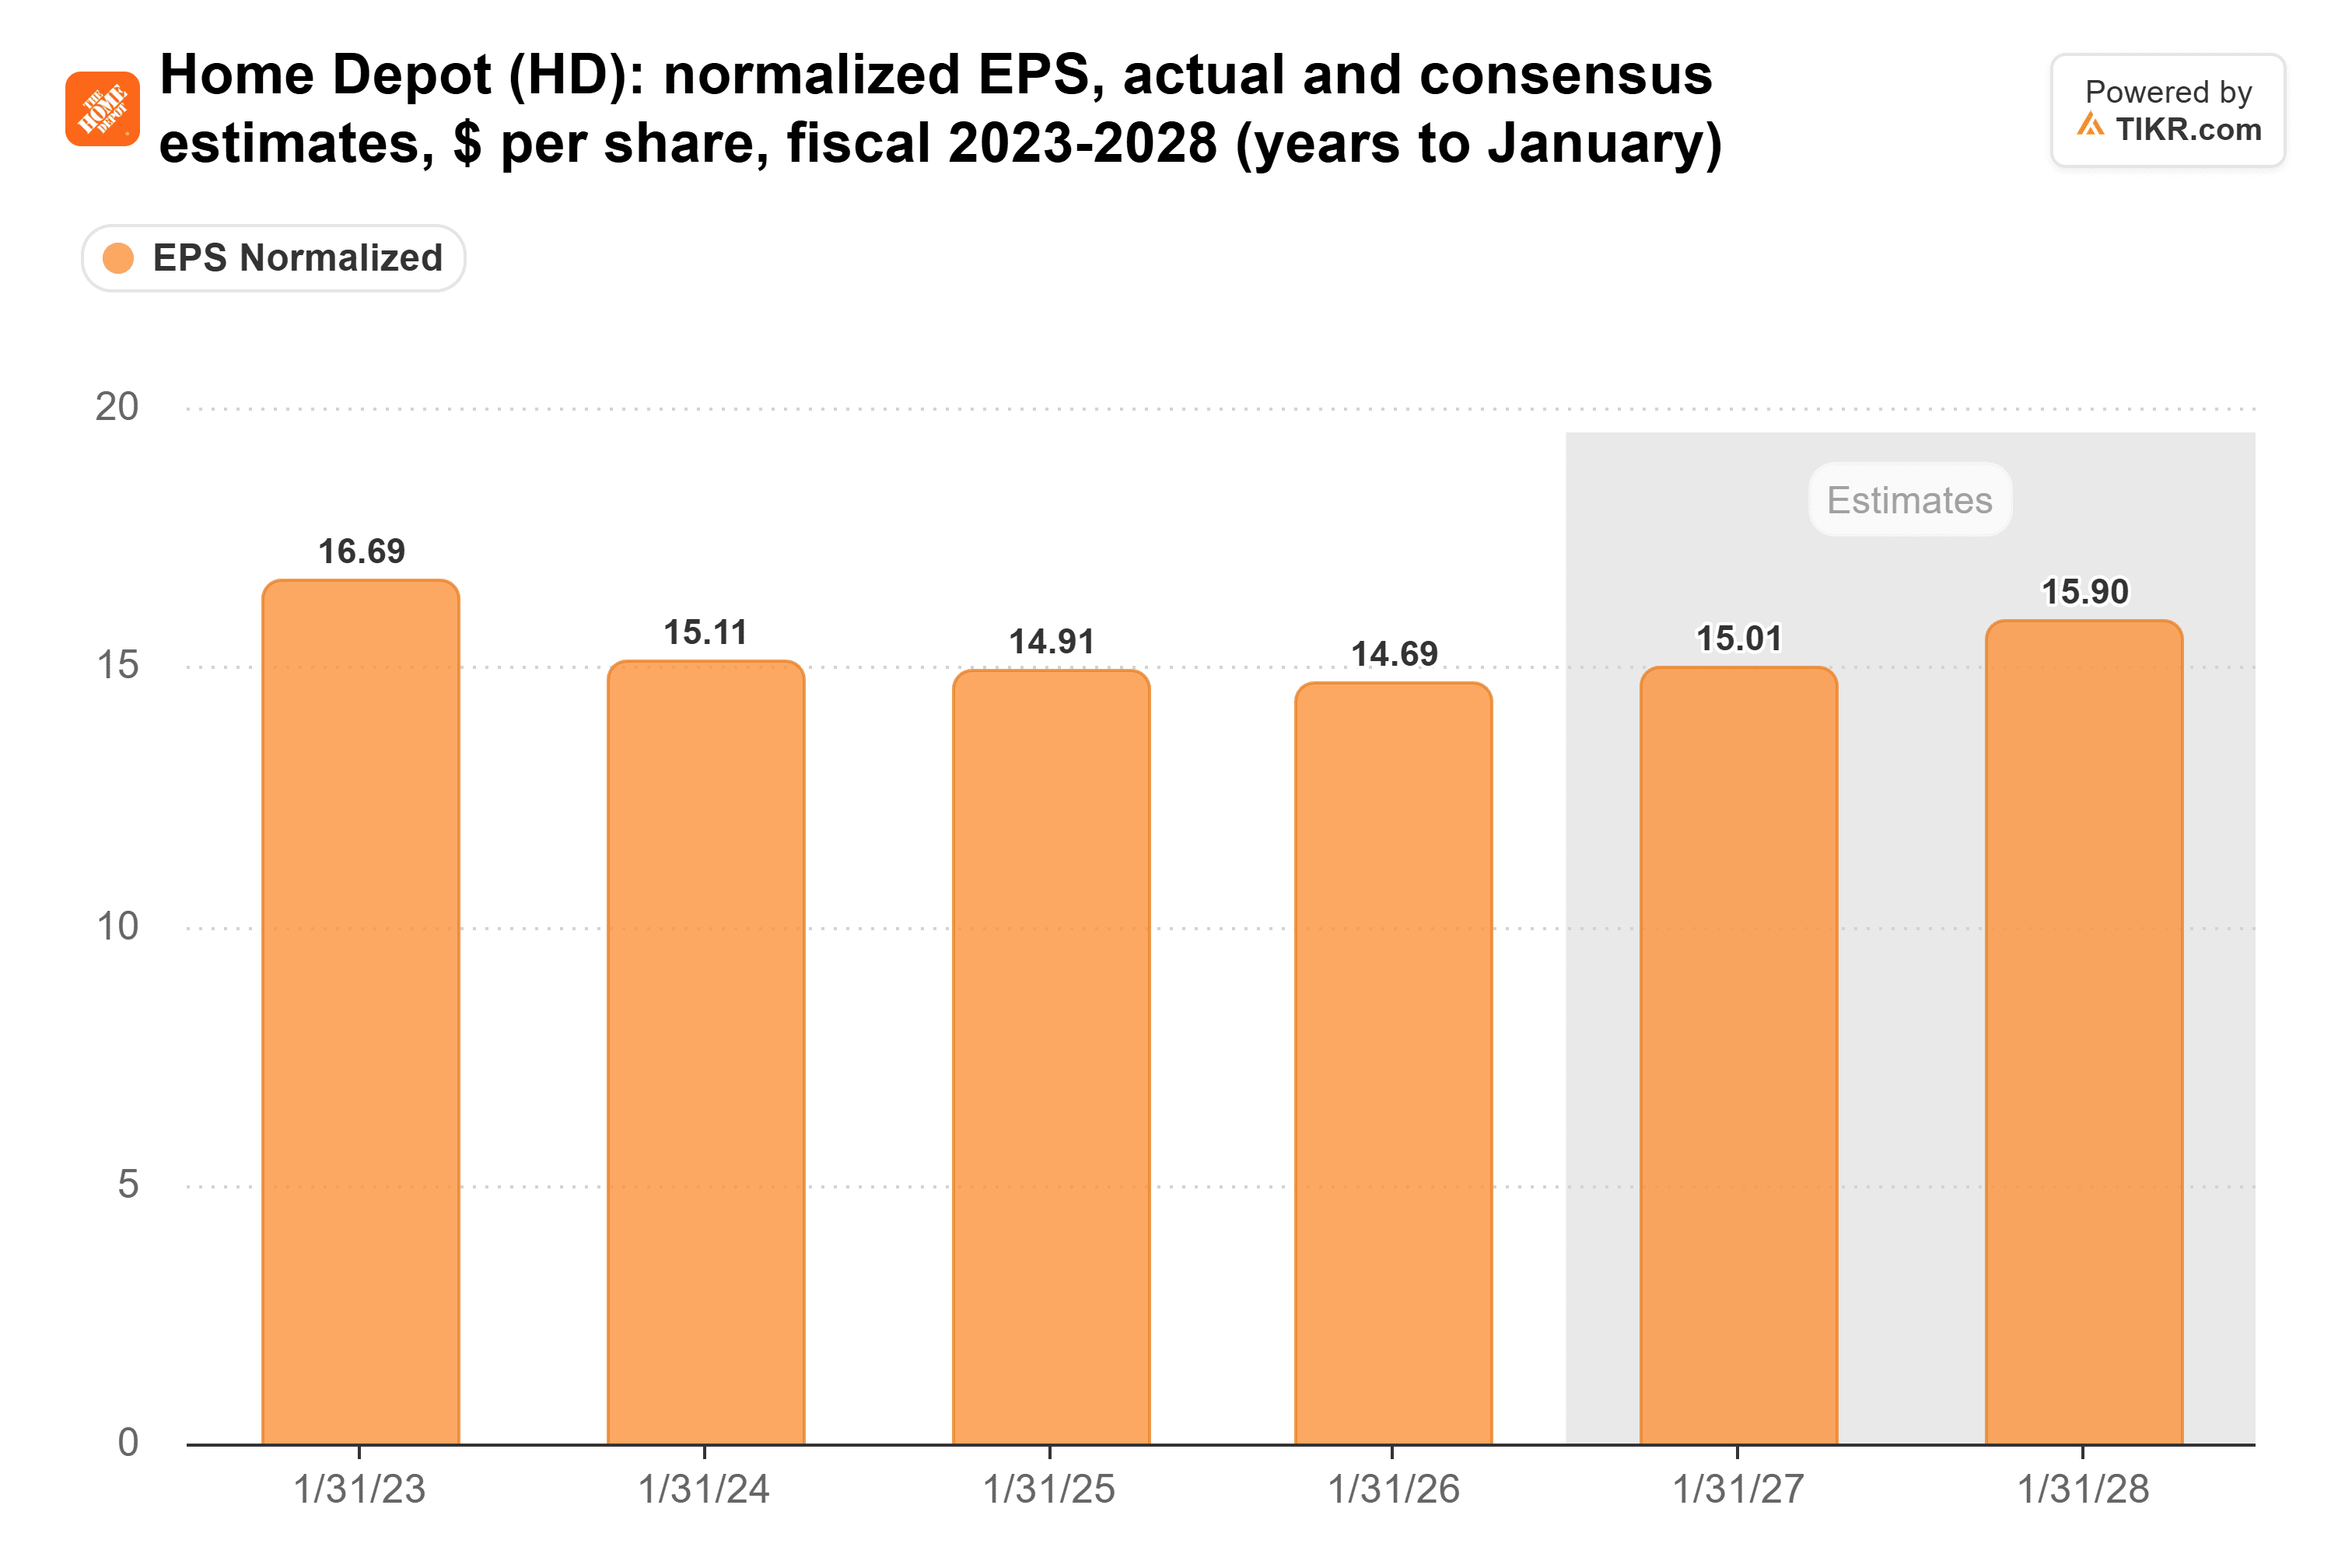
The harder bar is fiscal 2027’s $15.90. And Cramer’s “always conservative” has history behind it: a year ago, Home Depot guided to a fiscal 2025 gross margin of about 33.2% and delivered 33.3%.
Margins are the catch
Still, the sellers aren’t imagining things. Third-quarter operating income rose 2.4% to $5.5 billion, about half as fast as revenue, and the operating margin slipped to 12.6% from 12.9%. Home Depot also trimmed its full-year gross margin guide to about 33.0% from 33.1%, and its adjusted operating margin guide of about 12.8% now sits at the bottom of its earlier 12.8% to 13.0% range. Sales guidance went to the top of its range, while EPS guidance stayed at the midpoint.
Overdone, but no bargain
Home Depot traded at about 23x forward earnings at the last close, a little above its five-year average of 22x:
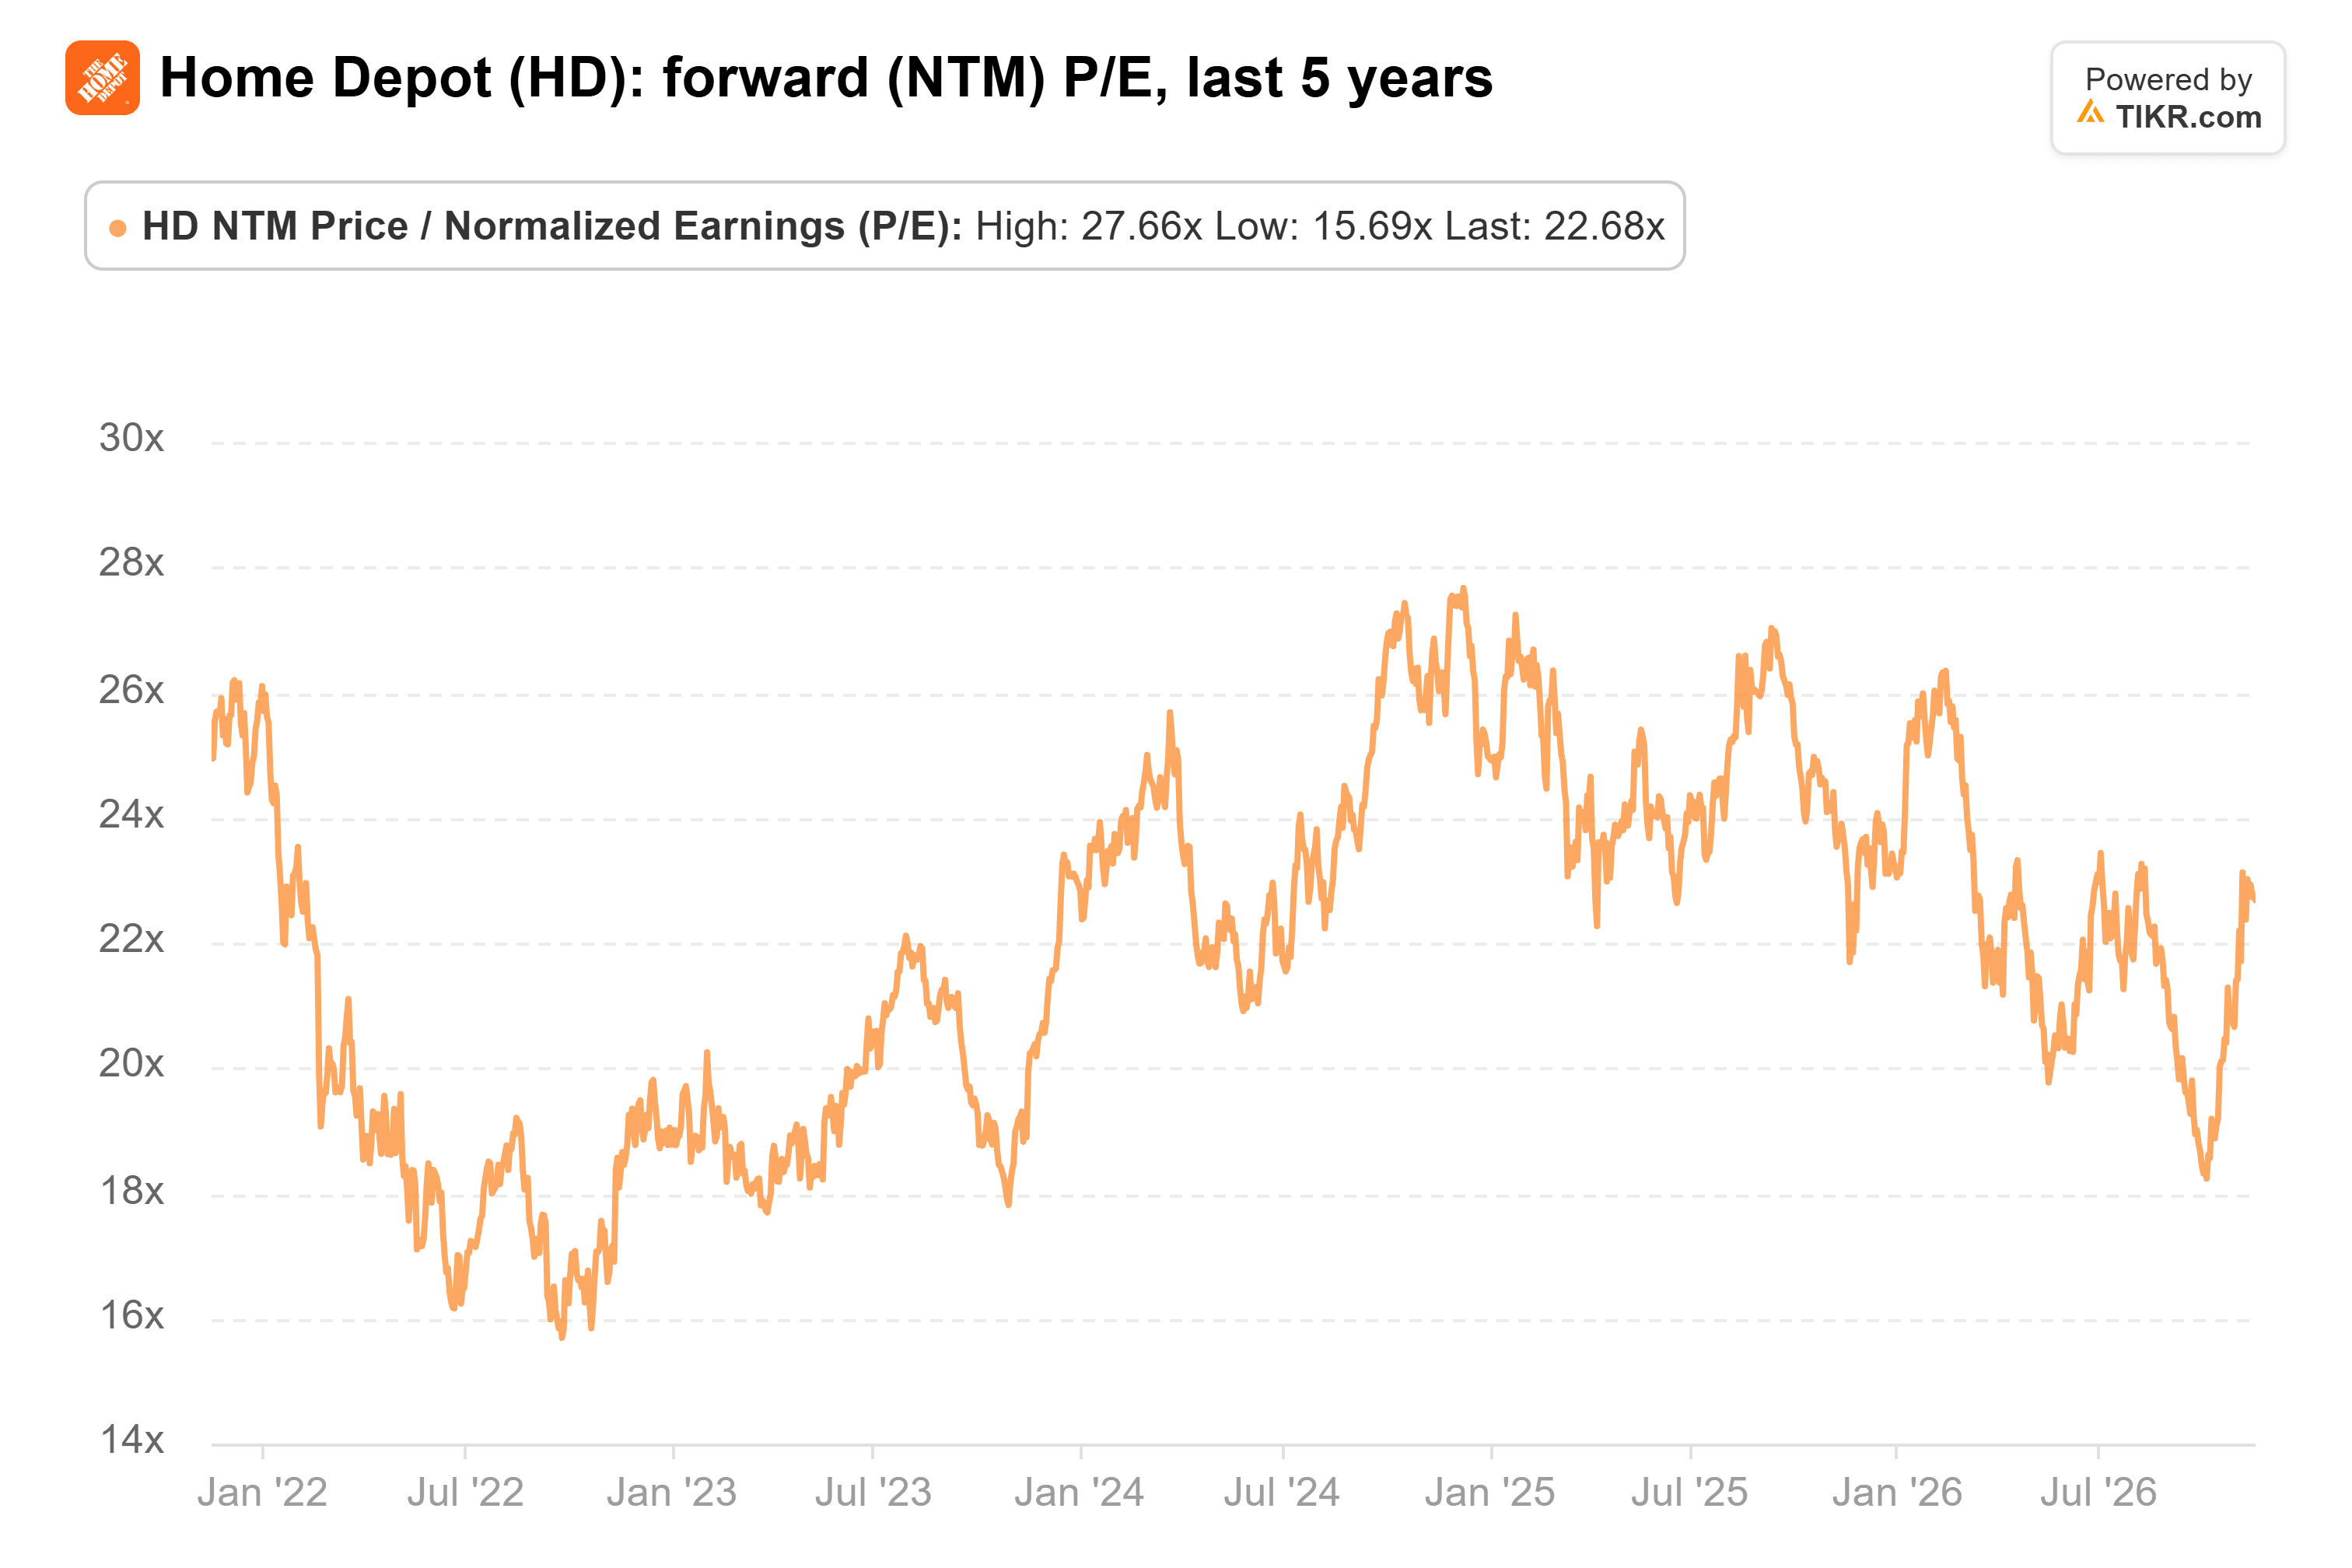
Today’s dip takes it a touch lower, inside a five-year range of 16x to 28x.
I’m with Cramer on the quarter. Same-store sales beat, the transaction decline narrowed, and the sales guide moved to the top of its range, so selling on that looks overdone. But at about its usual multiple, investors are already paying for EPS climbing to $17.28 by fiscal 2028, and that takes better margins than today’s guide shows. I’d call Home Depot fairly priced, with upside only if McPhail can turn sales growth into margin growth. Lowe’s report on Wednesday is the next read on whether Home Depot is still taking share.
So What Is Home Depot Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Home Depot could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



