Key Takeaways
- Bank of America kept its Buy rating and $280 target on NVIDIA on Nov. 16, 79% above the last close, with shares down 35% from their October high.
- At $280, NVIDIA would trade at about 23x forward earnings, below the 30x two-year median Bank of America cites.
- Price targets have fallen since late October, but fiscal 2028 earnings estimates are still 23% higher than three months ago.
- Tuesday’s third-quarter report, the first under interim CEO Colette Kress, is the first test of those estimates.
NVIDIA (NVDA) shares are down 35% from their Oct. 6 high, and Bank of America still sees them reaching $280 within a year, 79% above Monday’s close of $156.14. Analyst Vivek Arya reiterated his Buy rating and target on Nov. 16, a day before NVIDIA reports its third quarter.
His case doesn’t need NVIDIA to beat anyone’s numbers. It needs the market to stop pricing the stock like a company in crisis.
A CEO Exit, Then Washington
Jensen Huang resigned as CEO effective Nov. 11, a day before NVIDIA announced it, after admitting an affair with a former executive at a Singapore cloud company whom U.S. officials suspect of spying for China. CFO Colette Kress is interim CEO while the board searches for a permanent replacement.
Washington piled on. On Nov. 15, Treasury Secretary Scott Bessent said NVIDIA needs “a dramatic shakeup” and urged the board to hire an outside CEO. The same day, Axios reported that he’d questioned whether NVIDIA’s earnings were inflated by sales to China. Then on Nov. 17, CNBC reported, citing sources, that NVIDIA had warned customers a proposed law on remote Chinese access to its chips could expose them and the company to U.S. “legal action.”
NVIDIA’s last report predates all of this. In the quarter ended July 26, revenue more than doubled to $96.2 billion, and management guided to $108.0 billion, plus or minus 2%, for the third quarter.
Why $280 Isn’t a Stretch for NVIDIA
Arya cut his target from $350 to $280 on Nov. 12, and it still sits above the new targets from Morgan Stanley, UBS, Mizuho and TD Cowen, which all cut to between $200 and $267 over the past week.
The math is simple. Analysts expect NVIDIA to earn $12.09 a share over the next 12 months, so $280 is about 23x forward earnings. Bank of America puts the stock’s two-year median at 30x. Arya also ran a stress test: if data-center sales went flat in 2028, EPS would still top $15, putting $160 a share at about 10.6x those earnings.
TIKR Tracks 62 Analysts on NVIDIA. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on NVIDIA, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See NVIDIA’s Analyst Ratings
The Targets Fell. The Estimates Didn’t.
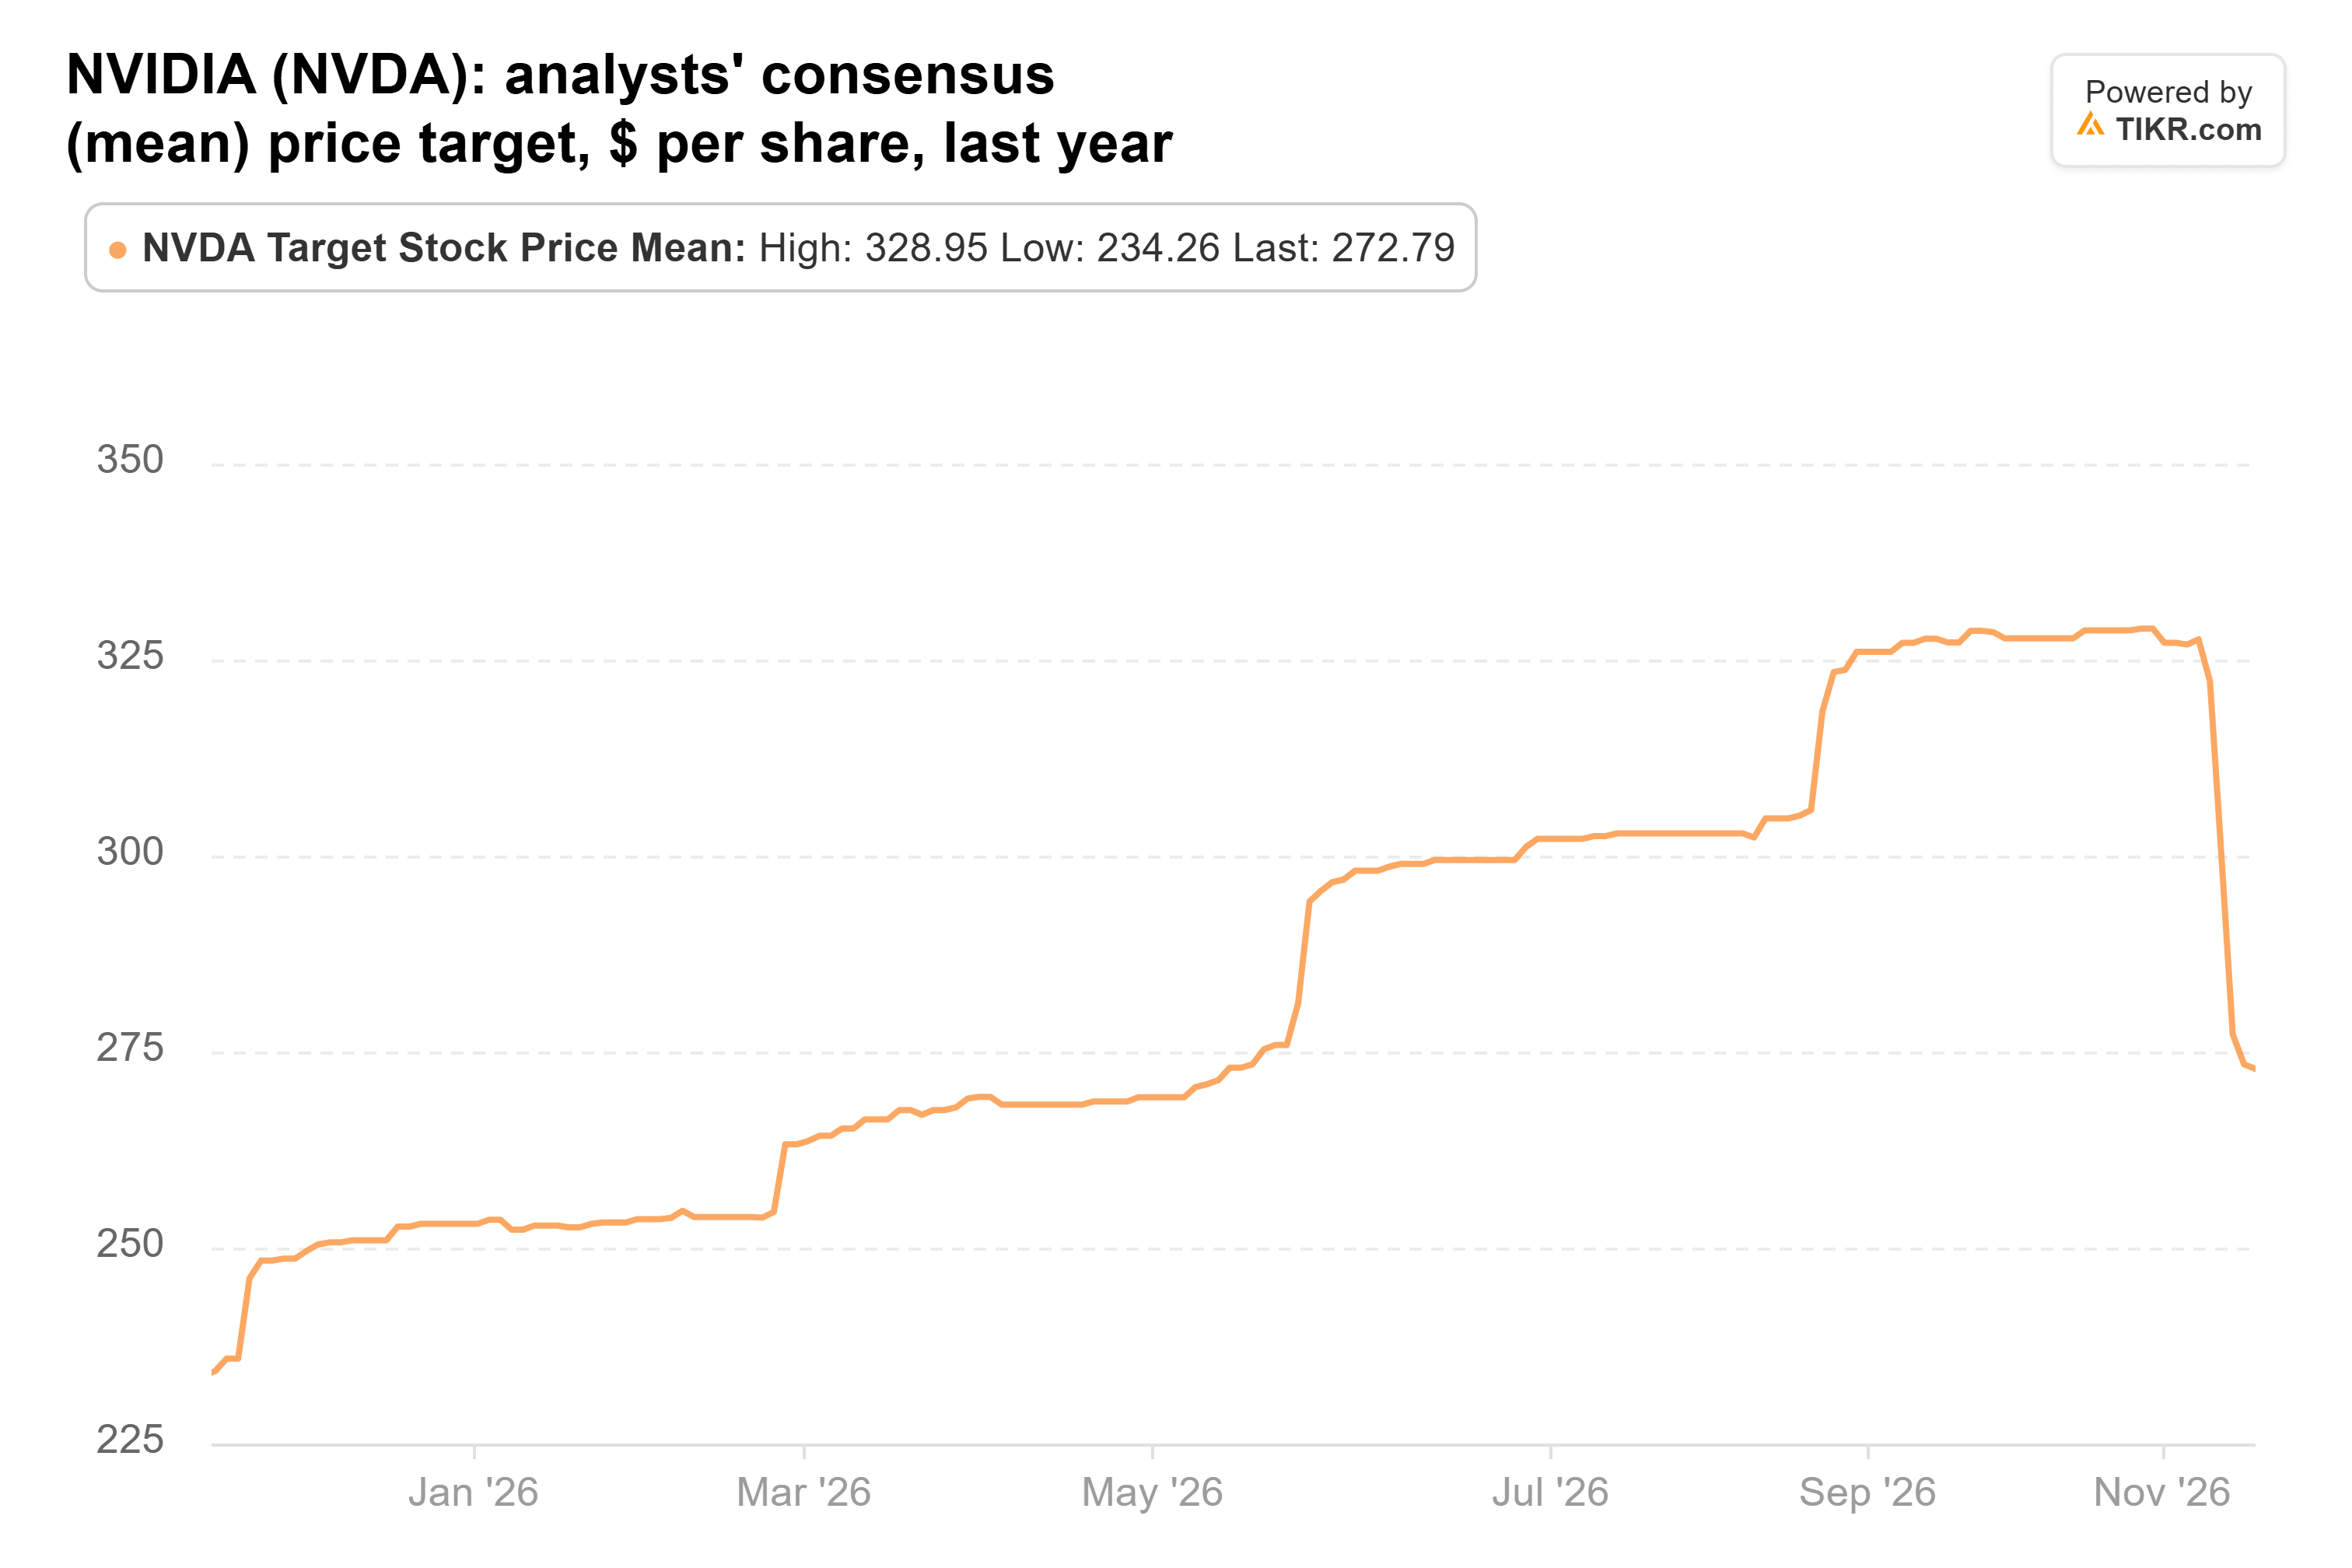
Wall Street’s consensus target has fallen from $329 in late October to $273, still 75% above the price:
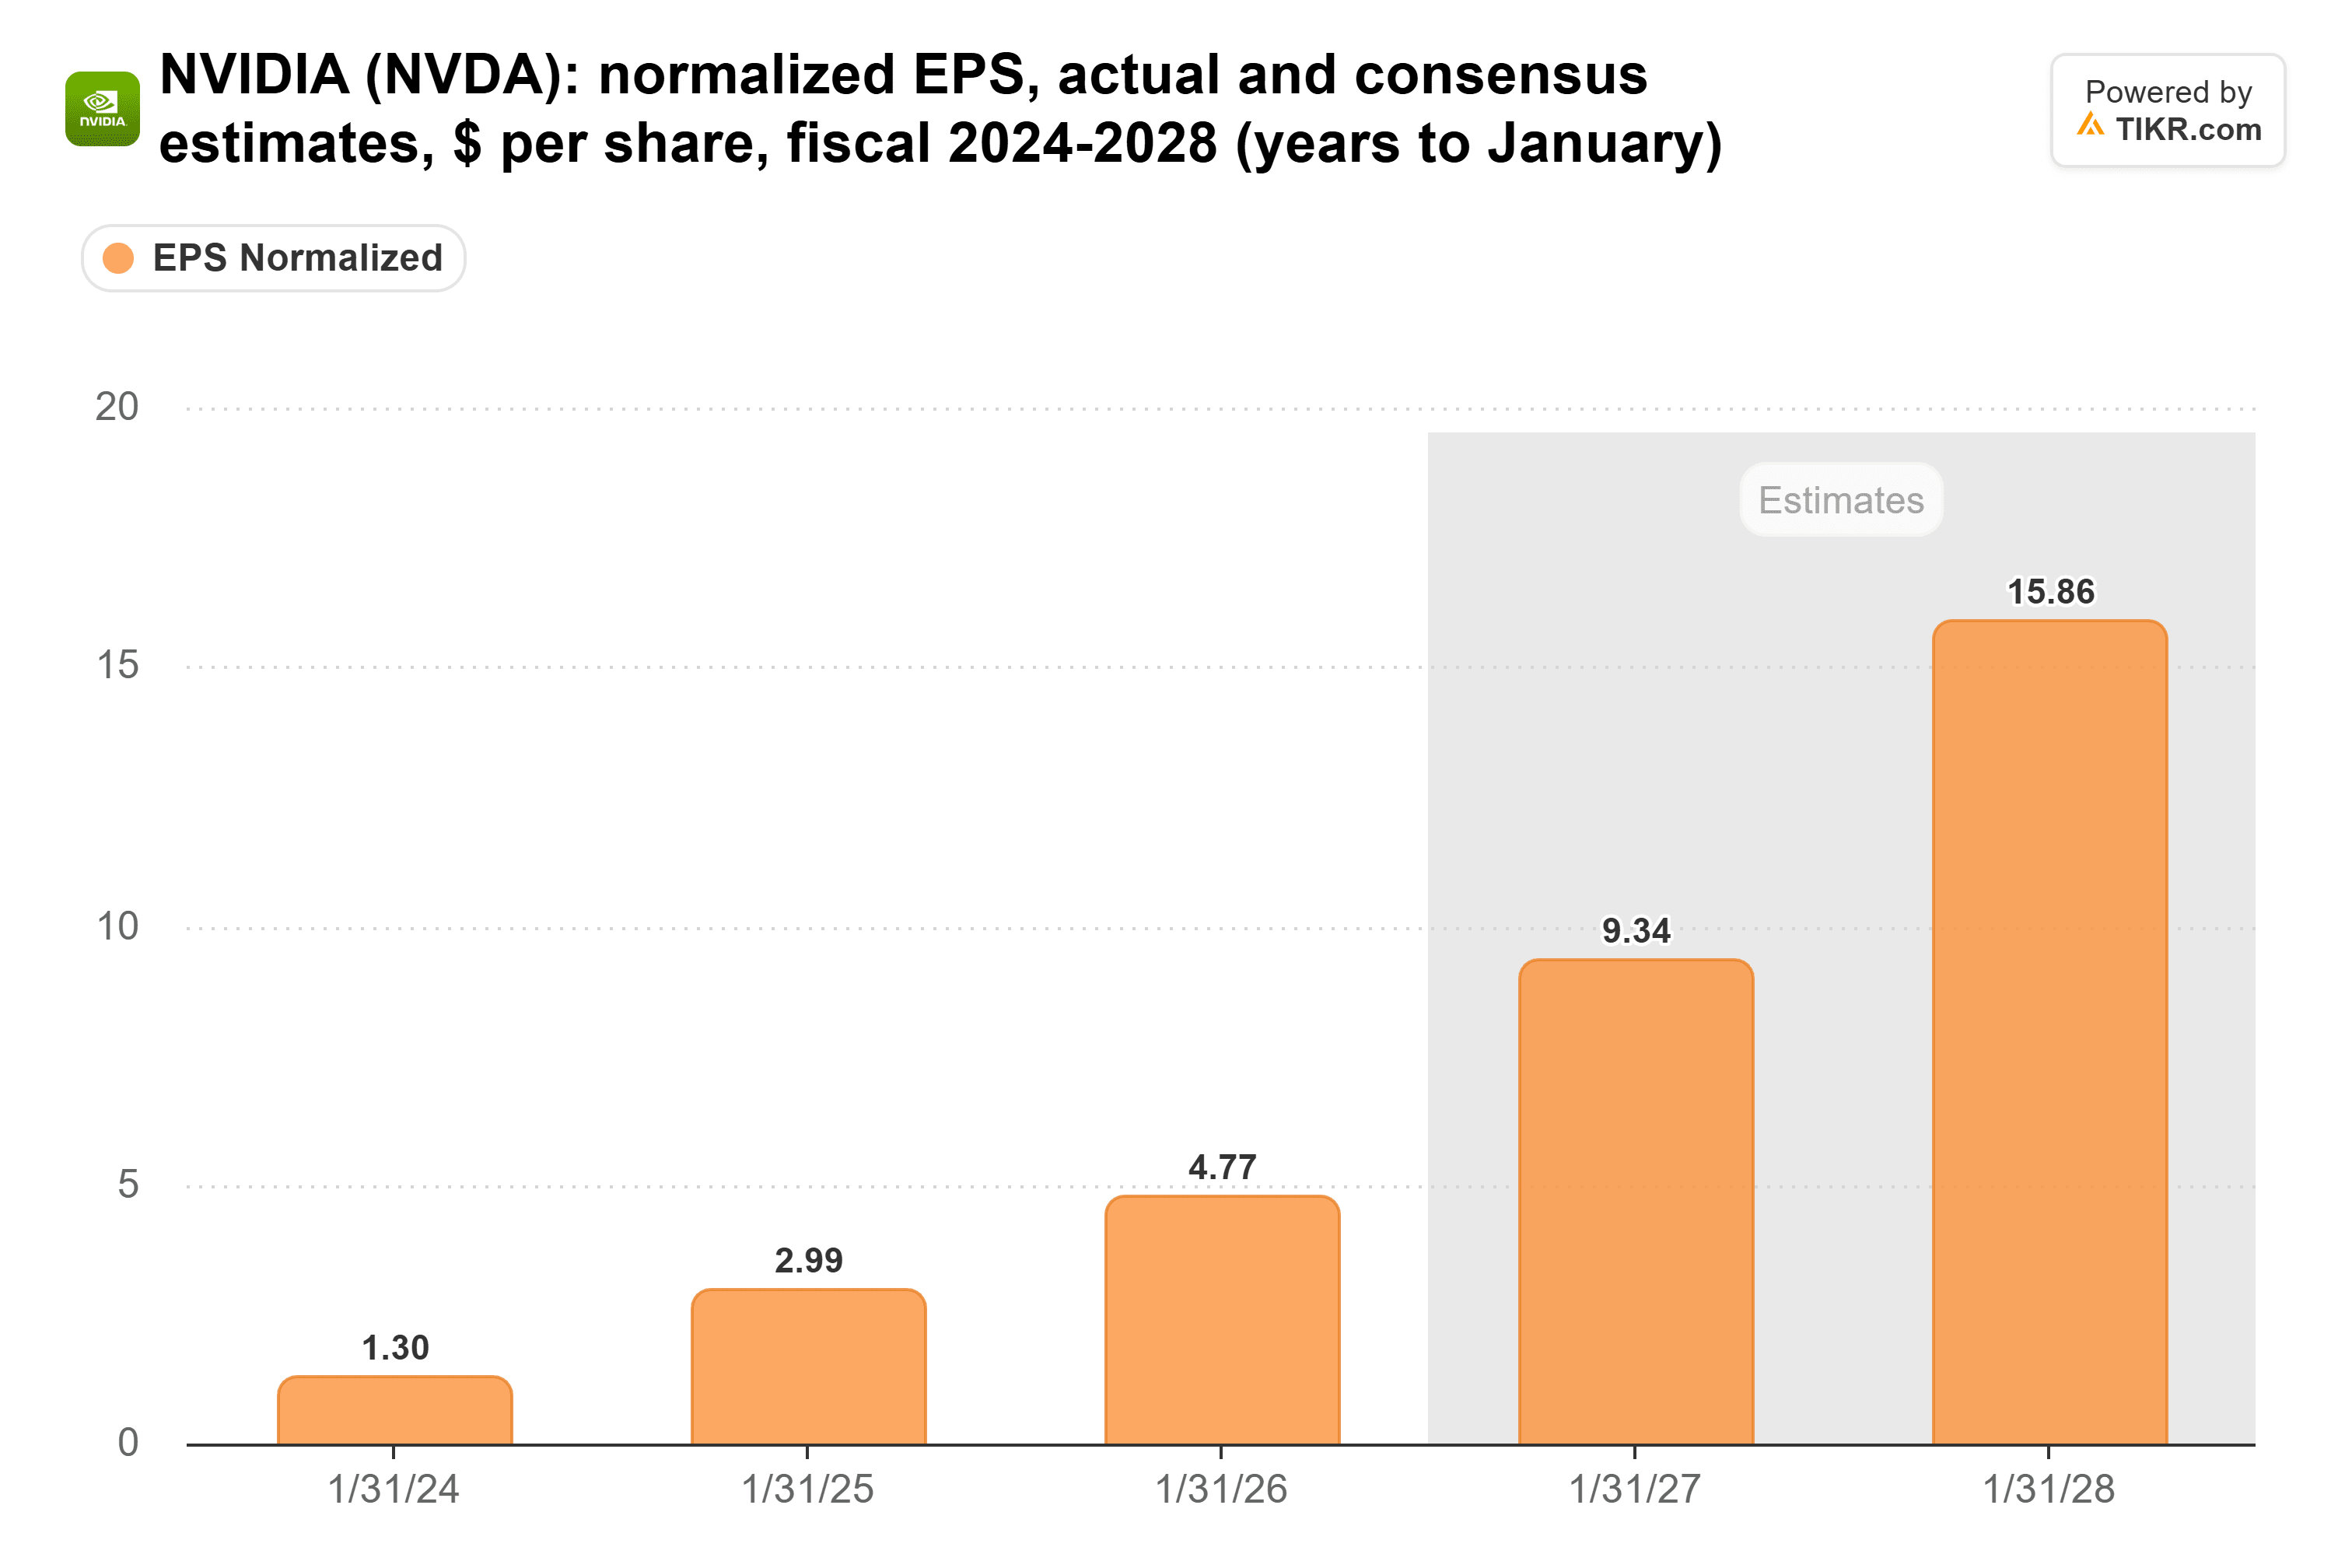
Earnings estimates didn’t follow. The fiscal 2028 consensus (the year ending January 2028) is $15.84 a share, against $15.91 a month ago and $12.85 three months ago:
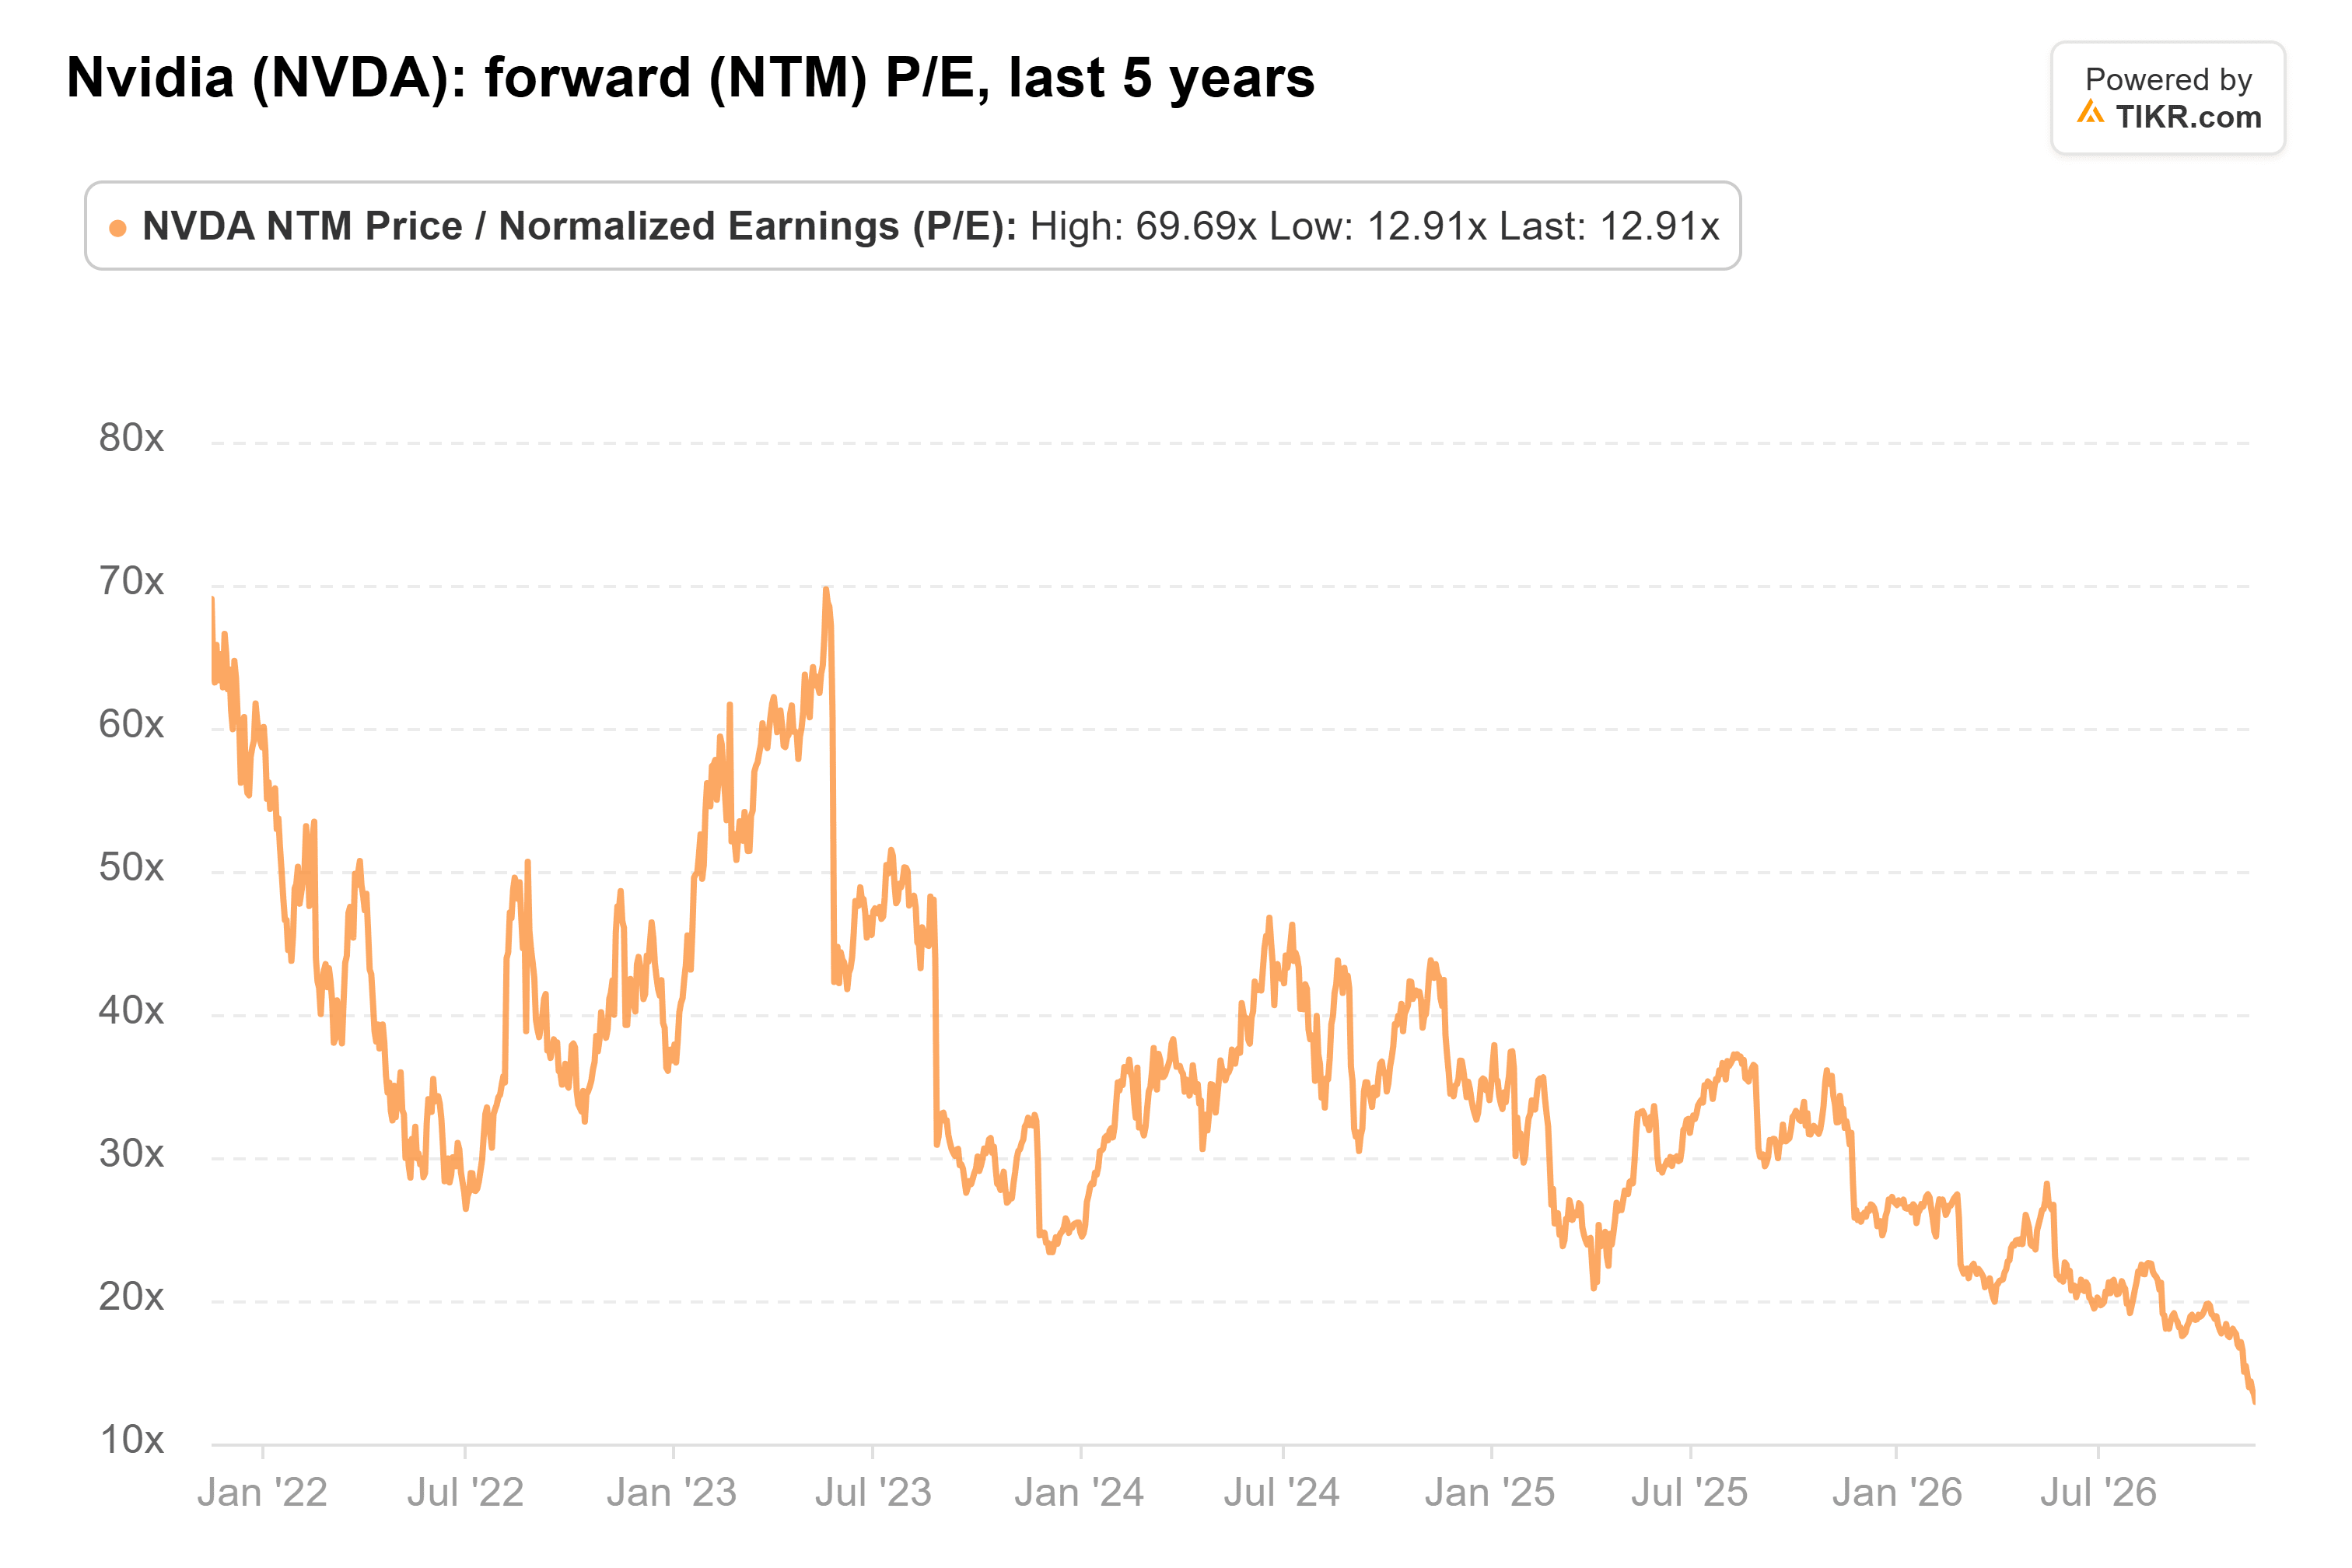
So the market is paying less for the same earnings. At 13x, NVIDIA trades at its lowest forward multiple in five years, against a five-year average of 36x:
What NVIDIA’s Report Has to Show
The risk sits inside those estimates. They rest on the roughly 70% fiscal 2028 revenue growth Kress guided to in August, and she expects AI lab demand backed by NVIDIA’s balance sheet to make up “roughly a quarter of our business next year.”
Still, Bank of America’s call looks right to me. At 13x, the stock already prices in a CEO search and Washington’s scrutiny, and $280 asks for less than NVIDIA’s own two-year median on estimates analysts have barely touched. Tuesday’s report needs three things: revenue at or above the $108.0 billion guide, a January-quarter gross margin guide no worse than the 71% to 72% floor Kress set in August, and a 70% growth outlook that survives Huang’s exit.
So What is NVIDIA Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!