Key Takeaways
- Of the 456 big funds that have filed 13Fs for the quarter ended Sept. 30, 13 bought Salesforce, including George Soros’ fund and Coatue, and 20 sold.
- Coatue’s new $1.84 billion stake is bigger than the cuts of all 20 sellers put together, and 8 of those sellers bought ExxonMobil in the same quarter.
- Salesforce trades at about 15x forward earnings, roughly half its five-year average, and analysts expect its earnings per share to keep growing.
- The buyers look right. Salesforce’s third-quarter report in early December will show whether organic growth is picking up from 6%.
Big funds can’t agree on Salesforce (CRM). Of the 456 that have filed 13Fs for the quarter ended Sept. 30 (funds readers know, or ones holding $1 billion or more of US stocks, with quant and index funds left out), 13 bought it, either by opening a stake or by adding 20% or more, and 20 sold out or cut their stake by 20% or more.
In all, 50 of those funds held Salesforce at the quarter’s end. And 8 of the 20 sellers bought ExxonMobil (XOM) in the same quarter. ExxonMobil is a cheaper stock, but analysts expect its earnings to shrink.
Coatue’s bet outweighs all the selling
Philippe Laffont’s Coatue, a hedge fund whose firm manages $92.71 billion, opened an 8.03 million-share Salesforce stake worth $1.84 billion at quarter-end prices, according to its 13F for the quarter ended Sept. 30, filed Nov. 16. That’s 3.4% of its 13F stocks and its 12th-biggest position. Soros Fund Management bought much less. Its 13F, filed Nov. 13, holds $6.48 billion of US stocks and shows a new stake of 65,193 shares worth $15 million, its 87th-biggest position at 0.2%. Chris Davis’ Davis Advisors, Lee Ainslie’s Maverick Capital and Whale Rock Capital opened new positions too. All 20 sellers’ cuts, added up at quarter-end prices, come to less than a third of Coatue’s purchase.
TIKR tracks 56 analysts on Salesforce. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Salesforce, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Salesforce’s Analyst Ratings
The biggest seller is still a big holder
Darlington Partners Capital Management, whose firm manages $3.28 billion, made the biggest cut. It sold 49% of its shares, going from 1.56 million to 796,852, or about $176 million worth. Even so, Salesforce was still its seventh-biggest position at Sept. 30, at 8.3% of its 13F stocks. ARGA Investment Management ($24.57 billion under management) cut its stake 94%, about $94 million worth. Mondrian Investment Partners ($49.31 billion) cut its stake 47%, about $71 million worth.
Mondrian is also one of the 8 sellers that bought ExxonMobil. It opened a stake of 335,547 shares worth $55 million, 1.0% of its 13F stocks. At about 12x forward earnings, ExxonMobil is cheaper. But analysts expect its normalized EPS to fall every year from 2026 through 2029, after a year when the war with Iran pushed up oil prices. Its average analyst target of $184 is only 10% above its share price. So far, ExxonMobil has done better since the quarter ended: it’s up 3% since Sept. 30, and Salesforce is down 6%.
At 15x, Salesforce is cheap
Salesforce’s earnings are expected to keep growing. Its normalized EPS was $12.52 in the year ended January 2026, and analysts expect $16.75 for the year ending January 2027 and $18.46 for the year ending January 2029:
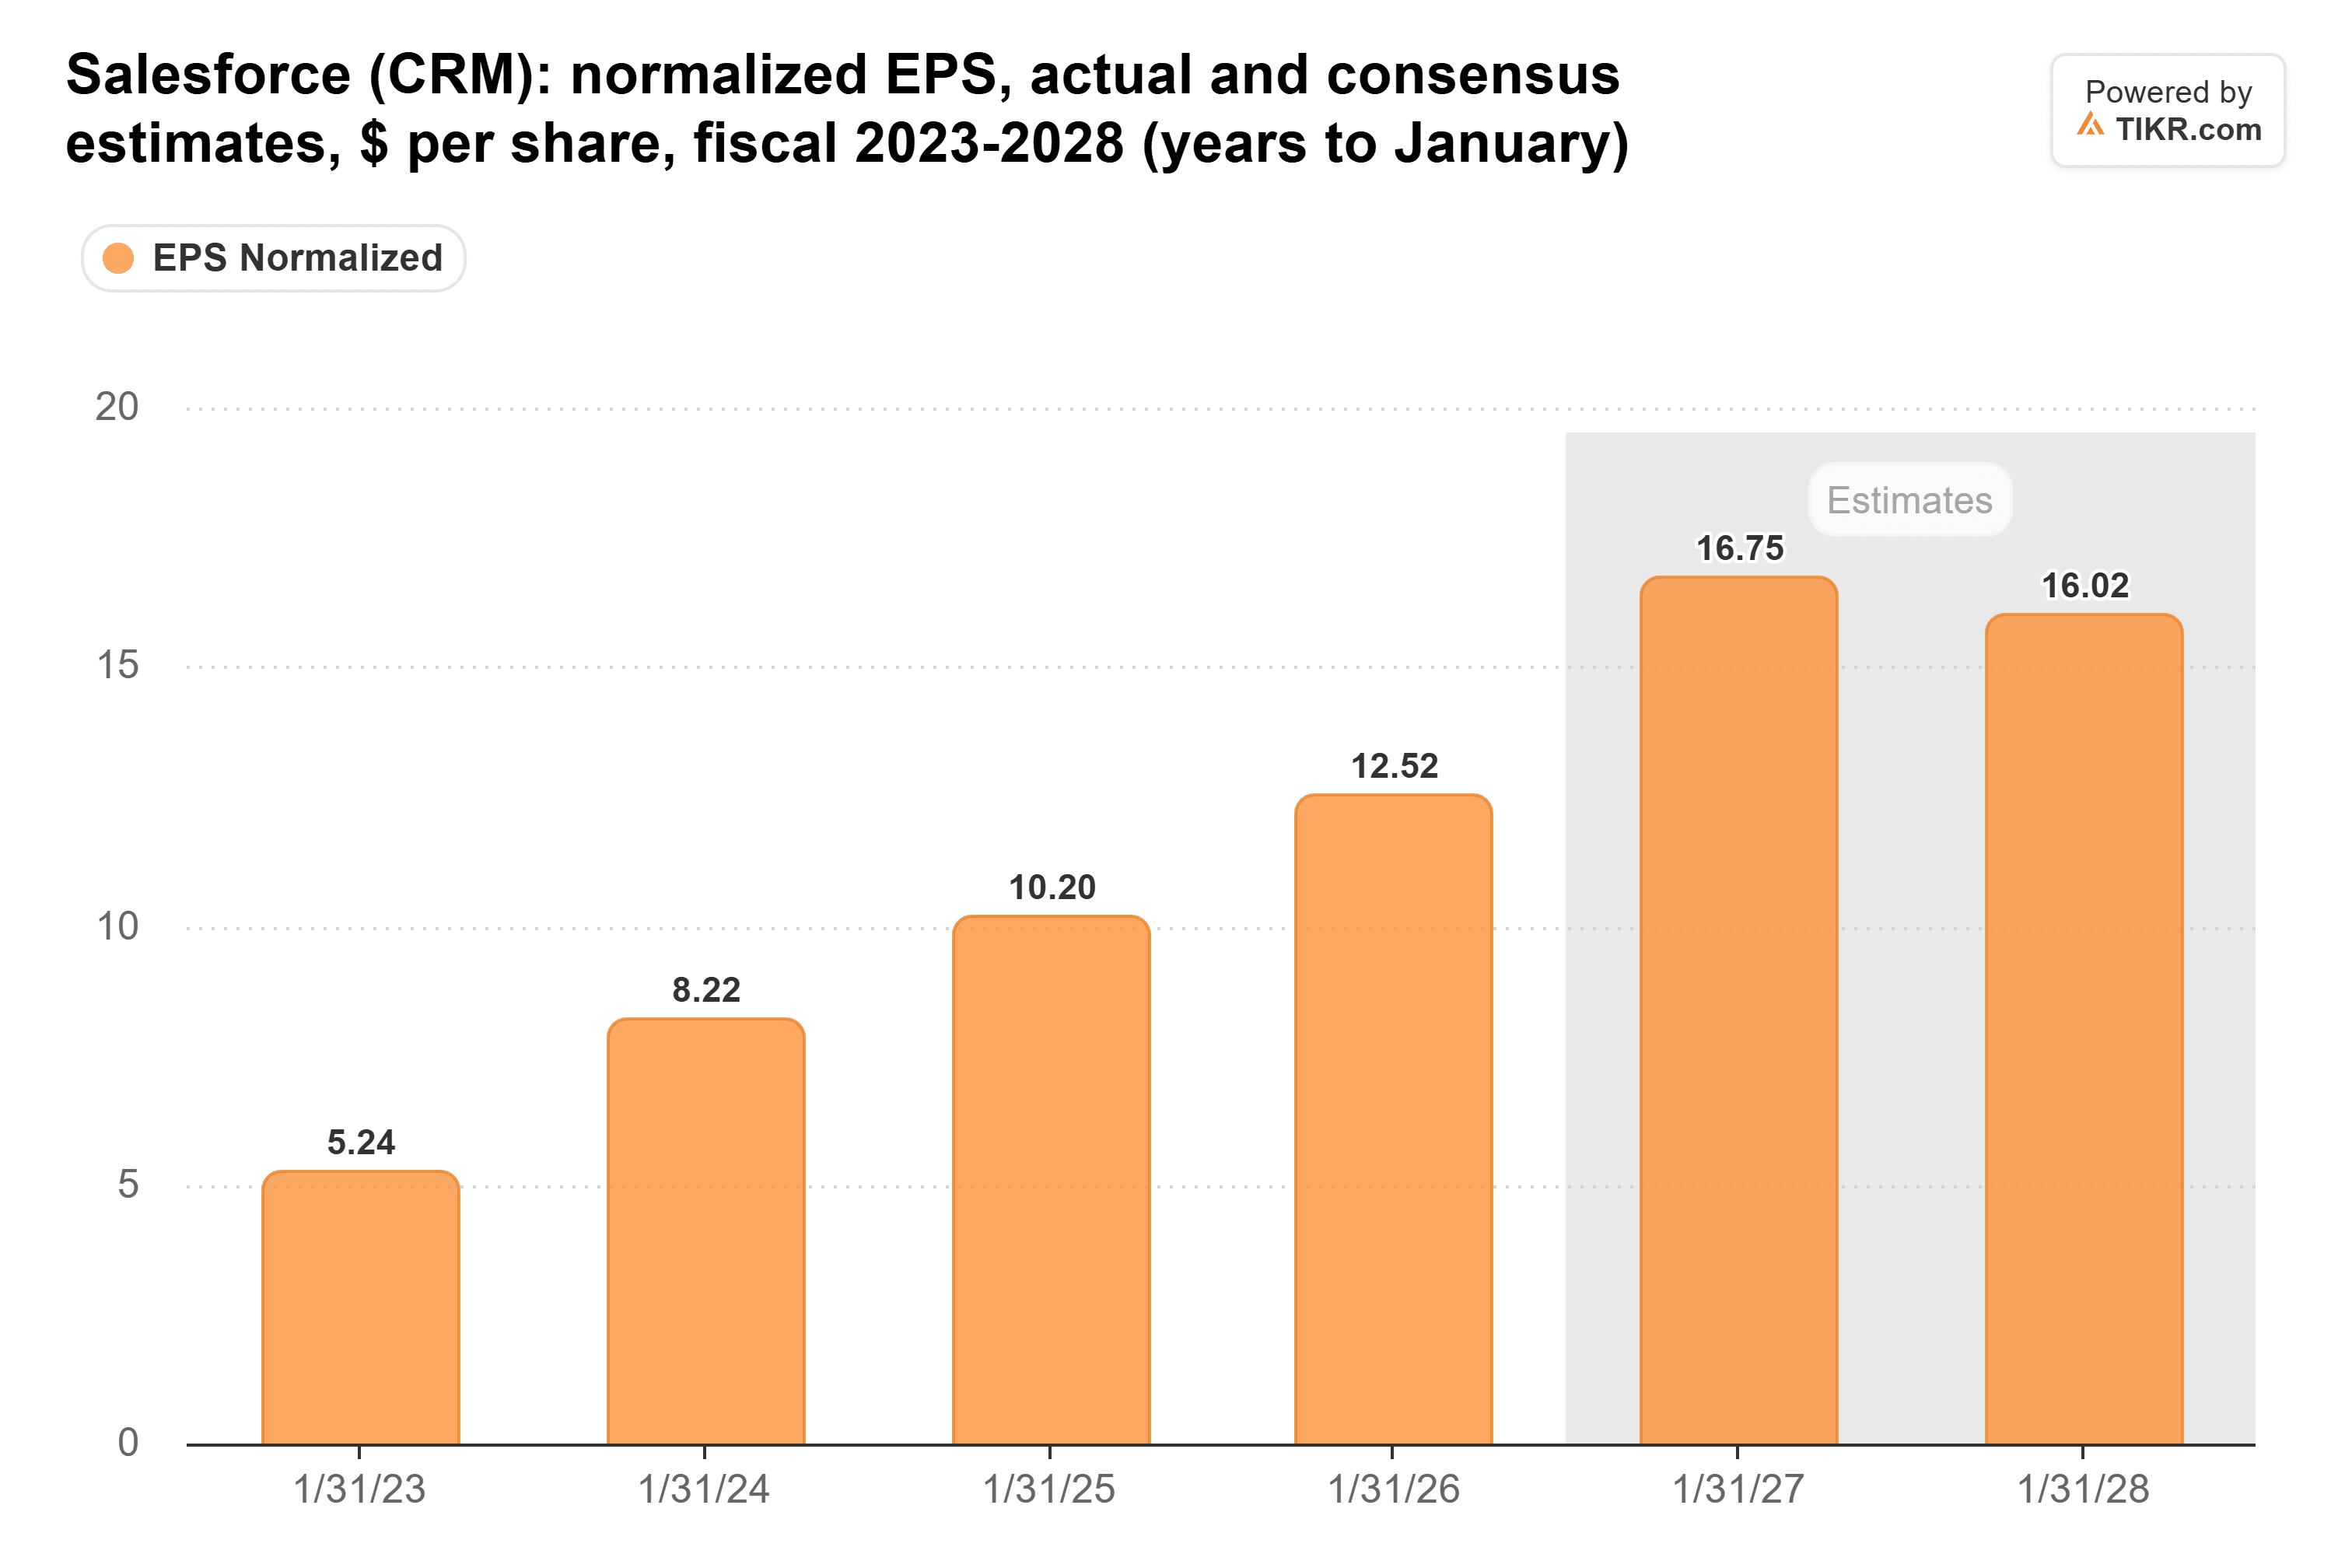
The dip in between comes from this year’s gains on Salesforce’s investments, mostly its stake in Anthropic. Take out the first half’s gains, and the $16.02 analysts expect for the year ending January 2028 is 17% above management’s guidance for this year.
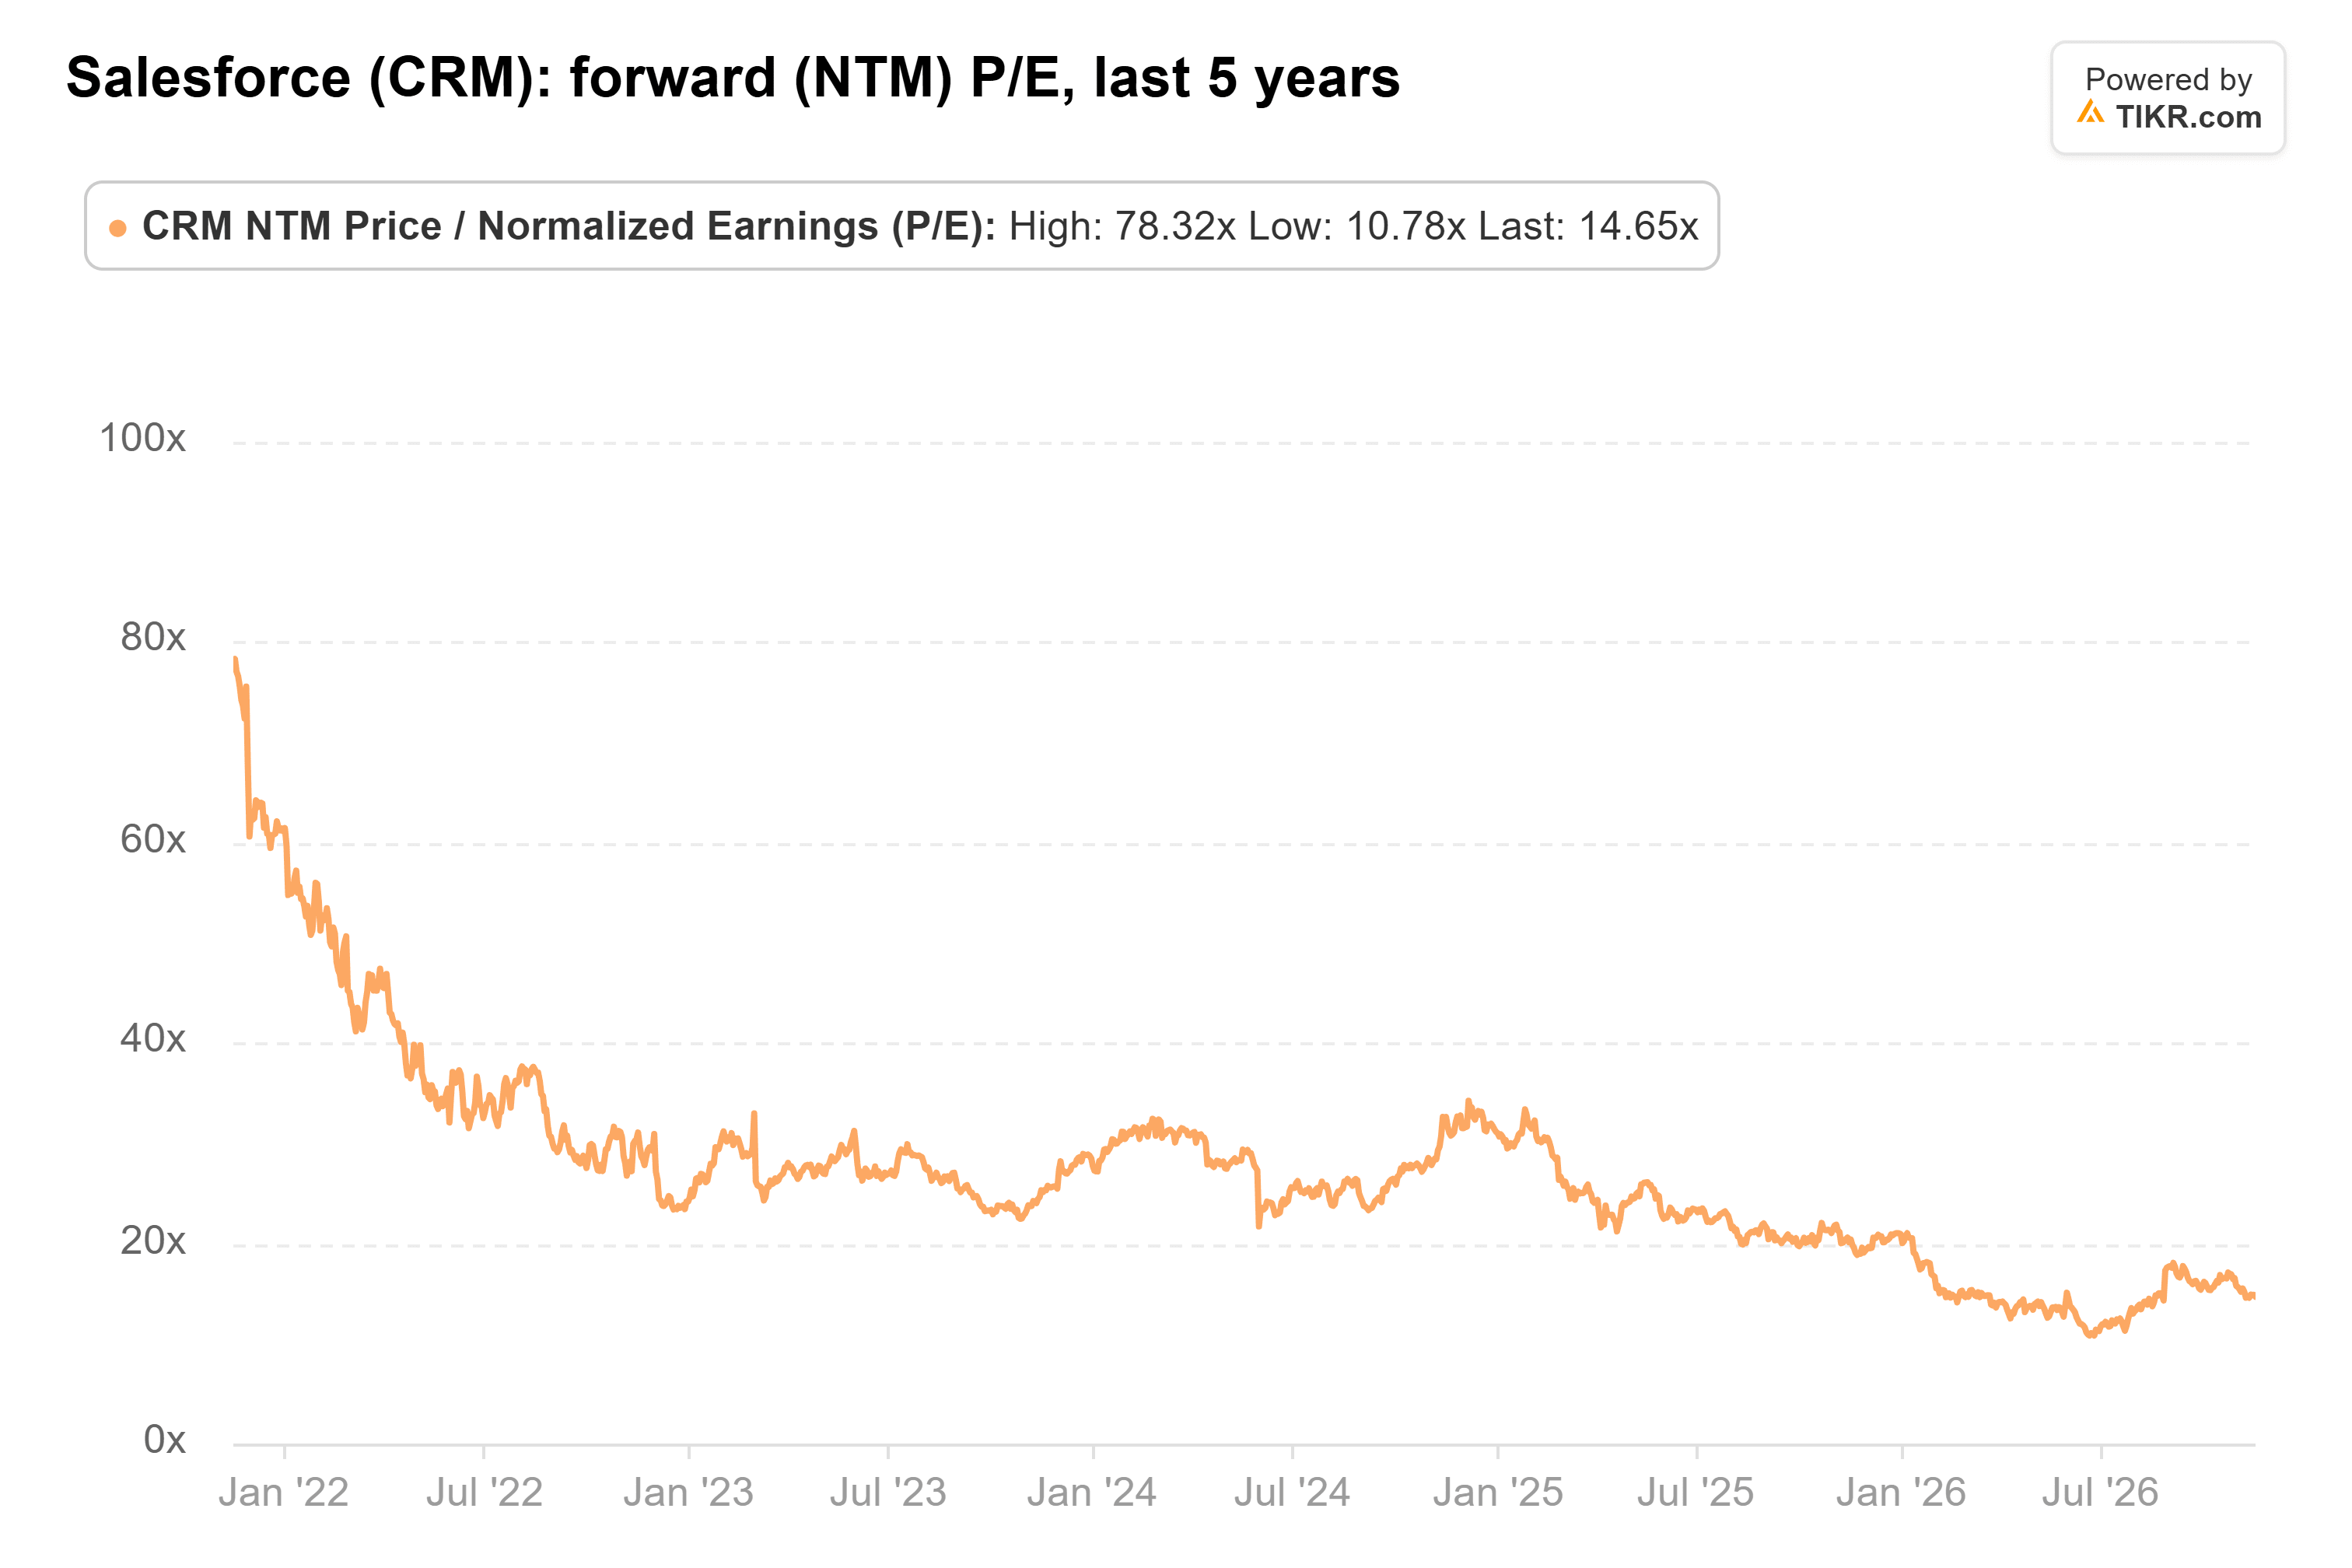
Even so, investors are paying far less for those earnings than they used to. Salesforce trades at 15x forward earnings. Its five-year average is 27x, and it hit a low of 11x in June:
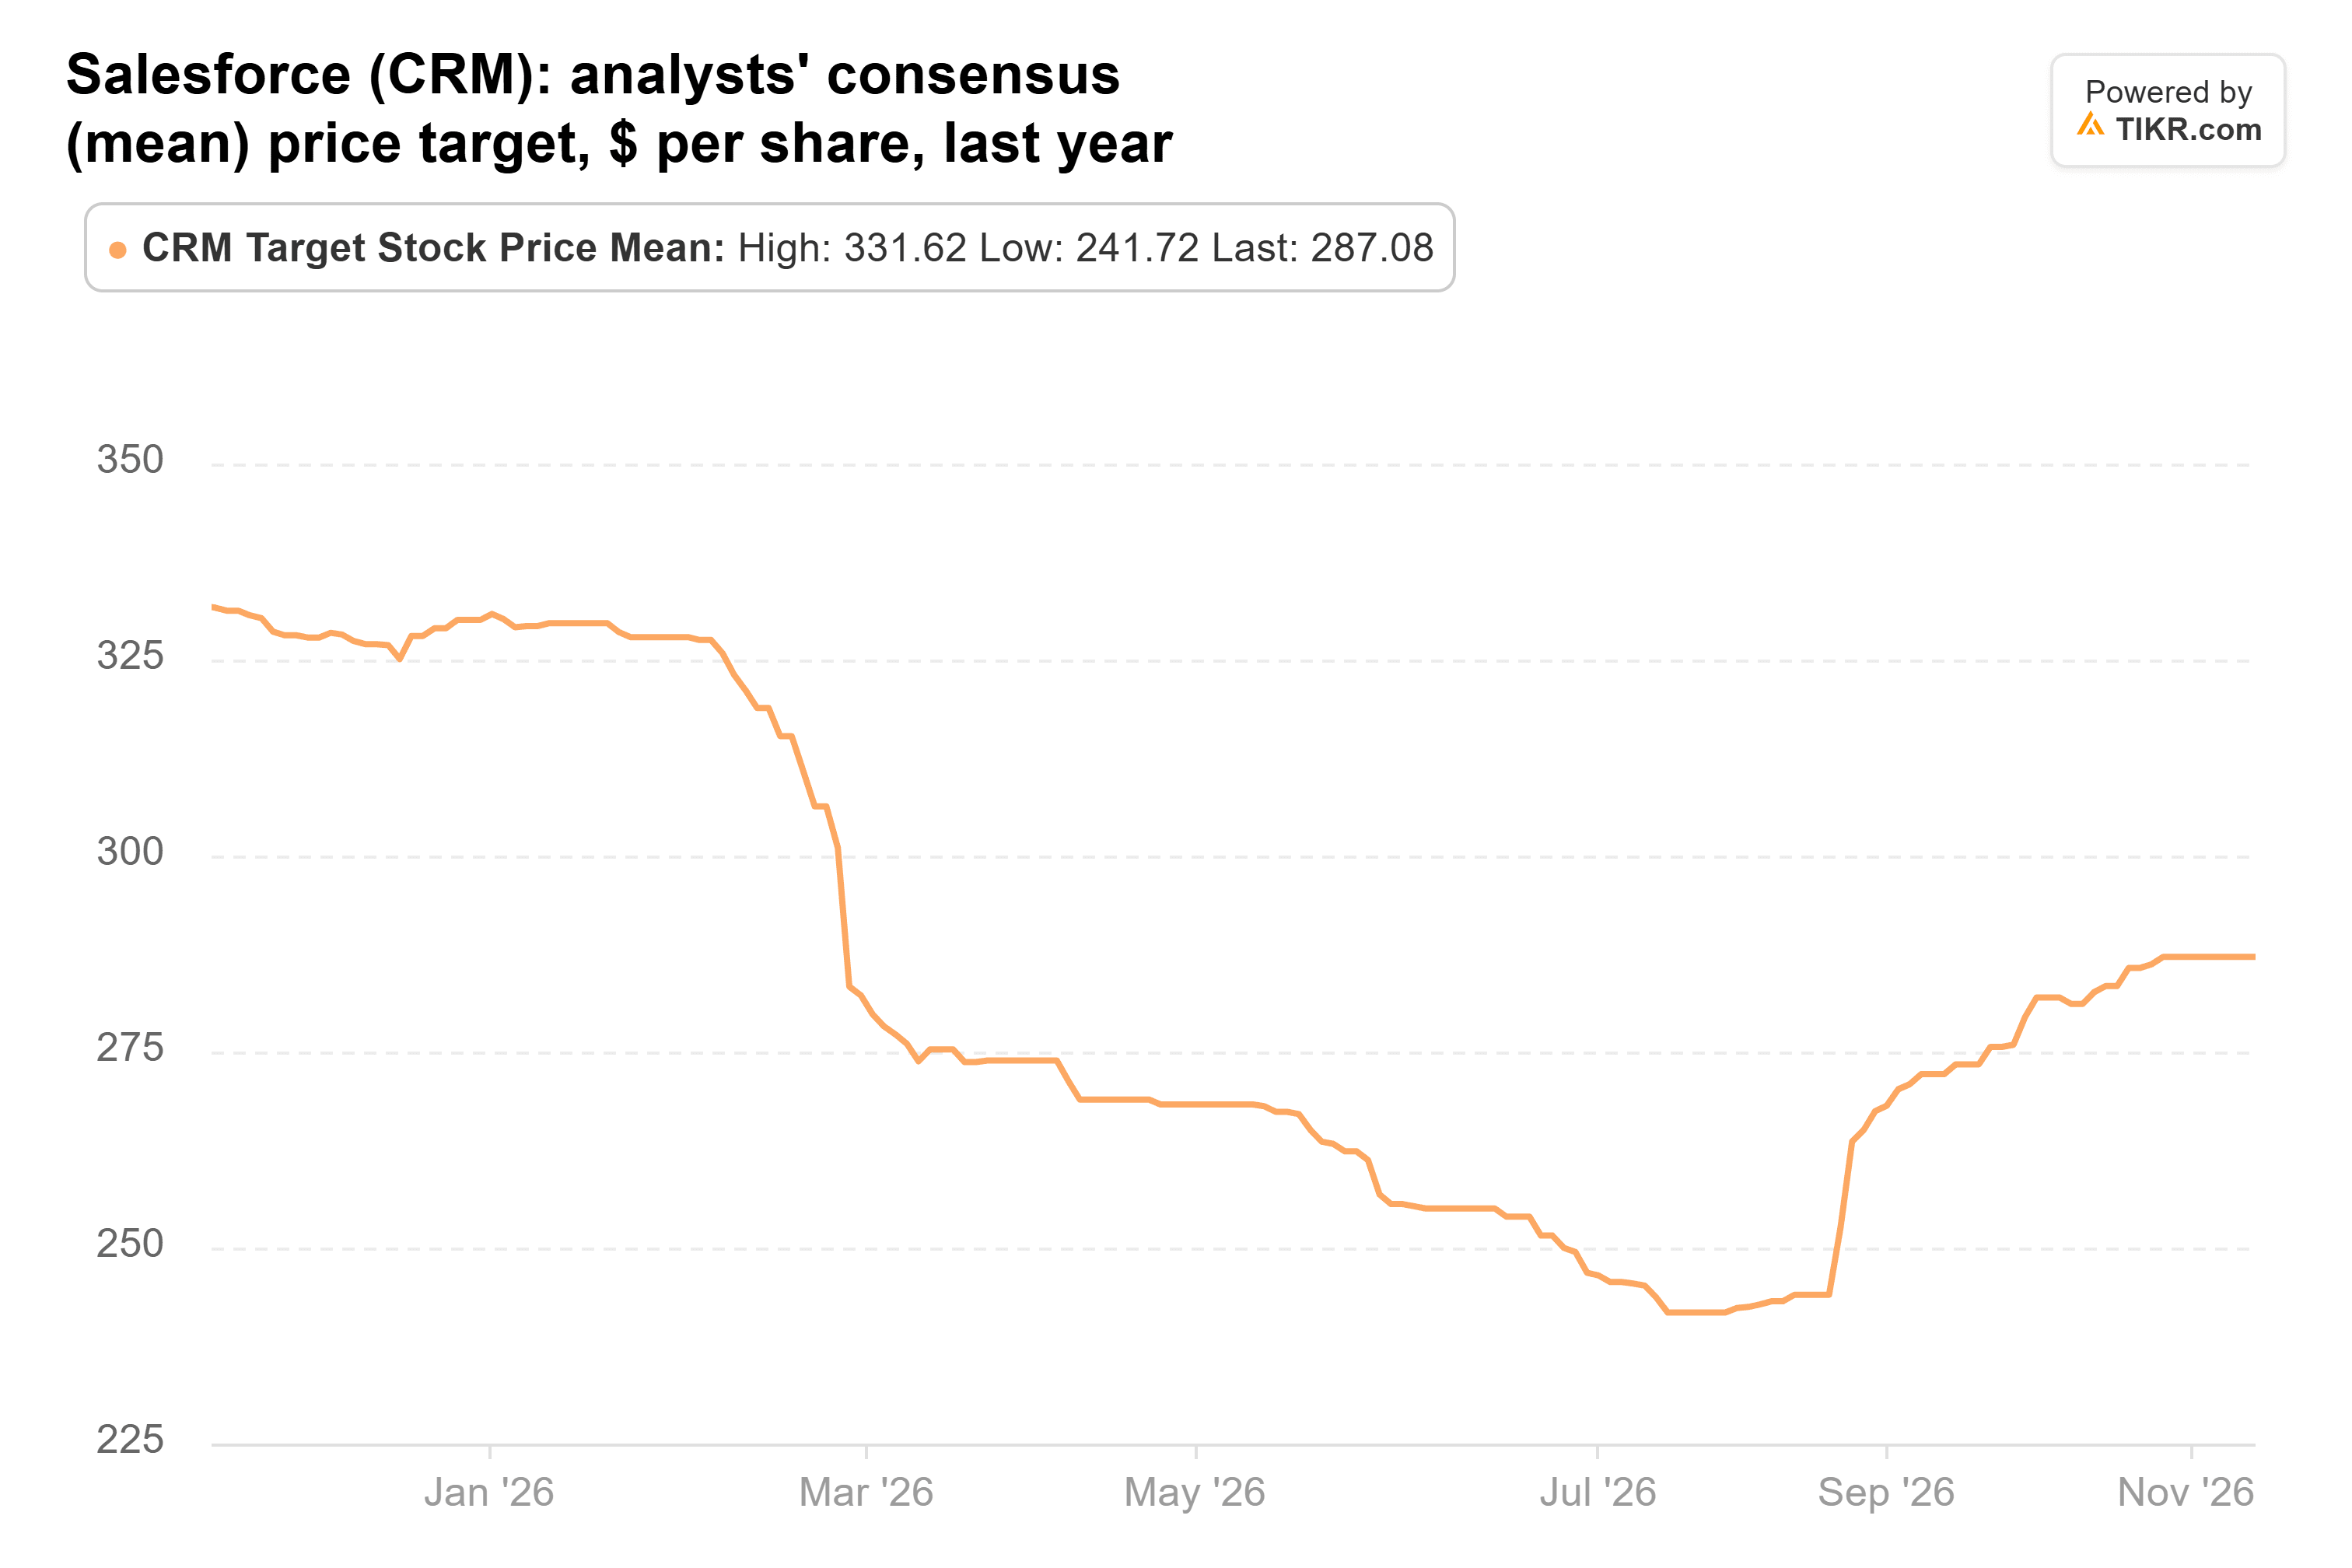
The 56 analysts who cover the stock have an average price target of $287, 34% above the current price. That target has recovered from a low of $242 in July, though it’s still below the $332 of a year ago:
The buyers look right
The sellers have good reasons to worry. Revenue rose 11% in the second quarter of fiscal 2027, but only 6% without the Informatica acquisition. Debt rose from $14.5 billion at Jan. 31 to $39.5 billion at July 31 to pay for a $25 billion buyback, and S&P cut Salesforce’s rating to A from A+ on Nov. 4, citing its deals and shareholder returns.
But at 15x earnings that analysts expect to grow, the stock already prices in a lot of that doubt. ExxonMobil’s lower multiple comes with earnings that analysts expect to fall. I’d side with the buyers, and Coatue’s big bet looks like the better call.
Salesforce’s third-quarter report in early December is the next test. Management expects revenue to grow 11% to 12%, with a little over 4 points of that from Informatica, which would put organic growth above the second quarter’s 6%. If growth stays near 6%, the sellers will have made the better call. The funds’ next 13Fs, due in mid-February, will show which side added.
So what is Salesforce stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Salesforce could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!