Key Takeaways
- Jim Cramer said Amazon could sell its Anthropic stake and have its capex “paid for for the next year and a half.”
- The Anthropic shares Amazon owns outright were worth about $188 billion at the first-day close, about 10 months of this year’s capex.
- Amazon only needs to cover its free cash flow shortfall, about $65 billion across 2026 and 2027, and those shares cover it more than twice over.
- Andy Jassy says Amazon will hold the stake. It’s a backstop, and its value, like Salesforce’s, now moves with Anthropic’s stock.
Anthropic’s IPO made Amazon (AMZN) one of the market’s biggest winners on paper, and Jim Cramer has an idea for what to do with the winnings.
Anthropic (ANT) closed its first day of trading Thursday at $97.17, 17% above its $83 IPO price, then fell 8.5% to $88.91 on Friday as AI stocks sold off. On Squawk on the Street, CNBC’s Cramer laid out the math:
“that number of their ownership in Anthropic is more than equivalent to what they’re going to spend in CapEx. They could actually sell the stake and say, hey, our CapEx is paid for for the next year and a half.”
That would be quite the trick. CEO Andy Jassy told CNBC’s Halftime Report on Nov. 17 that “we expect to spend around $220 billion this year in CapEx and that we expect to spend meaningfully more next year.”
Free cash flow has gone negative
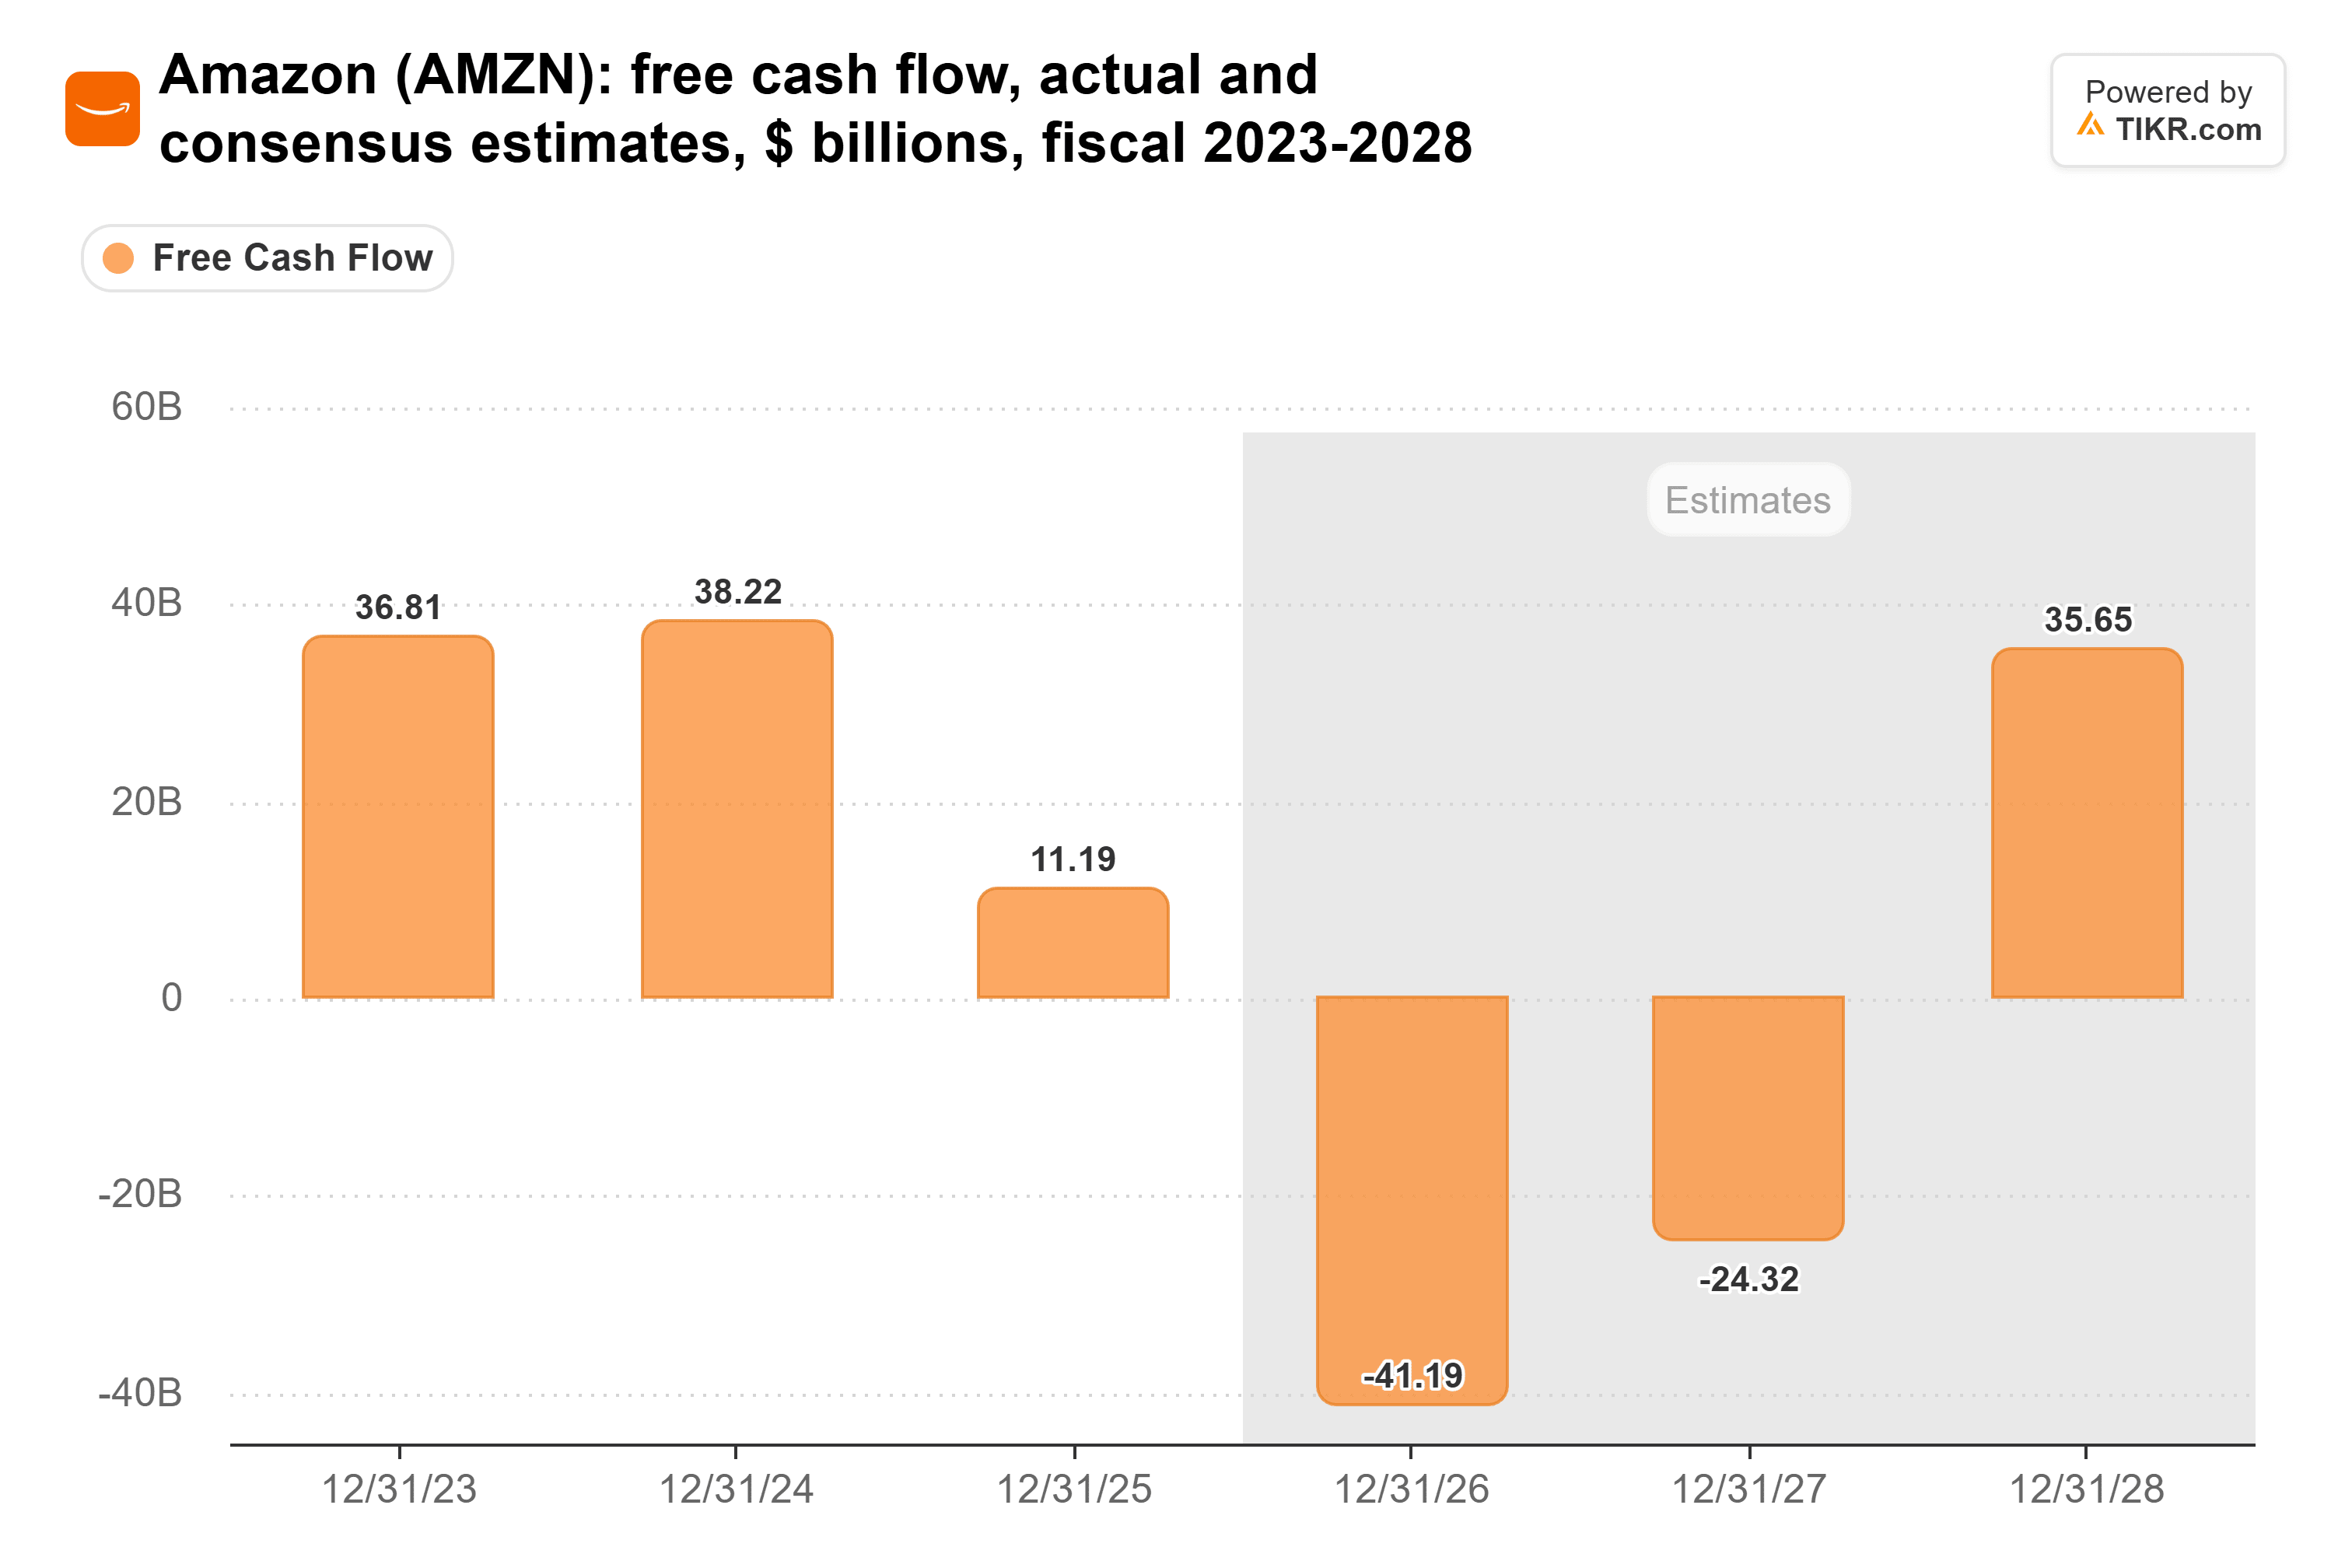
That spending has already pushed Amazon’s free cash flow below zero. Analysts don’t expect it to turn positive again until 2028:
So far, Amazon has filled the gap mostly by borrowing. Its long-term debt rose from $65.6 billion at the end of 2025 to $173.1 billion at Sept. 30, more than doubling in nine months.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Cramer counts the notes
After the IPO, Amazon owns 14.6% of Anthropic outright. At the first-day close, those shares were worth about $188 billion, roughly 10 months of this year’s capex.
Cramer’s figure is 23.6%, because it also counts convertible notes Amazon hasn’t converted, held back under an ownership cap it has chosen not to waive. At the $1.5 trillion valuation he used, that’s about $354 billion, or about 19 months of spending at this year’s pace.
But Amazon’s capex has more than doubled in five years:
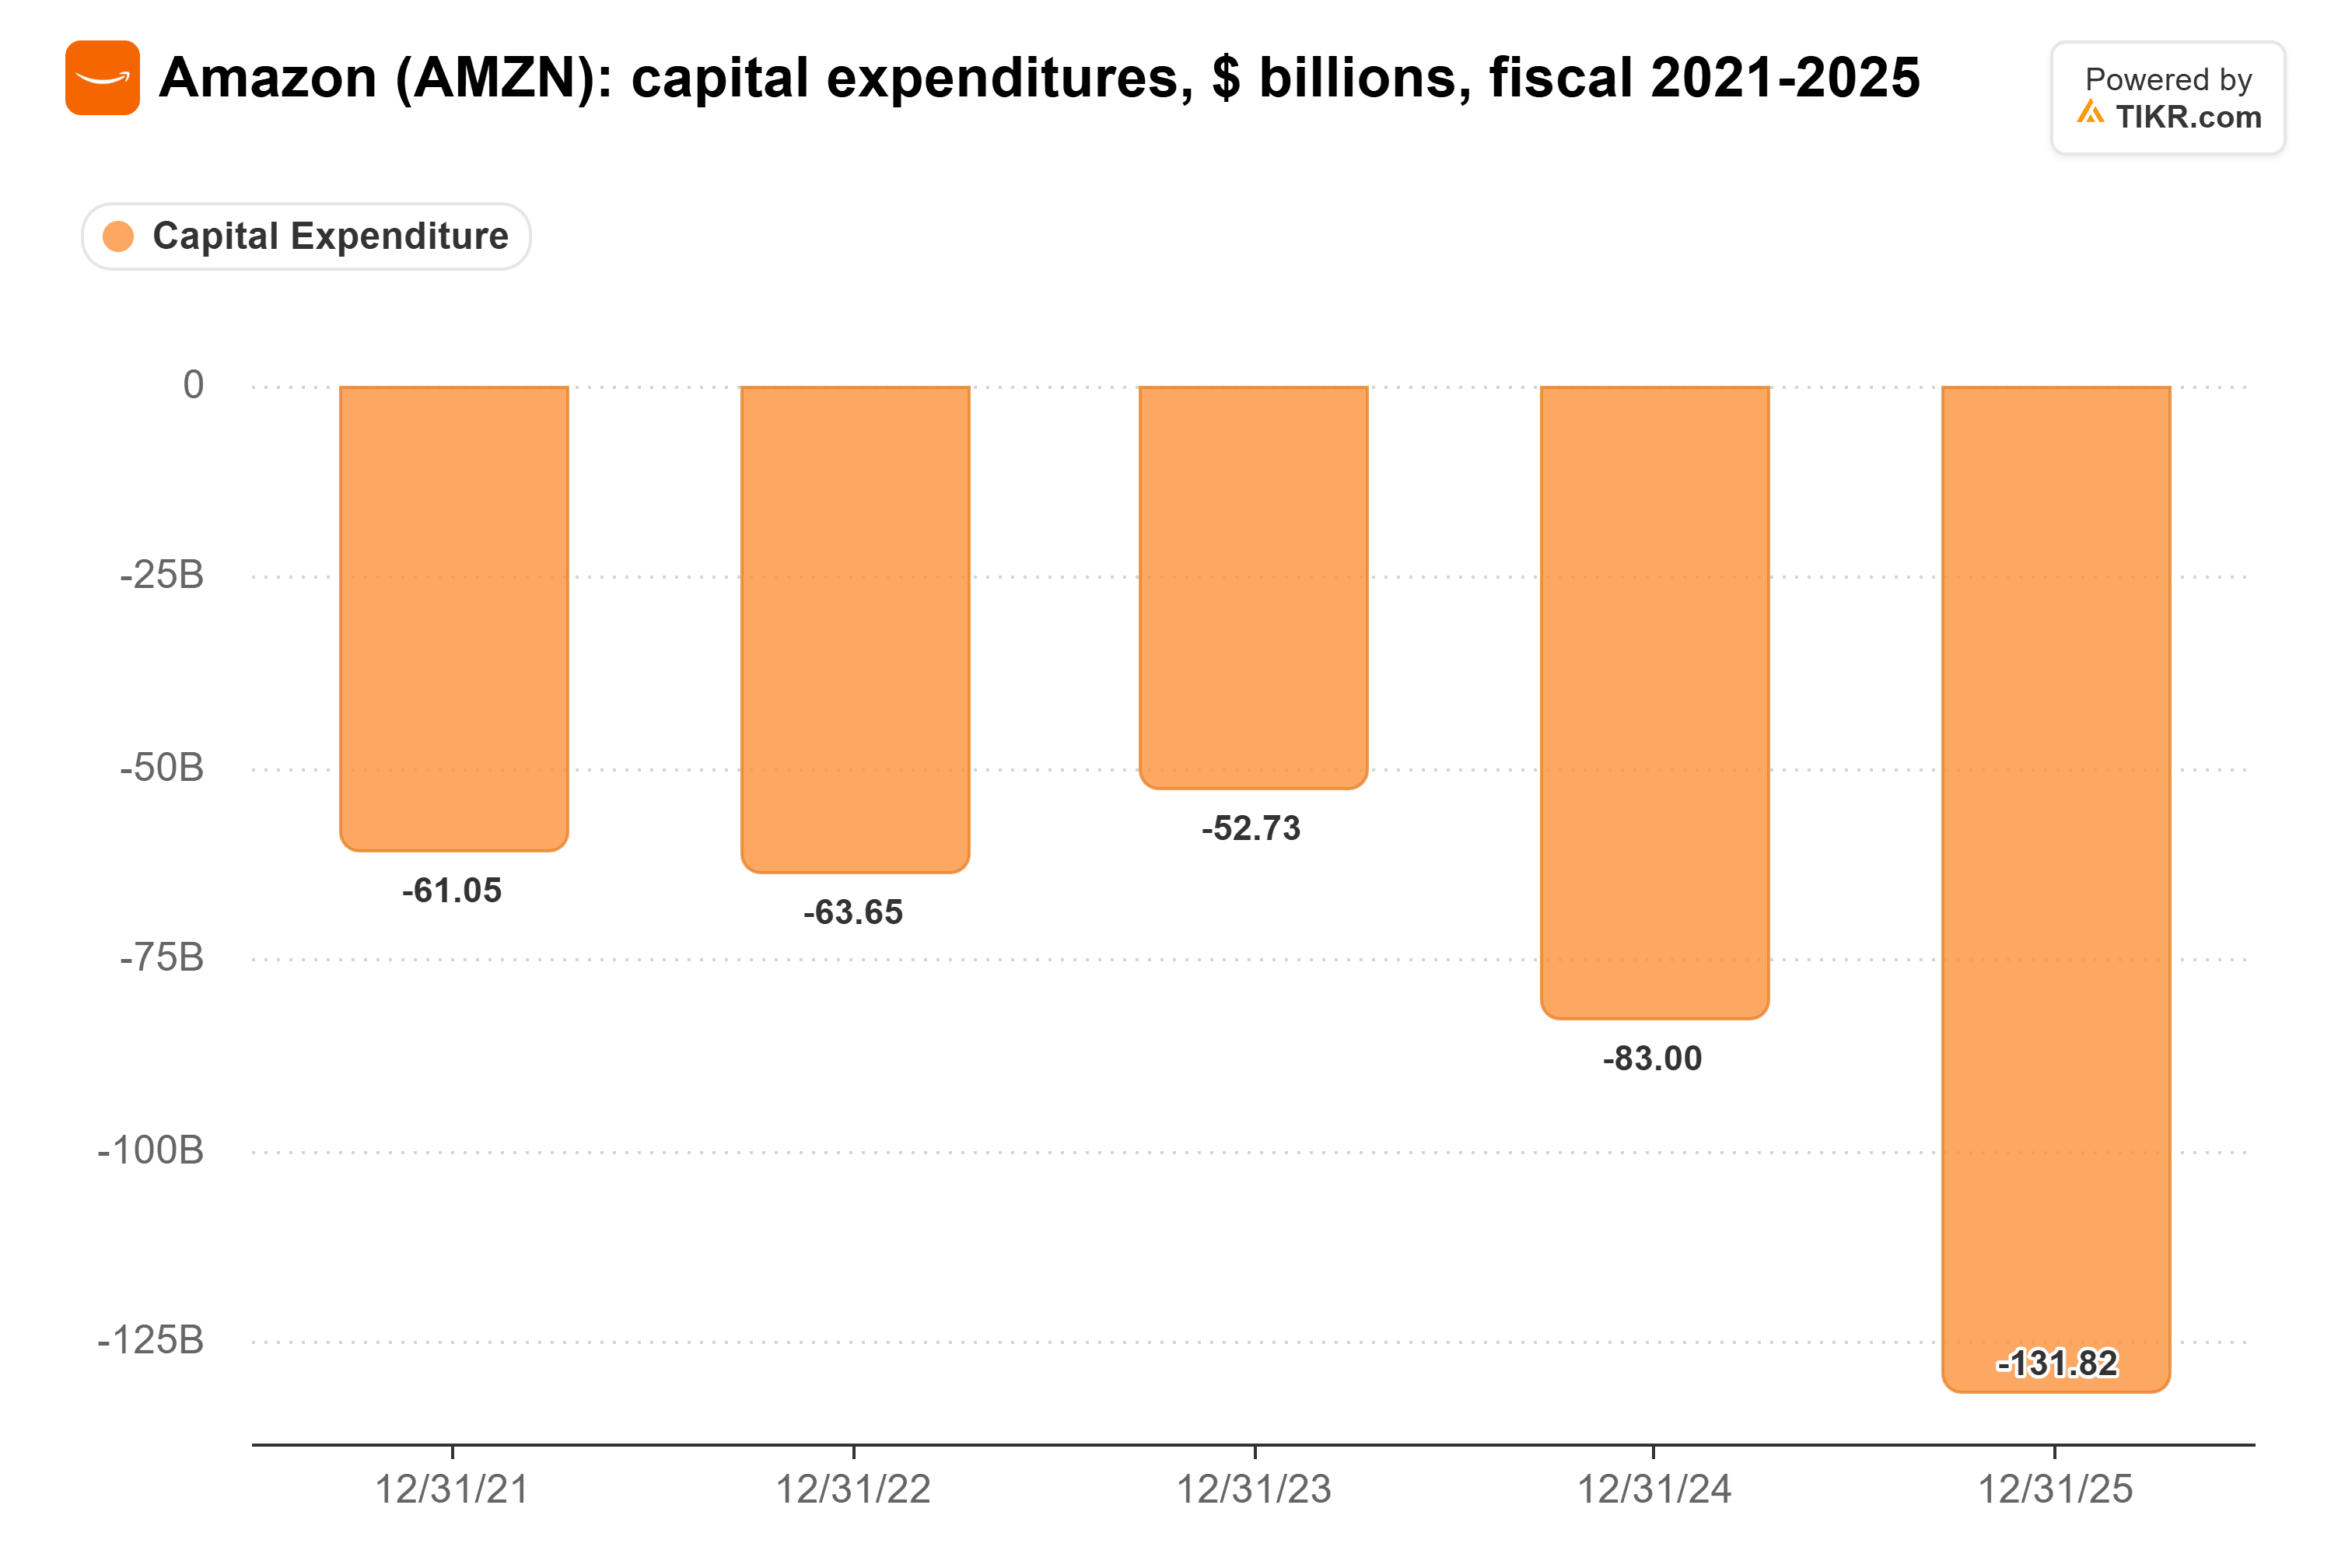
Analysts expect $278.2 billion in 2027, and at that pace even Cramer’s $354 billion covers only about 15 months.
Amazon only needs to fill the gap
Amazon also wouldn’t need the stake to pay for the whole build-out. Operating cash flow covers most of it: $168.3 billion over the 12 months to Sept. 30, against about $210.7 billion of capex net of proceeds and incentives. Amazon only has to fund the shortfall on the free cash flow chart above, which consensus puts at $41.2 billion this year and $24.3 billion next year, about $65 billion in all. Even after Friday’s drop, the shares Amazon owns outright, worth about $172 billion at the close, cover that more than twice over.
The catch: Amazon says it isn’t selling. Jassy told the Halftime Report that “we’re believers in Anthropic and we invested not to turn around and make a quick buck on it in a year.” Amazon put $18.0 billion into Anthropic, so almost all of any sale would also be a taxable gain.
Amazon isn’t alone. Salesforce (CRM) holds Anthropic shares through its venture arm, and its guidance assumes no change in their value, since it says it can’t forecast the gains or losses. Its Dec. 2 report covers the quarter that ended Oct. 31, before the listing, so the January quarter is its first with a market price for the stake, as the December quarter is for Amazon.
Cramer is a bit generous on the capex math but underselling the stake. Bridging two years of negative free cash flow with room to spare makes it a powerful backstop for a company borrowing this heavily, even if Jassy never sells a share.
Of course, the cushion shrinks with every down day for Anthropic, and a 2027 capex outlook well above the $278.2 billion consensus, due with fourth-quarter results in early February, would widen the gap.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!