Key Takeaways
- Anthropic fell 8.5% on its second day of trading and SpaceX dropped 7.7%, a day after SpaceX sold $32 billion of bonds to buy more AI chips.
- Venture capitalist Rory O’Driscoll says SpaceX stock rests on what Anthropic will pay it for compute a year from now, and SpaceX’s own figures back him up.
- Anthropic, SpaceX’s biggest compute renter ahead of Alphabet, can start ending its contracts on 90 days’ notice in early 2027.
- SpaceX’s 2027 revenue consensus of $180 billion depends on Anthropic buying more, and Amazon, another of Anthropic’s landlords, is tied to the same answer.
Anthropic (ANT) fell 8.5% on Nov. 20, its second day of trading, and SpaceX (SPCX) dropped 7.7% in a broad AI selloff. A day earlier, SpaceX sold $32 billion of bonds to buy more Nvidia chips, most of it at yields above 8%, Bloomberg reported.
Those two stocks are connected. Anthropic is SpaceX’s biggest compute customer. Alphabet (GOOG) is another big one: its Google unit agreed in June to pay SpaceX $920 million a month for compute. Anthropic also rents compute from Amazon (AMZN), which owns a stake in it.
On the Nov. 19 episode of 20VC, Scale Venture Partners general partner Rory O’Driscoll was asked whether he’d buy SpaceX. Not at this price, he said, because “it’s not about the rockets.” Then:
“You buy SpaceX the stock entirely on the basis of what you think [Anthropic] will be paying you one year from now for that compute. Will they be canceling it or will they be buying more? It’s the only question.”
That’s quite a claim about a rocket company.
TIKR tracks 40 analysts on SpaceX. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SpaceX, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SpaceX’s Analyst Ratings
Follow the rent
SpaceX’s latest quarter backs him up. Its Super Intelligence segment, which holds its compute rentals, brought in $7.56 billion of the third quarter’s $14.6 billion of revenue. One customer in that segment made up 34.5% of SpaceX’s total revenue. The 10-Q doesn’t name it, but Bloomberg reported on Oct. 29 that it’s Anthropic.
And Anthropic’s bill keeps growing. SpaceX’s prospectus put the original deal at $1.25 billion a month. Anthropic’s own IPO filing says that will rise to about $3.1 billion a month once all its capacity is delivered, which it expects in December. On CNBC’s Squawk on the Street, David Faber called it “a $3.1 billion a month bill that goes to SpaceX for compute.” Multiply that by 12, and you get $37.2 billion a year, more than the $32.0 billion of revenue SpaceX booked over the past four quarters.
That bill isn’t locked in. Anthropic’s filing says either side can cancel each agreement on 90 days’ notice once their lock-in periods end in January and March 2027.
Wall Street is counting on a lot more
Analysts expect SpaceX’s revenue to jump from $48.8 billion this year to $180 billion in 2027 and $333 billion in 2028:
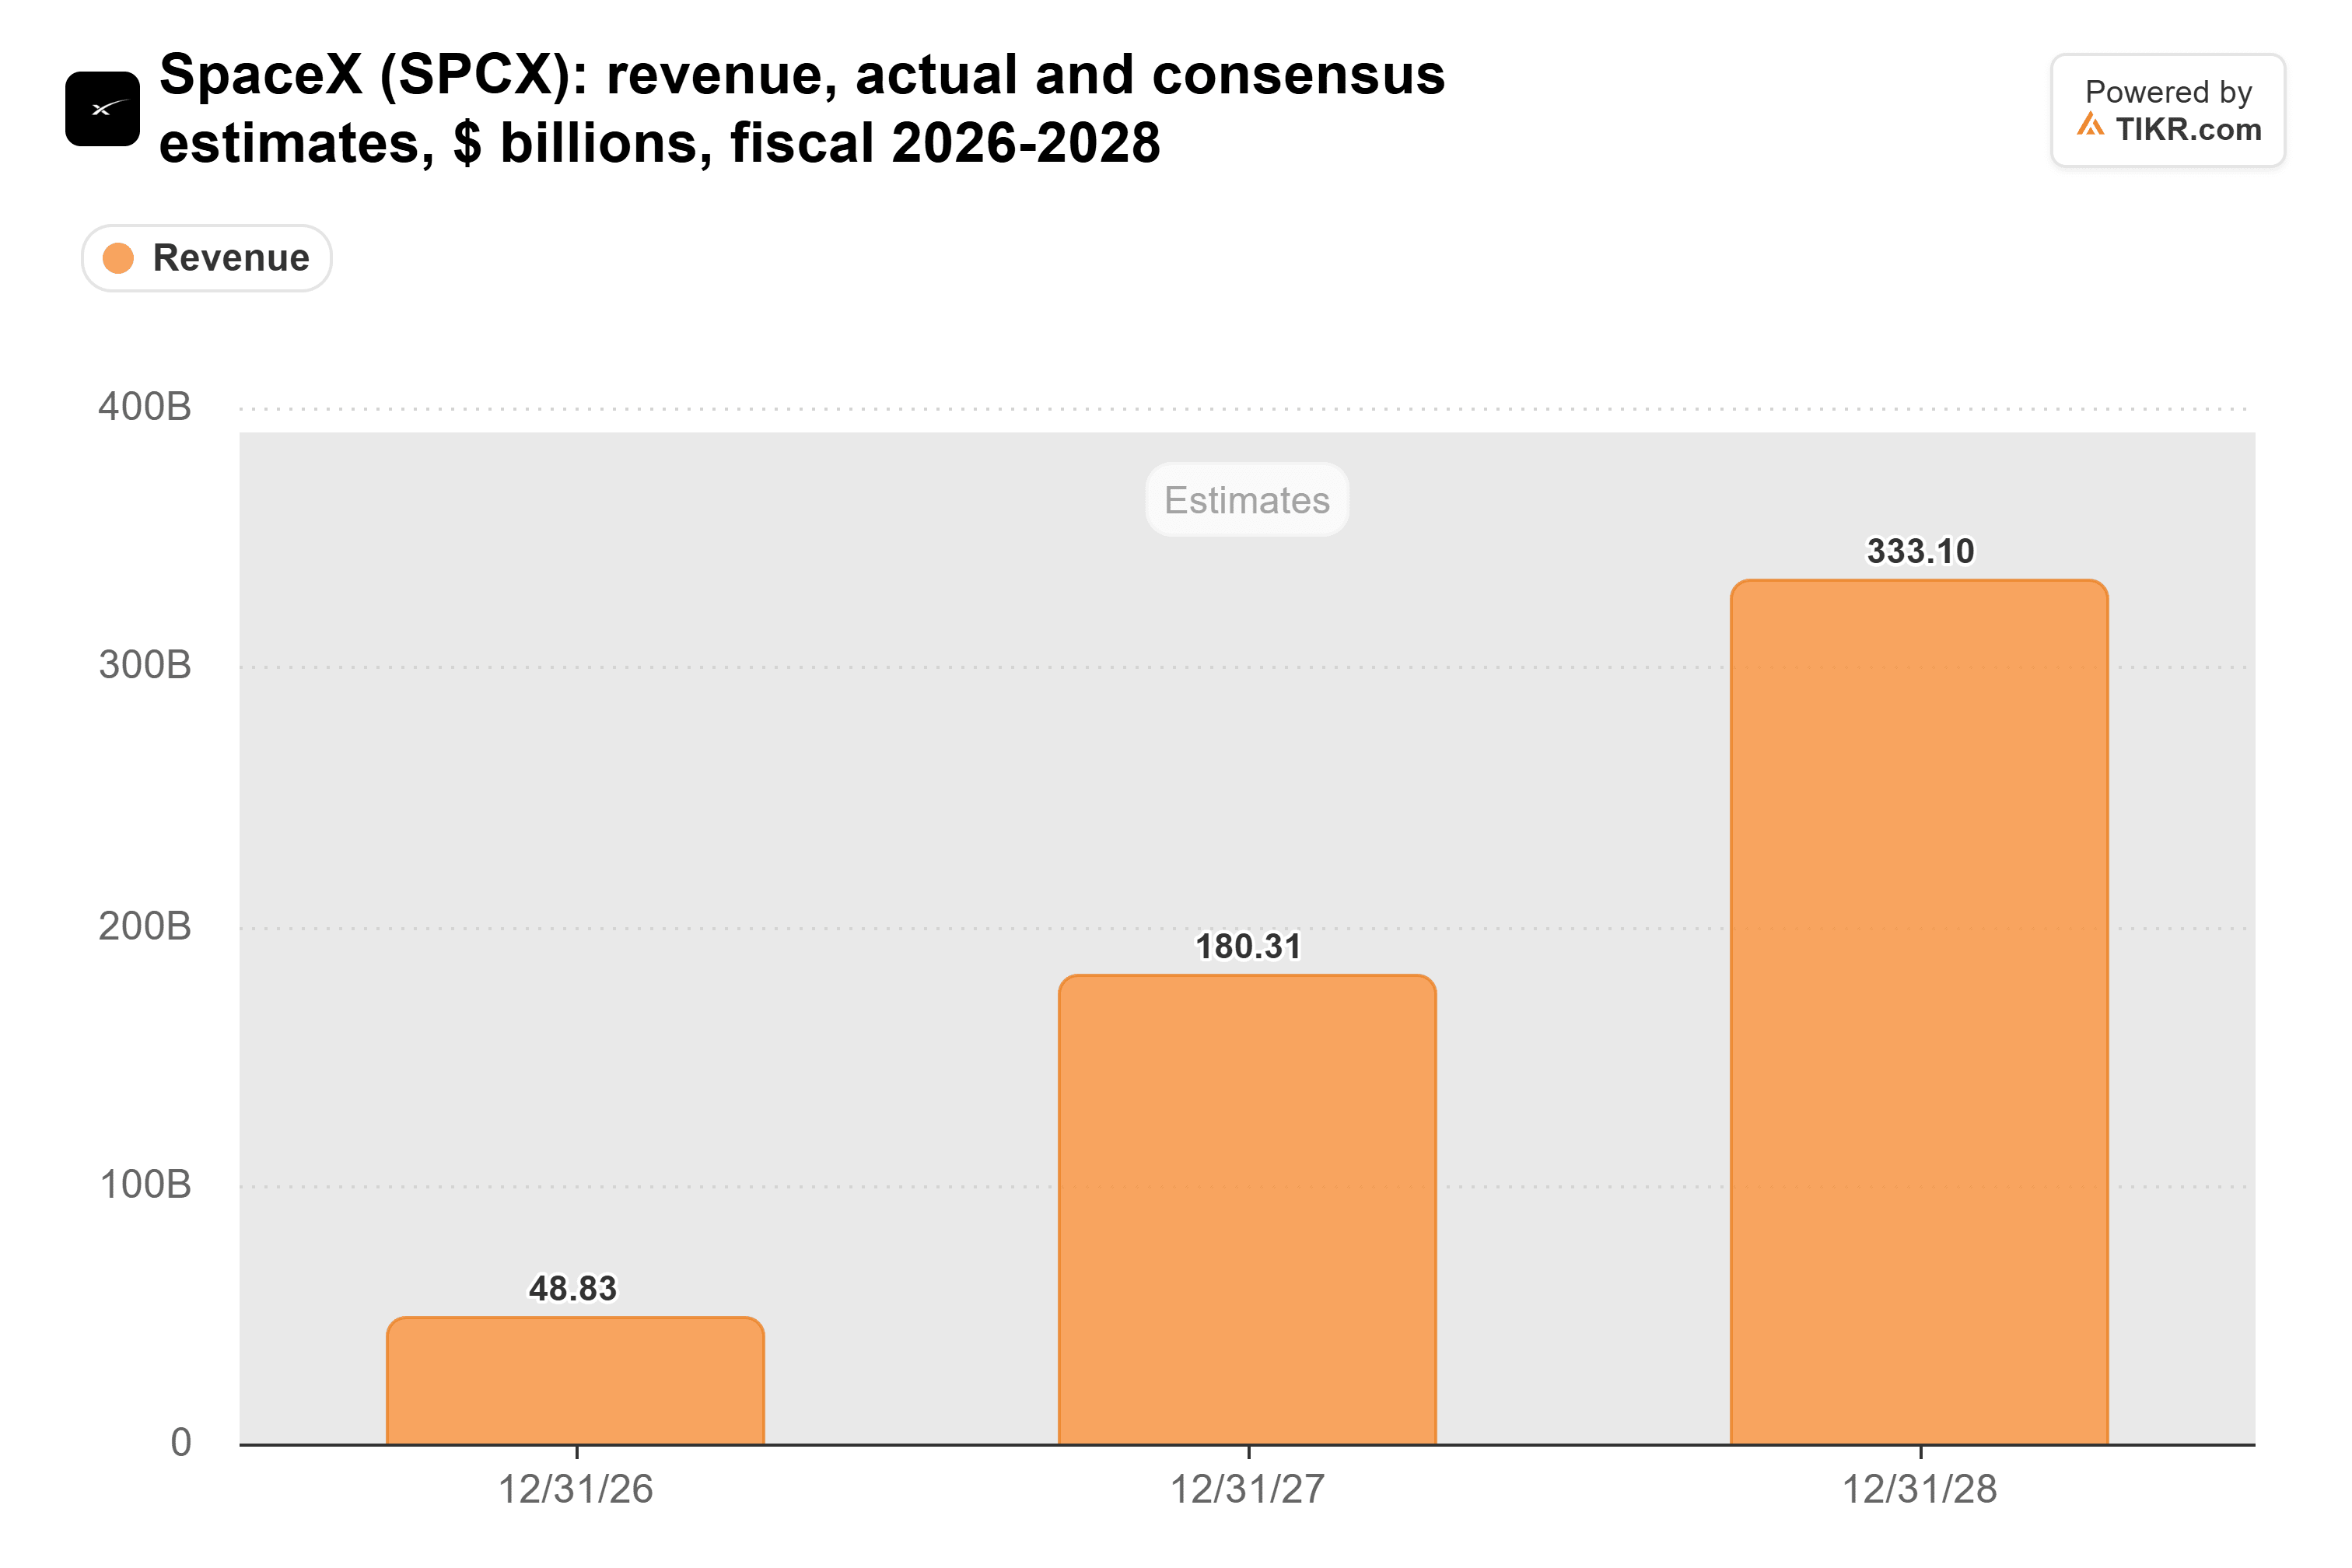
Four quarters at the top of SpaceX’s own first-quarter guide of $33 billion to $37 billion would add up to only $148 billion, so the 2027 consensus assumes the ramp speeds up from there.
SpaceX trades at more than 40x forward earnings, and how expensive that looks depends on which revenue you use. On Fast Money, Deepwater Asset Management’s Gene Munster pointed to SpaceX, “who trades at 10 times revenue and grows at 270%.” Those figures line up with next year’s consensus, which sits about 270% above this year’s. Against the $32.0 billion SpaceX has actually booked over the past four quarters, the multiple is above 50x, and Anthropic is the biggest buyer behind that gap.
Anthropic can pay, for now
Anthropic raised $107.3 billion through its IPO and a concurrent private placement, which would cover nearly three years of that monthly bill. And at the New York Times DealBook Summit on Nov. 18, Elon Musk said Anthropic’s highest-probability outcome is that “they would like an incremental 10 gigawatts of compute from SpaceX.” Anthropic hasn’t confirmed that figure.
But a falling stock makes Anthropic’s next raise more expensive. Meanwhile, most of SpaceX’s new chip debt priced above 8%, and one tenant already supplies about a third of SpaceX’s revenue. That’s a leveraged bet on that tenant’s ability to pay.
Amazon is tied to the same tenant. AWS sales rose 39% to $46.0 billion in the third quarter, and Amazon’s year-ago third quarter included $9.5 billion of pre-tax gains on its Anthropic investments. If a cooler market forces Anthropic to slow its spending, which landlord feels it first?
The next test comes early next year
Bottom line: O’Driscoll is right. At these prices, SpaceX stock only pays off if Anthropic’s bill keeps growing, and that has to show up in the numbers before the stock earns its premium. SpaceX’s fourth-quarter report in early 2027 should show whether December revenue reached $8.3 billion, the pace its $100 billion annual run-rate goal needs. A miss there, or any sign that Anthropic is using its 90-day exit, would answer O’Driscoll’s “only question” the wrong way.
So what is SpaceX stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SpaceX could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!