Key Takeaways
- Broadcom’s revenue rose 86% last quarter, and management expects AI revenue to double to about $115 billion in fiscal 2027.
- One investor questions Broadcom’s roughly 45x trailing GAAP multiple, but on adjusted earnings it trades at 36x trailing and 20x forward.
- Marvell trades at 26x forward earnings and Micron at 4.0x, with Broadcom in between.
- Fiscal 2027 consensus lines up with Tan’s AI doubling, and Dec. 9 is the next check.
A poster on r/ValueInvesting asked what many Broadcom (AVGO) investors are wondering ahead of its Dec. 9 report.
The stock sits about 26% below its June 2 closing high, even though third-quarter revenue rose 86% to $29.6 billion. But at what the poster calls “~45x trailing earnings,” that’s “not a value multiple by any definition.”
So is it “a growth-at-a-reasonable-price situation where the drawdown created an entry, or a momentum stock wearing a value costume?”
Fair question. Marvell (MRVL) and Micron (MU) help answer it, and Marvell reports first, on Dec. 1.
Broadcom’s Multiple Shrinks Fast
The poster’s bull case is that “earnings are growing so fast the multiple compresses on its own.” Analysts expect exactly that, with normalized EPS nearly tripling from $6.82 in fiscal 2025 to $19.41 in fiscal 2027:
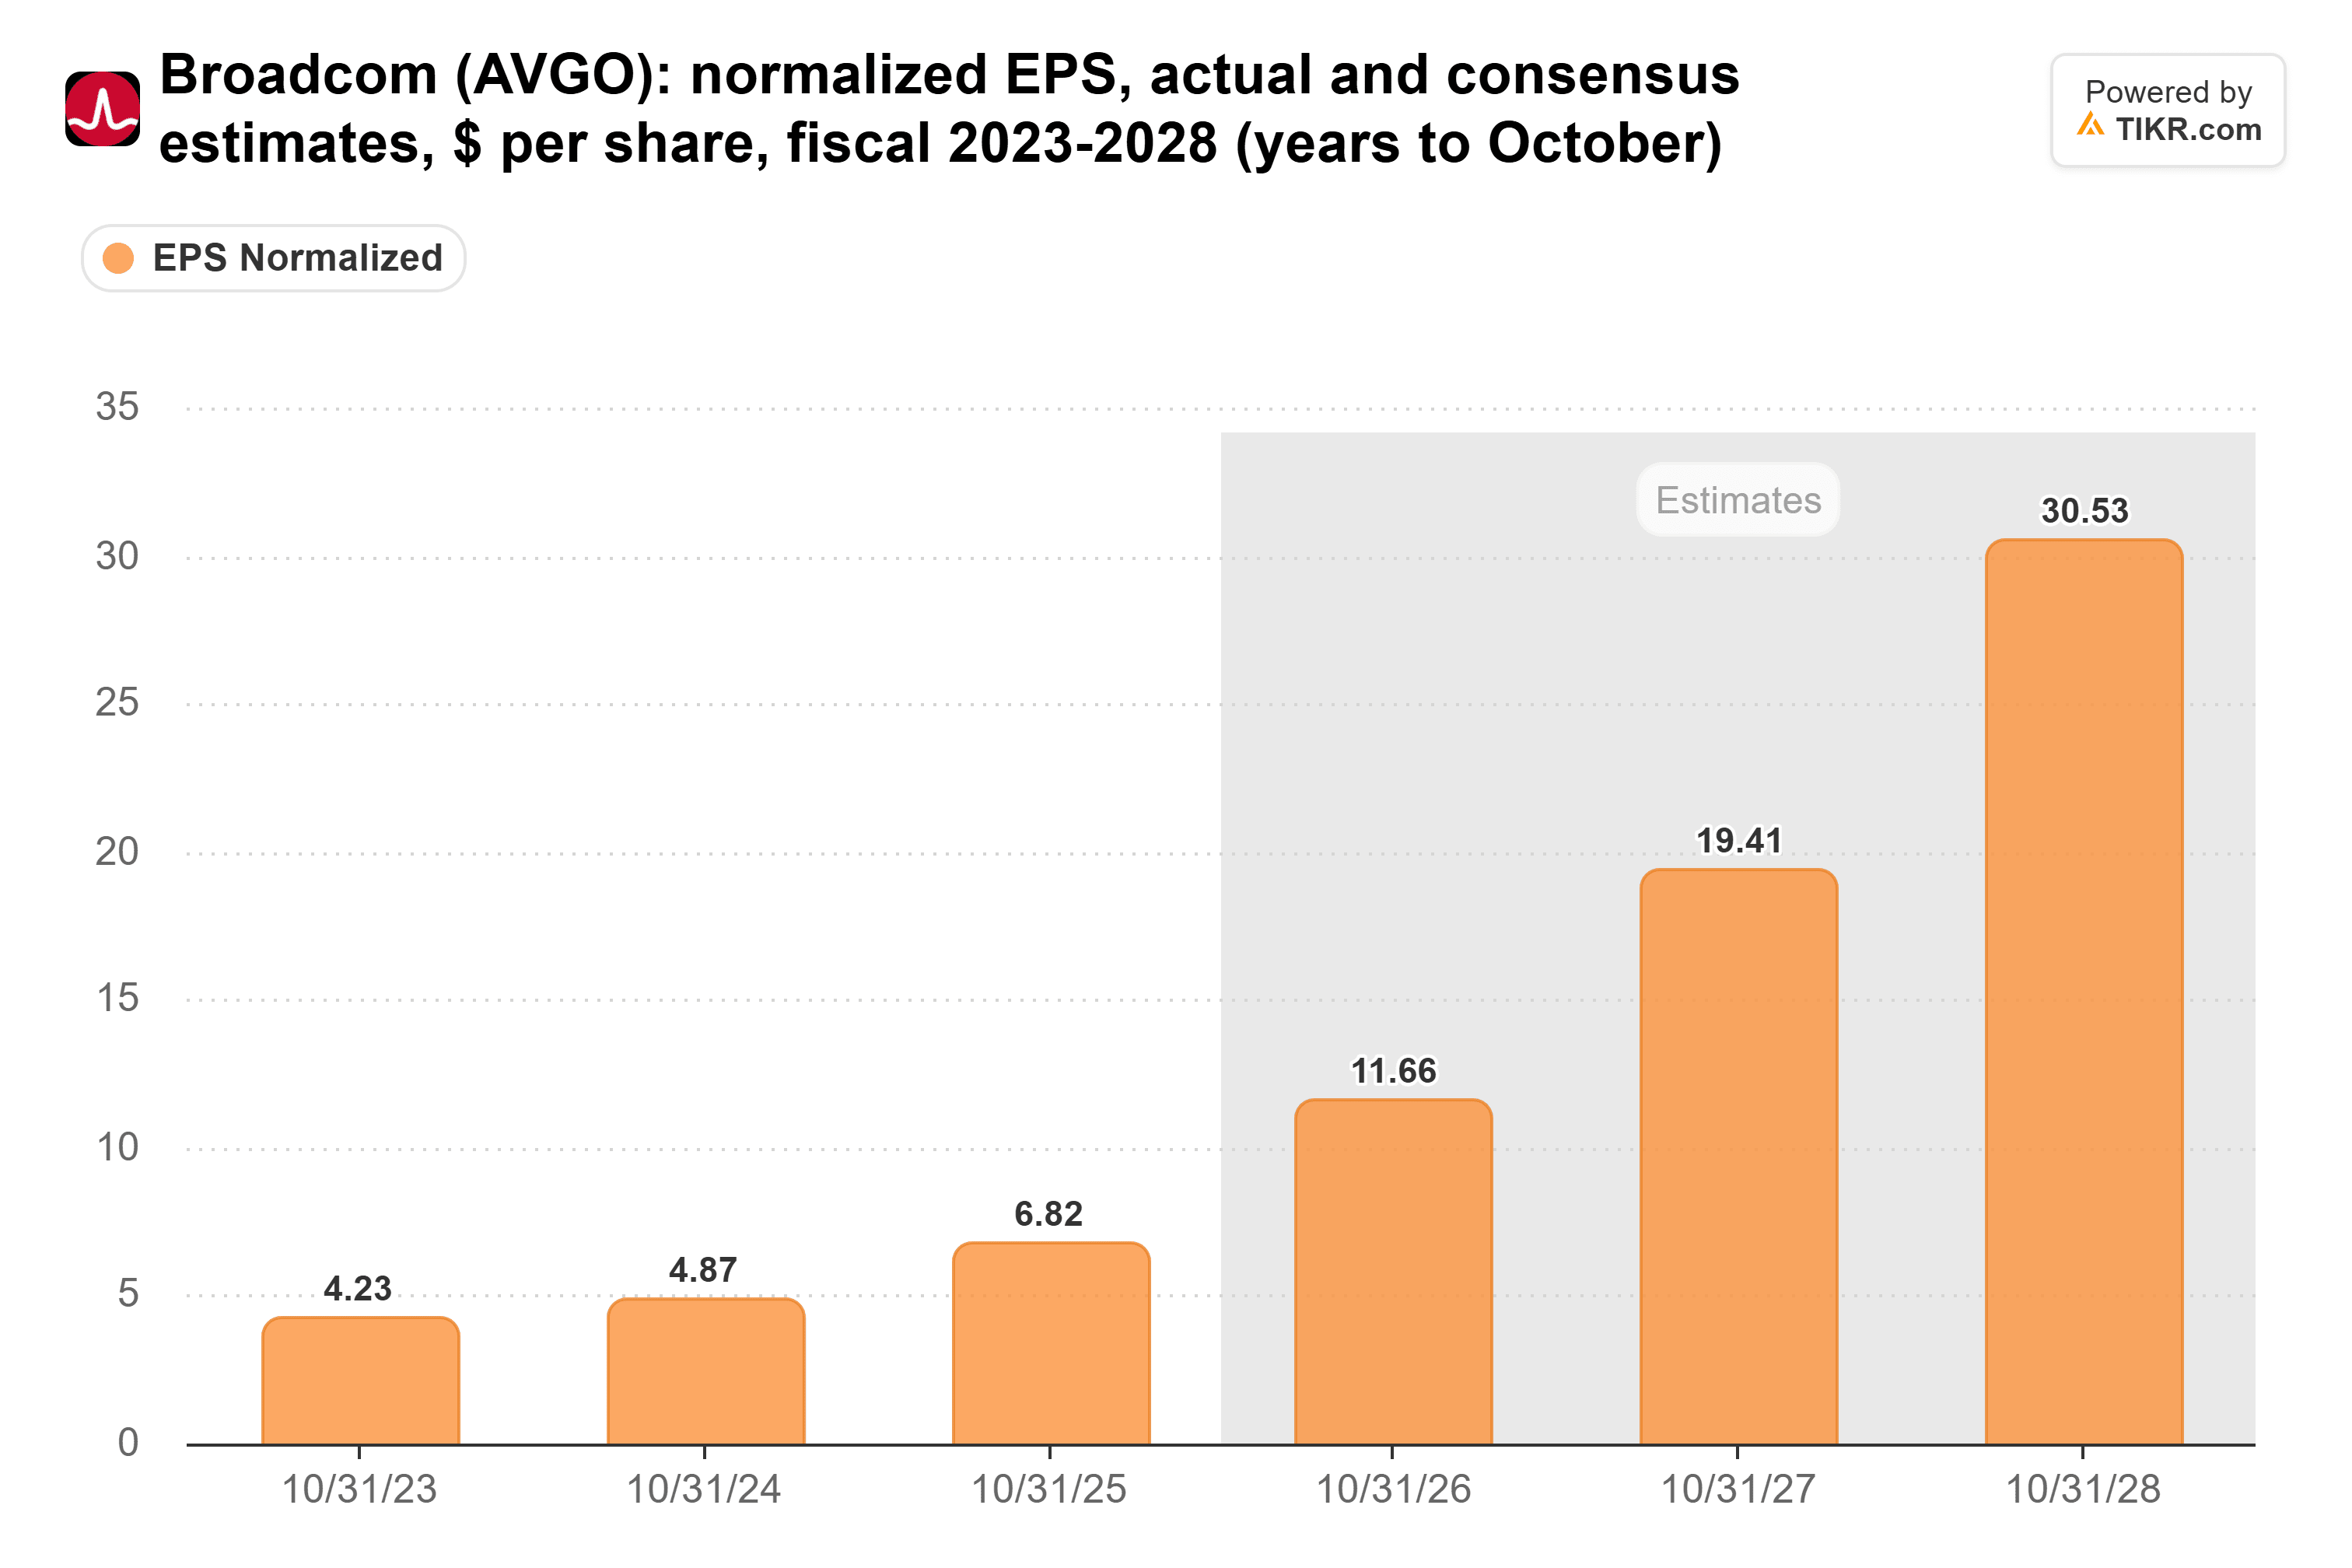
Whatever multiple you pay on fiscal 2025’s earnings shrinks to about a third on fiscal 2027’s.
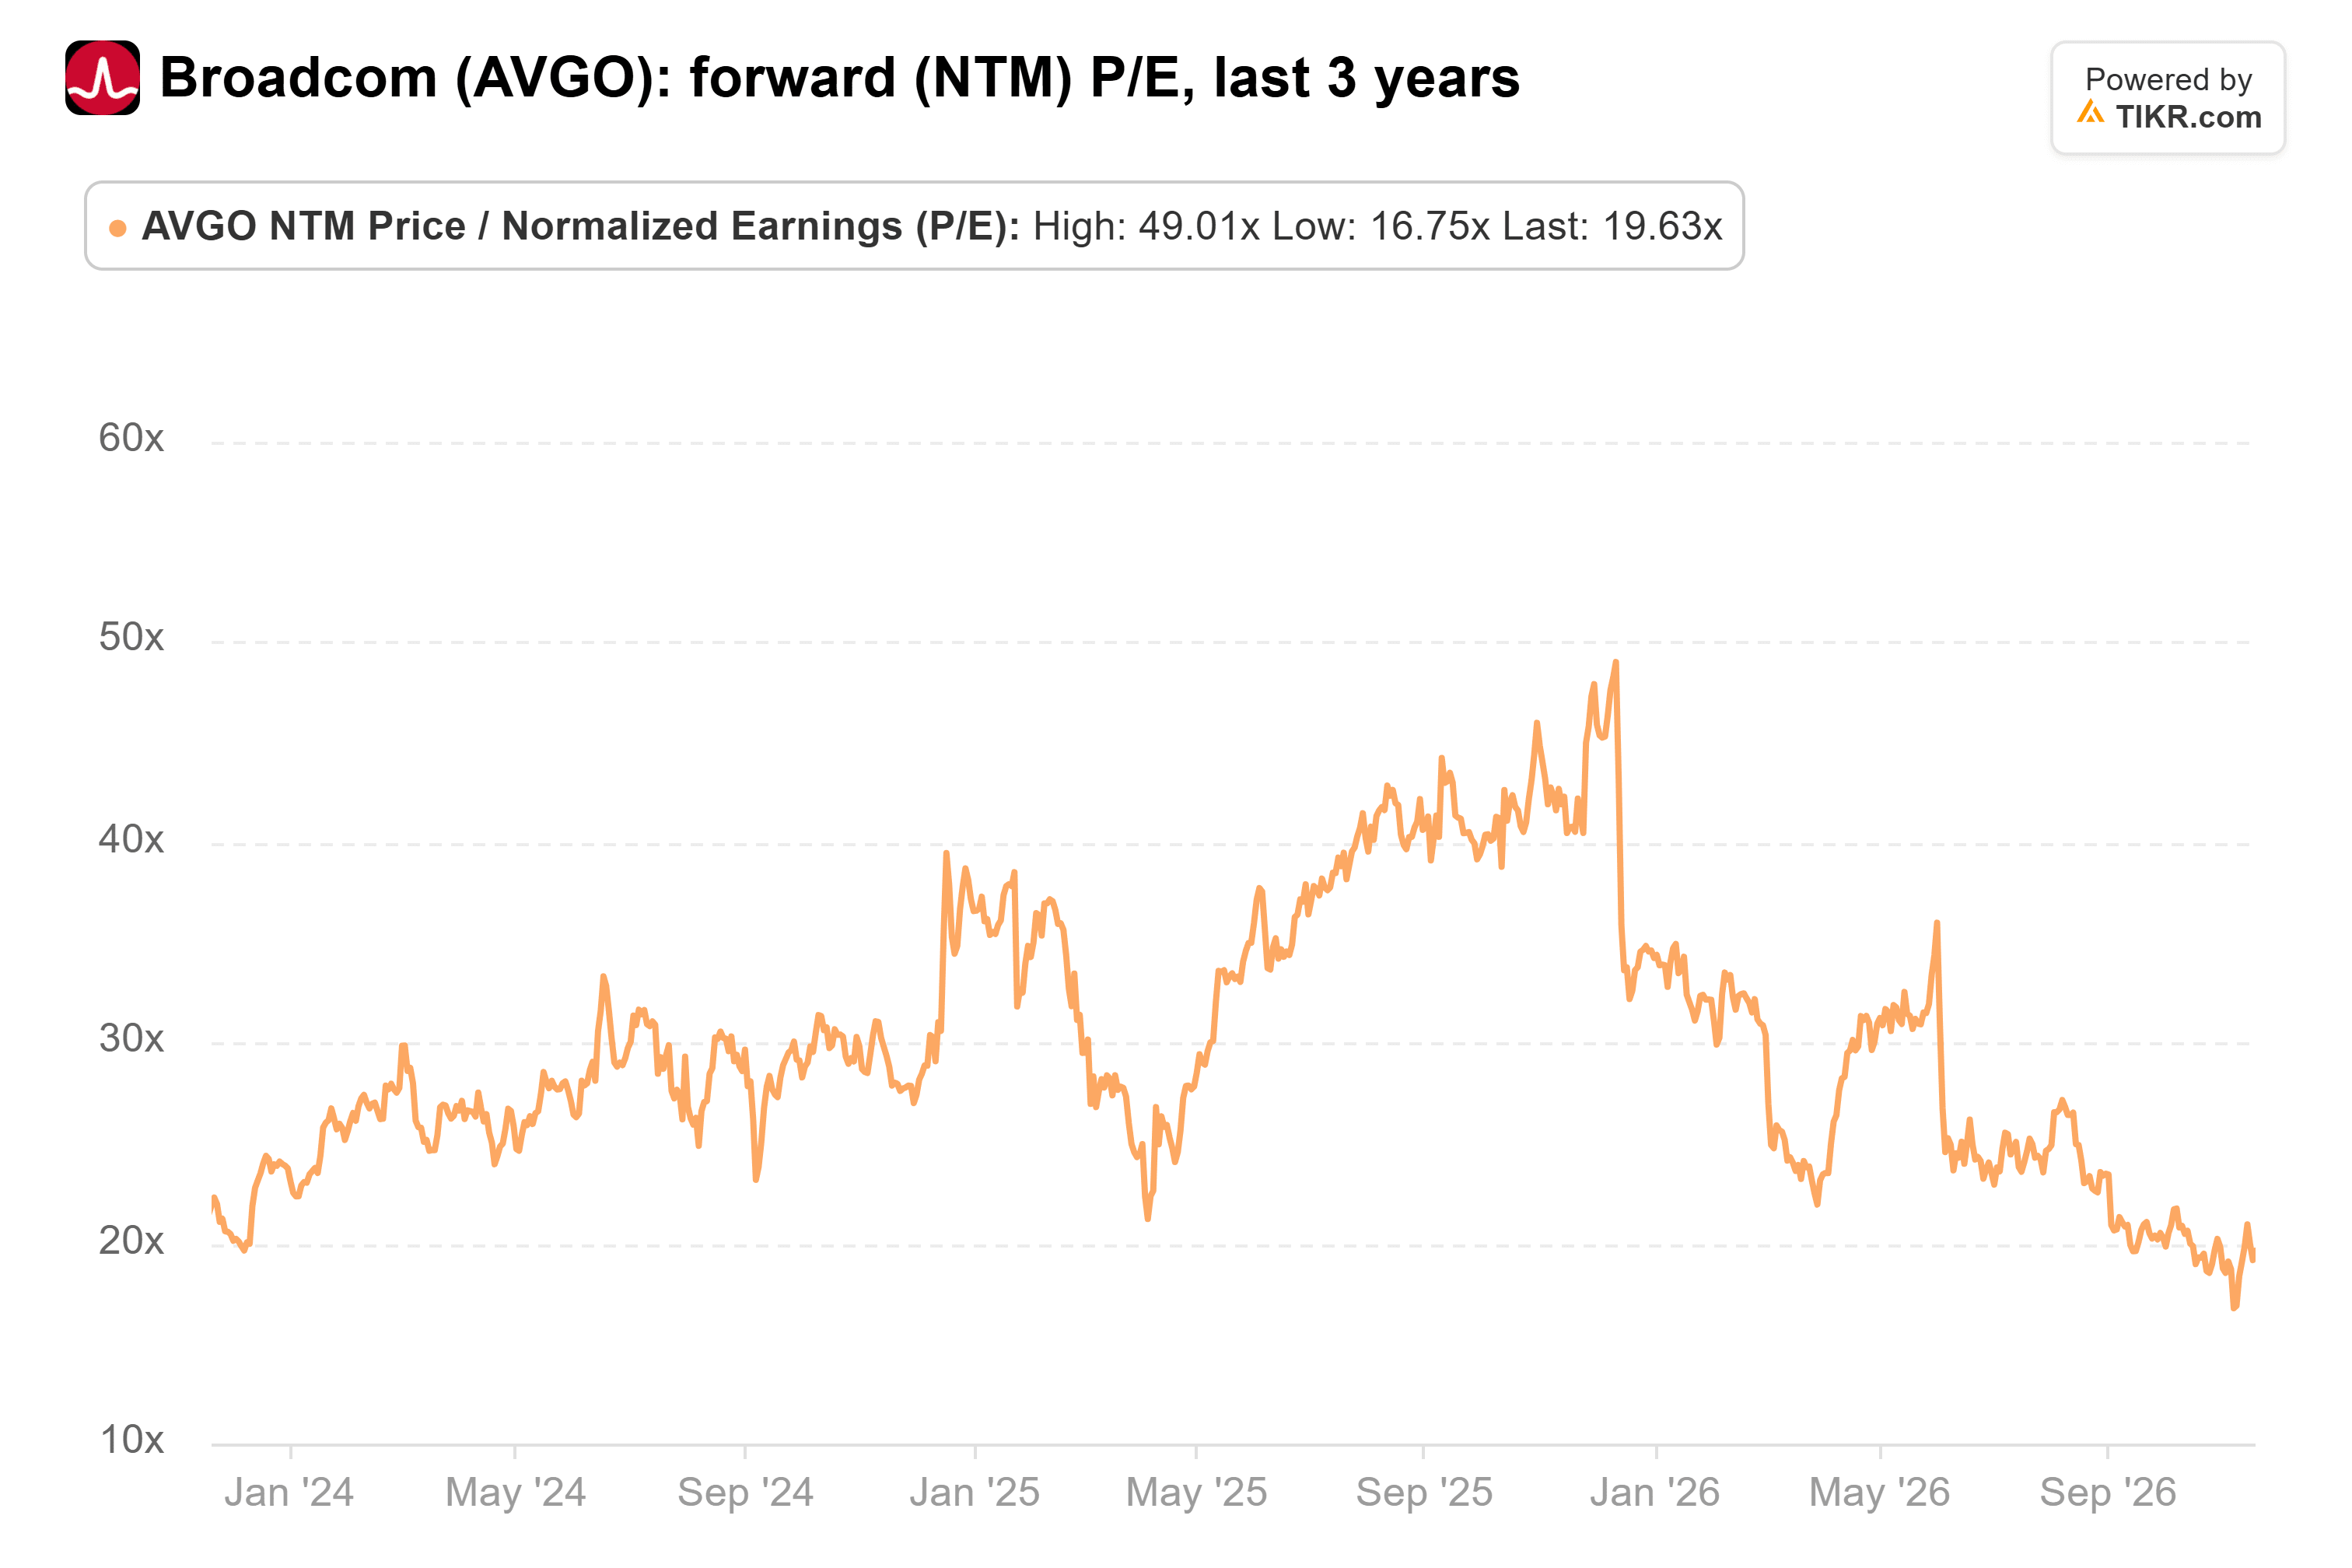
On adjusted earnings, Broadcom trades at 36x trailing and 20x forward, below its three-year forward average of 30x and not far above its Nov. 5 low of 17x:
The Price Leans on the Doubling
On the third-quarter call, CEO Hock Tan said, “In 2027, we have secured the supply to again double AI revenue to approximately $115 billion.”
Consensus revenue lines up with that, climbing from $106 billion in fiscal 2026 to $175 billion in fiscal 2027:
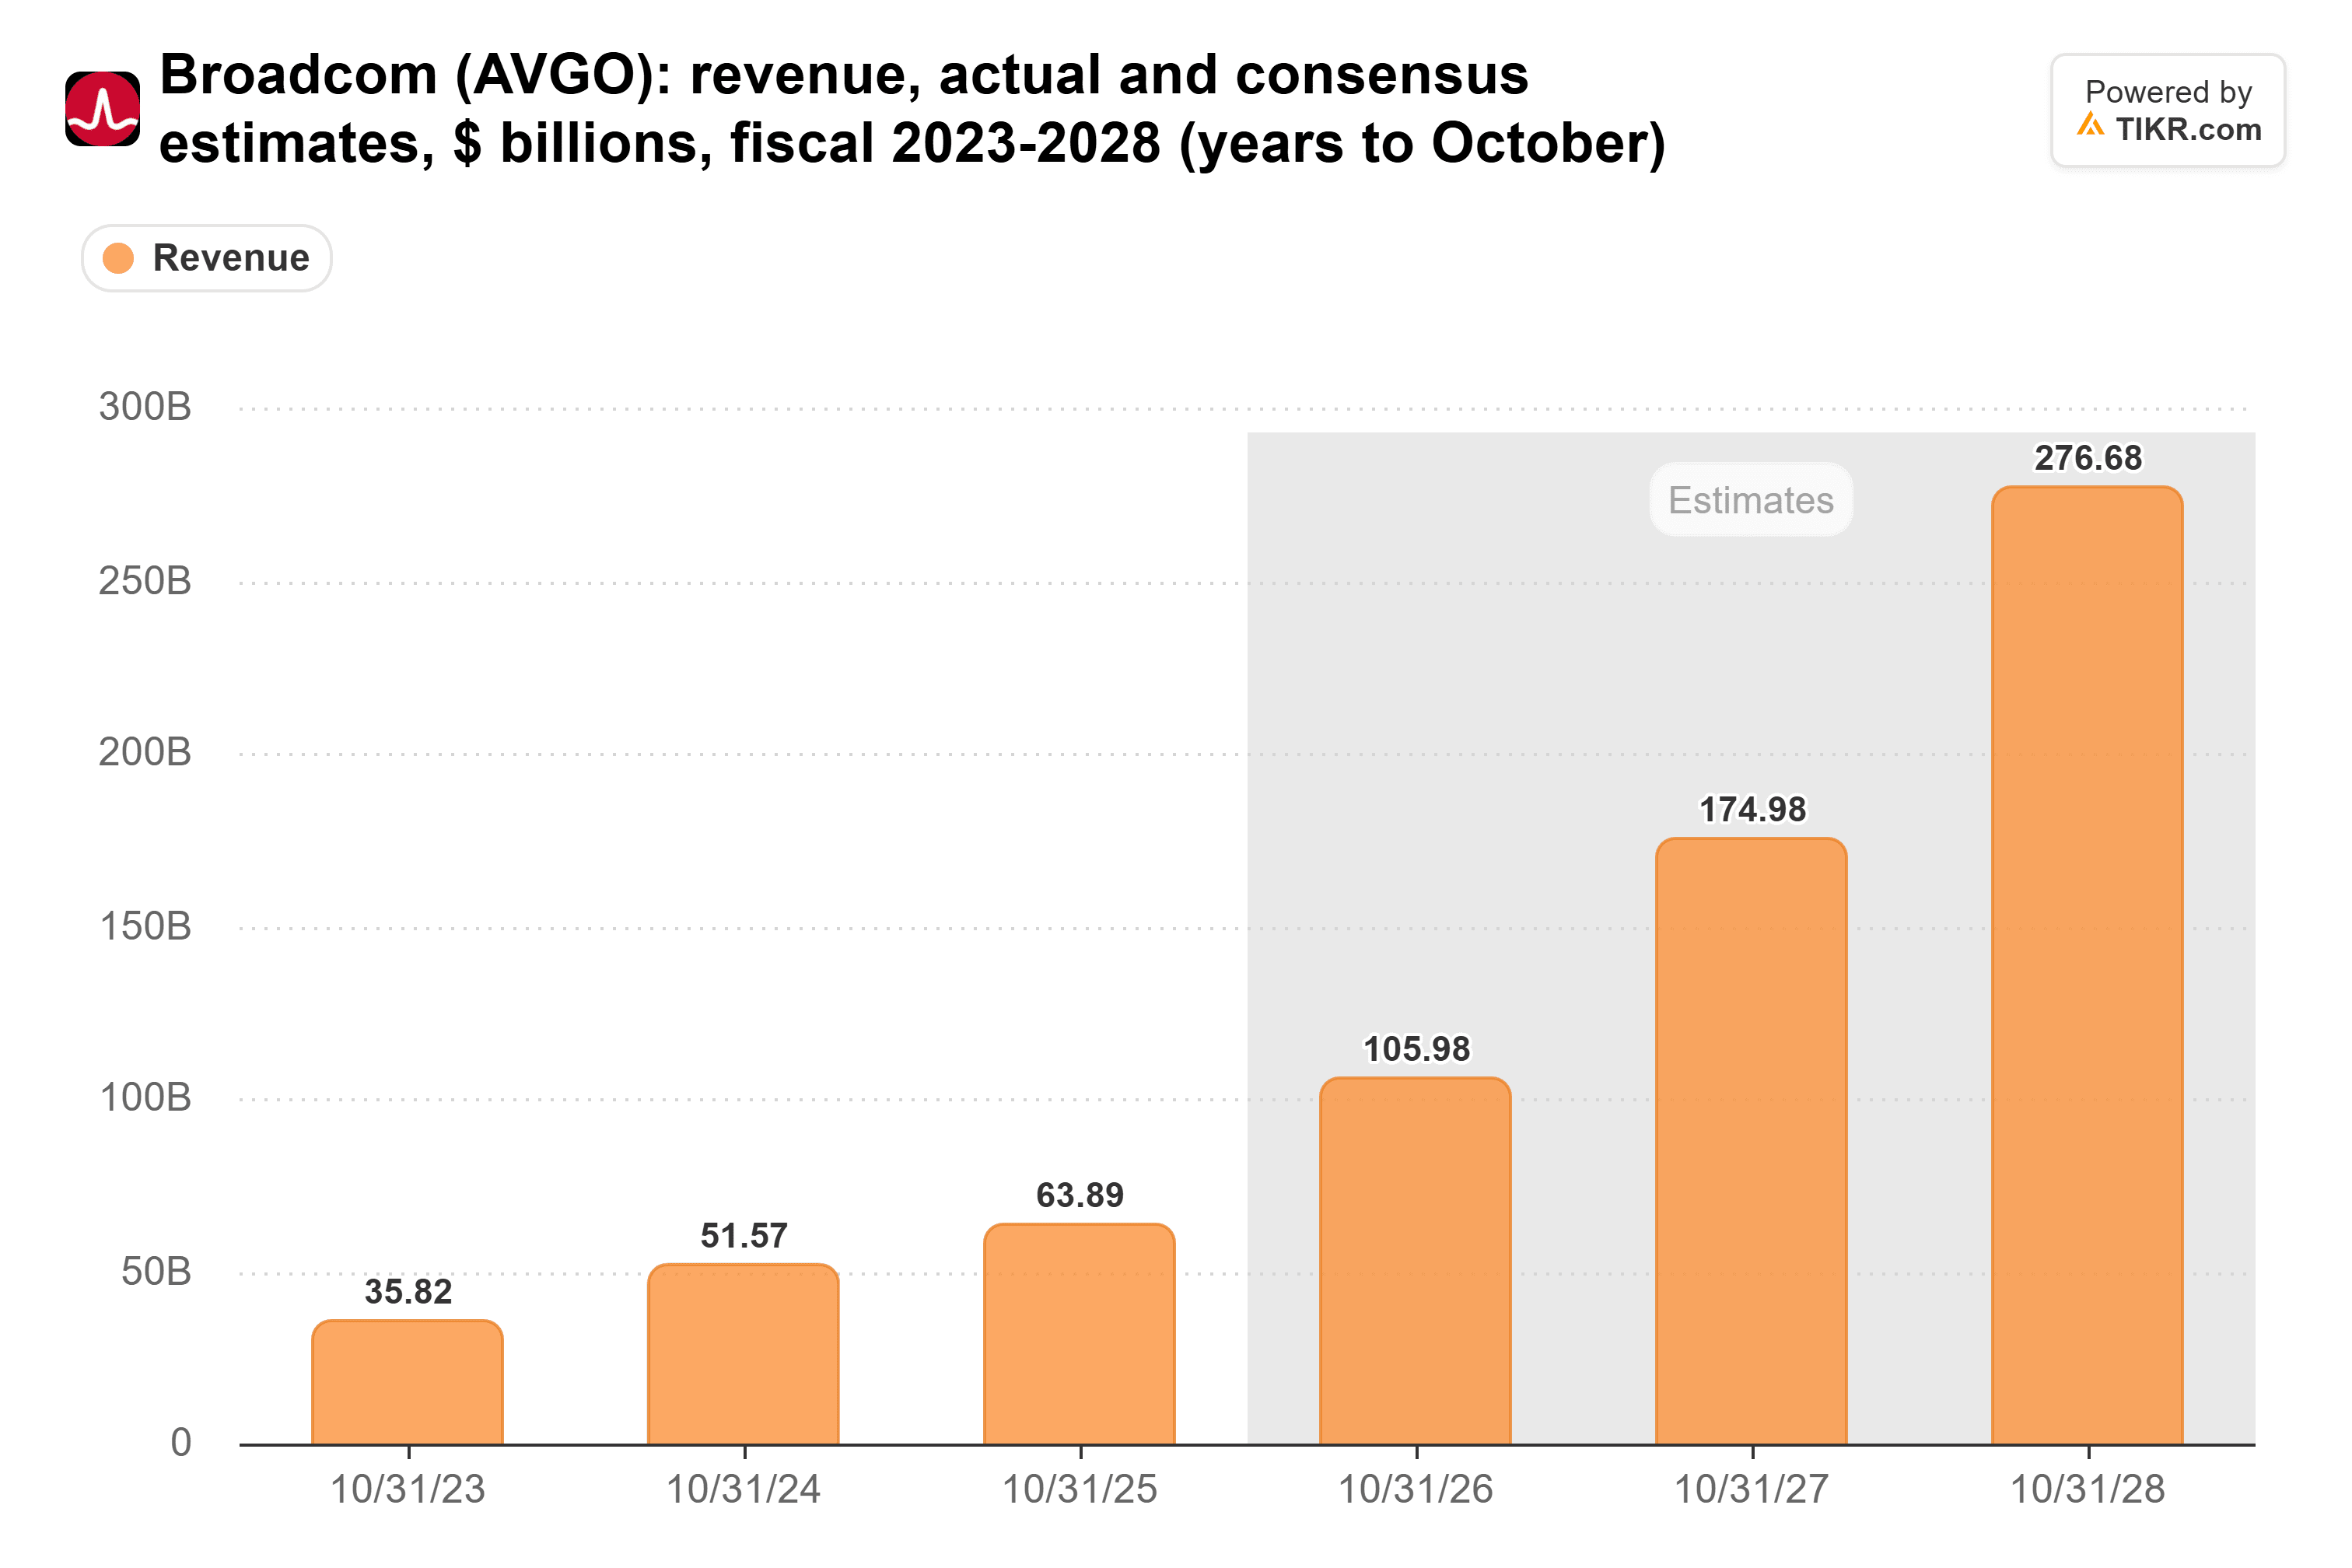
Take out Tan’s $115 billion of AI revenue, and about $60 billion is left for the rest of the business, more than it brings in this year. The 20x leans on that doubling.
TIKR Tracks 51 Analysts on Broadcom. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
The risk is who’s buying the chips. Tan expects Anthropic to become Broadcom’s largest custom-chip customer in 2027, and Broadcom now backstops two rounds of Anthropic’s rack leases, capped at $29 billion and about $43 billion. That’s about $72 billion, three times its $24.0 billion of cash on Aug. 2, and a big reason Rothschild & Co Redburn downgraded Broadcom to Neutral on Nov. 13 and cut its target to $398 from $595.
Marvell Costs More, Micron Far Less
Marvell trades at 26x forward earnings. In July, Google signed a custom-chip deal with Marvell, then got a warrant for up to $12.2 billion of stock that vests mostly with chip purchases. That raises questions for Broadcom. If Marvell holds its roughly $20 billion fiscal 2028 outlook on Dec. 1, hyperscaler budgets look big enough for both.
Micron sits at 4.0x forward earnings, even though analysts expect its normalized EPS to more than double to $176.50 in fiscal 2027. I read that as a memory-cycle peak being priced in. Broadcom’s 20x sits between: investors believe the AI doubling but want proof customers can pay.
Watch Broadcom’s 2027 Number on Dec. 9
Fourth-quarter AI revenue is guided to $21.7 billion, but fiscal 2027 matters more. If Tan repeats about $115 billion, 20x looks cheap.
Broadcom is a growth stock at a reasonable price, and the pullback improved it. A softer 2027 outlook, blamed on customers’ power and buildings, would change that fast.
So What Is Broadcom Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!