Key Takeaways
- IREN’s AI cloud revenue nearly tripled to $200 million last quarter, lifting total revenue 66% sequentially to $228 million.
- IREN moved its $4 billion annualized revenue target into January 2027 after Microsoft requested network changes, and it could slip to late February.
- IREN plans $15 billion of capex through June, and $6 billion of that still depends on market conditions.
- The next tests are IREN’s November 24 annual meeting and its December quarter report, expected in February.
IREN (IREN) just delivered the quarter its bulls wanted. AI cloud revenue nearly tripled, and operating ARR doubled to $1 billion.
Shares sank about 17% on November 5 during a broad selloff in AI infrastructure names, then jumped after results came out that evening. That rebound has since faded as neocloud stocks keep sliding.
Yet the tension sits with two marquee customers. Microsoft (MSFT) signed a roughly $9.7 billion contract with IREN last November. NVIDIA (NVDA) holds a $3.4 billion cloud services contract signed in May.
Meanwhile, CoreWeave (CRWV) showed on November 10 what scale looks like, with quarterly revenue up 168% to $3.66 billion.
Microsoft moves the finish line
For the quarter ended September 30, IREN reported:
- Total revenue of $228 million, up 66% from $137 million in the prior quarter.
- AI cloud revenue of $200 million, up 182%, at an 86% segment gross margin.
- A $20.3 billion revenue backlog, up 22%, with about two thirds tied to investment-grade customers.
Revenue beat estimates, but the outlook carried a catch. IREN now expects more than $4 billion of annualized run-rate revenue in January 2027 instead of year-end. And the date could slip to the end of February.
Microsoft is the cause. After taking Horizon 1, it asked for a network redesign so all 200 megawatts can serve newer frontier models. IREN faces no financial penalties for delays tied to those changes.
Timing made it worse. Bloomberg reported the same day that Microsoft is tightening oversight of neocloud projects, including IREN’s and Nebius’s. Here is how that week played out…
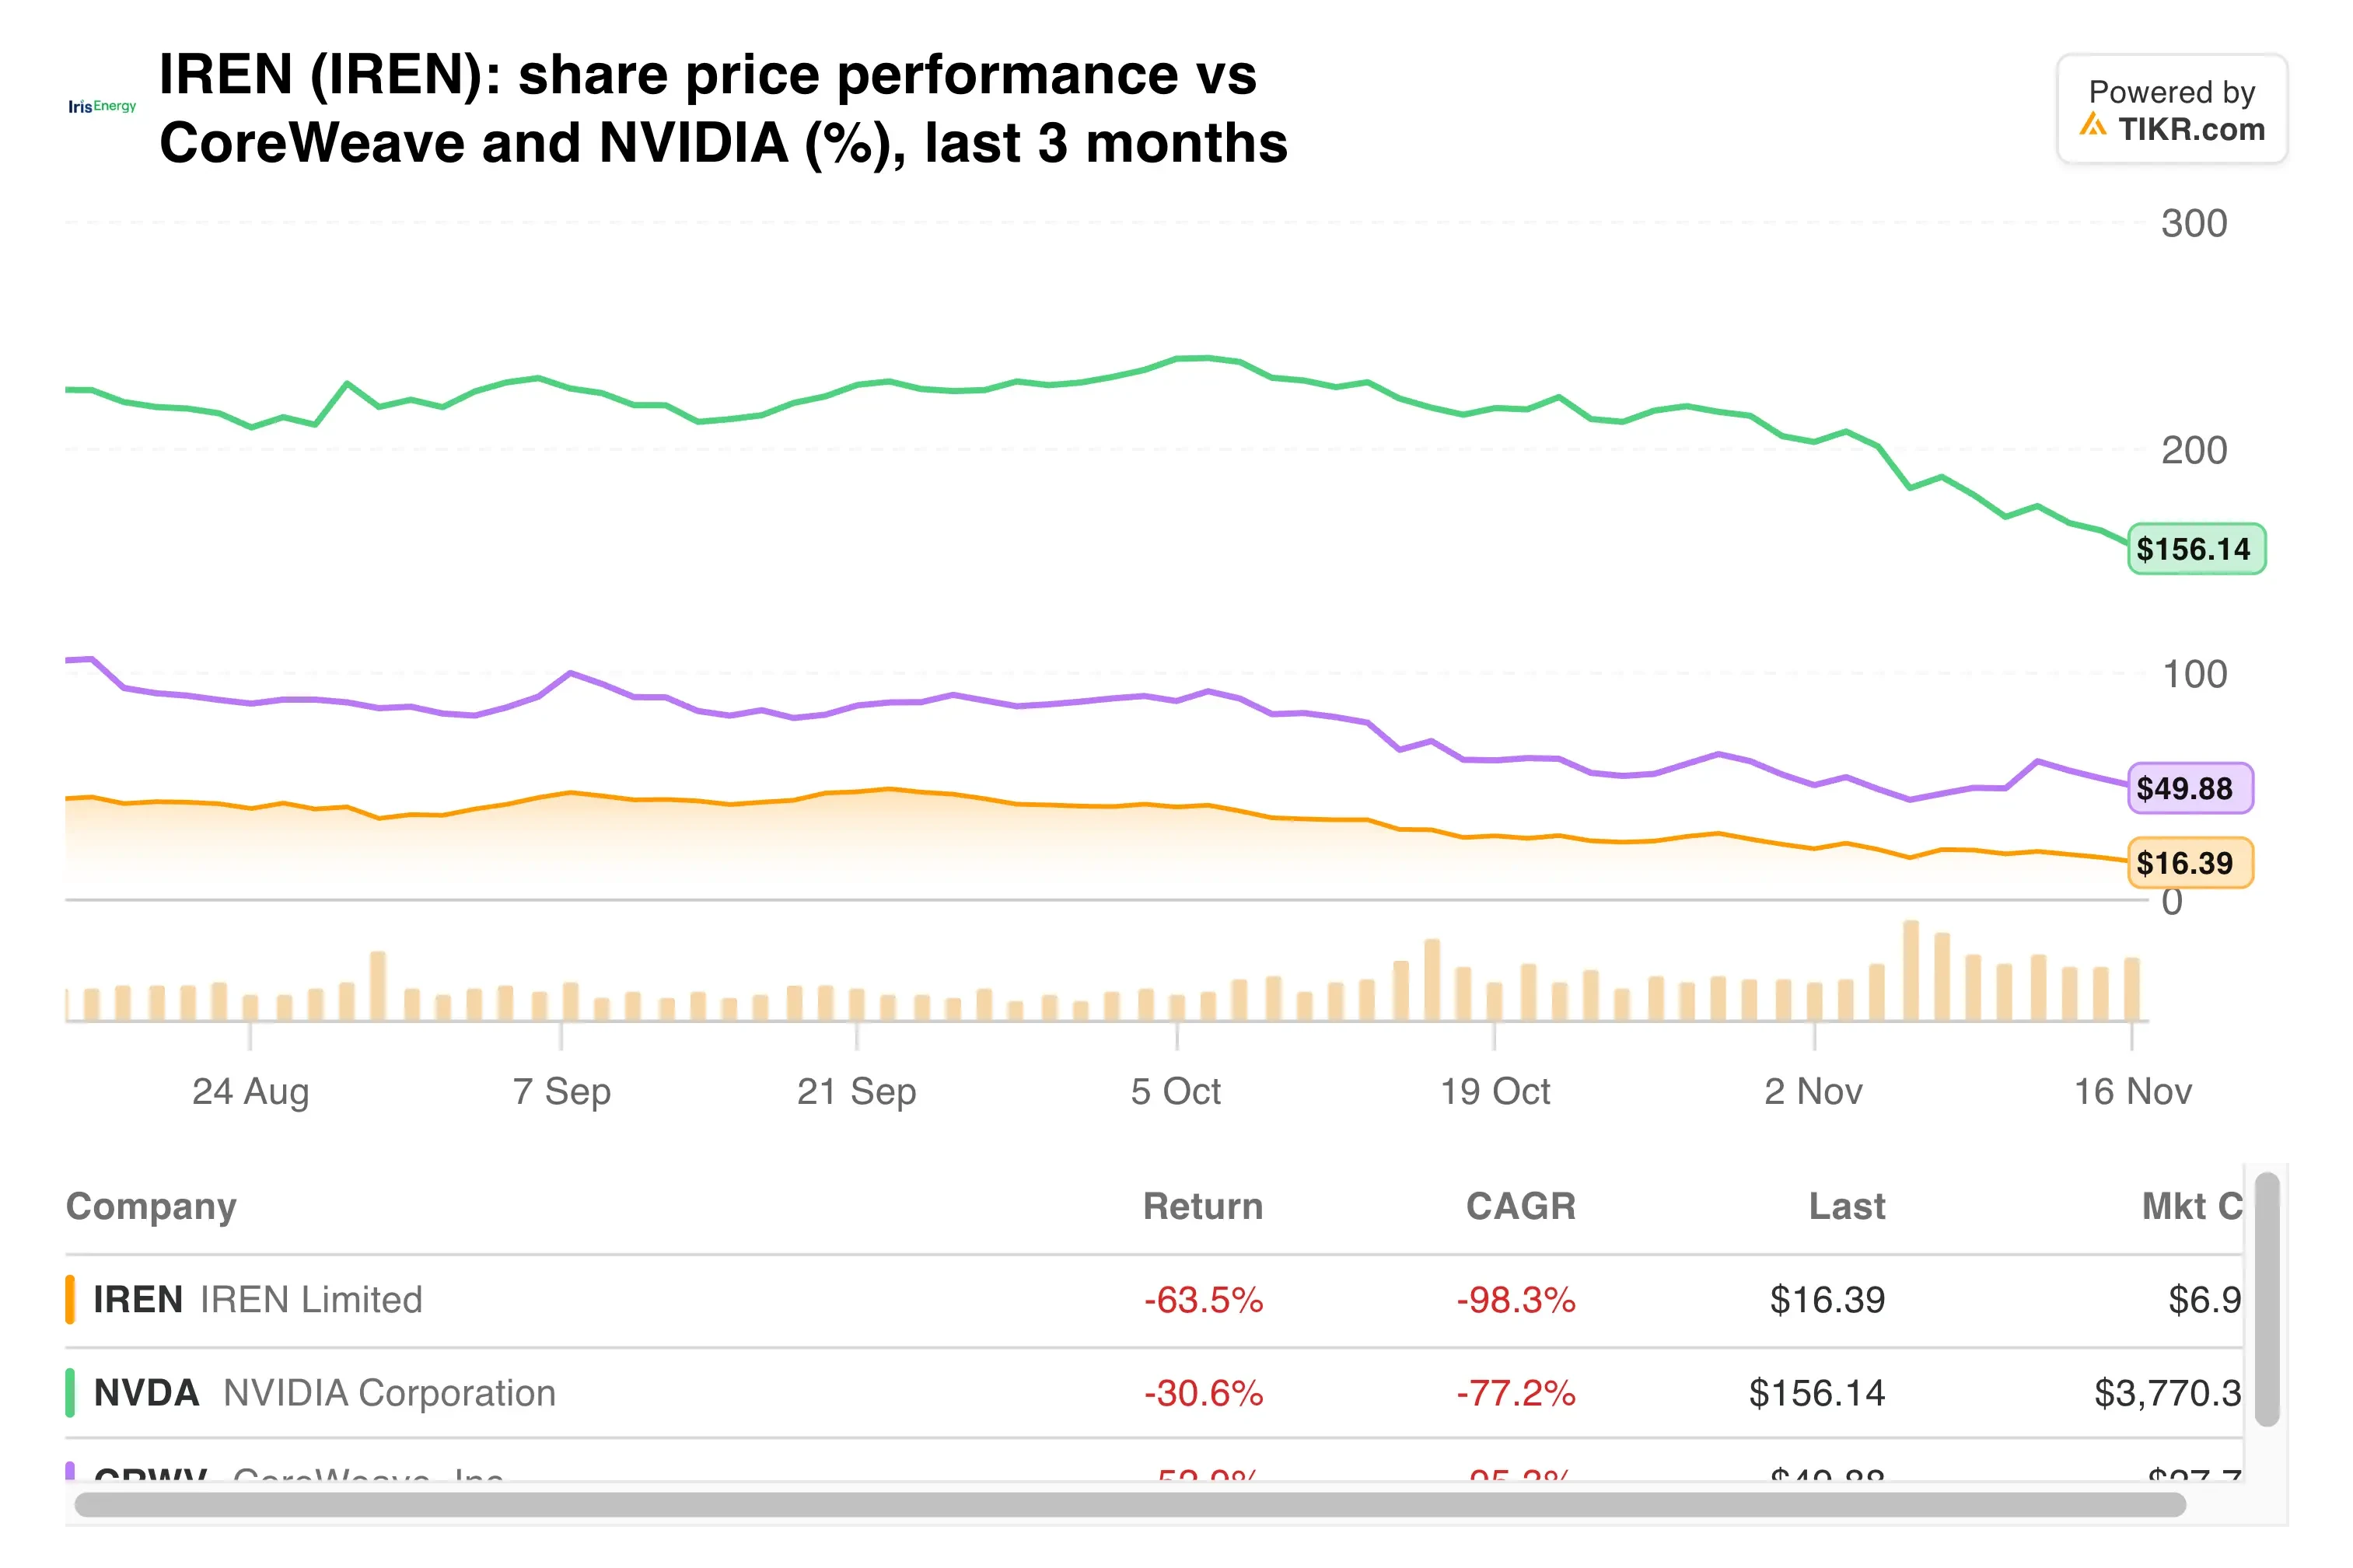
Demand held up, but the timeline slipped.
Mining fades as cloud takes over
The mix shift is moving fast. Bitcoin mining revenue fell to $28 million from $67 million because IREN is pulling miners to make room for GPUs. AI cloud now makes up almost 90% of sales.
So where is the new money coming from?
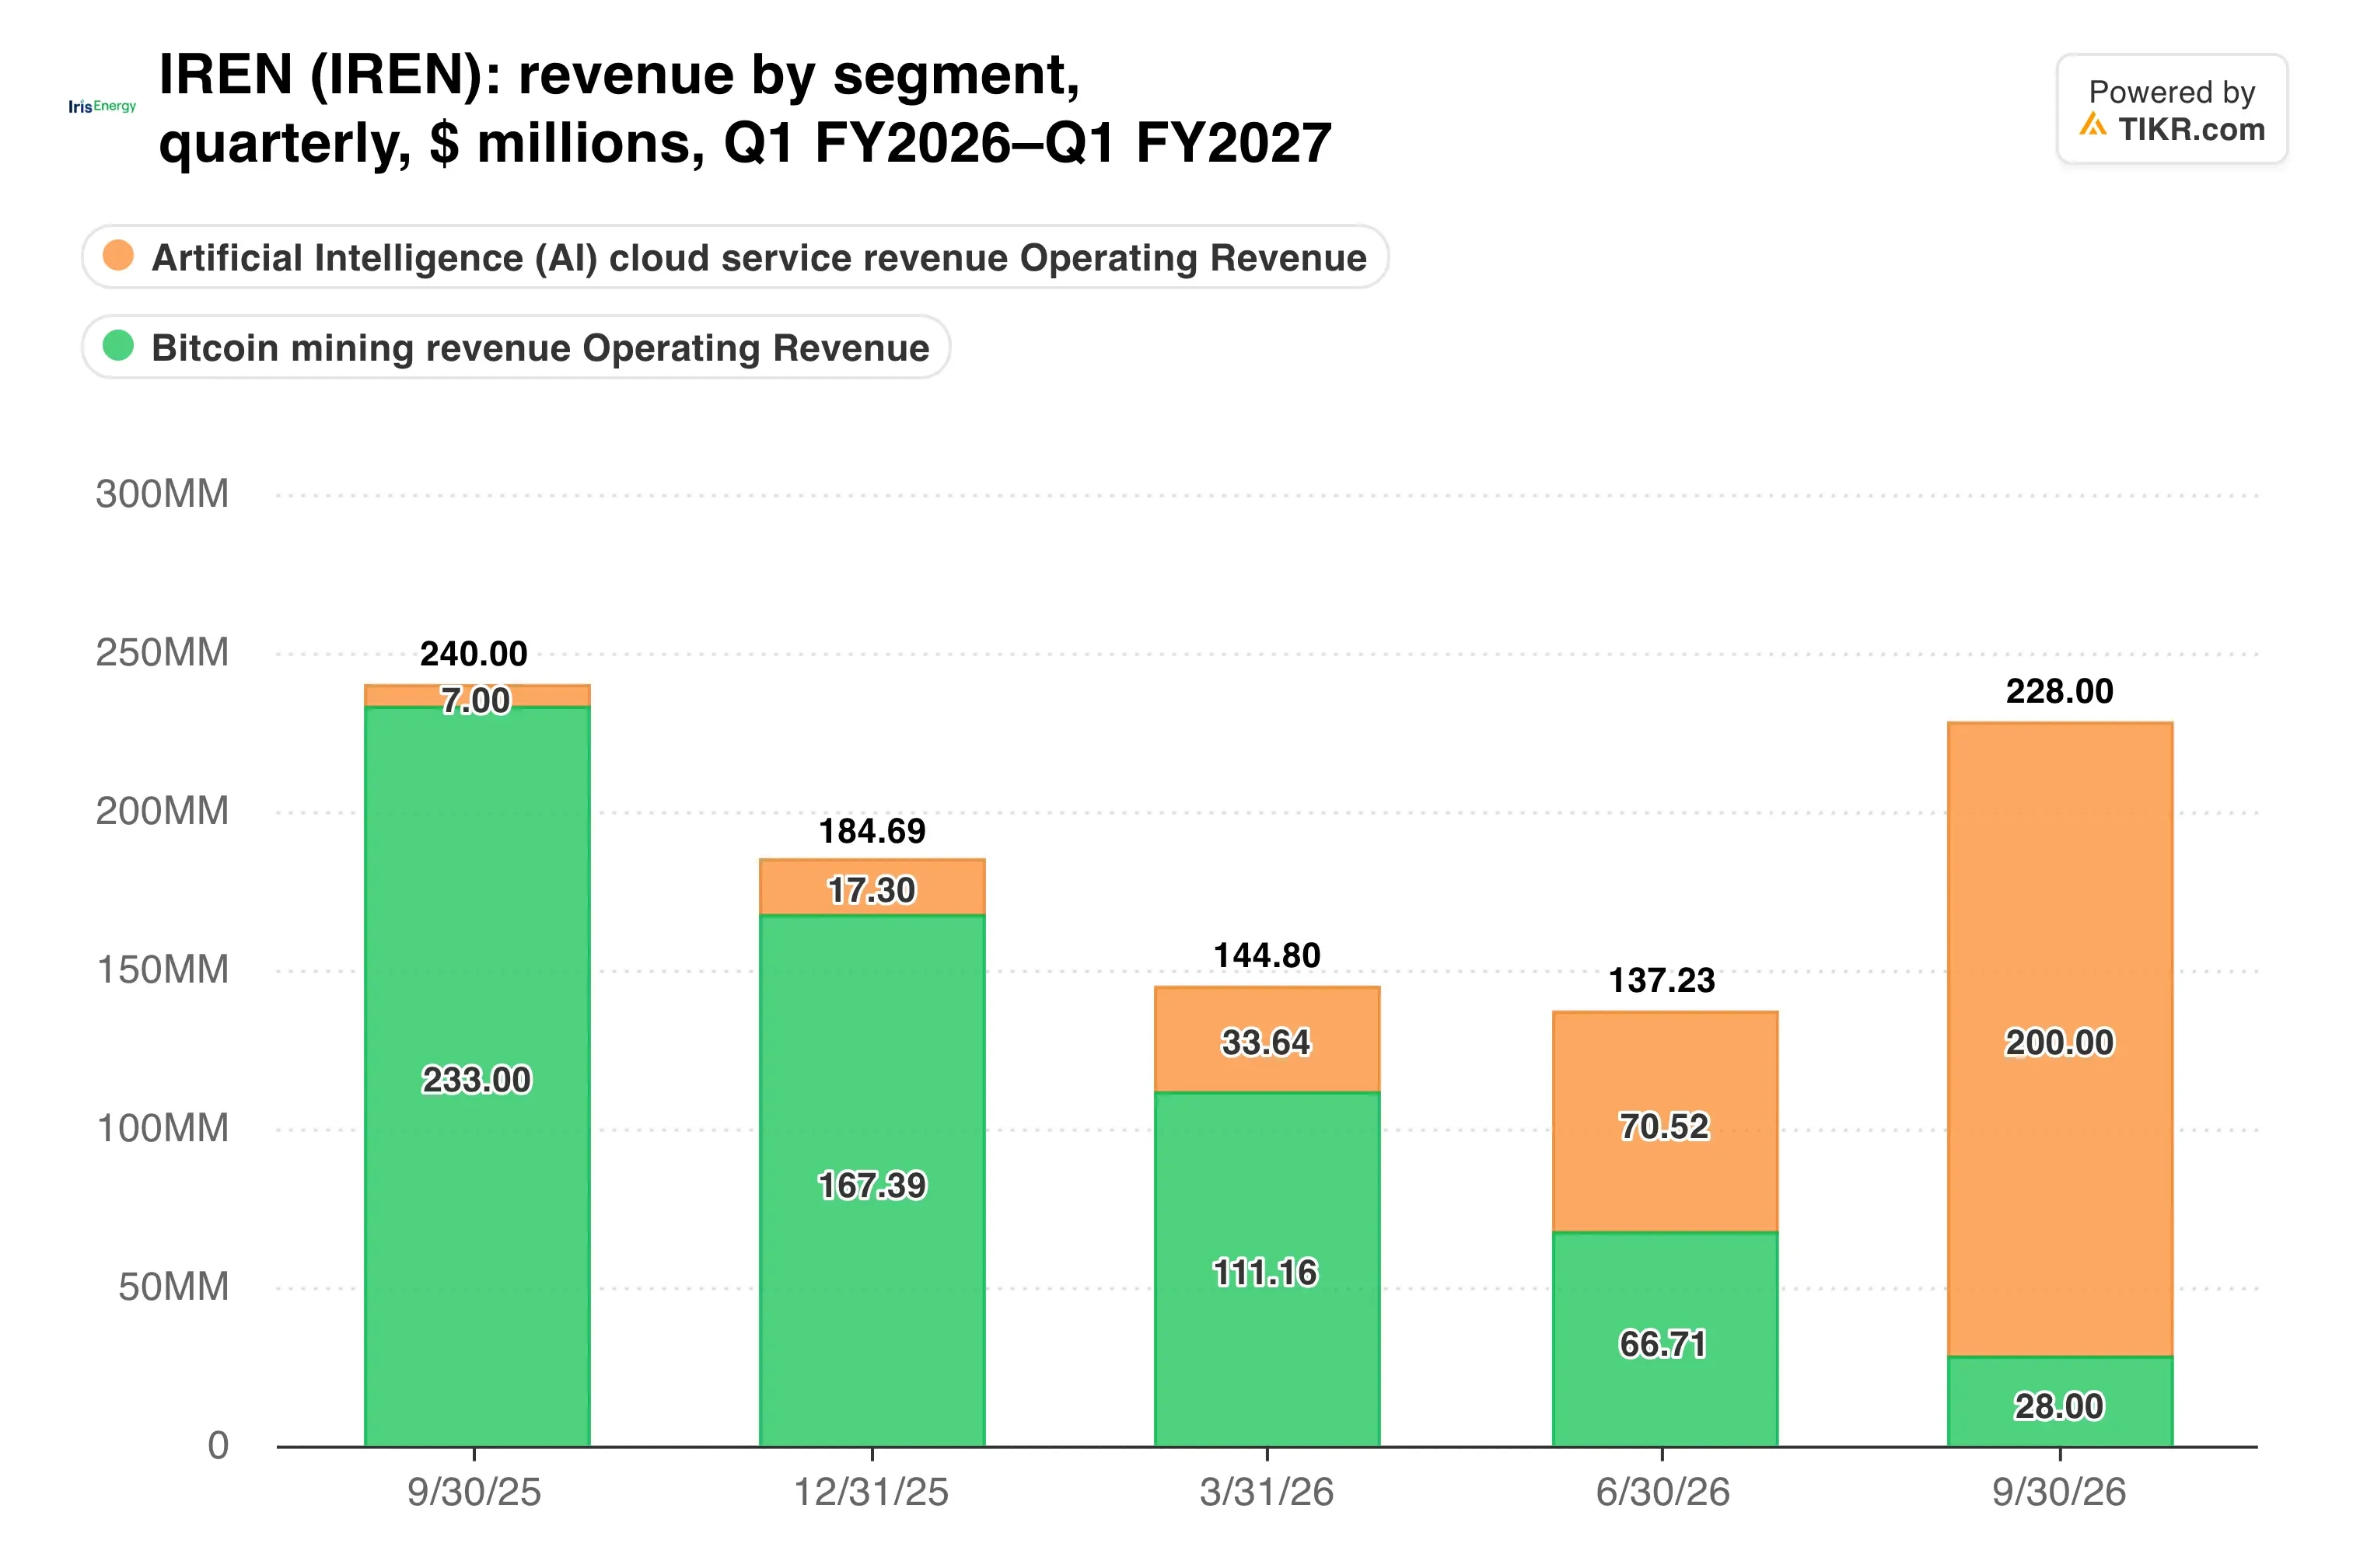
Horizon 1 lease revenue added $65 million in its first quarter.
That shift is lifting profitability. Gross margin before depreciation rose to 80% from 76%, and the adjusted EBITDA margin roughly doubled to 29%. Pricing helps too, since IREN recontracted older H100 GPUs with a frontier AI lab at double the original rate.
Scale remains the gap, since CoreWeave’s backlog of about $132.5 billion is more than six times IREN’s.
TIKR tracks 20 analysts on IREN. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on IREN, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See IREN’s Analyst Ratings
The $6 billion question
IREN plans $15 billion of capex over the rest of fiscal 2027, which ends in June. Cash, committed GPU financing and customer prepayments cover about $9 billion. Yet the other $6 billion still depends on market conditions.
Co-CEO Daniel Roberts said investor questions have moved to “whether it can be delivered, financed, and run at a profit.”
Heavy spending is already visible in the cash flow statement…
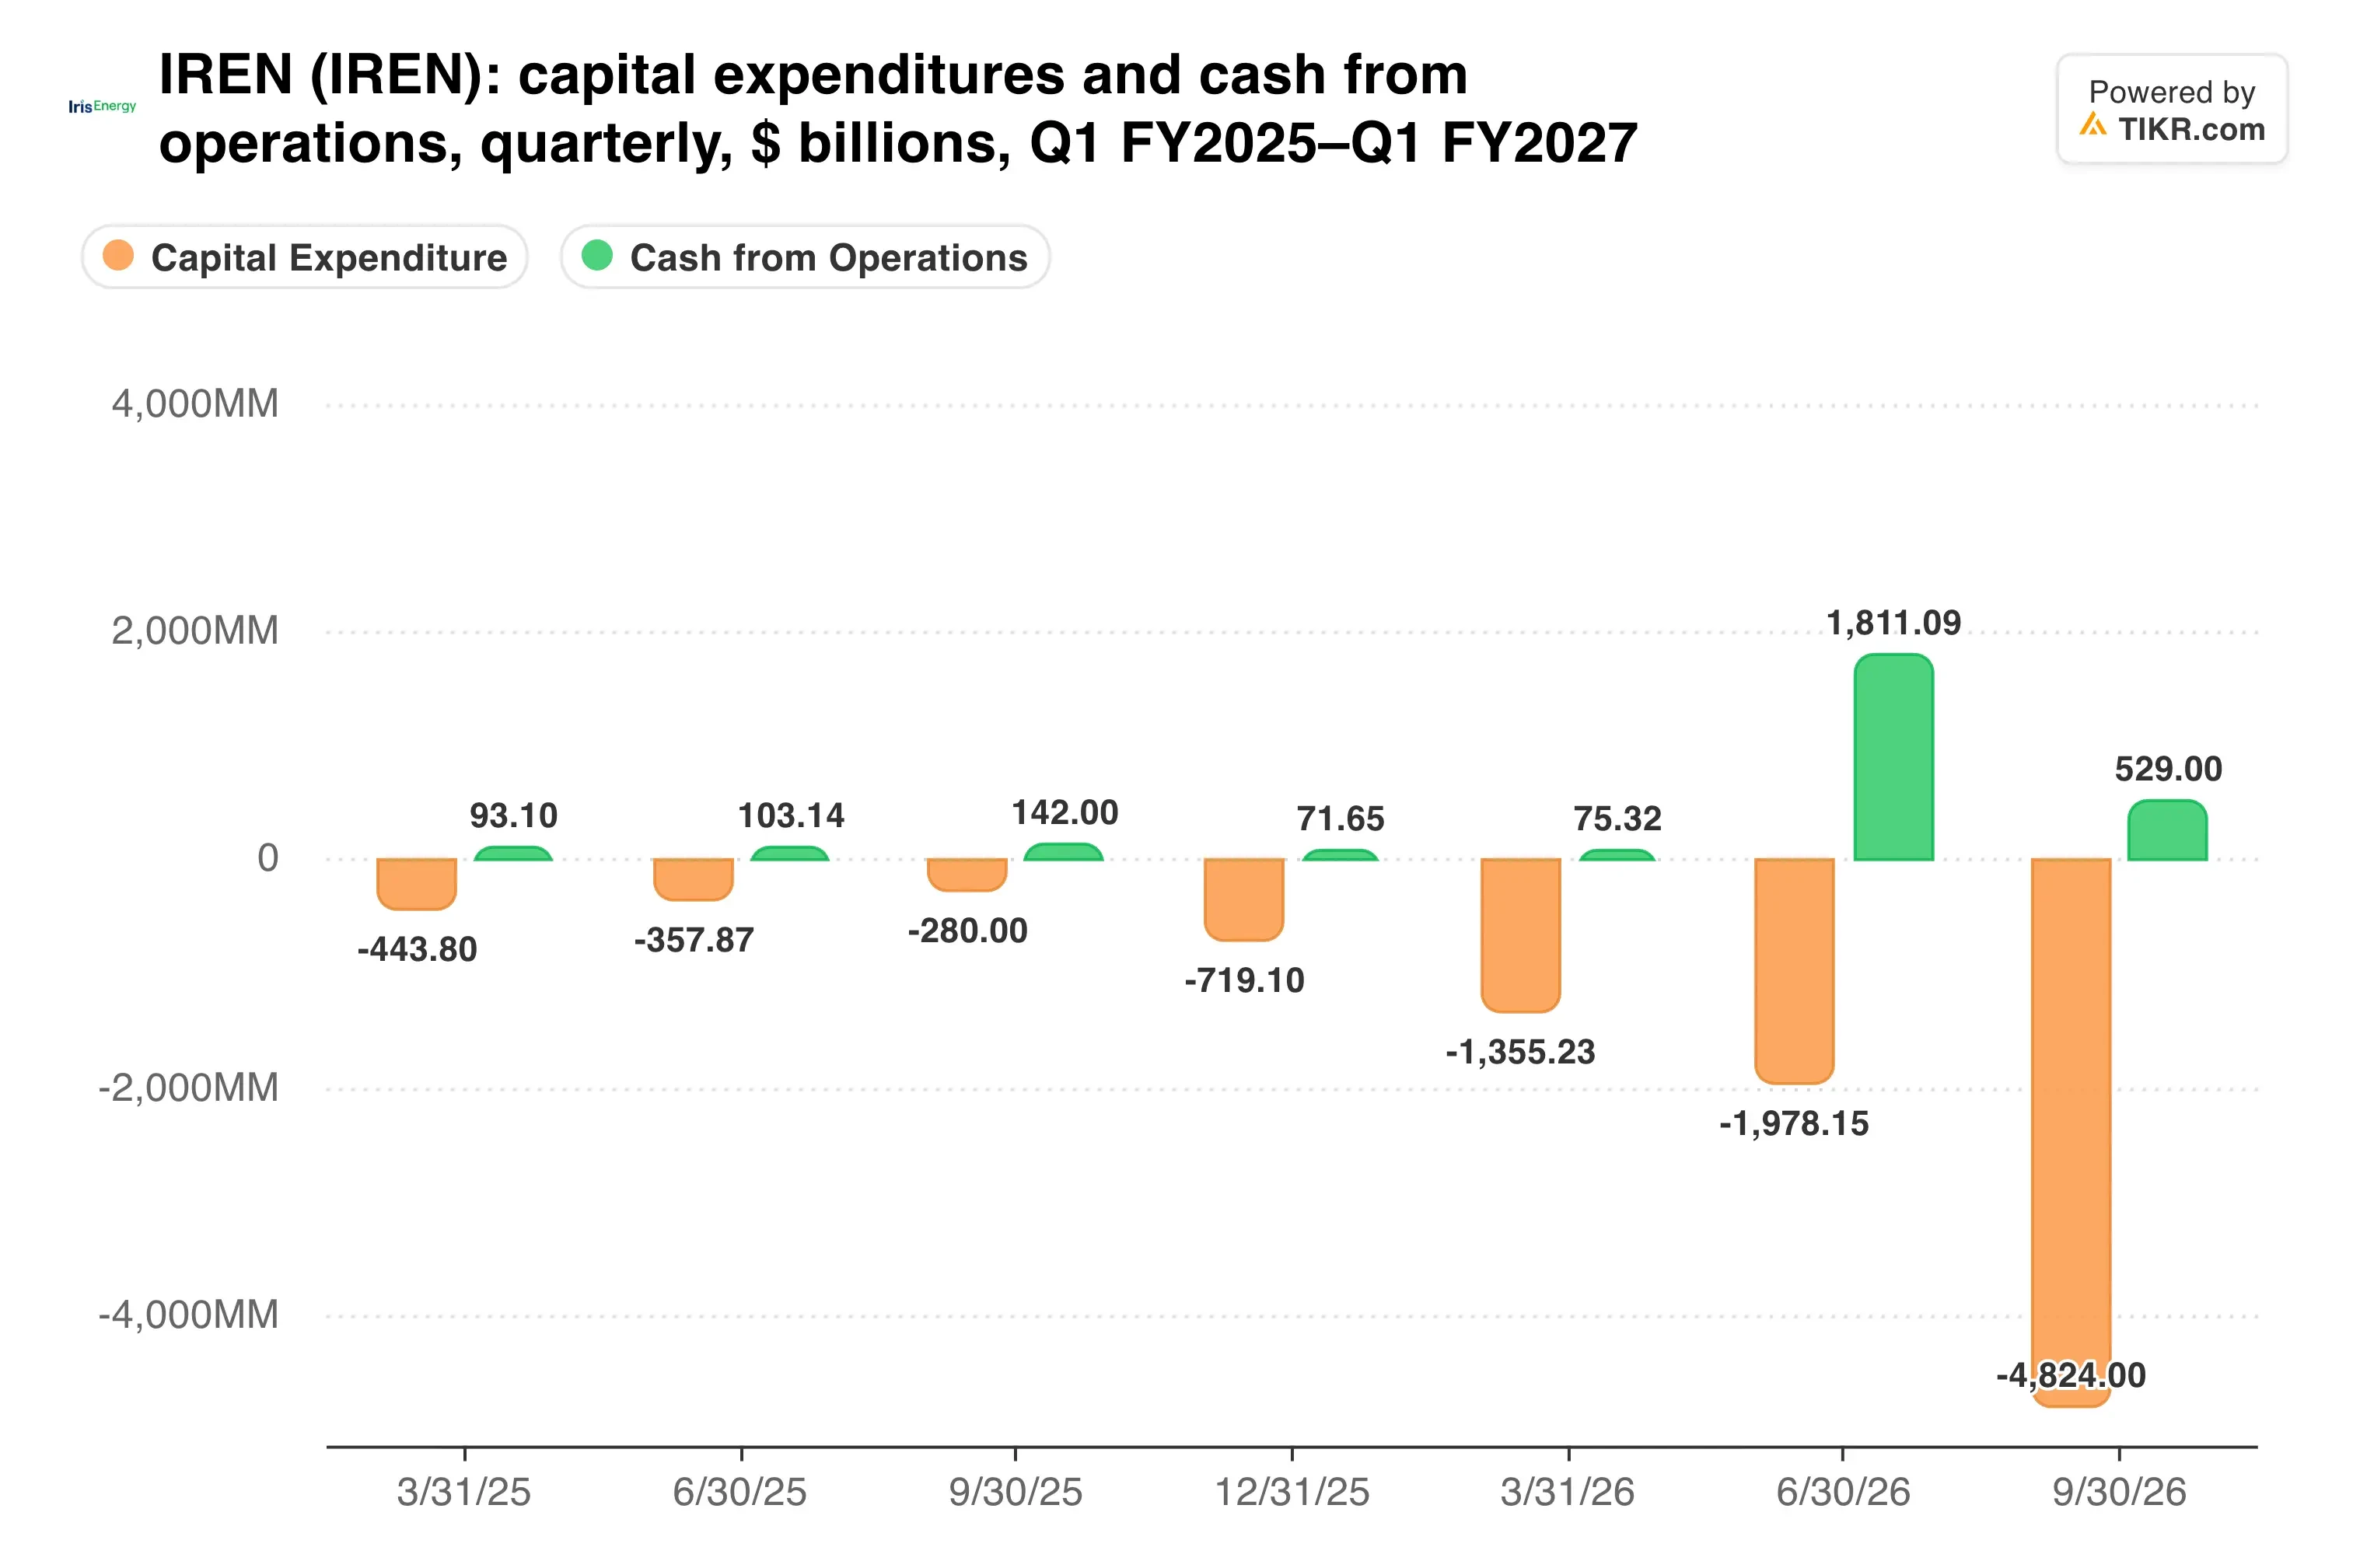
So the quarter still ended with a $263 million net loss.
Prepayments are the cleanest fix. After quarter-end, IREN signed a five-year contract at about $22 million per megawatt. “We just had a customer agree to fund 90% of the GPU capex,” Roberts said. By comparison, CoreWeave expects about $9 billion of customer prepayments and deposits within three months.
My take: IREN has solved its demand problem, and pricing keeps improving. The risk now is funding, especially if credit stays tight while Microsoft keeps changing specs. I would want that $6 billion gap to shrink before calling the selloff overdone. Still, the stock already trades far below its 2026 highs.
Shareholders vote November 24 on share repurchases tied to IREN’s prepaid forward and capped call deals. The December quarter report, expected in February, then shows whether the $4 billion run rate arrived on time.
So what is IREN stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what IREN could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!