Key Takeaways
- Greenoaks, a firm that manages $18.3 billion, sold out of DoorDash and Cerebras in the third quarter, its latest 13F shows.
- Both were small positions next to Coupang and ServiceTitan, which it added to.
- DoorDash trades below its usual forward multiple, while Cerebras still trades at about 93x forward earnings as its targets fall.
- Following Greenoaks out of Cerebras makes sense, but DoorDash looks worth holding at today’s price.
Greenoaks sold all of its DoorDash (DASH) and Cerebras Systems (CBRS) stock in the third quarter, its 13F for the quarter ended Sept. 30, filed Nov. 16, shows. The firm manages $18.3 billion in all, and its 13F holds $2.4 billion of US stocks across nine positions.
Both stocks are well off their highs, and Wall Street sees big upside in each. So should you follow Greenoaks out of either one? The numbers split them.
These were small bets for Greenoaks
At June 30, DoorDash was 3.9% of Greenoaks’ 13F stocks (500,000 shares worth $92 million), and Cerebras just 1.4% (150,000 shares worth $33 million). Its bigger bets went the other way. Coupang (CPNG), its No. 2 position, made up 18.5% of its 13F stocks at Sept. 30, worth $443 million after Greenoaks added 24% more shares. It also bought 42% more ServiceTitan (TTAN), its No. 3 at 5.0%. So the fund still has plenty riding on online retail: its Coupang stake alone was worth nearly five times what its DoorDash stake was in June.
TIKR tracks 42 analysts on DoorDash. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DoorDash, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DoorDash’s Analyst Ratings
DoorDash is cheaper than it’s been in years
DoorDash’s last close is 8% below its Sept. 30 close, and the stock sits 29% below its 52-week high. The worry is competition. On Nov. 5, Amazon started sending Prime members’ restaurant orders to Uber Eats, with no delivery fee on orders of $25 or more. Four days later, McDonald’s named Uber its preferred delivery partner in 14 markets. None of those orders go through DoorDash’s app or its ads.
The business itself is holding up: order value grew 23% in the third quarter, excluding Deliveroo, DoorDash said in its Oct. 29 release. But analysts have trimmed their 2027 normalized EPS estimate to $7.63 from $8.25 in late October, and its planned $17 billion purchase of Instacart faces antitrust scrutiny.
The Street’s average target has slipped to $250 from $276 a year ago, though it has stayed between $245 and $277 all year.
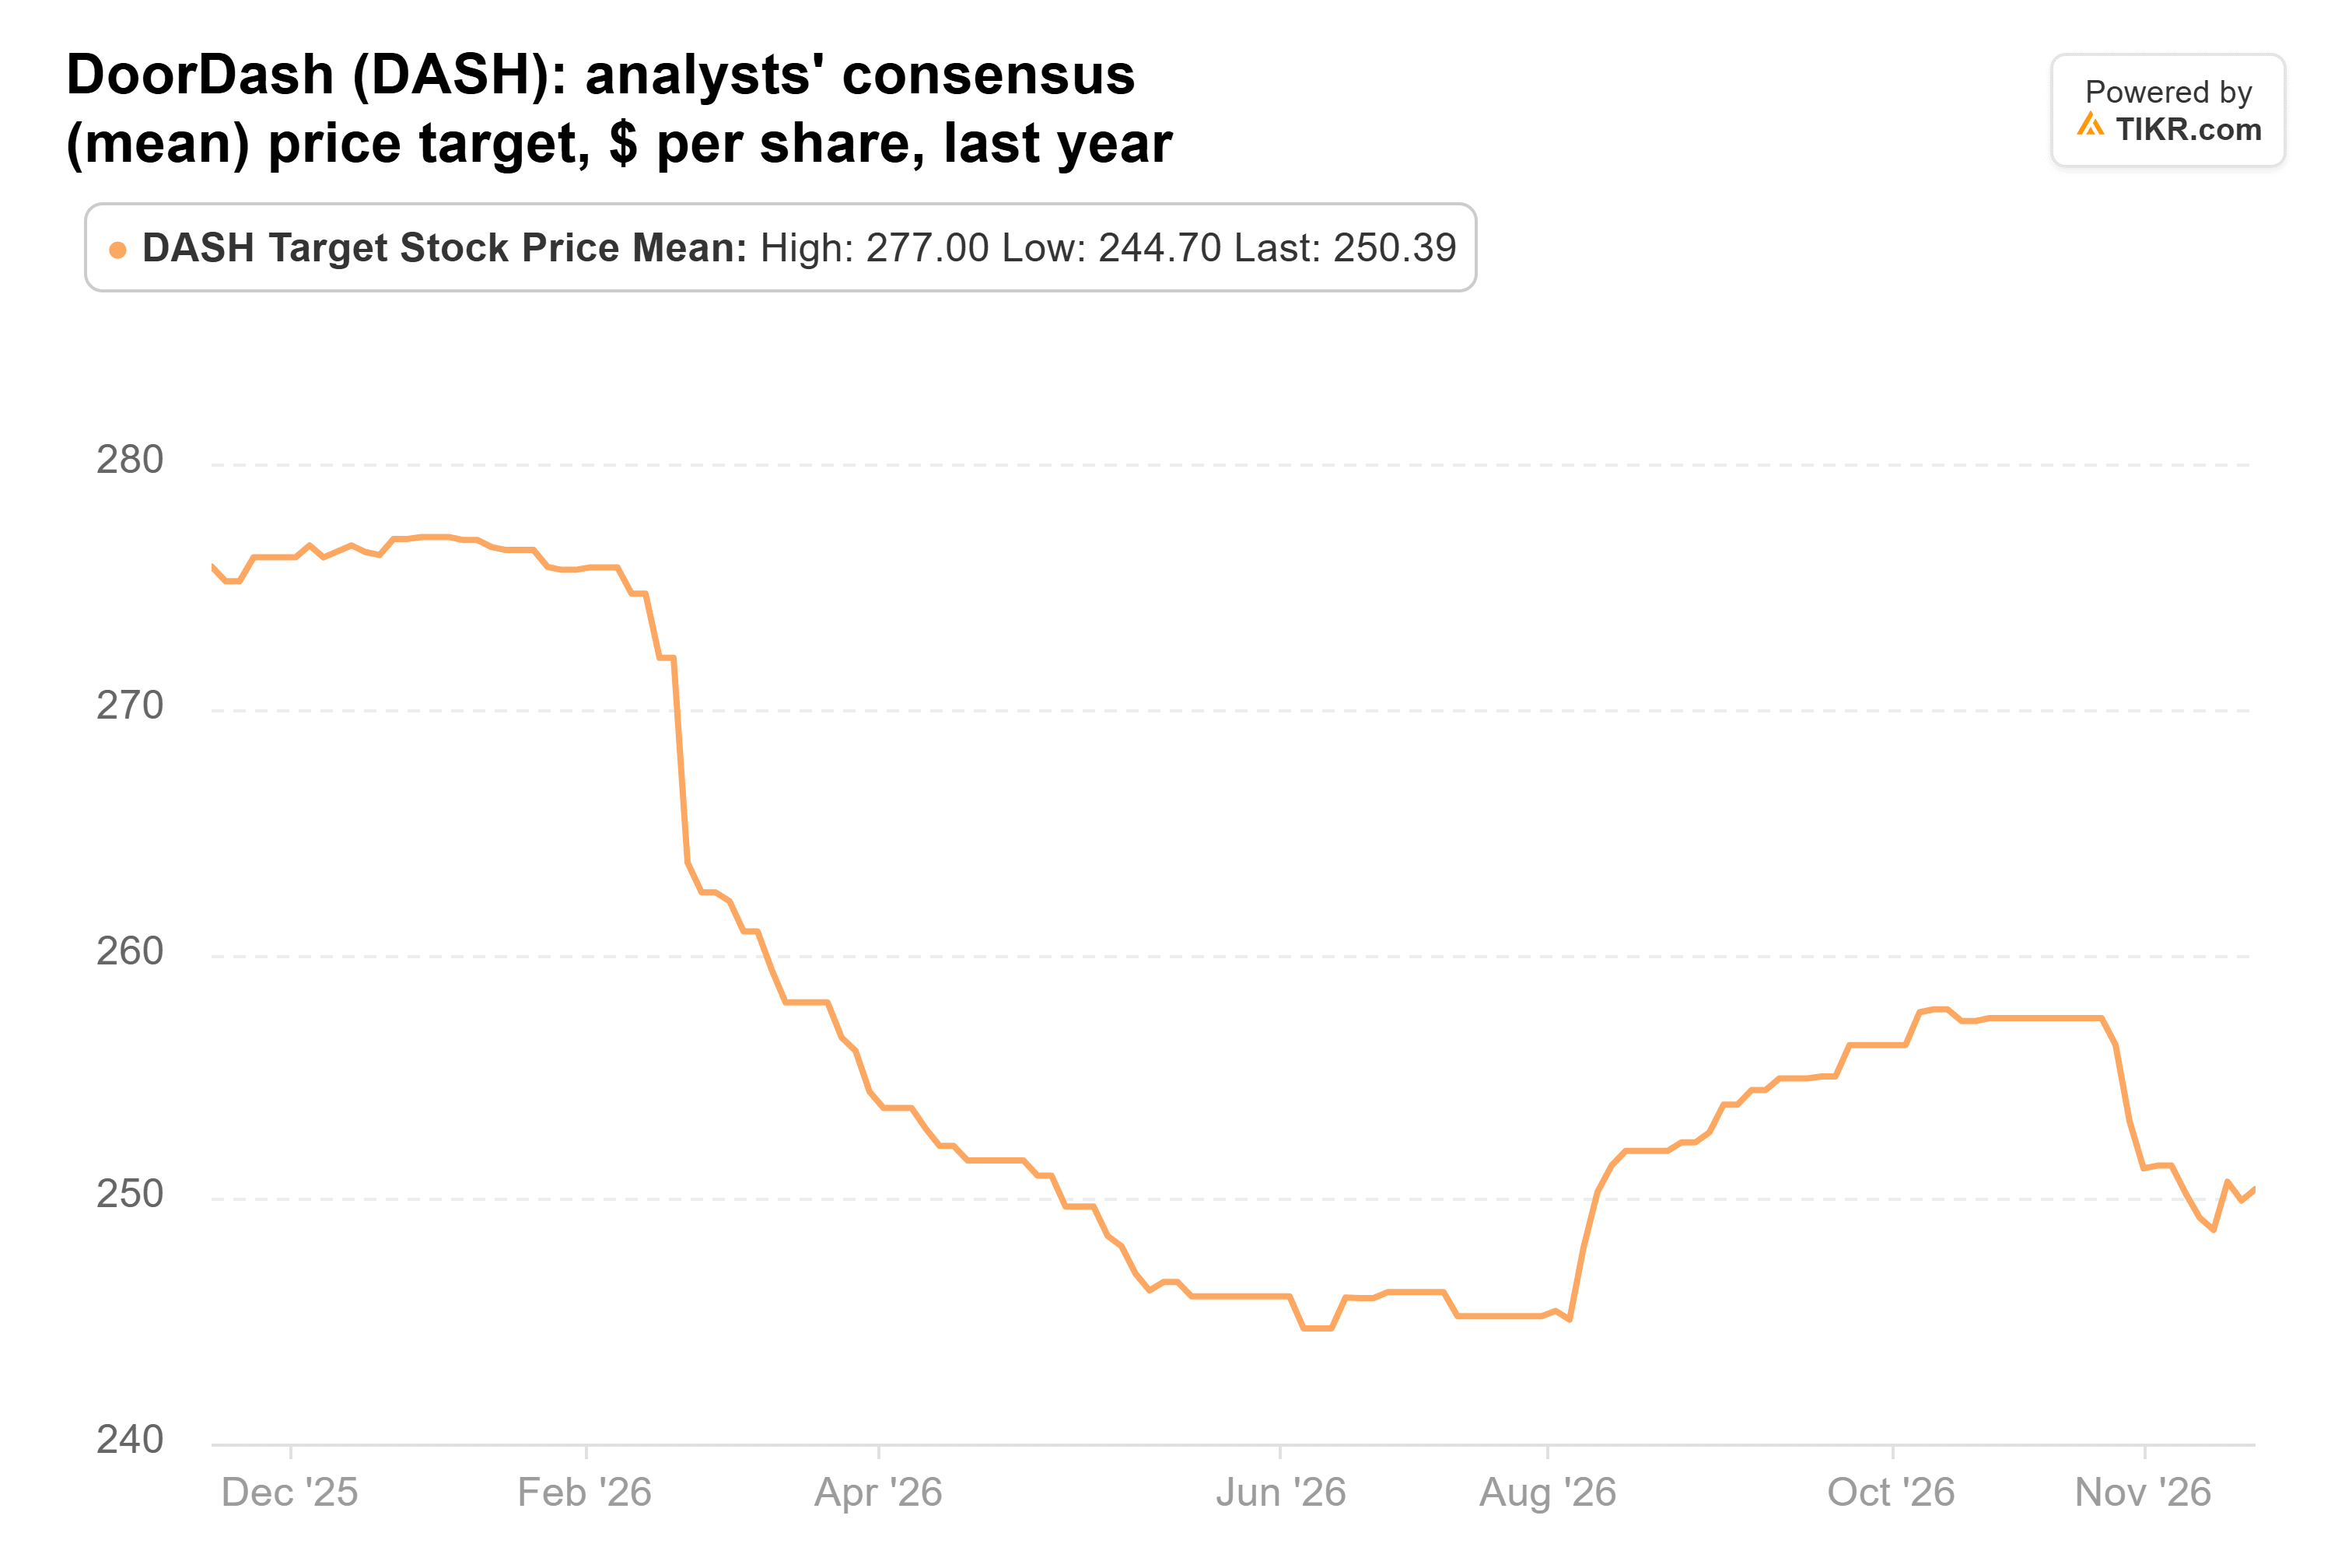
That target sits 47% above the last close, and MoffettNathanson kept its Buy rating on Nov. 11 even as it cut its target to $239 from $277. Meanwhile, at about 25x forward earnings, DoorDash trades below every quarter-end reading since December 2023. Those readings ran from 27x in March 2026 to 50x in March 2024.
Cerebras still has a lot to prove
Cerebras has had a much rougher ride: its last close is 54% below its Sept. 30 close and 74% below its 52-week high. Research firm SemiAnalysis reported on Sept. 30 that OpenAI would run a new model’s Ultrafast mode on Nvidia’s chips instead of Cerebras’s. Insiders began selling as its post-IPO lockup ended in early October, and on Oct. 28 short seller Culper Research put out a report questioning how long its chips last.
Then came a strong quarter. Third-quarter core revenue rose 70% to $230.9 million, Cerebras raised its 2026 core revenue outlook to $940 million to $960 million, and co-founder and CEO Andrew Feldman told CNBC that Microsoft signed on as a cloud customer in October. But OpenAI still makes up most of Cerebras’s $26.1 billion backlog, and the company lost $161.2 million under GAAP in the quarter.
Analysts have kept cutting their targets. The average now sits at $210, its lowest since Cerebras listed in May and down from a $294 peak in June.
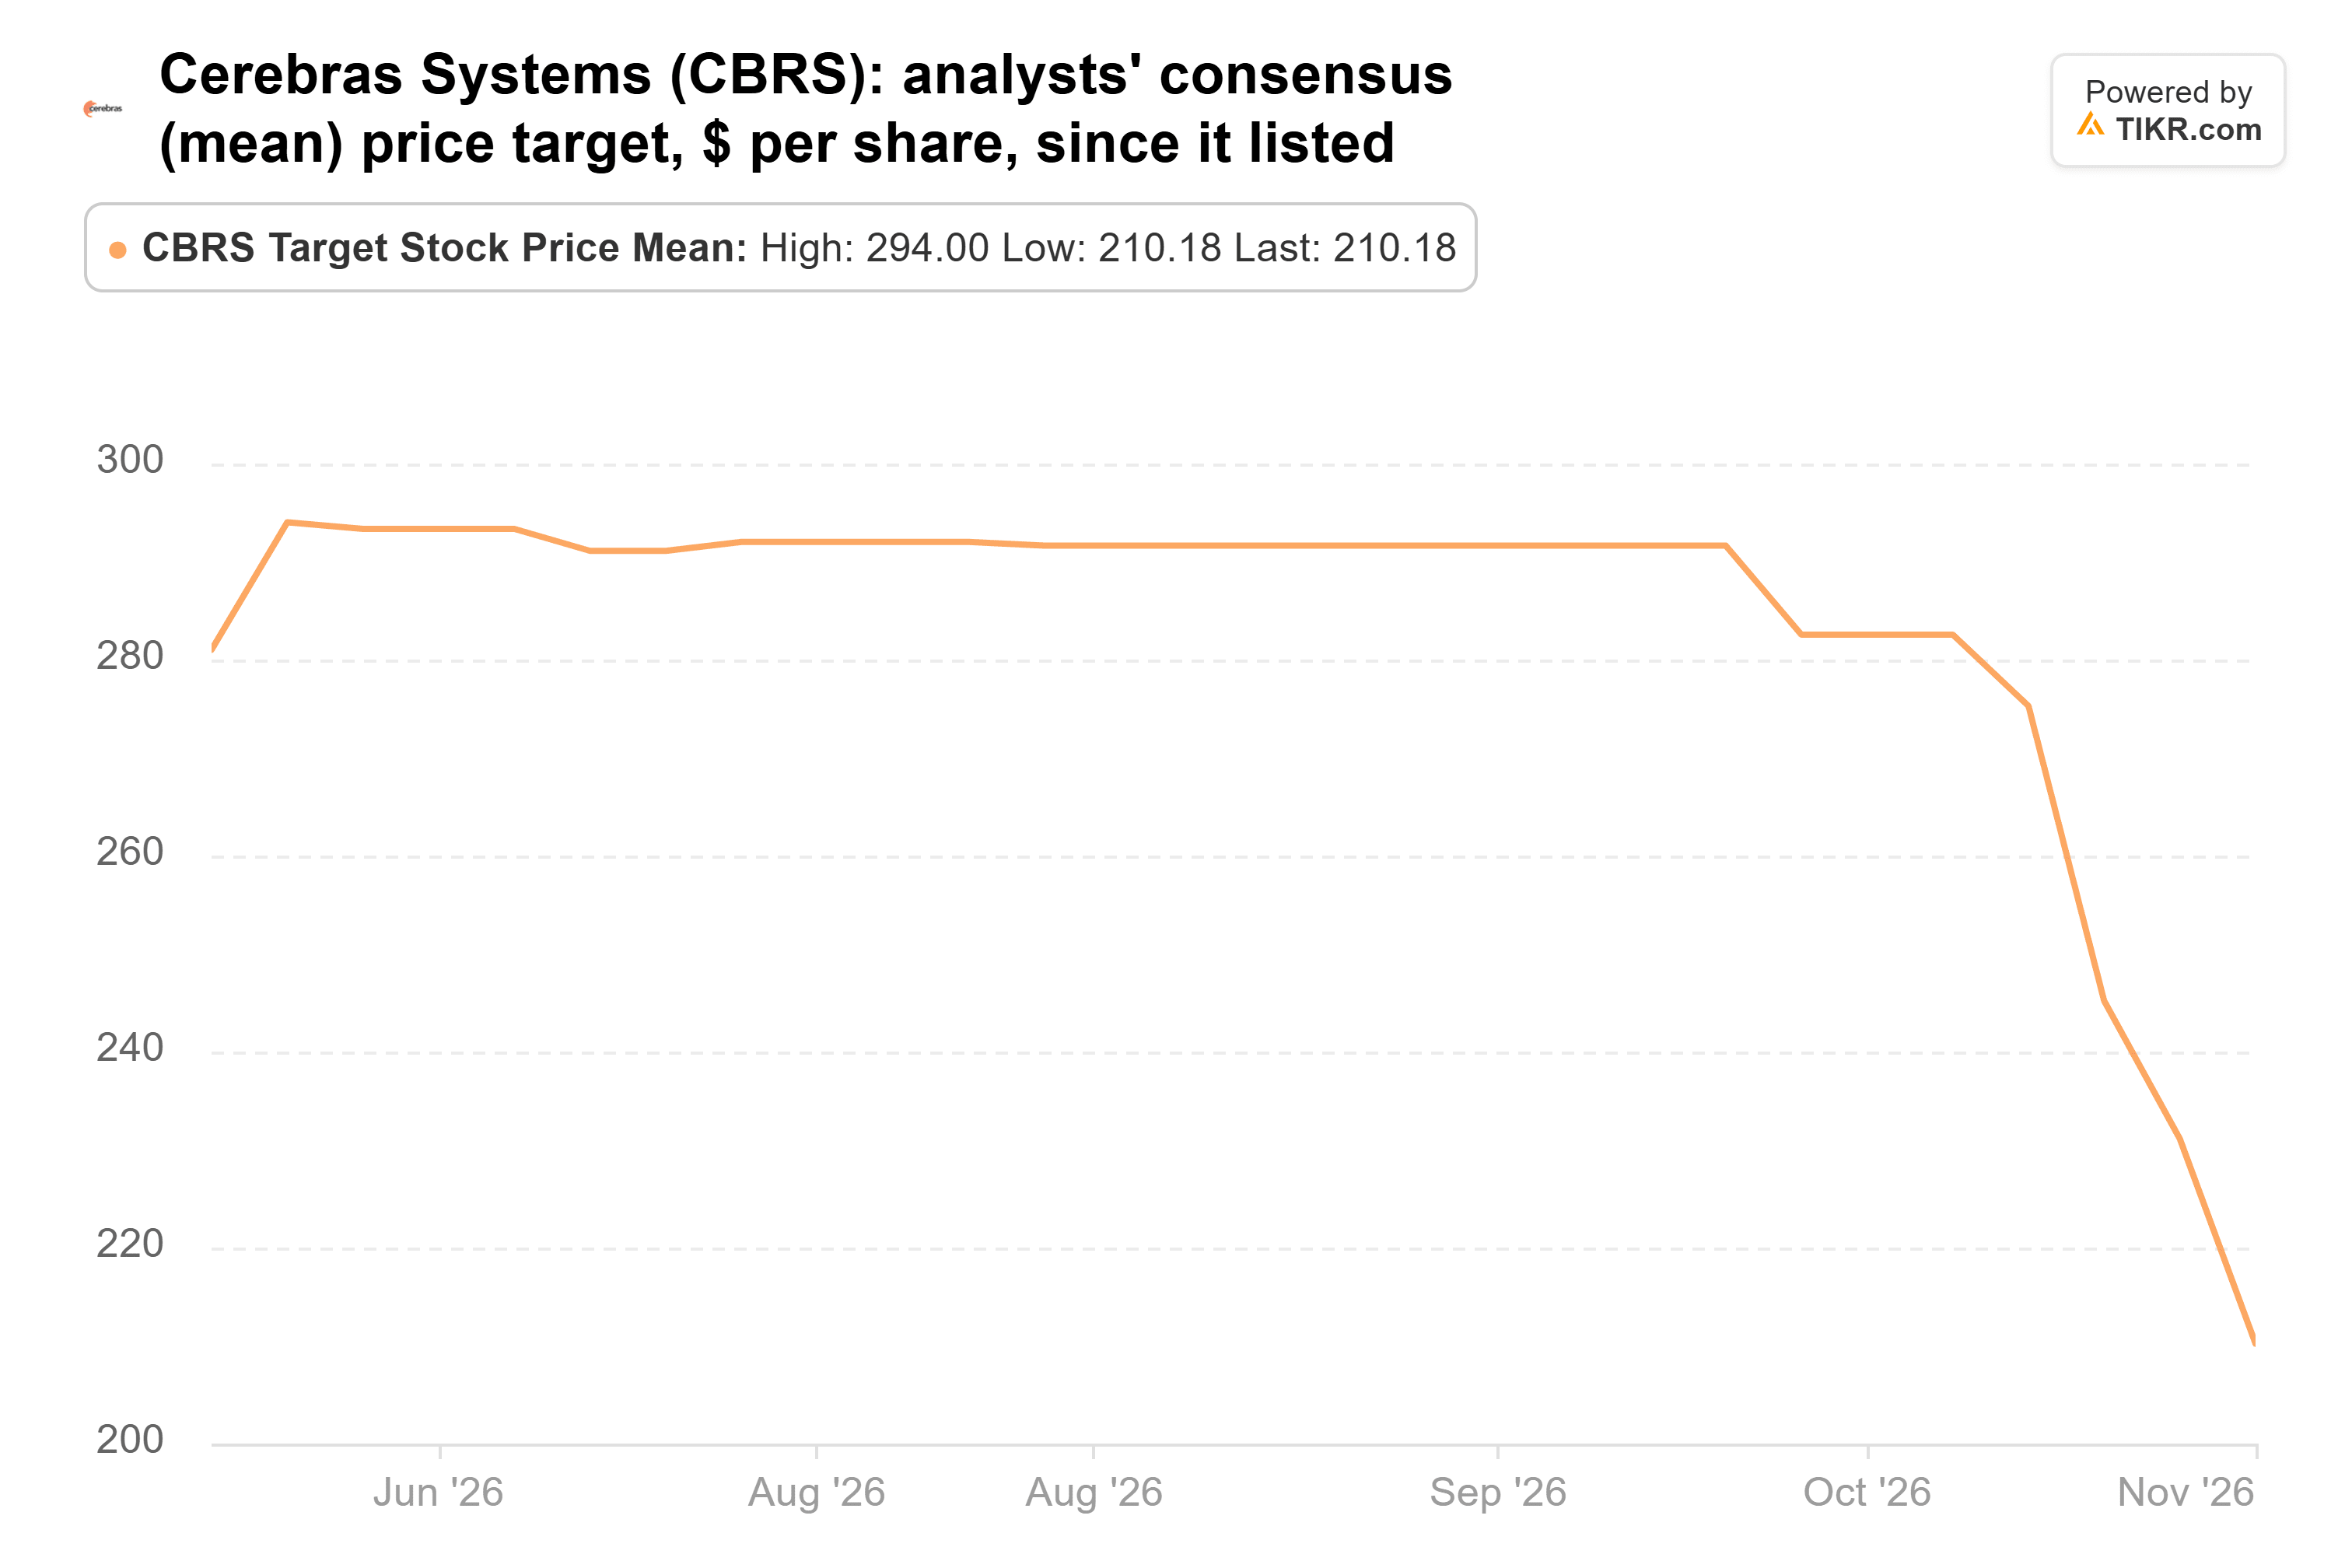
Even the lowest of the 11 analysts’ targets, $155, is 53% above the last close. And Greenoaks’ exit put it on the other side of Cathie Wood, Brad Gerstner and eight other big funds that bought Cerebras in the third quarter. At about 93x forward earnings, though, the stock still prices in a lot of growth even after its fall.
The one exit I’d follow
Both stocks carry real risk. Uber’s new deals with Amazon and McDonald’s could keep pushing DoorDash’s estimates down. Feldman also told CNBC that Cerebras is evaluating financing options, which could mean new shares.
If I could follow Greenoaks out of only one, it’d be Cerebras. A stock at about 93x forward earnings, with most of its backlog tied to one customer and its targets still falling, needs a lot to go right. DoorDash is a profitable business still growing order value at a healthy clip, and it trades at its cheapest multiple in years. I think the market is pricing in more damage from Uber than the numbers show so far.
DoorDash’s fourth-quarter report in February is the next test of whether the estimate cuts stop. And Greenoaks’ next 13F, due by mid-February, will show whether it stayed out of both.
So what is DoorDash stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DoorDash could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!