Key Takeaways
- At today’s prices, collecting $1,000 a month in dividends takes 5,661 shares of Coca-Cola, about $549,100, or 2,028 shares of PepsiCo, about $285,000.
- PepsiCo looks like the better buy for that income, as long as its turnaround gets its free cash flow growing again.
- Coca-Cola’s dividend is the less covered of the two, at 79% of free cash flow over the trailing 12 months against 75% for PepsiCo, but its cash flow is rebounding and its balance sheet is strong.
- The thing to watch is PepsiCo’s cost cutting, after its dividends ate essentially all of its free cash flow in fiscal 2024 and 2025.
Let’s take a hypothetical retiree who wants one dividend stock to pay $1,000 a month, or $12,000 a year. It’s hard to think of two more familiar names to lean on than Coca-Cola (KO) and PepsiCo (PEP).
But the two stocks charge very different prices for that income. At today’s prices, Coca-Cola’s 2.2% yield takes 5,661 shares, about $549,100. PepsiCo’s 4.2% yield takes 2,028 shares, about $285,000.
That’s a gap of about $264,000 for the same dividend check. So is Coca-Cola’s check worth paying up for?
| Metric | Coca-Cola (KO) | PepsiCo (PEP) |
|---|---|---|
| Yield | 2.2% | 4.2% |
| Shares for $1,000 a month | 5,661 | 2,028 |
| Cost | $549,060 | $285,015 |
| Cash dividend payout ratio (TTM) | 79% | 75% |
| Net debt / EBITDA | 1.45x | 1.95x |
| Forward P/E | 29x | 17x |
Source: TIKR, at today’s prices; dividends at each company’s current annual rate.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Coca-Cola is selling more almost everywhere
Coca-Cola had a strong third quarter of 2026. Net revenue grew 7% to $13.4 billion, and unit case volume rose 5%, led by India, China, Mexico and Brazil, with Coca-Cola Zero Sugar up 16%. North America was the soft spot, with volume even with a year earlier. When it reported on Oct. 27, management raised its 2026 outlook and now expects comparable EPS to grow at least 11%, up from 9% to 10%.
No wonder the stock has climbed about 36% over the past year. That run pulled its yield down from roughly 2.9%, and the stock now trades at 29x forward earnings. That’s why Coca-Cola’s check costs so much more.
The dividend takes a fairly full 79% of free cash flow over the trailing 12 months. That’s an improvement. Free cash flow covered the dividend every year from fiscal 2019 to fiscal 2023, then fell short of it in fiscal 2024 and 2025:
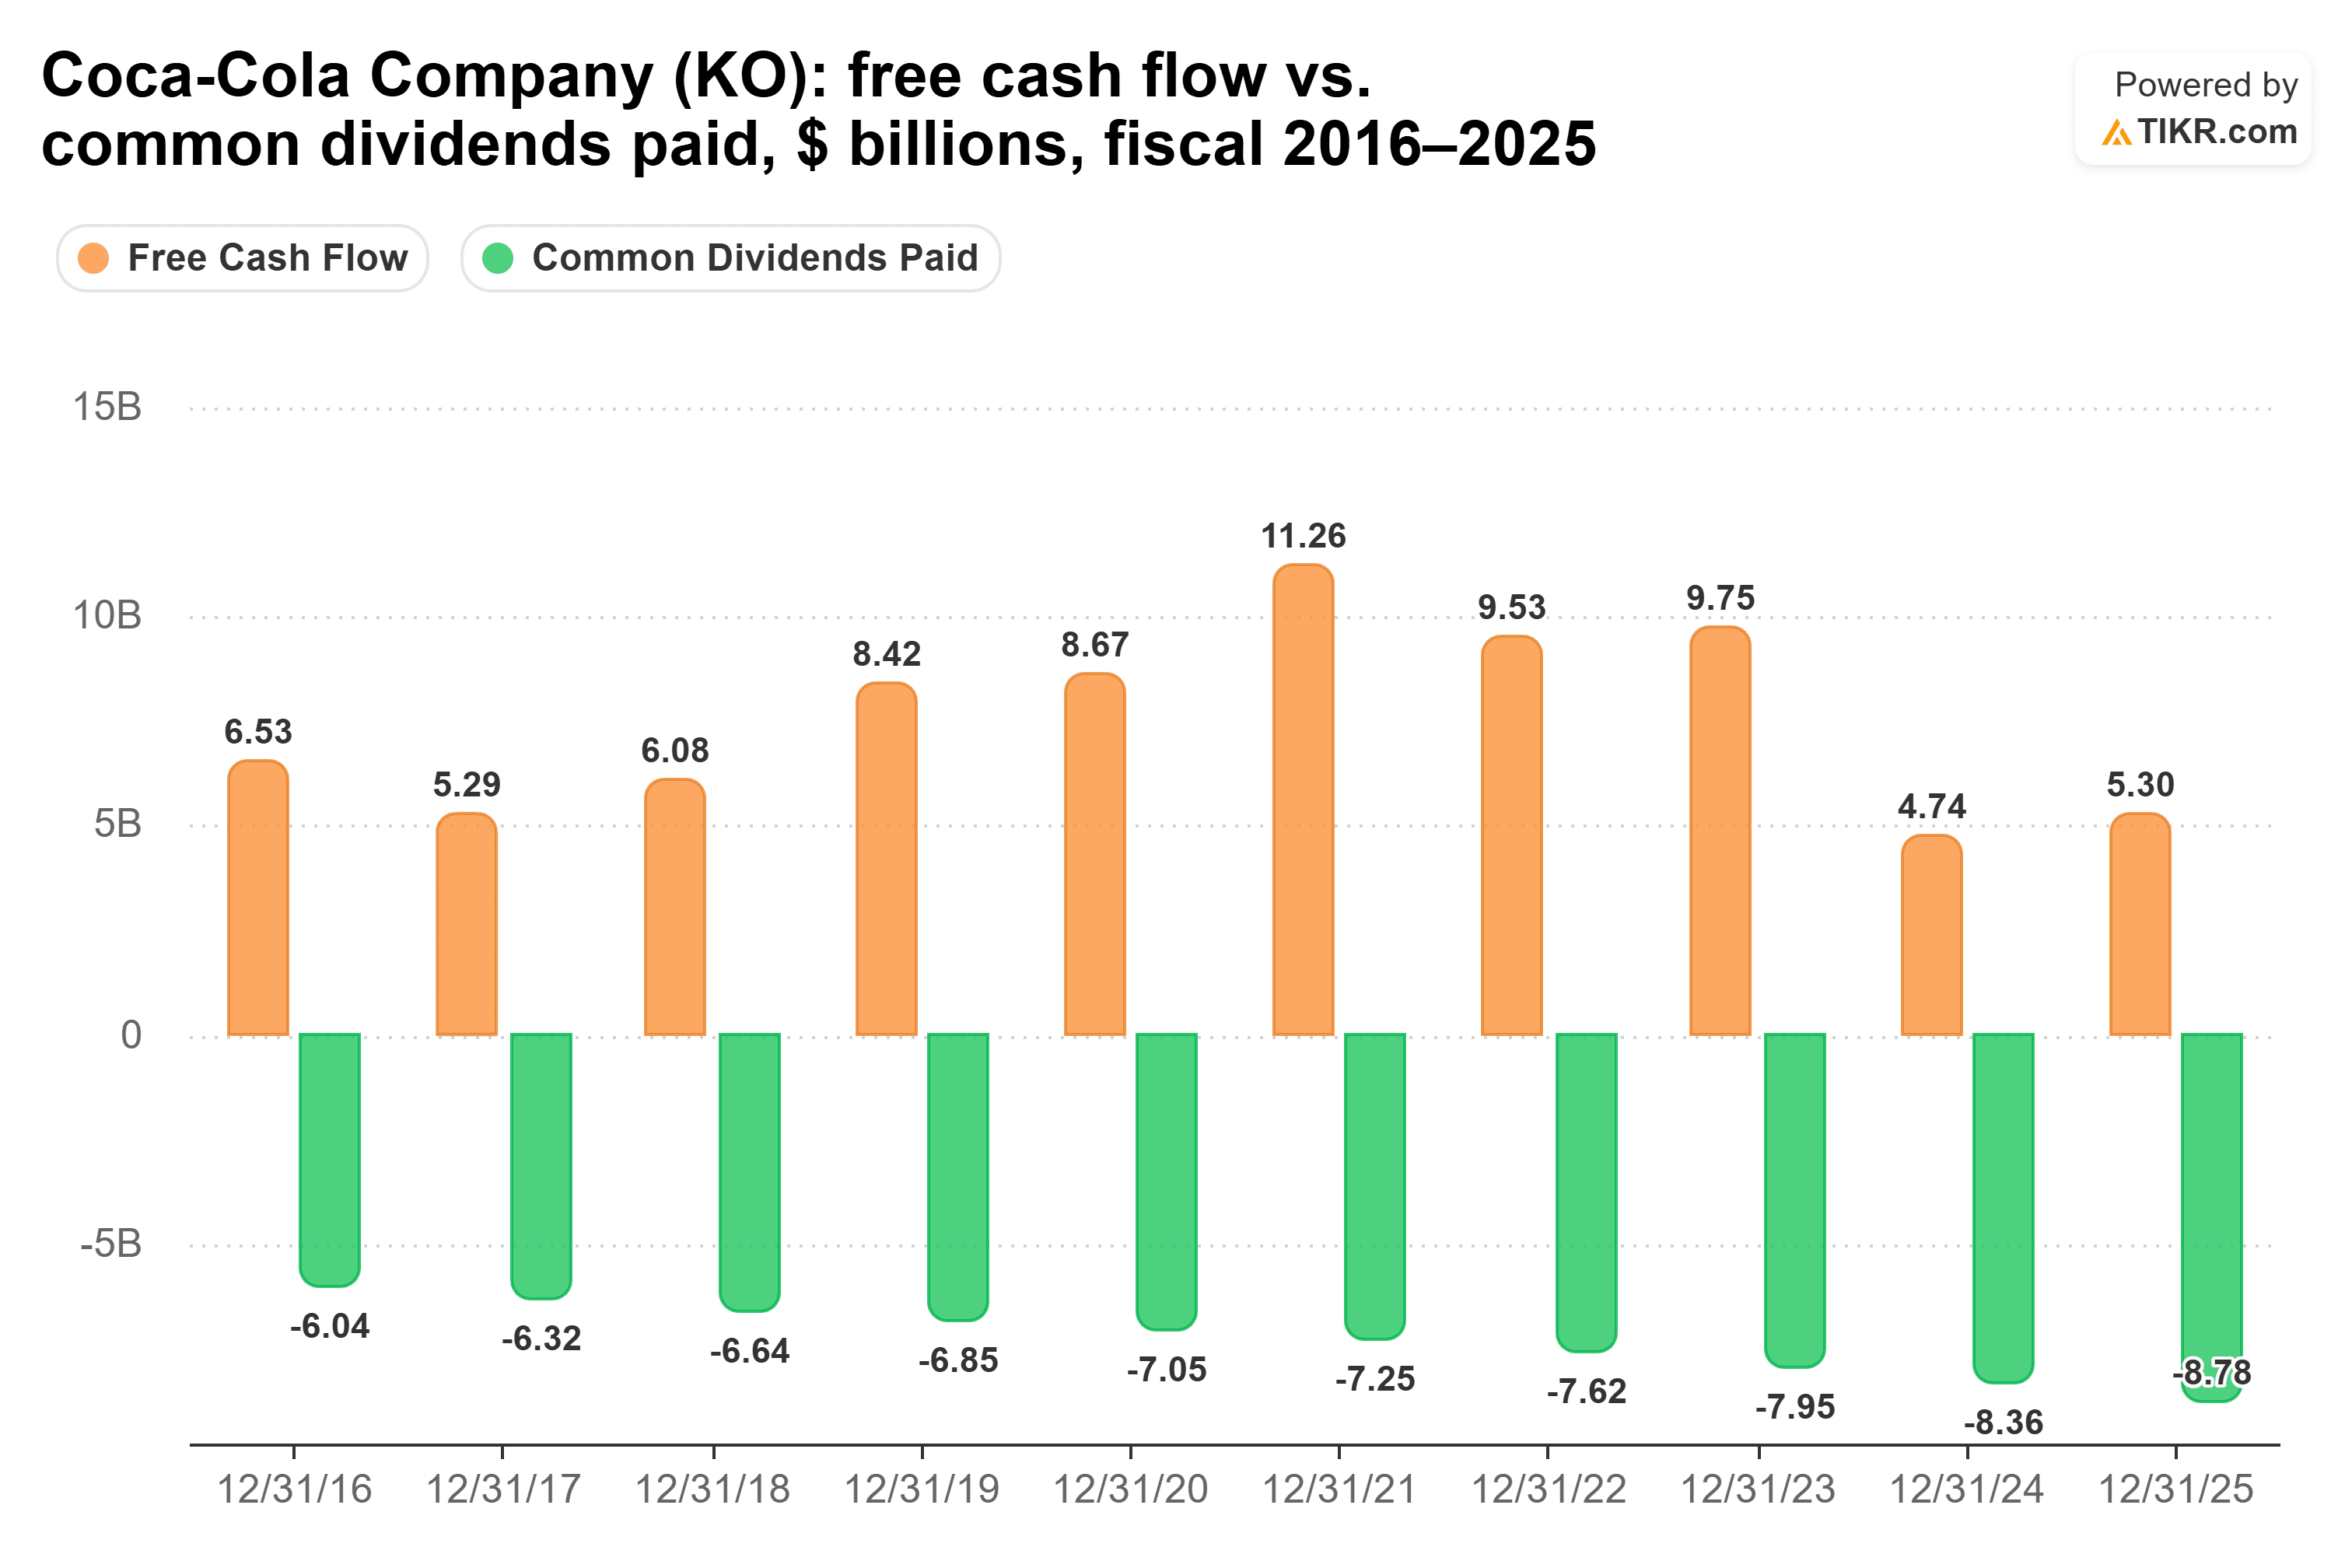
Dividends came to 176% of free cash flow in fiscal 2024 and 166% in fiscal 2025. This year, the cash is back. Free cash flow reached $11.4 billion through the third quarter, and management expects at least $13.0 billion for the full year.
PepsiCo is in fix-it mode
PepsiCo’s year has gone the other way. In its third quarter, reported Oct. 8, organic revenue grew 3.1% and core EPS rose 2% to $2.34, from $2.29. Its international businesses grew strongly, but North American beverages lagged, and PepsiCo cut its fiscal 2026 outlook for core EPS growth to 2.5% to 3.5%, from the low end of 5% to 7%. Chairman and CEO Ramon Laguarta said on the call: “we’re not satisfied with the performance in the U.S.”
Big changes are underway. PepsiCo has a new CFO, Stephen Schmitt, who joined from Walmart. And on Nov. 12, it announced about 1,000 job cuts across its North American units, part of a turnaround that activist investor Elliott Investment Management has pushed for.
The dividend has caught up with the cash. Free cash flow was $7.62 billion in fiscal 2016 and $7.67 billion in fiscal 2025, while the dividends PepsiCo paid rose from $4.23 billion to $7.64 billion:
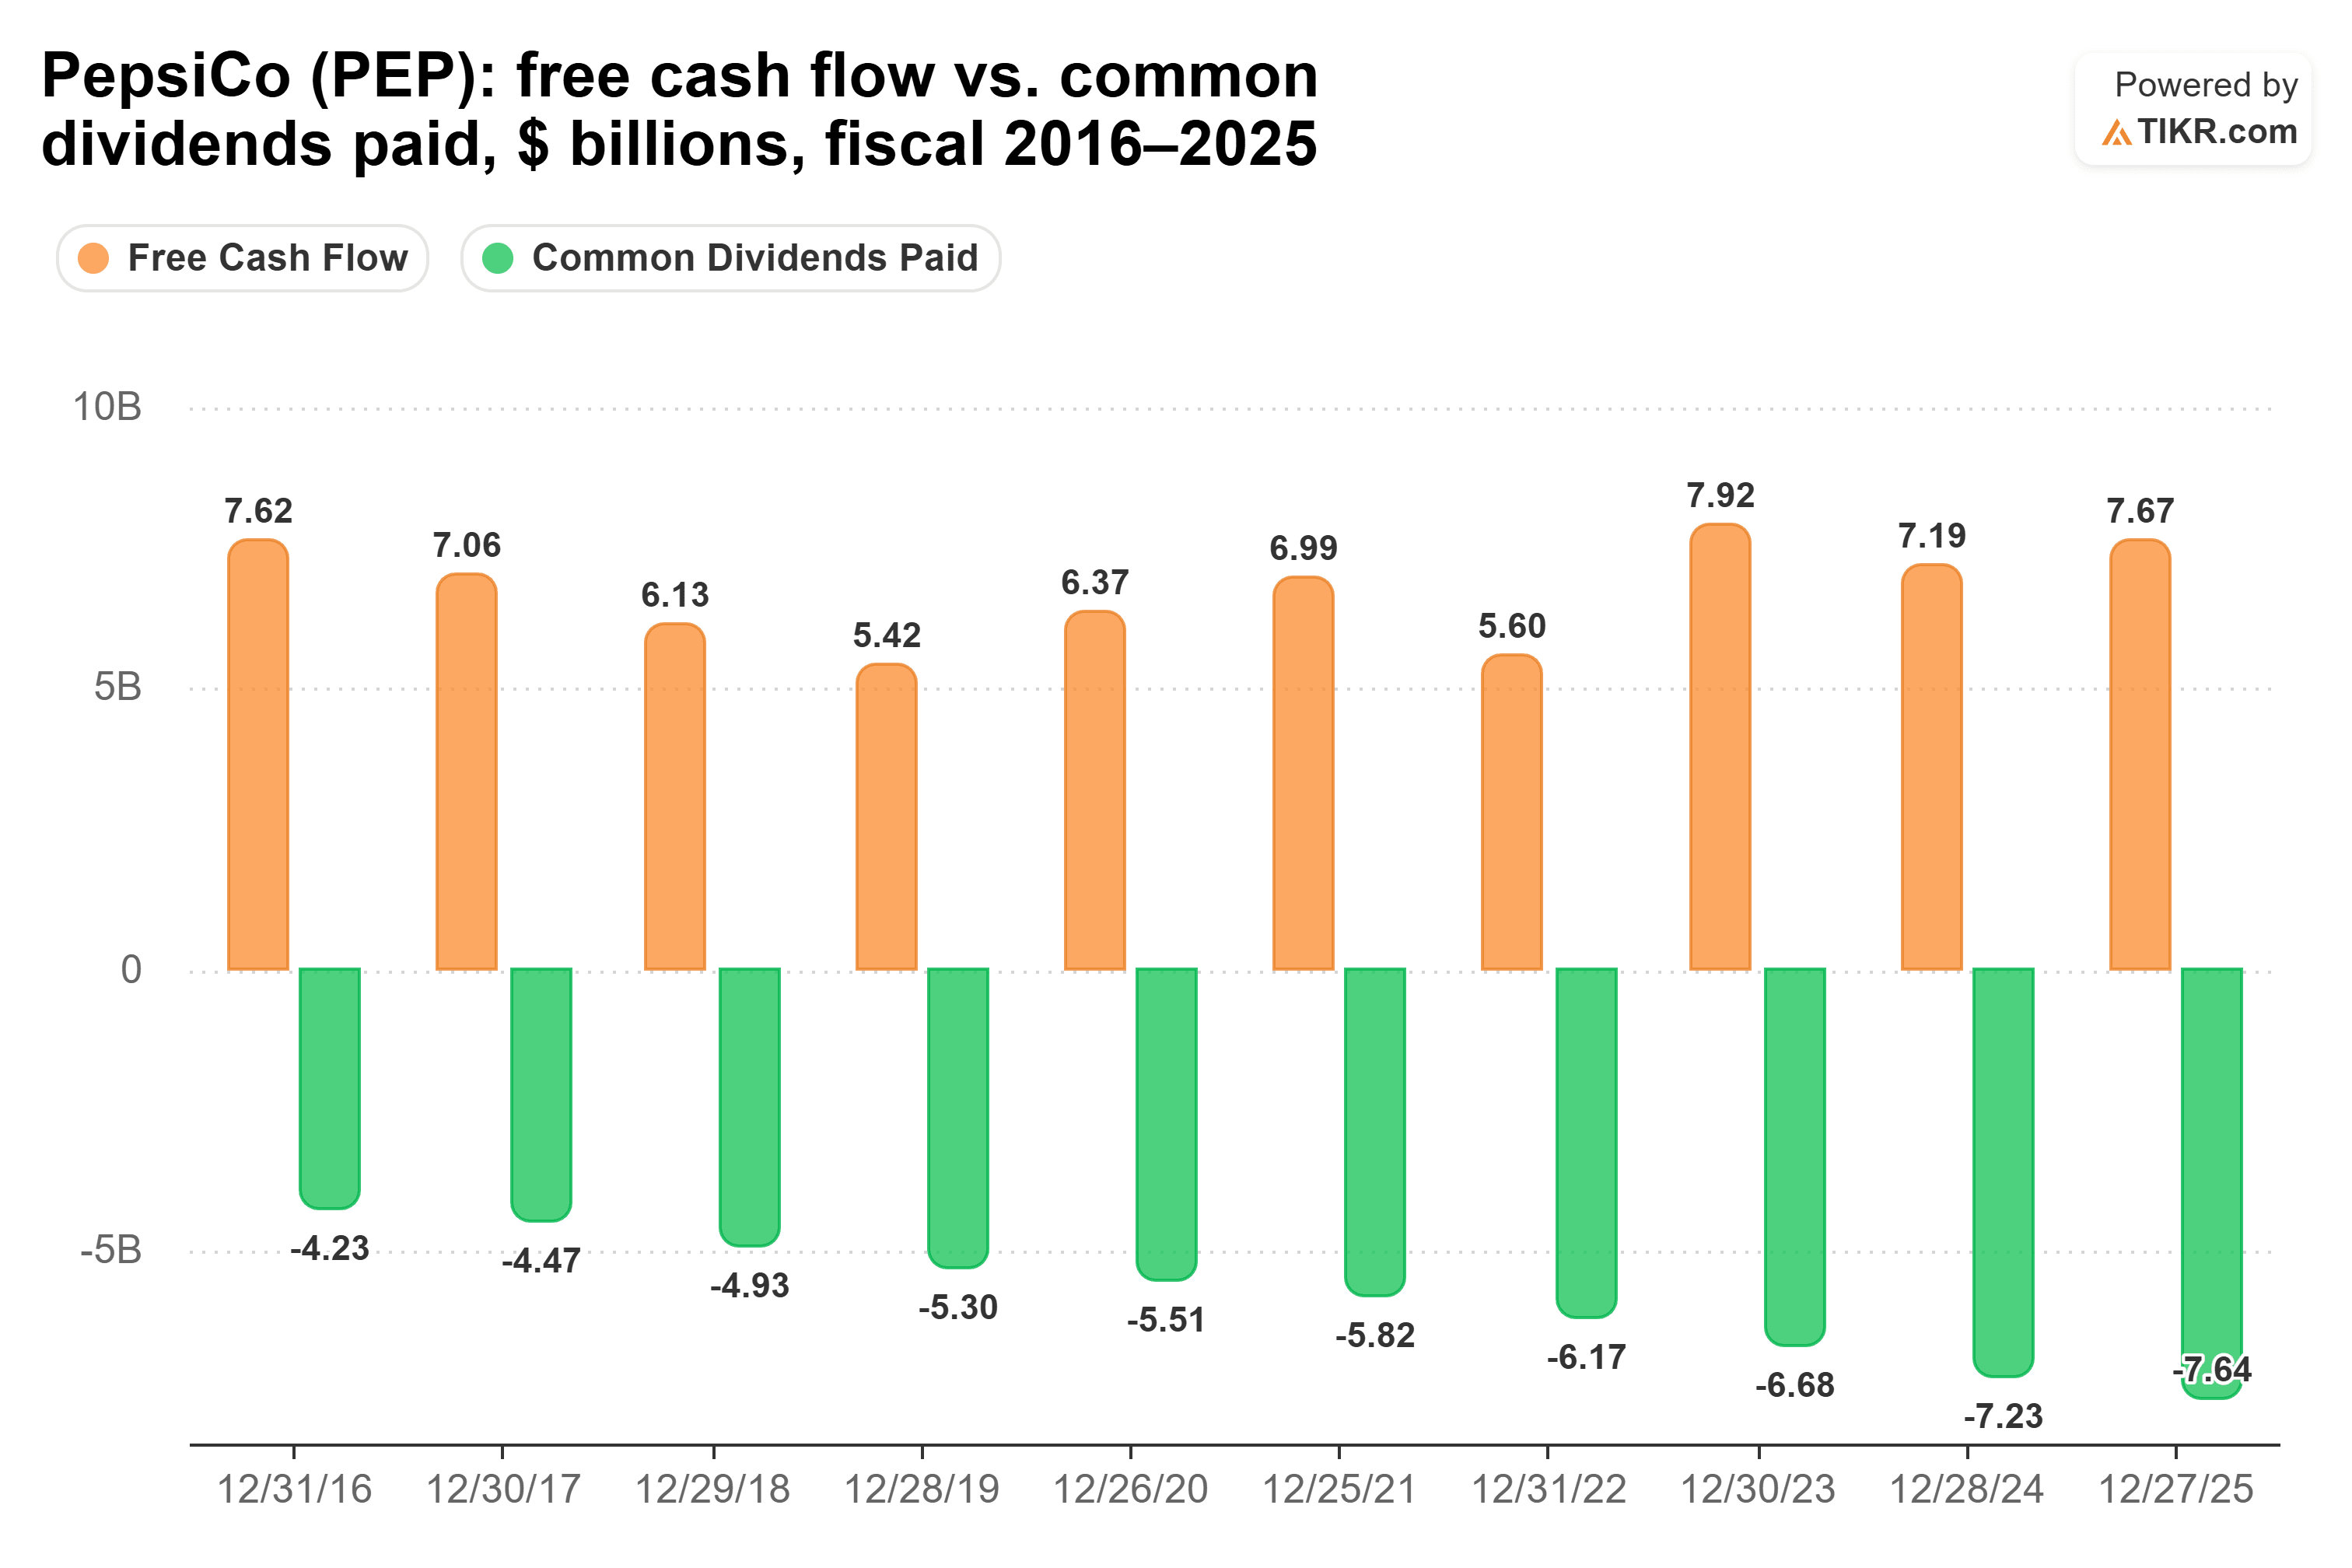
Dividends took 101% of free cash flow in fiscal 2024 and 100% in fiscal 2025, and PepsiCo sold new long-term notes in October. This year is better so far. Operating cash flow reached $7.95 billion in the first 36 weeks of fiscal 2026, up from $5.47 billion a year earlier, and the dividend takes a slightly roomier 75% of free cash flow over the trailing 12 months. Still, PepsiCo plans to pay $7.9 billion in dividends in fiscal 2026, more than all of fiscal 2025’s free cash flow.
I’d take PepsiCo’s check
Coca-Cola is the less covered of the two at 79%, so it’s the one I’d call most at risk of a cut. But being the most at risk doesn’t make it truly risky. Free cash flow is rebounding, net debt is just 1.45x EBITDA, and operating earnings cover interest 10.7x. President and CFO John Murphy said on the third-quarter call, “I believe our balance sheet today is in as good a shape as it’s been for many years.” Management also said on the call that the dividend is “primarily” how Coca-Cola returns capital to shareowners right now. The wild card is its ongoing dispute with the IRS, which is still waiting on a court decision.
Ultimately, I have to go with PepsiCo. It pays the same $1,000 a month for about $264,000 less. Its dividend also grew faster, at 6.9% a year from fiscal 2020 to fiscal 2025 against 4.5% for Coca-Cola. At those paces, PepsiCo’s 2,028 shares would pay about $21,900 in year 10, against about $17,800 from Coca-Cola’s 5,661. And at 17x forward earnings, you’re not paying a premium for it. I wouldn’t count on PepsiCo keeping that pace, though, until its cost cuts get free cash flow growing again.
This isn’t to say Coca-Cola’s check isn’t worth owning. Its business is growing faster, it carries a lighter debt load, and its cash flow is coming back strong. It’s just that, for a retiree who wants $1,000 a month, I’d rather keep that extra $264,000 working elsewhere.
Coca-Cola will give its 2027 guidance with its fourth-quarter results. PepsiCo says more structural cost cuts “will be implemented in the coming months.” If those cuts don’t lift its free cash flow, I’d happily pay up for Coca-Cola.
Forget PepsiCo: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And PepsiCo isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!