


Key Takeaways
- Home Depot reports fiscal third-quarter results before the open on Tuesday, Nov. 17, days after Stifel cut Lowe’s to Sell and called Home Depot the better-positioned of the two.
- Home Depot leads Lowe’s on comparable sales and full-year margin guidance, but its own operating margin has slipped over three years, and its second quarter leaned on $685 million of tariff refunds.
- Masco, Stanley Black & Decker and Floor & Decor have already reported, pointing to strong tool demand, soft paint and still-weak flooring projects.
- At 23x forward earnings, above its five-year average of 22x, the stock already prices in the lead, so the quarter needs an operating margin at or above last year’s 12.9% without refund help.
Home Depot (HD) reports its fiscal third-quarter results before the open on Tuesday, Nov. 17, and it goes in as the leader in home improvement. On Friday, Nov. 13, Stifel cut Lowe’s (LOW) to Sell from Hold, and analyst W. Andrew Carter said Home Depot is better positioned, with a stronger platform for professional contractors.
You can see that lead plainly in sales. Tuesday has to show it in the margin, where Home Depot has been slipping.
Three companies tied to its aisles have already reported: suppliers Masco (MAS) and Stanley Black & Decker (SWK), and flooring rival Floor & Decor (FND).
Home Depot’s lead shows up in the guide
In their second quarters, Home Depot’s comparable sales rose 1.7% against 0.2% at Lowe’s, and its transactions fell 1.0% against 2.1%. For fiscal 2026, Home Depot guides to comps of flat to 2% and an adjusted operating margin of 12.8%-13.0%. Lowe’s now expects flat comps and an 11.6% adjusted margin, both at the bottom of its earlier ranges.
But none of that has turned into earnings growth yet. Analysts expect Home Depot’s normalized EPS of $15.01 this fiscal year, up 2% from last year’s $14.69 and still below fiscal 2023’s $15.11:
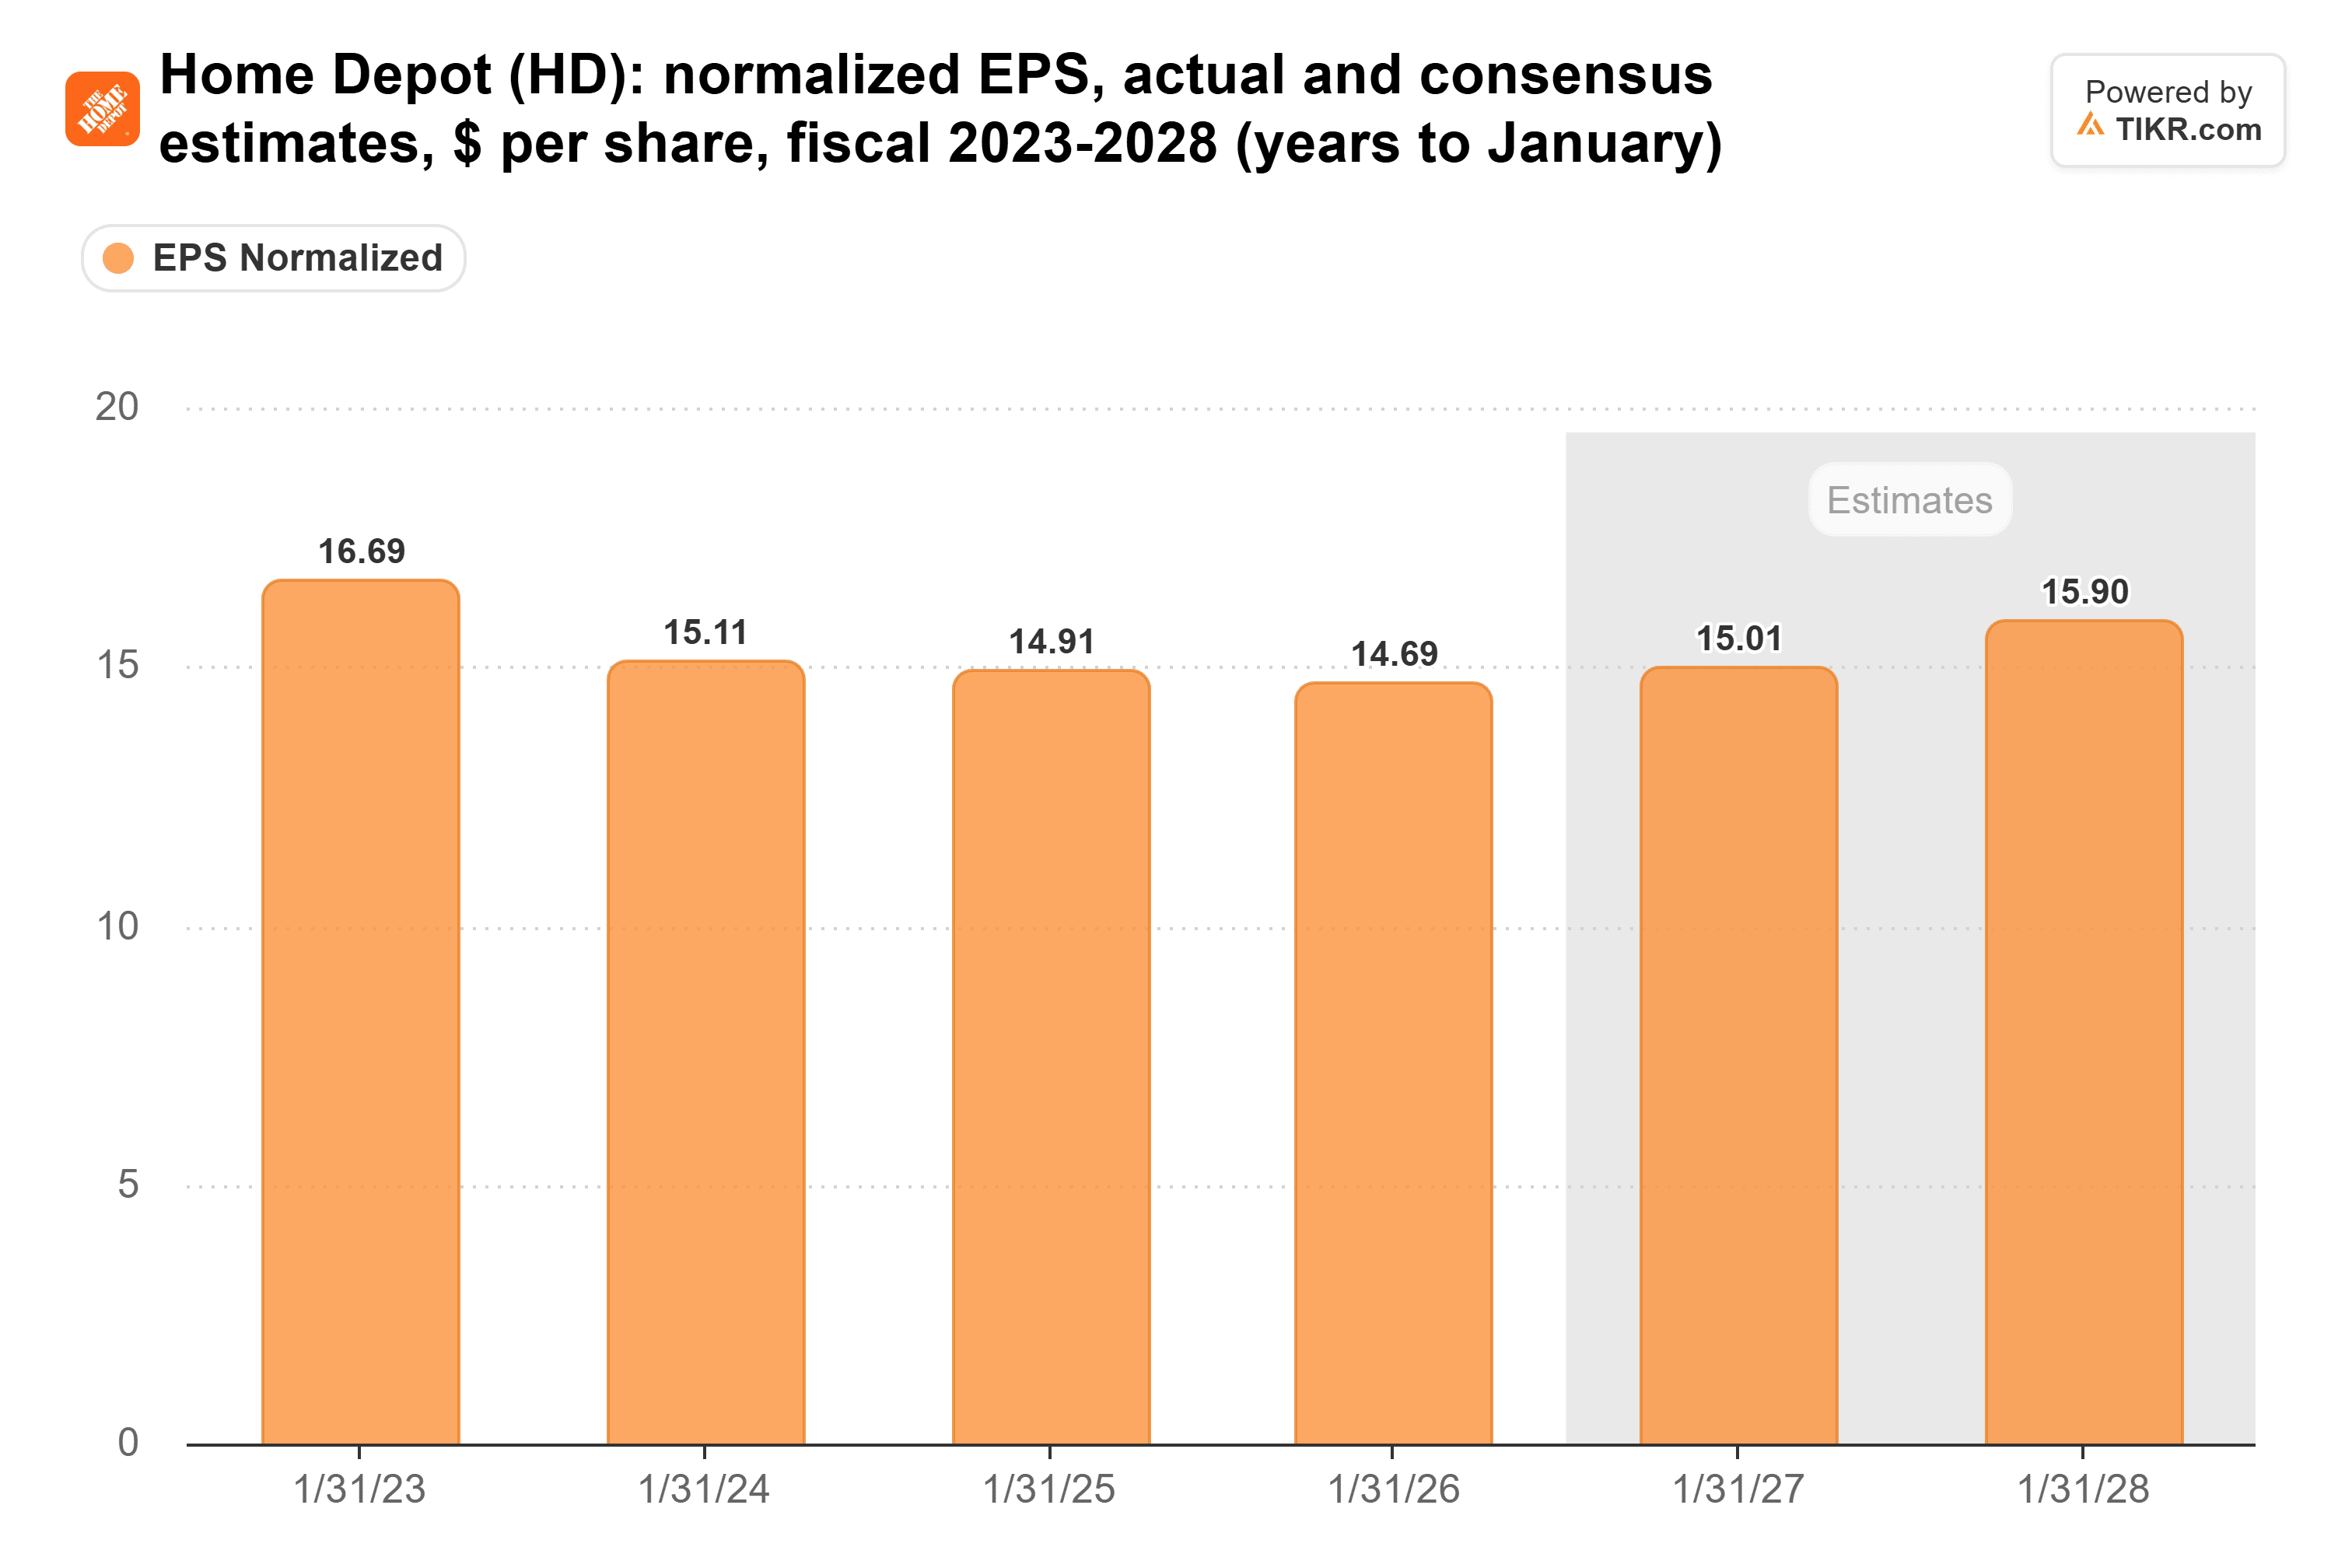
And the years ahead have come down. At the end of September 2025, analysts expected $17.74 for fiscal 2027. Now they expect $15.90.
TIKR tracks 36 analysts on Home Depot. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Home Depot, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Home Depot’s Analyst Ratings
The margin has to stop sliding
On TIKR’s figures, Home Depot’s third-quarter operating margin fell from 14.3% in fiscal 2023 to 13.5% in fiscal 2024 and 12.9% in fiscal 2025. The rest of the last three years shows the same slide:
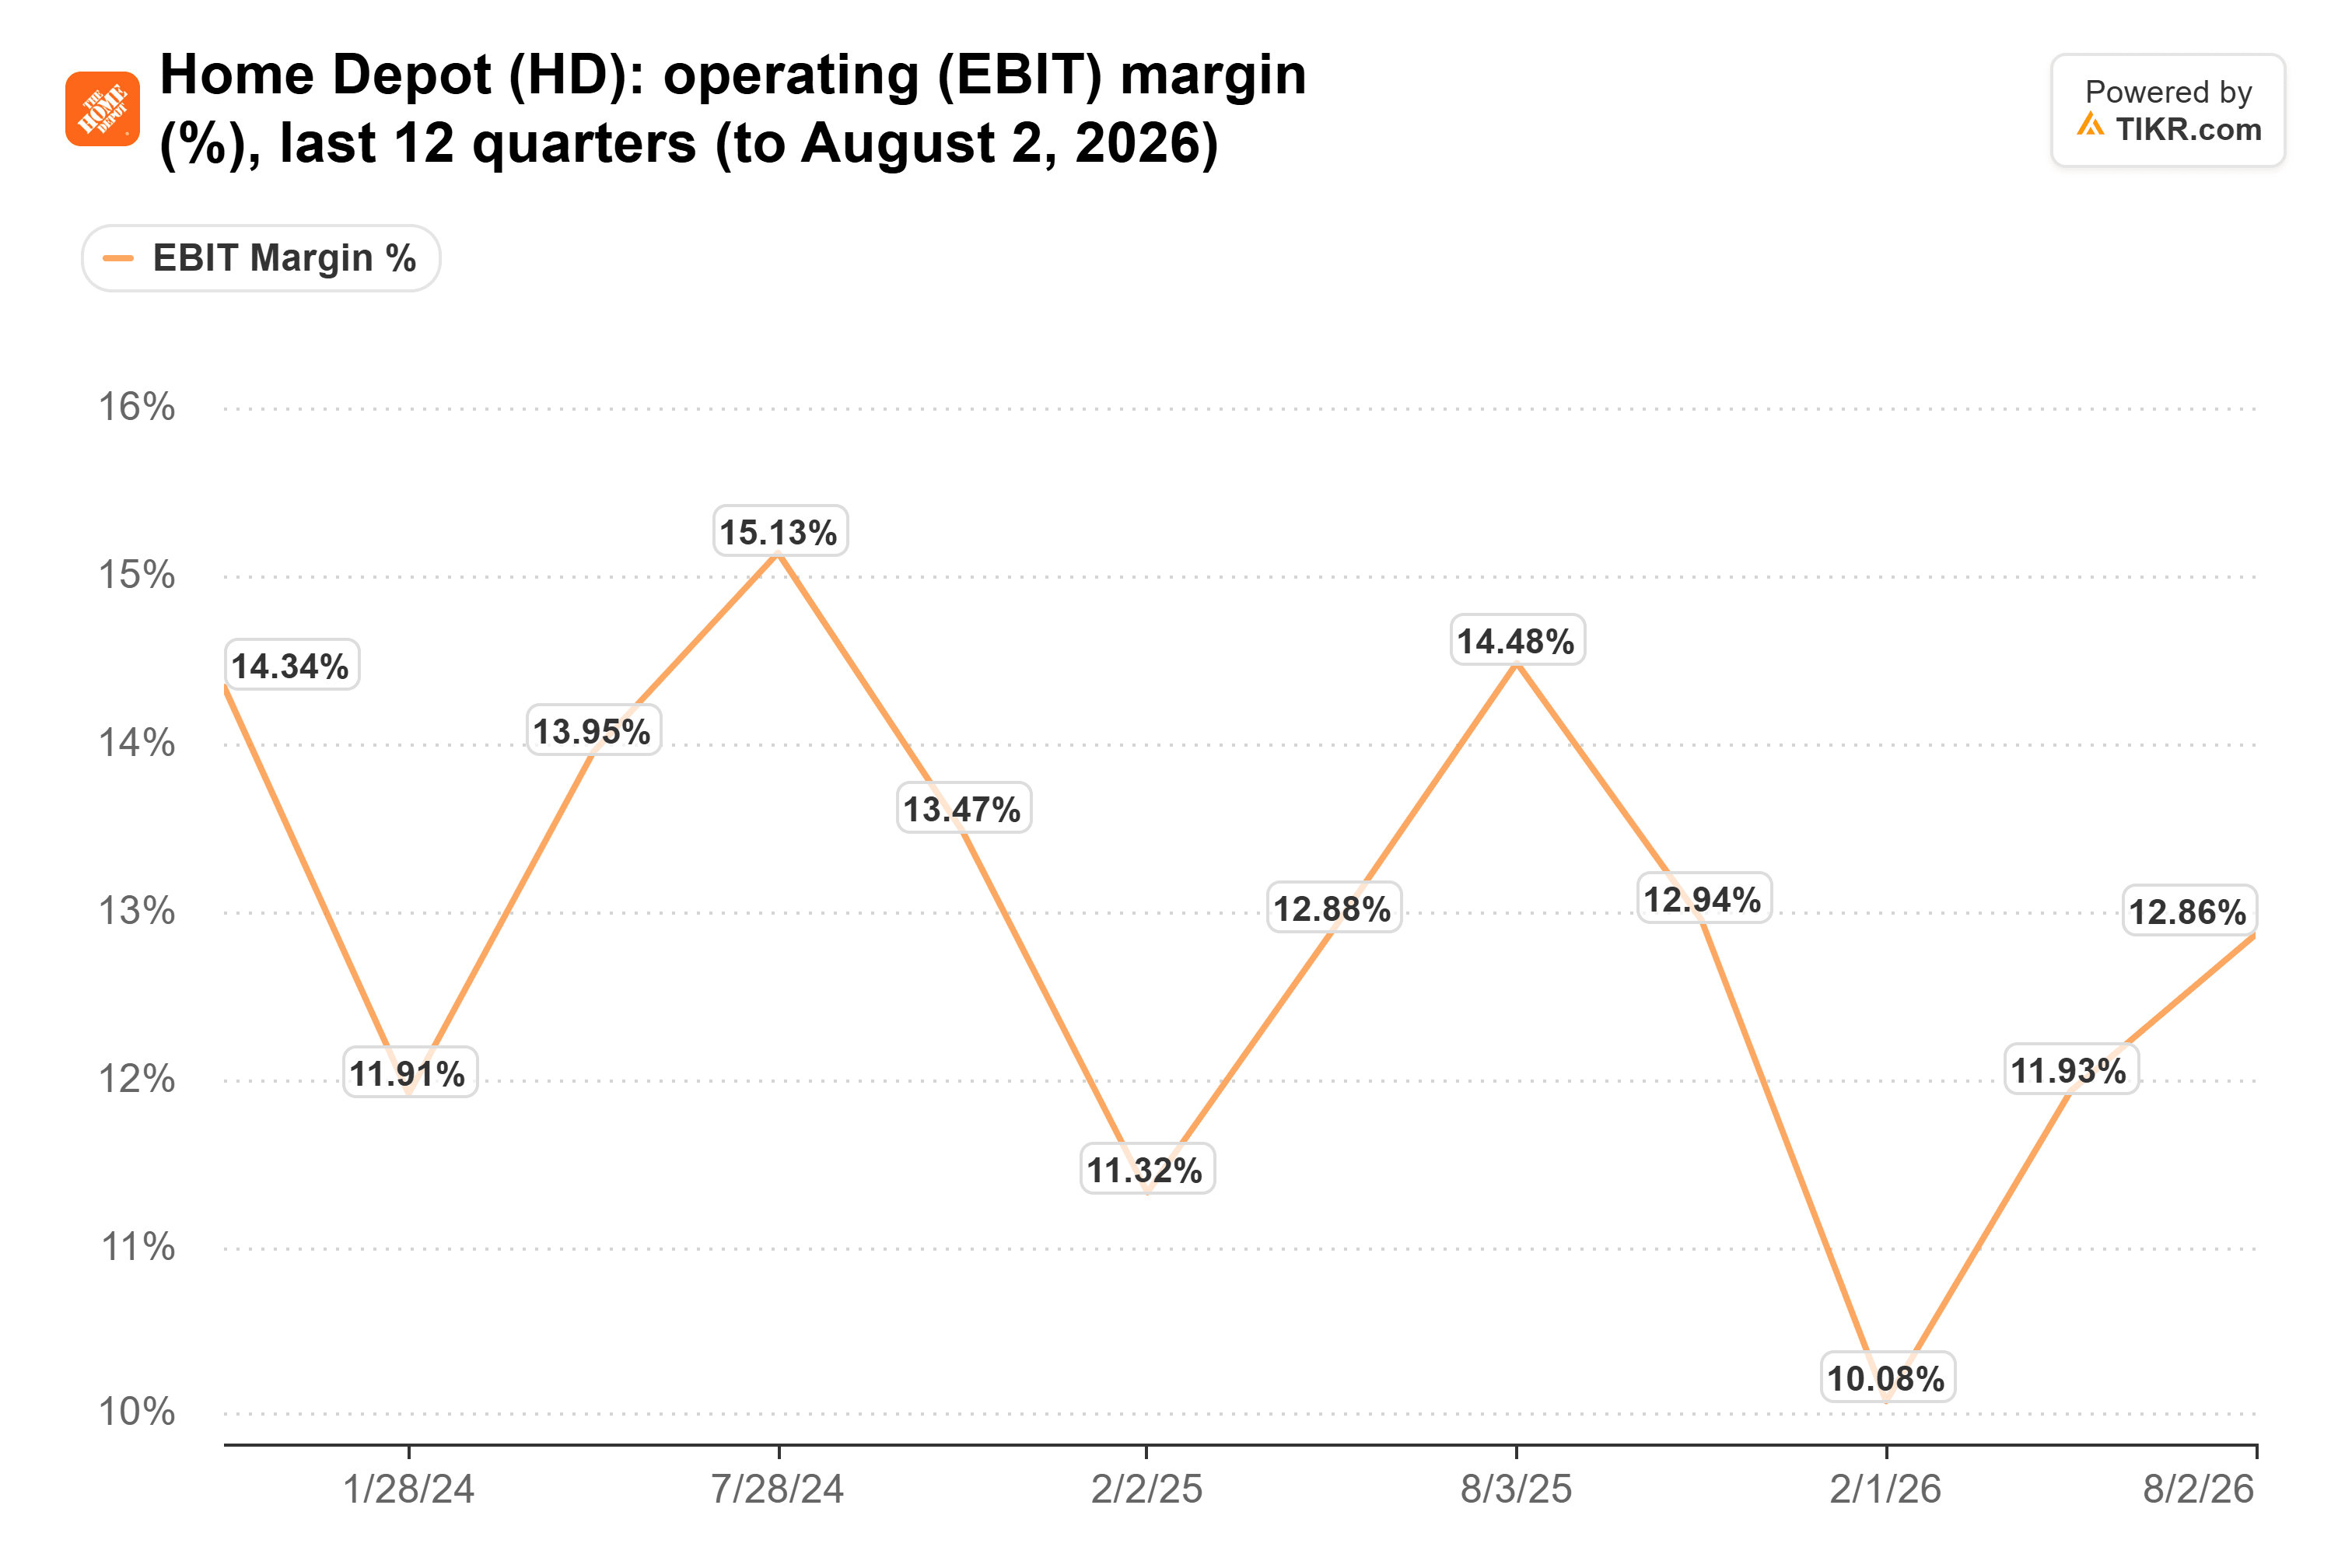
The second quarter looked better on paper. Home Depot reported a 14.3% operating margin, close to 14.5% a year earlier, but that included $685 million of tariff refunds (out of $730 million received), and TIKR’s 12.9% leaves them out. Lowe’s booked about $80 million of refunds in its own second quarter. Take them out of both, and Lowe’s margin was about half a point higher than Home Depot’s.
That’s hardly a widening lead.
Home improvement stocks usually trade on comps and the full-year guide, but this quarter the guide comes down to the margin. Management has said costs only start to leverage once growth runs above about 3%, and it guides comps to flat to 2%. So the margin holds only if spending does, and SG&A in its core retail segment grew 5.3% in the second quarter on segment sales up 1.5%. For Tuesday, Home Depot needs a third-quarter margin at or above last year’s 12.9% on TIKR’s basis, and it needs to keep the 12.8%-13.0% range.
Tools are selling, and flooring still isn’t
Masco’s quarter ran to Sept. 30, so it overlaps most of Home Depot’s. Sales in its paint segment, home of Behr, were flat from a year earlier, and CEO Jon Nudi said, “we expect the demand environment to remain challenged in the near term.” Behr sells through Home Depot, so paint could be a soft spot in its aisles too.
Stanley Black & Decker had better news. Volume in its Tools & Outdoor segment rose 7% in the third quarter, and CEO Chris Nelson credited “continued strength in the U.S. retail and commercial & industrial channels.” That fits Home Depot’s August call, when it credited a 2.4% rise in big-ticket transactions partly to single large purchases such as refrigerators, portable power tools and patio furniture. Stanley’s gross margin also got about 430 basis points from net tariff refunds. That’s one more reason to read this season’s margins with the refunds taken out.
Floor & Decor shows the big projects are still waiting. Its comparable sales fell 1.4% in the quarter to Sept. 24, and it guides to a full-year decline of 2.0%-3.5%. Yet its operating margin rose 30 basis points to 6.4%. If a flooring specialist can widen its margin while comps fall, Home Depot, with comps still positive, should be able to hold its own.
The price already assumes the lead holds
After a rally on midterm housing hopes, Home Depot trades at 23x forward earnings. That’s above its five-year average of 22x and up from 18x at the end of September:
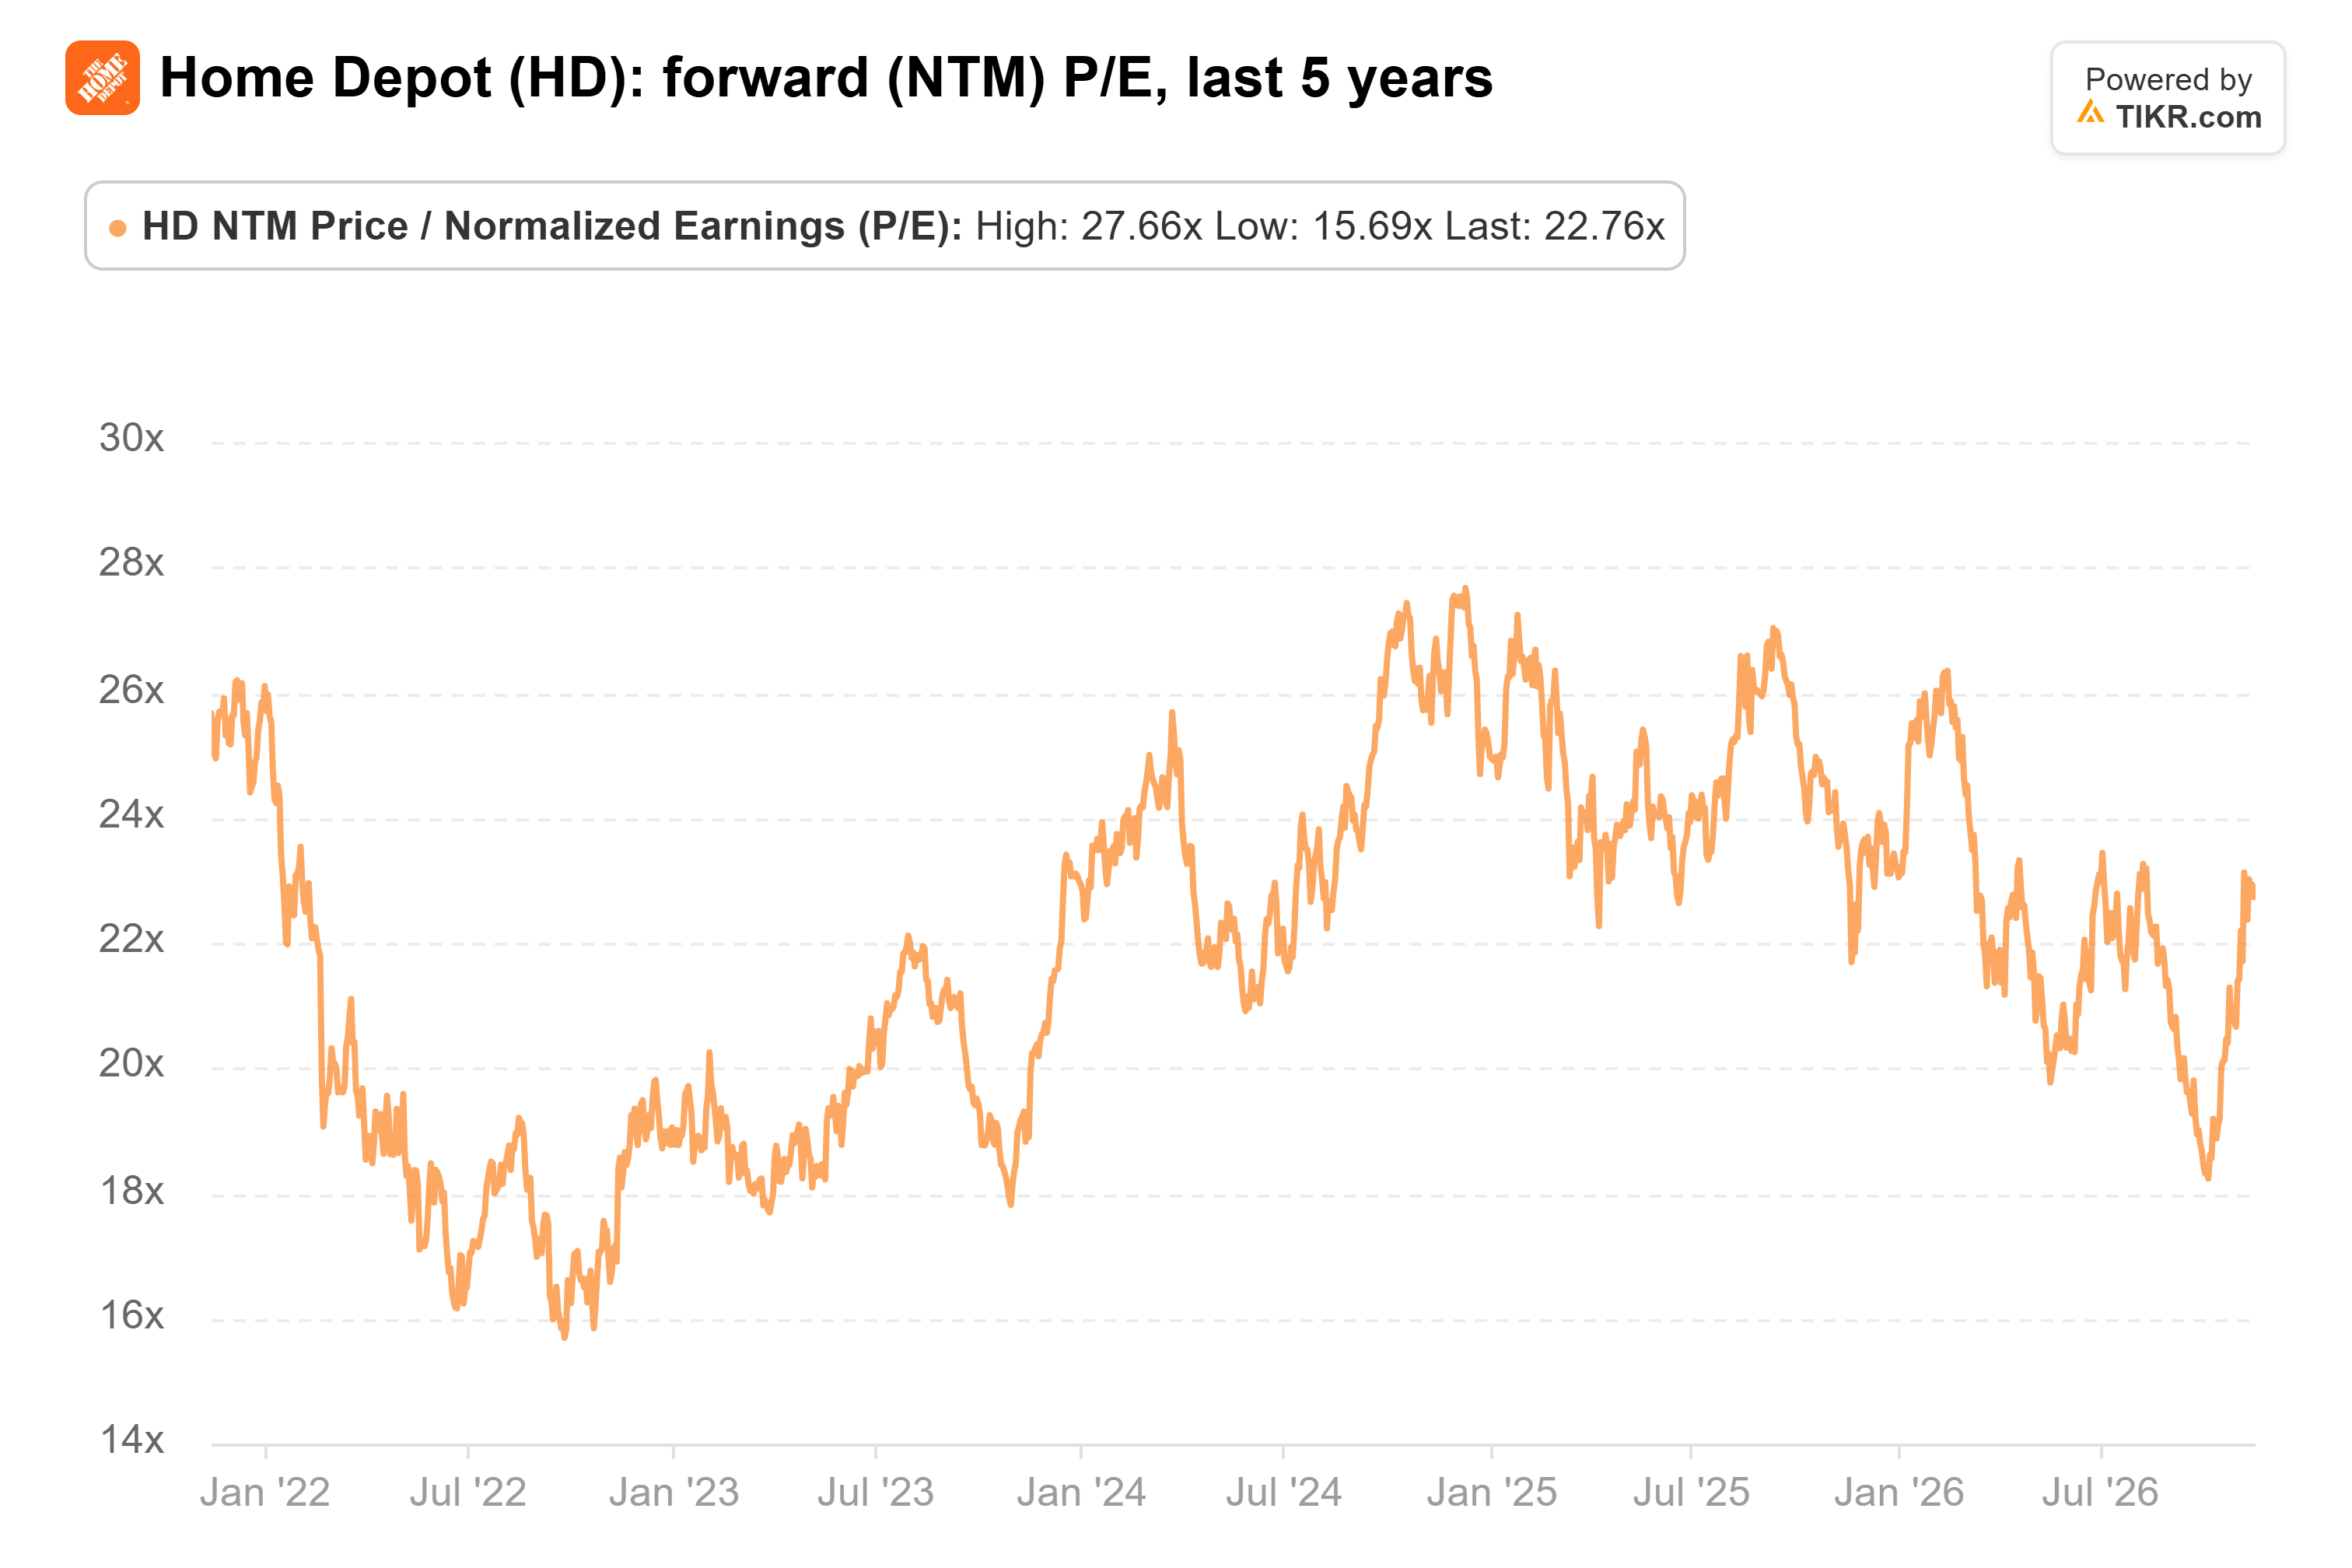
Stifel’s Carter thinks both stocks have run too far. He expects demand to weaken in the second half of 2026 and operating margins to come under pressure in fiscal 2027 and 2028, the same line Home Depot now has to defend.
Home Depot looks like the better business, and at 23x the market already knows it. That multiple, on earnings expected to grow 2% this year, is a bet on the recovery analysts see in fiscal 2027 and 2028. Home Depot only gets there if the margin stops falling. If Tuesday’s operating margin holds at or above 12.9% without refund help, the lead is real where it counts. If it slips again, the multiple has room to give back some of its run.
Lowe’s reports the next morning, Wednesday, Nov. 18, which puts both margins side by side within a day. Home Depot’s fiscal 2027 outlook in February is the bigger test.
So what is Home Depot stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Home Depot could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


